
 Lidding Foil Market | 2026-2036
Lidding Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Lidding Foil Market Foresight
Pharmaceutical-grade barrier specifications is collapsing the gap between commodity lidding and high-performance medical packaging. Amcor leverages its laminating technology leadership to capture premium pharmaceutical contracts. Novelis anchors North American supply through captive aluminum rolling capacity. Constantia Flexibles differentiates via cold-forming expertise for moisture-sensitive drug formats.
Lidding foil denotes a thin-gauge barrier material, typically 20-50 micrometer aluminum or metallized polymer, engineered for peelable or weld-seal closure of thermoformed trays, cups, and blister packs. Heat sealing dominates dairy and food packaging lines, while cold forming retains structural integrity for hygroscopic pharmaceutical tablets. Composite foil commands the widest application footprint across end users, though aluminum foil sustains the highest unit margins in pharmaceutical blisters where oxygen transmission rates below 0.01 cc/m²/day are mandatory. Food packaging applications generate the largest volume throughput, yet healthcare providers drive specification intensity and certification burdens.
FDA enforces 21 CFR 177.1390 compliance for indirect food contact laminates, while EU REACH and F-Gas Regulation restrict perfluorinated barrier chemistries in imported lidding structures. EMA's MDR elevates traceability requirements for pharmaceutical lidding suppliers serving European healthcare providers. Stakeholders must weigh aluminum recyclability mandates against polymer composite cost advantages as regulators tighten extended producer responsibility frameworks.
Market Dynamics
EU F-Gas Regulation and REACH compliance are forcing aluminum suppliers to reformulate barrier chemistries while dairy processors accelerate cold-chain lidding adoption across refrigerated distribution networks.
Growth Catalysts
- Organized Retail Expansion:India's supermarket and hypermarket chains are standardizing pre-packaged dairy formats, driving consistent demand for peelable lidding structures in cup and tray applications.
- EMA MDR Traceability Mandates:European pharmaceutical packaging must now maintain batch-level documentation through lidding supply chains, elevating specification intensity for certified barrier suppliers.
- Metallized Polymer Advances:Improved vacuum deposition techniques are extending oxygen barrier performance in polymer-based lidding, opening cost-competitive alternatives to aluminum in mid-tier food segments.
Market Restraints
- Primary Aluminum Volatility:LME aluminum price swings directly compress margins for foil laminators lacking long-term smelter contracts or captive rolling capacity.
- Perfluorinated Chemistry Phase-Out:EU F-Gas Regulation restrictions on fluorinated barrier coatings are forcing costly R&D pivots for lidding producers serving European export markets.
- Technical Thickness Floor:Pharmaceutical blister applications cannot reduce below 20-micrometer aluminum gauges without compromising pinhole integrity and moisture barrier performance.
Strategic Opportunities
- Aseptic Dairy Formats:Extended-shelf-life milk and yogurt producers in Southeast Asia are adopting retort-compatible lidding structures previously limited to European and North American markets.
- Digital Printing Integration:Variable-data printing on lidding surfaces enables unit-level traceability and promotional customization, creating service-layer revenue for converters.
- Extended Producer Responsibility:EU packaging waste directives are mandating aluminum recovery rates that favor mono-material foil designs over multi-layer composites in circular economy frameworks.
Industry Challenges
- Barrier Certification Timelines:FDA 21 CFR 177.1390 compliance documentation for new laminate structures requires 18-24 month validation cycles, delaying commercialization of reformulated products.
- Specialized Coating Expertise Scarcity:Heat-seal lacquer formulation for aggressive dairy fat environments demands polymer chemistry capabilities concentrated among a limited pool of European and Japanese suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lidding Foil Market |
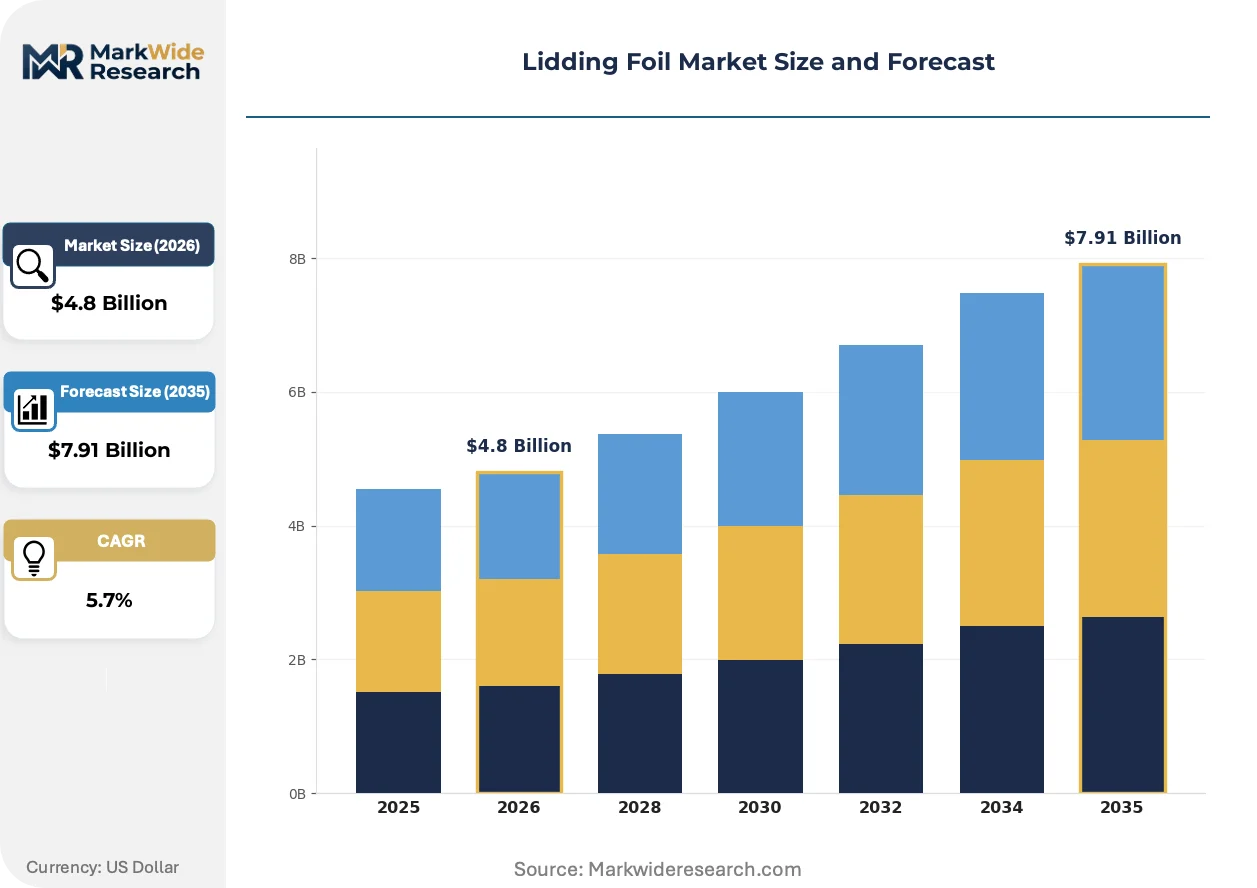
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
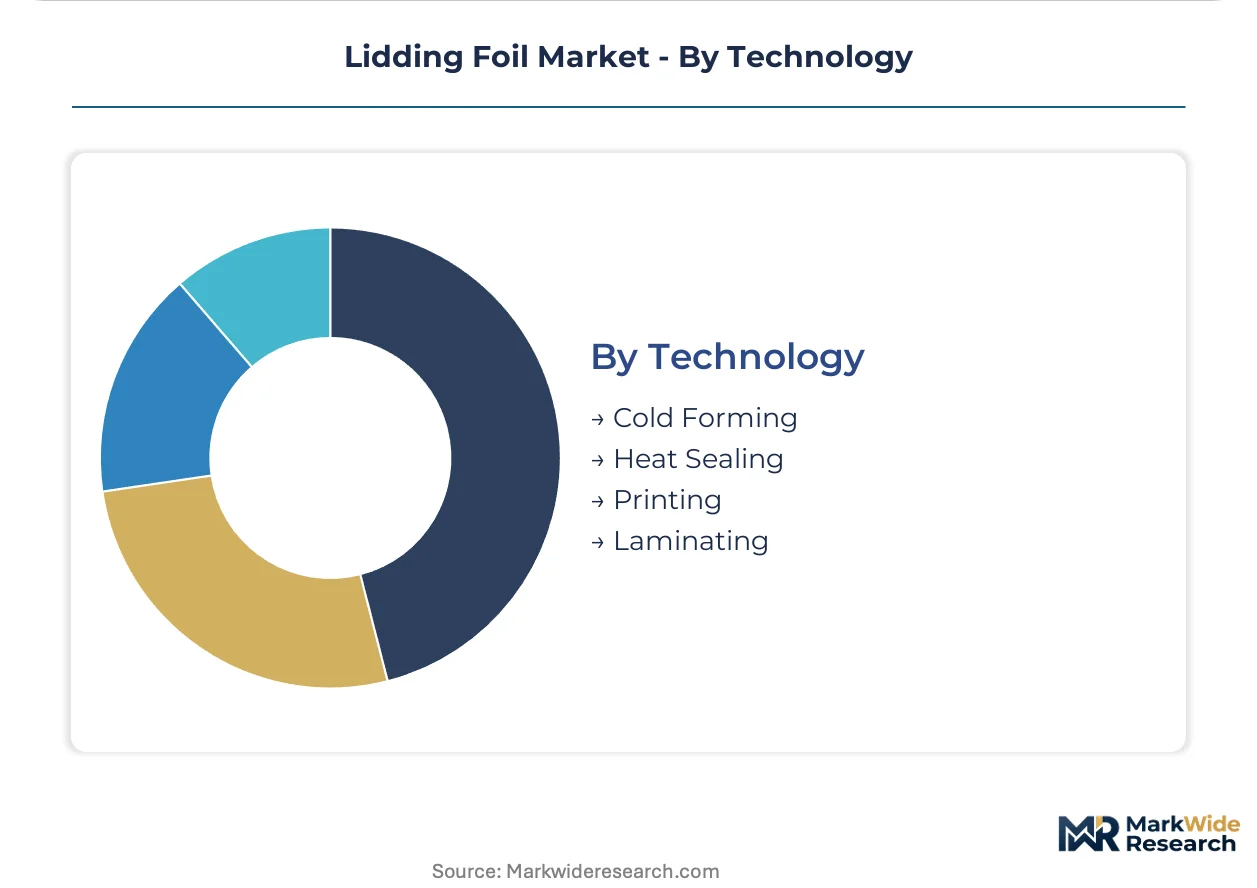
| Segmentation | Product Type: Aluminum Foil, Plastic Film, Composite Foil, Paper Foil Application: Dairy Products, Pharmaceuticals, Food Packaging, Confectionery End User: Food Manufacturers, Cosmetic Companies, Healthcare Providers, Beverage Producers Technology: Cold Forming, Heat Sealing, Printing, Laminating |
| Companies Covered | Winpak, UACJ Corporation, Amcor, Alcoa Corporation, Hydro Aluminium, Novelis, Constantia Flexibles, Constellium, Reynolds Consumer Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lidding Foil Market Shifts & Advancements
Active and intelligent packaging functionalities are migrating from premium pharmaceutical blisters into mainstream food lidding as unit costs decline and regulatory traceability requirements expand.
High-barrier metallized polyethylene terephthalate is fragmenting traditional aluminum foil's dominance in chilled dairy applications. German yogurt processors are adopting 12-micrometer metallized PET structures for cup lidding at scale previously reserved for foil. This substitution is fragmenting raw material supply chains and compressing specification premiums across mid-performance segments.
EU REACH restrictions on perfluorinated compounds are eliminating legacy grease-resistant coatings from food-contact lidding structures. Laminate producers serving European markets must validate fluorine-free alternatives without sacrificing seal integrity against fatty substrates. Pharmaceutical lidding suppliers face parallel pressure as EMA MDR documentation requirements extend to indirect contact materials.
Direct-store-delivery networks for fresh dairy are consolidating procurement authority at regional distributor level rather than individual plant level. This concentration favors lidding converters with national logistics footprints and inventory pooling capabilities over localized suppliers. The shift is most visible in Germany's northern dairy processing corridor where three distributors now control specification authority for approximately sixty percent of chilled cup volume.
Lidding Foil Market Segmentation
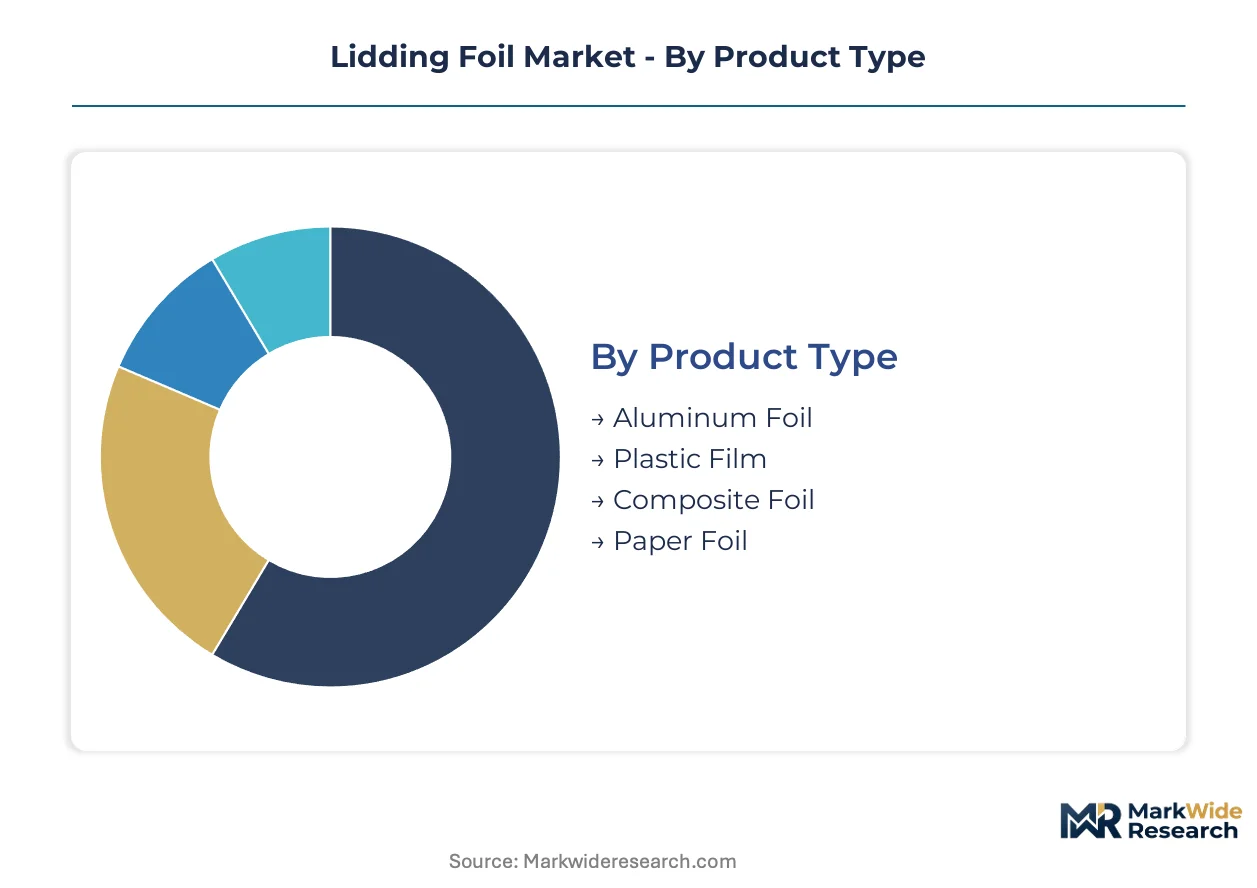
Lidding foil segmentation reflects divergent barrier specifications across regulated end-uses. Material selection, sealing technology, and end-user certification requirements create distinct commercial tiers with incompatible supply chains.
Product Type:
REACH and FDA 21 CFR 177.1390 compliance thresholds separate pharmaceutical-grade materials from commodity food-contact substrates.
- Aluminum Foil:Thin-gauge rolled aluminum, typically 20-50 micrometers, delivers oxygen transmission rates below 0.01 cc/m²/day mandatory for hygroscopic drug formats. Healthcare providers in Germany's pharmaceutical corridor specify this grade exclusively for moisture-critical blister applications despite primary aluminum volatility.
- Composite Foil:Multi-layer laminates combining aluminum, polymer films, and adhesive tie layers balance cost against performance across mid-tier food packaging. India's organized retail expansion standardizes these structures for pre-packaged dairy cups where extended shelf life meets price sensitivity.
- Plastic Film:Metallized and co-extruded polymer barriers serve confectionery and chilled food segments with moderate oxygen sensitivity.
- Paper Foil:Fiber-based substrates with wax or polymer coatings address limited barrier requirements in dry food and cosmetic overwrap applications.
Established volume favors composite foil; emerging adoption favors aluminum foil.
Application:
Cold-chain infrastructure investments and EMA MDR traceability mandates are rebalancing demand concentration across end-use verticals.
- Pharmaceuticals:Cold-forming and heat-seal blister lidding for tablets, capsules, and unit-dose formats requires batch-level documentation under EMA MDR. European healthcare providers drive specification intensity with oxygen and moisture barriers that exclude lower-performance alternatives.
- Dairy Products:Peelable and weld-seal lidding for yogurt cups, cream containers, and extended-shelf-life milk formats dominates volume throughput. Germany's northern dairy processing corridor and India's supermarket chains standardize retort-compatible and chilled distribution structures.
- Food Packaging:Tray and cup closures for prepared meals, fresh produce, and protein formats serve retail and foodservice channels with variable barrier requirements.
- Confectionery:Twist-wrap and flow-wrap lidding for chocolate and sugar confectionery prioritizes moisture protection and printability over ultra-high barrier performance.
Food packaging generates the largest volume base; pharmaceuticals command the steepest expansion trajectory.
End User:
Procurement authority consolidation among distributors and healthcare networks is compressing supplier fragmentation.
- Food Manufacturers:Dairy processors and prepared meal producers in Germany and India drive standardization of peelable lidding formats across refrigerated supply chains.
- Healthcare Providers:Hospital systems and pharmacy chains in Europe enforce EMA MDR documentation requirements that elevate certified barrier suppliers over commodity converters.
- Beverage Producers:Extended-shelf-life and aseptic liquid packaging manufacturers in Southeast Asia adopt retort-compatible lidding previously limited to European markets.
- Cosmetic Companies:Skincare and personal care brands specify lidding for jar and tray formats with moderate barrier and premium aesthetic requirements.
Healthcare providers impose the tightest certification burdens; beverage producers are gaining share fastest.
Technology:
Sealing method selection locks converters into specific equipment bases and coating chemistries with limited interchangeability.
- Heat Sealing:Thermal activation of lacquer-coated foil against thermoformed trays dominates dairy and food packaging lines. EU F-Gas Regulation restrictions on fluorinated grease-resistant coatings force reformulation of seal layers for fatty substrates without compromising integrity.
- Cold Forming:Mechanical deformation of aluminum foil around cavity tooling retains structural integrity for moisture-sensitive pharmaceutical tablets. Constantia Flexibles and Amcor anchor supply through captive laminating and forming expertise.
- Laminating:Adhesive and extrusion bonding of multi-layer structures enables property combinations unobtainable in mono-materials.
- Printing:Flexographic and digital variable-data technologies enable unit-level traceability and promotional customization on lidding surfaces.
Heat sealing commands installed equipment base; cold forming captures premium specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for lidding foil tilt toward surplus in aluminum-rich jurisdictions while deficit markets in India and Southeast Asia absorb inbound volumes. Germany and the United States maintain structural export positions through captive rolling and laminating capacity. India's organized retail expansion and cold-chain buildout now attract direct investment from foil converters seeking to bypass tariff barriers.
Germany
Dairy processors in Lower Saxony and Bavaria standardize retort-compatible lidding for extended-shelf-life yogurt formats. ECHA REACH restrictions on perfluorinated barrier coatings force reformulation of heat-seal lacquers for fatty substrates. The northern dairy processing corridor concentrates procurement authority among three regional distributors controlling specification for approximately sixty percent of chilled cup volume.
United States
Pharmaceutical blister demand from New Jersey and Massachusetts manufacturing clusters sustains premium aluminum foil consumption. FDA 21 CFR 177.1390 compliance documentation requirements extend validation timelines for new laminate structures. The Great Lakes region anchors captive aluminum rolling capacity serving domestic healthcare and food packaging converters.
India
Supermarket and hypermarket chains in Maharashtra and Karnataka standardize pre-packaged dairy formats requiring peelable lidding structures. FSSAI food contact material regulations align with EU standards for imported barrier substrates. The Gujarat pharmaceutical manufacturing corridor drives specification intensity for certified cold-forming foil among domestic and multinational drug packagers.
China
Aseptic dairy producers in the Yangtze River Delta adopt retort-compatible lidding previously limited to European markets. NMPA pharmaceutical packaging regulations elevate traceability requirements for blister foil suppliers serving domestic healthcare networks. The Pearl River Delta concentrates metallized polymer deposition capacity for mid-tier food lidding exports to Southeast Asia.
Japan
Confectionery and prepared meal manufacturers in the Kanto region specify high-barrier lidding with premium printability requirements. METI circular economy guidelines favor mono-material aluminum designs over multi-layer composites in packaging waste frameworks. The Osaka-Kobe industrial zone maintains specialized coating expertise for aggressive dairy fat environments.
Lidding Foil Market Competitive Landscape
Concentration sits with integrated aluminum producers and specialized converters possessing captive laminating technology. The vendor base spans three tiers: primary aluminum rollers with downstream foil capacity, independent laminators serving regional food processors, and pharmaceutical-grade specialists with cold-forming expertise. Consolidation pressure intensifies as EMA MDR traceability mandates and EU F-Gas Regulation compliance costs disadvantage smaller converters lacking certification infrastructure. Strategic moves center on backward integration into aluminum rolling and geographic expansion into India's organized retail corridor.
Among North American and European integrated players, Novelis and Alcoa Corporation exemplify the captive aluminum supply archetype, while Amcor and Constantia Flexibles occupy positions within the pharmaceutical-grade conversion tier. Amcor leverages laminating technology leadership across healthcare and food packaging segments. Constantia Flexibles anchors European supply through cold-forming expertise for moisture-sensitive drug formats. These three companies represent distinct competitive positions: upstream metal control, premium healthcare certification, and specialized forming capability.
| Leading Market Players |
|---|
| Winpak |
| UACJ Corporation |
| Amcor |
| Alcoa Corporation |
| Hydro Aluminium |
| Novelis |
| Constantia Flexibles |
| Constellium |
| Reynolds Consumer Products |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German dairy distributors and captive aluminum rollers lock in both supply access and price visibility across the northern processing corridor. These contracts insulate volume buyers from LME volatility while exposing independent laminators to margin compression during primary aluminum spikes.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Pharmaceutical-grade cold-forming foil commands steep premiums due to FDA 21 CFR 177.1390 and EMA MDR certification requirements, while composite foil for Indian dairy cups competes on volume scale. Price differentiation rests on barrier performance tier and geographic delivery cost. Cost compression in mid-tier food segments is intensifying because metallized PET substitutes erode aluminum specification premiums. Contract food manufacturers exhibit highest price sensitivity; certified pharmaceutical suppliers remain least sensitive.
Supply Chain Analysis
Strategic stockpile preferences dominate among European pharmaceutical converters buffering against primary aluminum volatility and REACH compliance delays. Supply concentrates in Germany, the United States, and China through captive rolling capacity and laminating expertise. The lidding foil supply chain draws from primary aluminum smelters, polymer film extruders, and specialized heat-seal lacquer formulators. Single-source vulnerability runs through Japanese coating specialists serving aggressive dairy fat applications. Distribution runs through regional distributor networks consolidating procurement authority in Germany and India's organized retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lidding foil market faces high-growth disruption as EMA MDR traceability mandates and EU F-Gas Regulation compliance costs consolidate procurement around certified barrier suppliers. Metallized polymer advances threaten mid-tier aluminum positions while cold-chain expansion in India and Southeast Asia opens volume frontiers.
For Market Incumbents: Compound laminating technology leadership through backward integration into aluminum rolling and geographic expansion into India's Gujarat pharmaceutical corridor. Prioritize certification infrastructure investments to capture EMA MDR-mandated batch-level documentation contracts. Defend against metallized PET substitution by emphasizing pinhole integrity specifications in pharmaceutical blister applications.
For New Entrants and Emerging Players: Differentiate on fluorine-free barrier coating expertise as EU REACH restrictions eliminate legacy grease-resistant chemistries. Target India's Maharashtra and Karnataka supermarket chains standardizing pre-packaged dairy formats with peelable lidding structures. Pursue white-space opportunities in aseptic dairy retort-compatible lidding for Southeast Asian extended-shelf-life milk producers.
For Investors and Strategic Acquirers: Specialized cold-forming converters with EMA MDR certification infrastructure represent attractive acquisition targets in a consolidating vendor landscape. Frame long-term viability around aluminum recyclability mandates favoring mono-material foil designs in circular economy frameworks. Watch for inflection when EU packaging waste directive recovery rate thresholds cross implementation deadlines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Novelis and Alcoa Corporation anchor North American supply through captive upstream capacity. |
| EMA MDR Certification Investment | Amcor leverages batch-level documentation capabilities to capture premium pharmaceutical contracts. |
| Fluorine-Free Coating Development | Constantia Flexibles pivots heat-seal lacquer formulations to meet EU F-Gas Regulation restrictions. |
| Geographic Expansion into India | Converters bypass tariff barriers by establishing laminating capacity near Gujarat pharmaceutical clusters. |
| Digital Printing Integration | Variable-data capabilities enable unit-level traceability and promotional customization for dairy distributors. |
Research Methodology
Desk research of customs trade data, SEC 10-K filings, and EMA regulatory submissions preceded structured interviews with foil laminator procurement directors, pharmaceutical packaging engineers, dairy processor supply chain managers, and heat-seal coating formulators. Primary fieldwork across Germany's northern dairy corridor and India's organized retail networks combined with secondary validation from aluminum industry association reports and REACH compliance databases. Bottom-up volume modeling triangulated against top-down market sizing across material grade tiers.
Variance decomposition across product type, application vertical, sealing technology, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include barrier performance tier, end-use certification requirements, and cold-chain infrastructure maturity. CAGRs derived from weighted average growth rates across these segments incorporated aluminum price elasticity assumptions and substitution coefficients for metallized polymer alternatives.
The analysis sits within stated boundaries; outcomes outside sustained EMA MDR enforcement or accelerated EU F-Gas Regulation implementation would require recalibration. Forecasts reflect assumptions regarding primary aluminum supply stability and REACH compliance timeline adherence. Revision becomes warranted when metallized PET oxygen barrier performance crosses pharmaceutical specification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
China Packaging Market
Packaging Materials
PCR Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Thermoformed Tubs Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
Water Soluble Pods Packaging Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Punnet Packaging Market