
 Direct Thermal Printing Films Market | 2026-2036
Direct Thermal Printing Films Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Thermal Printing Films Market Outlook
Consolidation among third-party logistics providers is realigning procurement leverage toward bulk film contracts. Fujifilm leverages its coating chemistry expertise to serve high-volume label converters. Zebra Technologies anchors the hardware-integrated film segment through printer-film bundling. SATO Holdings competes on specialized synthetic substrates for cold-chain applications.
Direct thermal printing films are thermally sensitive substrates coated with dye-developer chemistry that darkens when exposed to heat from a print head, eliminating ink or ribbon requirements. These films typically employ leuco dye-bisphenol A or phenolic developer systems on polyester or paper bases, engineered for print speeds exceeding 150 mm per second in industrial environments. Polyester substrates dominate premium applications where chemical resistance and dimensional stability command margin premiums, while paper-based films occupy high-volume retail labeling where cost minimization governs purchasing decisions. Synthetic films represent the fastest-growing product category as food service and cold-chain logistics expand label durability requirements.
FDA food-contact substance regulations and EPA chemical safety assessments govern thermal coating formulations in the United States, while REACH and EU Packaging and Packaging Waste Regulation shape material compliance obligations across European supply chains. These frameworks elevate testing costs for new chemistries but simultaneously create competitive moats for established compounders with validated substance dossiers. Stakeholders must monitor evolving bisphenol restrictions and substrate recyclability mandates to anticipate reformulation cycles and qualification timelines.
Market Dynamics
Consolidation among third-party logistics providers concentrates procurement leverage toward bulk film contracts, while REACH chemical compliance and evolving EU packaging waste rules force continuous reformulation of thermal-sensitive coatings across European supply chains.
Growth Catalysts
- Cold-chain logistics expansion:Food service and pharmaceutical distributors in Germany's automated distribution corridor drive synthetic film demand for labels requiring freezer-grade durability and moisture resistance.
- EU Packaging and Packaging Waste Regulation:Substrate recyclability mandates accelerate qualification of polyester films with validated recycling pathways, creating first-mover advantages for compounders with established dossiers.
- Print head thermal efficiency gains:Next-generation piezoelectric arrays operating at reduced temperatures extend dye-developer chemistry lifespan and reduce energy consumption in high-speed industrial environments.
Market Restraints
- Bisphenol A feedstock volatility:Leuco dye-bisphenol A developer systems face input cost pressure from petrochemical supply disruptions and emerging toxicity restrictions under EPA chemical safety assessments.
- Asia-Pacific coating concentration:Specialty chemical production for thermal-sensitive layers clusters in Chinese and South Korean manufacturing zones, exposing buyers to logistics bottlenecks and tariff friction.
- Direct thermal image permanence limitations:Heat and UV sensitivity of unprotected prints restricts application in archival documentation and outdoor asset tracking, ceding share to thermal transfer alternatives.
Strategic Opportunities
- Bio-based developer chemistry:Phenolic compounds derived from lignin and agricultural waste streams offer pathways to reduce petrochemical dependency and satisfy EU Green Deal circular economy targets.
- India's warehouse automation buildout:E-commerce fulfillment center expansion in Mumbai, Delhi, and Bangalore corridors creates untapped demand for high-speed direct thermal labeling systems.
- Hardware-film bundling models:Printer OEMs are capturing recurring film revenue through subscription-based consumable programs that lock in converter relationships and stabilize volume forecasts.
Industry Challenges
- REACH substance dossier timelines:New thermal coating chemistries require 18-24 month validation cycles through ECHA, delaying product launches and consuming R&D capital without revenue offset.
- Legacy print infrastructure interoperability:Warehouse operators running mixed fleets of 203 dpi and 300 dpi thermal printers face compatibility headaches when upgrading to next-generation film formulations optimized for higher-resolution heads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Thermal Printing Films Market |
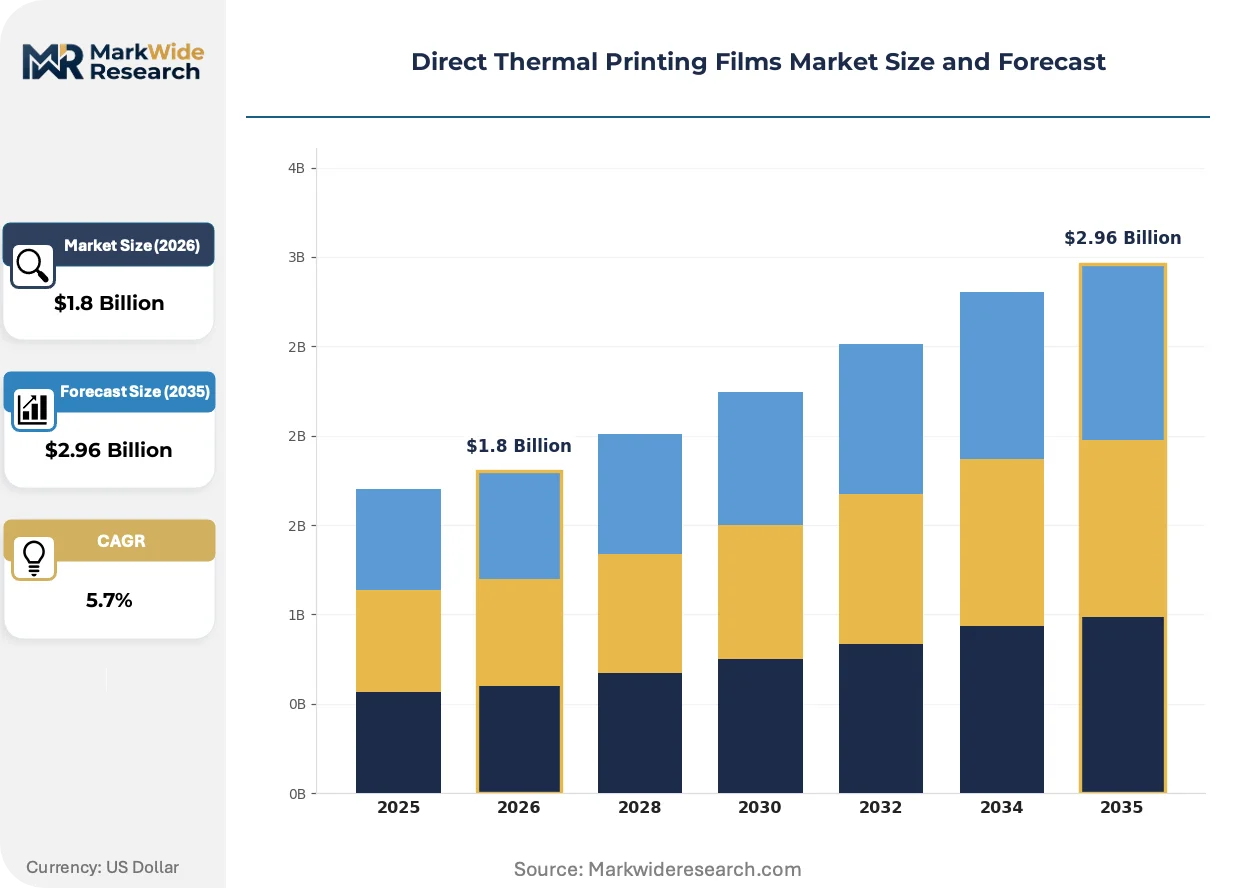
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Paper, Synthetic, Labels Application: Retail Labeling, Shipping Labels, Ticketing, Food Packaging End User: Manufacturing, Retail, Logistics, Food Service Market Channel: Direct Sales, Distributors, Online Retailers, Others |
| Companies Covered | Fujifilm, Zebra Technologies, Avery Dennison, Mondi Group, SATO Holdings, Cosmo Films, 3M, LINTEC, UPM-Kymmene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Thermal Printing Films Market Strategic Shifts
Reformulation of thermal developer chemistry around bio-based feedstocks and non-bisphenol activators is compressing traditional qualification timelines while opening competitive positioning for compounders with validated sustainable alternatives.
Water-based thermal coating deposition is decentralizing manufacturing geography by eliminating solvent handling requirements and volatile organic compound emissions controls. Mid-size converters in Poland, Mexico, and Vietnam are adopting these systems to produce regional film supply without capital-intensive environmental compliance infrastructure. This diffusion is eroding the historical concentration of premium film production in German and Japanese chemical corridors.
REACH restrictions on bisphenol A and related phenolic developers are forcing systematic chemistry transitions across European supply chains. Compounders with pre-registered alternative substances under Annex XIV authorization pathways are capturing specification wins from competitors facing substance sunset deadlines. Food-contact label applications face the most acute compliance pressure, driving accelerated migration to bisphenol S and Pergafast developer systems.
Third-party logistics operators are consolidating label procurement through managed print service contracts that bundle hardware, film, and maintenance into per-label pricing. This model transfers inventory risk from warehouse operators to converter-distributors while locking in volume commitments. The US Gulf Coast warehouse cluster and Benelux distribution hubs exhibit the most advanced adoption of this procurement structure, compressing spot-market film transactions.
Direct Thermal Printing Films Market Segmentation
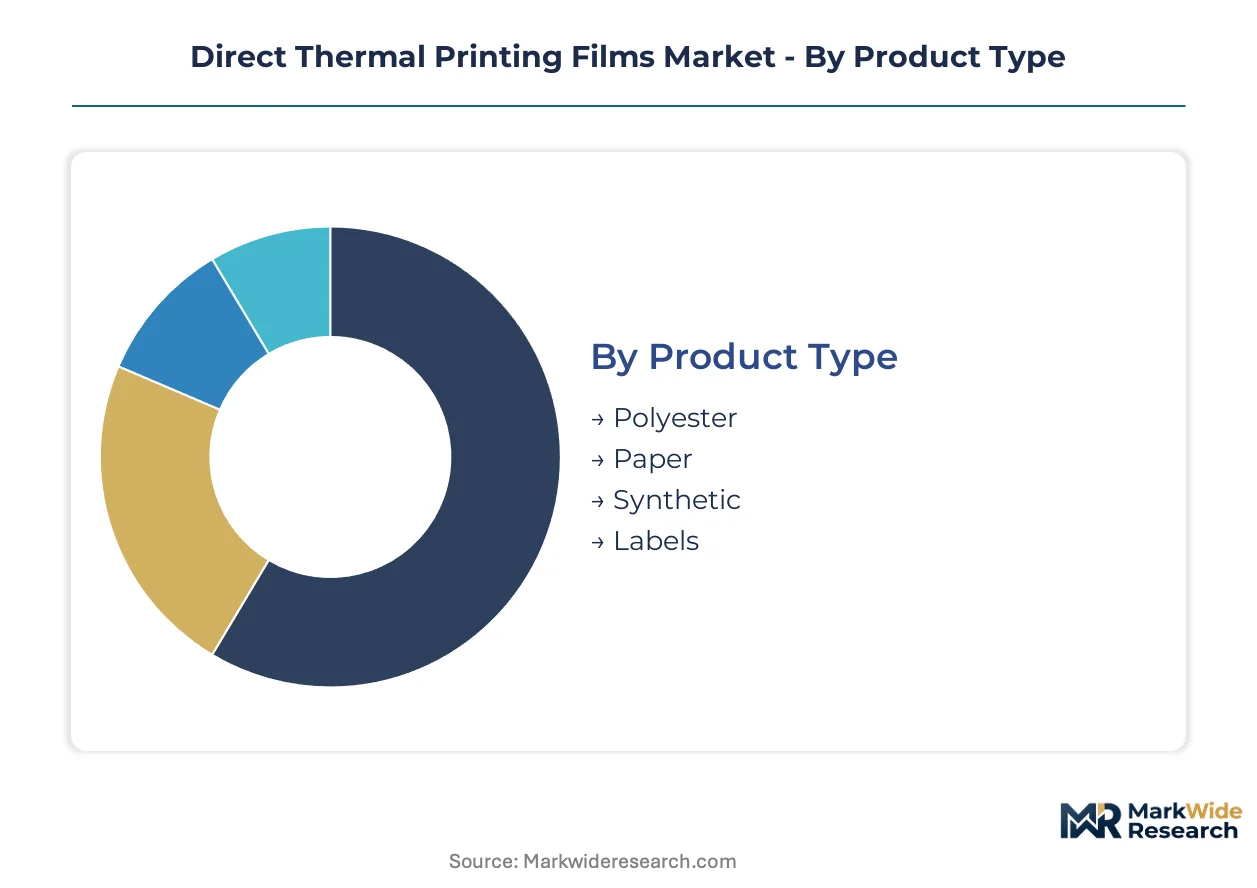
Segmentation in direct thermal printing films reveals how substrate chemistry, application durability requirements, and procurement channel economics create distinct margin profiles across the value chain. Upgrade cycles in warehouse automation and cold-chain infrastructure are redefining volume concentration across material categories.
Product Type:
Warehouse operators replacing legacy paper-based systems with synthetic alternatives are driving the current upgrade wave across industrial labeling environments.
- Polyester:Biaxially oriented polyethylene terephthalate substrates deliver dimensional stability and chemical resistance for asset-tracking applications in automated distribution centers. Demand concentrates in Germany's pharmaceutical logistics corridor where freezer-grade durability commands specification premiums.
- Paper:Calendered wood-pulp bases coated with standard leuco dye chemistry serve high-volume retail price marking where cost minimization governs procurement decisions. US Gulf Coast grocery distribution hubs anchor volume for this segment.
- Synthetic:Polypropylene and polyethylene blends engineered for moisture resistance and tear strength address cold-chain logistics expansion. Food service distributors in Benelux distribution hubs specify these films for freezer-to-thaw label integrity.
- Labels:Pre-converted die-cut formats with pressure-sensitive adhesives streamline converter operations for mid-size logistics providers.
Paper sits at the top of the volume ranking, with synthetic climbing the fastest.
Application:
Cost tier differentiation separates mission-critical pharmaceutical tracking from commodity retail marking where per-label economics dominate supplier selection.
- Retail Labeling:Shelf-edge price tickets and promotional tags require rapid print speeds but minimal environmental resistance. Mass merchandisers in India's Mumbai-Delhi e-commerce corridor are deploying high-speed direct thermal systems for same-day fulfillment labeling.
- Shipping Labels:Parcel identification tags with barcode and human-readable data face mechanical abrasion and humidity exposure during sortation. Third-party logistics consolidation across North America is concentrating procurement leverage toward bulk film contracts with standardized specifications.
- Ticketing:Event access credentials and transportation passes demand thermal image stability against body heat and friction. Polyester substrates with protective overcoats capture specification wins in this durability-sensitive niche.
- Food Packaging:Direct contact and proximity labeling for fresh and prepared foods faces the most acute regulatory pressure under FDA food-contact substance regulations and REACH substance restrictions. Bisphenol S and Pergafast developer systems are displacing legacy BPA-based coatings in European supply chains.
Shipping labels generate the highest absolute volume, with food packaging expanding most quickly due to regulatory-driven chemistry transitions.
End User:
Customer type segmentation maps directly to print volume density and specification sophistication, separating enterprise fleet operators from fragmented small-format users.
- Manufacturing:Work-in-process tracking and finished goods identification require 24/7 print reliability in industrial environments. Automotive and electronics producers in South Korea's Gyeonggi-do cluster specify premium polyester films for component traceability.
- Retail:Store-level price marking and inventory management operate on razor-thin per-label economics with minimal technical service requirements.
- Logistics:Parcel carriers and warehouse operators represent the most concentrated demand pool, with managed print service contracts bundling hardware, film, and maintenance into per-label pricing.
- Food Service:Restaurant chains and food distributors face dual pressure from FDA compliance and cold-chain durability requirements, driving fastest migration to synthetic substrates.
Logistics commands the volume lead, with food service gaining share fastest as cold-chain infrastructure expands.
Market Channel:
Supply concentration in coating chemistry creates channel leverage differences between converter-direct relationships and distributor intermediaries.
- Direct Sales:Converter-direct procurement serves high-volume label producers with dedicated technical service and custom formulation support. Fujifilm and Zebra Technologies anchor this channel through hardware-film bundling programs.
- Distributors:Regional stocking distributors provide inventory buffering and credit terms for mid-size converters in Poland, Mexico, and Vietnam adopting water-based coating systems.
- Online Retailers:E-commerce procurement platforms serve small-format end users with standardized SKUs and rapid fulfillment.
- Others:Managed print service providers and hardware OEMs capturing recurring film revenue through subscription-based consumable programs.
Distributors hold the volume position, with direct sales expanding most quickly as printer OEMs deepen converter relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled coating chemists and polymer engineers concentrate in Germany's industrial belt, Japan's precision materials corridor, and the US Gulf Coast chemical hub, anchoring regional production capabilities for thermal-sensitive substrates.
United States
FDA food-contact substance regulations and EPA chemical safety assessments govern thermal coating formulations for food service and pharmaceutical labeling. The US Gulf Coast warehouse cluster drives synthetic film demand for cold-chain logistics, with third-party logistics operators consolidating procurement through managed print service contracts that bundle hardware and consumables.
Germany
REACH substance restrictions and EU Packaging and Packaging Waste Regulation mandate continuous reformulation of bisphenol-based developer systems. The automated distribution corridor spanning North Rhine-Westphalia and Bavaria anchors European demand for freezer-grade polyester films, with pharmaceutical logistics operators specifying premium substrates for traceability applications.
China
GB standards and MIIT industrial policies shape domestic manufacturing requirements for thermal-sensitive coatings. The Yangtze River Delta coating chemistry cluster supplies leuco dye and phenolic developer systems to regional converters, though logistics bottlenecks and tariff friction expose international buyers to supply disruption risks.
Japan
METI industrial standards and JIS specifications govern substrate quality for precision labeling applications. The Kanto region's precision materials corridor hosts compounders with validated substance dossiers under REACH Annex XIV pathways, capturing specification wins as European competitors face bisphenol sunset deadlines.
India
BIS standards and the PLI scheme for manufacturing incentivize domestic film production capacity. The Mumbai-Delhi-Bangalore e-commerce corridor drives warehouse automation buildout, creating demand for high-speed direct thermal labeling systems as fulfillment center operators upgrade from manual price-marking infrastructure.
Direct Thermal Printing Films Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across substrate chemistry and hardware-integrated segments. Market structure tilts toward consolidation at the coating chemistry level while fragmenting across regional converter networks. Three archetypes dominate: chemical compounders with validated regulatory dossiers, printer OEMs capturing recurring film revenue through bundling, and synthetic substrate specialists serving cold-chain durability requirements. Competitive moves center on hardware-film subscription programs and bio-based developer chemistry qualification.
Among coating chemistry specialists, Fujifilm leverages its photographic materials heritage to occupy a position in high-performance thermal-sensitive layers. SATO Holdings exemplifies the substrate-to-system integrator archetype, bridging synthetic film production with specialized cold-chain applications. Zebra Technologies anchors the hardware-captive consumables model, converting printer installed bases into recurring film revenue streams through managed service contracts.
| Leading Market Players |
|---|
| Fujifilm |
| Zebra Technologies |
| Avery Dennison |
| Mondi Group |
| SATO Holdings |
| Cosmo Films |
| 3M |
| LINTEC |
| UPM-Kymmene |
| Others |
Value Chain & Pricing Dynamics
Skilled coating chemists in Germany's industrial belt and polymer engineers across Japan's precision materials corridor anchor labor-cost differentials that widen pricing-tier spreads between premium polyester substrates and economy paper-based alternatives. REACH dossier preparation costs and EPA chemical safety assessment timelines compound these spreads, as compounders with validated substance registrations command specification premiums while regional converters in Poland and Mexico compete on water-based coating operational savings.
Pricing Analysis
Bundled hardware-film subscription programs diverge from unbundled spot-market transactions, creating distinct pricing architectures across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates freezer-grade polyester specifications from retail price-marking paper substrates, with certification tier under FDA food-contact substance regulations and REACH Annex XIV authorization pathways driving price differentiation. Cost compression in economy paper grades is intensifying because third-party logistics consolidation concentrates procurement leverage toward bulk contracts. Small-format retail end users exhibit highest price sensitivity, while pharmaceutical logistics operators in Germany's automated distribution corridor demonstrate lowest sensitivity due to traceability compliance requirements.
Supply Chain Analysis
Direct-to-converter channels handle high-volume label producer demand, while regional stocking distributors serve mid-size operators in Poland, Mexico, and Vietnam adopting water-based coating systems. Specialty chemical production for thermal-sensitive layers concentrates in China, South Korea, and Japan, with leuco dye and phenolic developer systems drawing from petrochemical feedstocks and bisphenol A derivatives. Single-source vulnerability around bisphenol S and Pergafast developer alternatives exposes European supply chains to qualification timeline delays as REACH substance sunset deadlines approach. Distribution runs through converter-direct relationships for premium specifications and distributor intermediaries for standardized retail-grade films.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where REACH bisphenol A restrictions and evolving EU Packaging and Packaging Waste Regulation mandate continuous reformulation investment that advantages established dossier holders.
For Market Incumbents: Deploy hardware-film bundling programs to capture recurring consumable revenue and lock converter relationships against emerging synthetic substrate specialists. Consolidate coating chemistry capabilities through backward integration into leuco dye production to defend margin position against petrochemical feedstock volatility. Secure REACH Annex XIV pre-registration for bisphenol S and Pergafast alternatives before competitor substance sunset deadlines erode specification wins. For New Entrants and Emerging Players: The price-point gap between premium freezer-grade polyester and economy paper-based films offers entry positioning through mid-tier synthetic substrates for cold-chain logistics expansion. Target India's warehouse automation buildout in the Mumbai-Delhi-Bangalore corridor, where fulfillment center operators seek high-speed direct thermal systems without legacy converter relationships. Pursue water-based coating deposition technology to establish regional production in Vietnam and Poland without capital-intensive environmental compliance infrastructure. For Investors and Strategic Acquirers: Printer OEMs are the most active acquirer in this space, seeking coating chemistry capabilities to deepen hardware-captive consumables models. Compounders with validated REACH dossiers and established FDA food-contact substance registrations present durable acquisition targets through the medium-term projection horizon. Monitor ECHA substance authorization timeline announcements as inflection indicators for competitive repositioning around bisphenol-free developer systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Developer Chemistry | Captive supply of leuco dye compounds insulates margin from petrochemical volatility under EPA assessments. |
| REACH Annex XIV Pre-Registration | Validated substance dossiers for bisphenol S and Pergafast create competitive moats as BPA faces sunset deadlines. |
| Hardware-Film Subscription Programs | Zebra Technologies and Fujifilm convert printer installed bases into recurring revenue through managed service contracts. |
| Water-Based Coating Deposition Adoption | Elimination of solvent handling requirements enables mid-size converters in Poland and Vietnam to enter regional supply. |
| Synthetic Substrate Capacity Expansion | Polypropylene and polyethylene blend production addresses cold-chain durability requirements in Benelux distribution hubs. |
Study Parameters
Bottom-up logistics operator modeling reconciled against top-down coating chemistry production tracking forms the analytical core of this study. Primary interviews with label converter procurement directors, thermal printer OEM technical leads, third-party logistics fleet managers, and specialty chemical R&D directors combined with secondary validation from ECHA substance dossier databases, FDA food-contact substance notifications, SEC 10-K filings of listed compounders, and EU Packaging and Packaging Waste Regulation implementation documents. Trade data from customs authorities and industry association reports provided cross-reference points for volume triangulation.
Input-output matrices mapped thermal-sensitive coating formulation costs through substrate conversion stages to end-use pricing across product type, application durability tier, and procurement channel segments. Modeled dimensions included substrate chemistry class, end-use industry vertical, geographic regulatory cluster, and converter scale tier. CAGRs were derived from regression analysis of historical volume trends against projected warehouse automation investment cycles and cold-chain infrastructure expansion. Forecast inputs incorporated print head thermal efficiency gain curves and bio-based developer chemistry qualification timelines.
The model assumes a particular technology adoption path; alternative pathways for water-based coating deposition or non-bisphenol activator systems would alter the outlook. Forecasts reflect base-case assumptions regarding REACH substance authorization timelines and FDA food-contact substance regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Book Wraps Market
Packaging Materials
Global Strapping Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
Asia-Pacific Solar Control Window Films Market
Packaging Materials
PET Strap Market
Packaging Materials
Food Grade Sealant Market
Packaging Materials
Thermoformed Tubs Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Desiccant Market
Packaging Materials
Composite Packaging Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Hot-Melt Based Packaging Market