
 Bonding Films Market | 2026-2036
Bonding Films Market Size, Share, and Industry Trends Forecast 2026-2036
Bonding Films Market Intelligence
The European Union's RoHS directive, restricting hazardous substances, is realigning material selection criteria for bonding films in the electronics industry. This shift creates opportunities for compliant material suppliers like DuPont de Nemours, which leverages its polymer science expertise. Henkel AG & Co. KGaA competes with a diverse portfolio of thermoplastic and thermosetting films, while 3M Company specializes in advanced pressure-sensitive adhesives for high-stress applications.
Bonding films are thin, solid-state adhesive layers designed to create a permanent or semi-permanent bond between two substrates when activated by heat, pressure, or light. Their primary purpose is to provide structural integrity and uniform bond line thickness in complex assemblies. Thermoplastic films dominate due to their processing flexibility, while thermosetting chemistries are specified for applications requiring superior thermal and chemical resistance. The electronics assembly segment is a key demand center, outpacing growth in more mature applications like packaging.
Regulatory frameworks like the EU's REACH regulation and the US EPA's standards for volatile organic compounds (VOCs) govern material composition. These rules promote the development of solvent-free and water-based film technologies. Consequently, manufacturers must innovate films that comply with evolving environmental standards without compromising adhesion performance for next-generation electronics and automotive components.
Market Dynamics
The market's central dynamic is the tension between escalating performance needs for miniaturized electronics and tightening regulations like the EU's RoHS directive. This forces a constant cycle of material innovation to meet dual demands.
Growth Catalysts
- Component Miniaturization:The push for smaller electronics and automotive modules demands ultra-thin bonding films for structural integrity without adding significant bulk or weight.
- Regulatory Mandates:Directives like the EU's RoHS and REACH frameworks steer demand toward advanced, compliant films, favoring suppliers with strong materials science capabilities.
- Asian Production Hubs:Concentrated electronics manufacturing in China, Taiwan, and South Korea creates a massive, localized demand base for films in displays and semiconductors.
Market Restraints
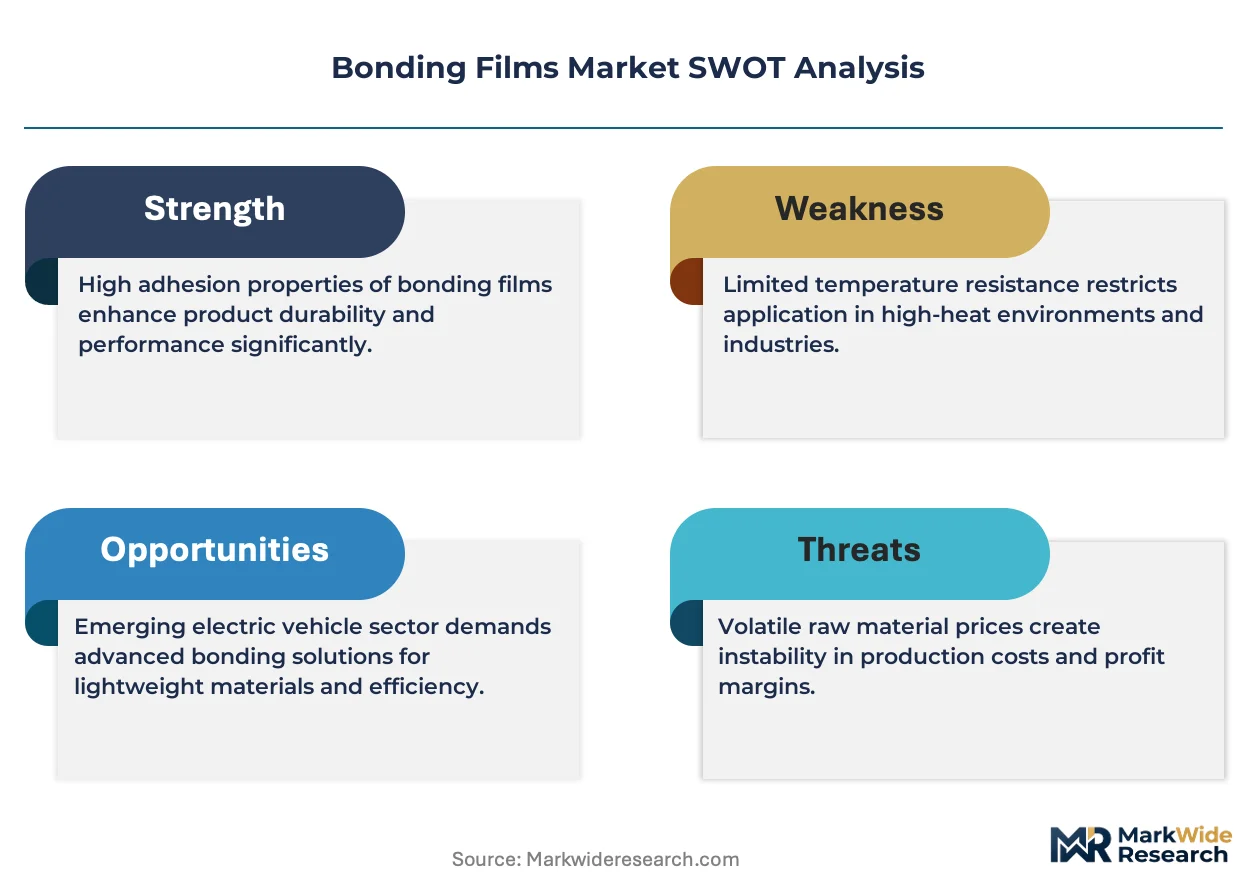
- Raw Material Volatility:Price fluctuations for specialty polymer resins, the primary feedstock, create margin pressure and unpredictable production costs for film manufacturers.
- Performance Trade-offs:Achieving high adhesion and thermal resistance in thinner films presents a materials science challenge, limiting use in extreme-temperature applications.
- Substitution Threat:In some cost-sensitive segments, conventional liquid adhesives offer a lower-cost alternative, capping market penetration for bonding films.
Strategic Opportunities
- Automotive Electronics:The growth of ADAS and EV battery systems creates new applications for specialized films in sensor mounting and cell-to-pack bonding.
- Multi-Functional Films:Developing films that integrate secondary properties like thermal conductivity or EMI shielding can reduce component count and simplify assembly processes.
- Solvent-Free Technologies:Stricter VOC regulations from the US EPA create a strong tailwind for 100% solids-based thermoplastic and thermosetting film technologies.
Industry Challenges
- Extended Qualification Cycles:Gaining approval for new films in high-reliability sectors like aerospace and medical devices involves long, expensive testing and certification.
- Raw Material Purity:Securing consistent, high-purity polymers is a challenge for producing films that meet the defect-free requirements of the semiconductor industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bonding Films Market |
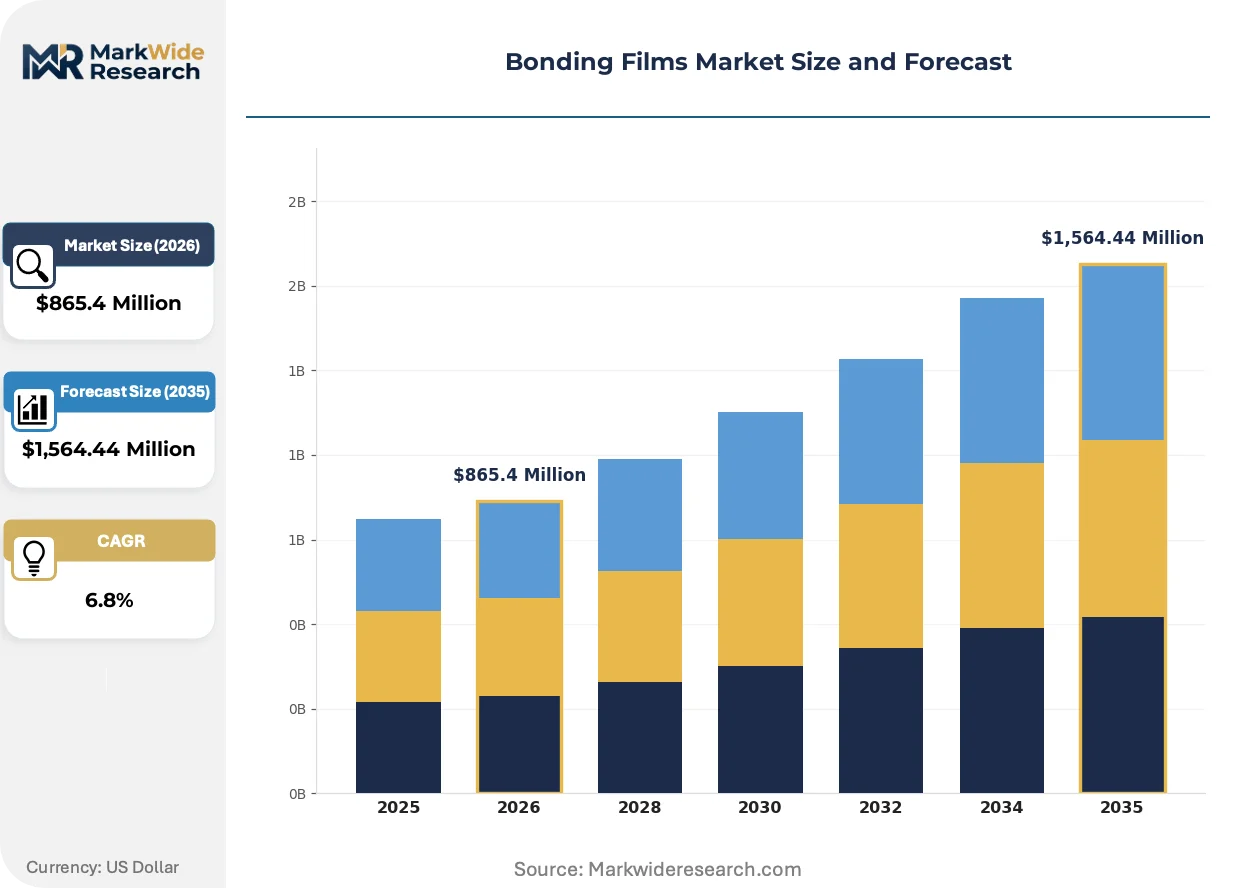
| Market Size in 2026 | $865.4 Million |
| Market Size in 2035 | $1,564.44 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Thermosetting, Acrylic, Polyester, Polyimide, Polyurethane Application: Electronics Assembly, Automotive Components, Packaging, Medical Devices, Aerospace Interiors, Consumer Goods Technology: Hot Melt, Pressure Sensitive, Solvent-Based, UV Curable, Water-Based, Reactive End User: OEMs, Contract Manufacturers, Packaging Companies, Medical Equipment Suppliers, Aircraft Manufacturers, Electronics Fabricators |
| Companies Covered | Henkel AG & Co. KGaA, DuPont de Nemours, 3M Company, Avery Dennison Corporation, H.B. Fuller Company, Dow Inc., Toray Industries, Nitto Denko Corporation, Kuraray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bonding Films Market Strategic Shifts & Innovations
Materials science is evolving on a dual front, pushing the boundaries of chemical formulations for performance while simultaneously adapting manufacturing processes to meet global environmental standards. This dynamic shapes both product capabilities and market access.
Multi-functional films integrate properties like thermal conductivity directly into the adhesive layer. Electronics designers are adopting these materials to simplify the construction of compact devices like 5G modules. This technology is expanding into roles previously held by multiple components, such as separate adhesive tapes and thermal interface materials.
China's stringent regulations on volatile organic compounds (VOCs), enforced by the MEE, are a major force. This policy compels a shift from solvent-based chemistries within its electronics manufacturing ecosystem. Consequently, solvent-free thermoset and thermoplastic hot-melt films are gaining adoption in production hubs like Shenzhen and Suzhou.
A behavioral shift is underway where OEMs specify films based on total cost of ownership and process yield, not just unit price. This change favors suppliers providing application engineering support, disrupting commoditized distributors. This trend is most pronounced in high-reliability sectors like medical devices and aerospace, where bond failure has severe consequences.
Bonding Films Market Segmentation
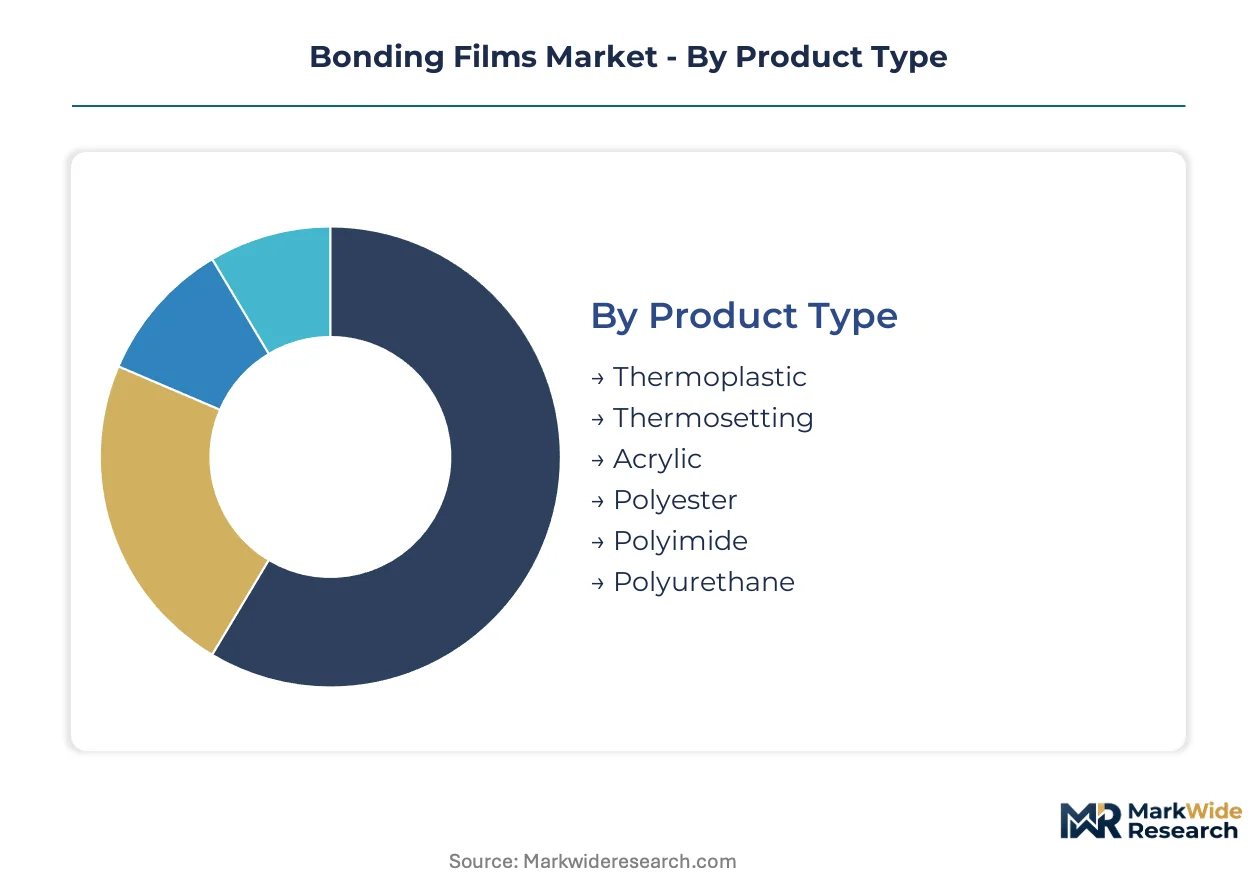
The bonding films market segments based on product type, application, technology, and end user, reflecting the diverse performance requirements across various industries. Each segment represents distinct material science challenges and market opportunities, driven by specific functional needs and regulatory pressures.
Product Type:
The product type segmentation highlights the customization-vs-standardization spectrum, with some formulations offering broad utility while others are highly specialized for niche applications.
- Thermoplastic:These films soften upon heating and solidify upon cooling, allowing for reworkability and efficient processing, particularly in high-volume electronics assembly. Demand concentrates in consumer electronics and automotive displays due to their processing flexibility and cost-effectiveness.
- Thermosetting:These materials undergo an irreversible chemical reaction when heated, forming a rigid, cross-linked structure that offers superior thermal and chemical resistance. This type is critical for high-reliability applications in aerospace and advanced semiconductor packaging where extreme conditions are present.
- Acrylic:Acrylic bonding films provide excellent clarity and UV resistance, making them suitable for optical applications and display bonding.
- Polyester:Polyester films offer good mechanical strength and dimensional stability, commonly used in flexible circuits and general industrial laminations.
- Polyimide:Polyimide films are known for their exceptional thermal stability and electrical insulation properties, essential for demanding aerospace and high-temperature electronics.
- Polyurethane:Polyurethane films exhibit high flexibility and abrasion resistance, finding use in textile lamination and protective coatings.
Leading the category by volume: Thermoplastic. Growing fastest: Thermosetting.
Application:
Application segments delineate where bonding films deliver critical functional value, often dictating material specifications and performance benchmarks.
- Electronics Assembly:Bonding films are indispensable for miniaturized components, providing structural integrity and electrical insulation in smartphones, tablets, and advanced computing devices. The continuous drive for thinner devices in China's manufacturing hubs fuels demand for ultra-thin films.
- Automotive Components:These films secure sensitive electronic modules, sensors, and battery cells within vehicles, requiring high thermal stability and vibration resistance. The expansion of ADAS and electric vehicle battery systems creates new specialized film requirements.
- Packaging:Bonding films contribute to the structural integrity and barrier properties of flexible packaging for food and consumer goods.
- Medical Devices:Precision bonding films are used in disposable medical instruments and wearable health monitors, demanding biocompatibility and sterilization resistance.
- Aerospace Interiors:Lightweight and fire-retardant bonding films secure interior panels and components in aircraft, adhering to strict safety standards.
- Consumer Goods:These films bond various materials in household appliances and sporting equipment, often balancing cost-effectiveness with performance.
The electronics assembly segment drives the largest volume, while automotive components exhibit significant expansion due to technological advancements.
Technology:
The technology segmentation reflects the activation method and chemical composition, directly impacting processing efficiency and environmental compliance.
- Hot Melt:These films are solid at room temperature and activate upon heating, offering solvent-free application and rapid bonding cycles. Hot melt technologies are gaining traction in high-speed assembly lines in Southeast Asia.
- Pressure Sensitive:These films adhere upon contact with slight pressure, providing immediate tack without heat or solvent activation. 3M Company specializes in these for high-stress applications.
- Solvent-Based:These films utilize a solvent carrier to facilitate application, which evaporates during curing, though regulatory pressures from the US EPA and China's MEE are reducing their use.
- UV Curable:UV curable films polymerize rapidly under ultraviolet light, offering fast processing and precise control, particularly in optical bonding.
- Water-Based:Water-based films use water as a carrier, reducing VOC emissions and aligning with stricter environmental regulations like REACH.
- Reactive:Reactive films undergo a chemical cross-linking process during bonding, forming robust and durable bonds.
Regulatory frameworks heavily influence the adoption of solvent-free and water-based film technologies.
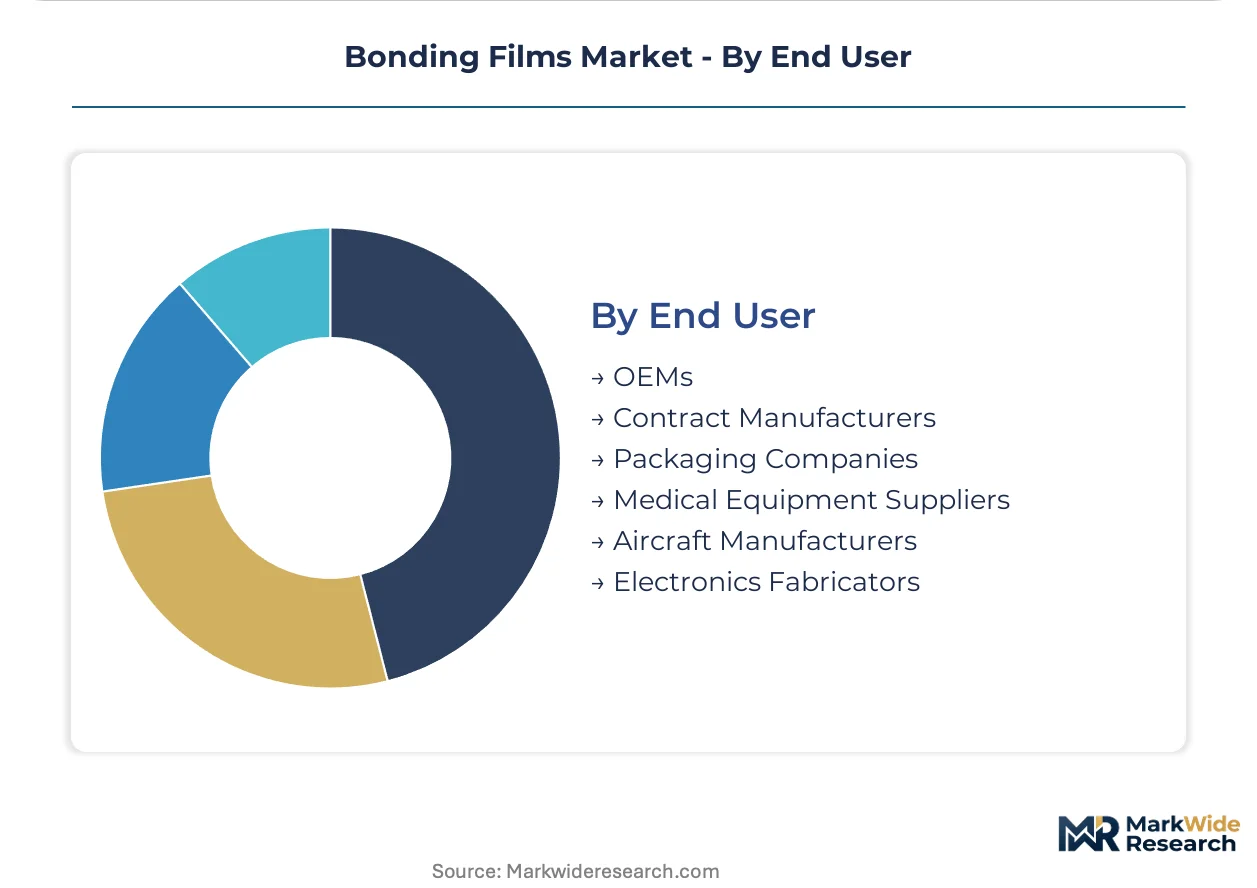
End User:
End user segments define the primary purchasers and integrators of bonding films, influencing procurement patterns and technical support needs.
- OEMs:Original Equipment Manufacturers directly integrate bonding films into their final products, often requiring custom formulations and extensive qualification support from suppliers. These companies demand films that meet specific design and performance criteria for their proprietary products.
- Contract Manufacturers:These firms produce components or entire products for other companies, managing complex supply chains and seeking cost-effective, high-performance films for diverse client projects. Their procurement prioritizes process efficiency and material versatility.
- Packaging Companies:These entities utilize bonding films for creating flexible and rigid packaging solutions for various industries.
- Medical Equipment Suppliers:Manufacturers of medical devices require specialized films that meet stringent regulatory and biocompatibility standards.
- Aircraft Manufacturers:Aerospace firms procure high-performance films for structural bonding and interior applications, emphasizing safety and durability.
- Electronics Fabricators:These companies specialize in producing electronic components and boards, using films for lamination and assembly processes.
OEMs and Contract Manufacturers exert significant influence over market specifications due to their scale and technical requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bonding films market exhibits a distinct geographical imbalance between production and consumption. Major electronics manufacturing hubs in Asia drive significant demand, while regulatory shifts in Europe and North America influence material innovation. This creates a complex interplay of localized requirements and global supply chains.
China
China's vast electronics manufacturing ecosystem creates immense demand for bonding films in smartphones and displays. The MEE's stringent regulations on volatile organic compounds compel a shift towards solvent-free chemistries. Production hubs like Shenzhen and Suzhou are rapidly adopting advanced hot-melt films for compliant manufacturing.
United States
United States demand for bonding films stems from its advanced electronics sector and expanding automotive electronics production, particularly ADAS. The US EPA's standards for volatile organic compounds promote solvent-free film technologies. Manufacturers in Silicon Valley and Detroit integrate specialized films for next-generation components and sensor mounting.
Germany
Germany's robust automotive industry and precision engineering sectors drive demand for high-performance bonding films. The EU's REACH regulation and RoHS directive significantly influence material selection for compliant films. Manufacturers in Bavaria and Baden-Württemberg develop specialized solutions for EV battery systems and sensor integration.
South Korea
South Korea's leadership in semiconductor packaging and advanced display technologies generates substantial demand for ultra-thin bonding films. National environmental standards influence the adoption of water-based and solvent-free film technologies. Manufacturing centers in Gyeonggi Province and Busan integrate these films for high-volume consumer electronics and complex device assembly.
Japan
Japanese manufacturers require bonding films for their sophisticated flexible circuits and high-temperature electronics applications. METI initiatives encourage development of advanced materials with superior thermal stability and electrical insulation. The Kanto and Kansai regions are key centers for specialized film development, particularly for demanding aerospace and medical devices.
Bonding Films Market Key Industry Players
The competitive structure tilts toward diversified material science conglomerates and specialized adhesive manufacturers. This market features a tiered landscape where large chemical companies compete alongside niche players focusing on specific performance requirements. Strategic archetypes include global chemical producers, advanced materials specialists, and regional electronics suppliers. Portfolio diversification and strategic partnerships are dominant competitive moves for securing market share.
Within the diversified material science tier, DuPont de Nemours exemplifies a company leveraging polymer science expertise for compliant material selection. Henkel AG & Co. KGaA, a German-based conglomerate, occupies a strong position with its diverse portfolio of thermoplastic and thermosetting films. The 3M Company, headquartered in the United States, anchors the advanced materials specialist archetype, particularly for high-stress pressure-sensitive adhesives. These entities represent the blend of chemical innovation and application-specific solutions driving market evolution.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| DuPont de Nemours |
| 3M Company |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| Dow Inc. |
| Toray Industries |
| Nitto Denko Corporation |
| Kuraray |
| Others |
Cost & Logistics Intelligence
Chinese manufacturing hubs' skilled labor concentrations drive cost-competitive bonding film production, influencing global pricing tiers for standard electronics applications. Wage differentials across Asian production centers directly impact the final product pricing for OEMs.
Pricing Analysis
Price erosion across standard thermoplastic films traces to high-volume manufacturing in Asia and intense competition among suppliers. The dominant pricing model is tiered, differentiating between highly customized, high-performance thermosetting films for aerospace and commodity-grade acrylics for consumer goods. Price differentiation stems from material quality, application-specific certifications like those for medical devices, and volume scale. Electronics assembly OEMs exhibit high price sensitivity for commodity films, while aerospace and medical device manufacturers prioritize performance and reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in key manufacturing hubs like China and South Korea manage the flow of bonding films to electronics fabricators. Global supply concentration centers on China, Japan, and Germany for specialized polymer resin production. The market draws from specialty polymer resins and various chemical additives as primary inputs. A structural risk involves commodity price volatility for these chemical feedstocks. The dominant distribution model involves direct sales from manufacturers to large OEMs and contract manufacturers, supplemented by specialized distributors for smaller players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bonding films market is undergoing a technology transition, with solvent-free hot melt and water-based films displacing traditional solvent-based chemistries. This shift aligns with evolving environmental regulations and performance demands.
For Market Incumbents: Deploy advanced R&D into multi-functional film technologies to counter the threat of component integration. Secure long-term supply agreements for high-purity polymer resins to mitigate raw material volatility. Invest in capacity expansion in compliant production facilities, particularly for solvent-free and water-based technologies, to maintain market share against emerging competitors. Pursue strategic partnerships with leading electronics OEMs to co-develop next-generation bonding solutions.
For New Entrants and Emerging Players: Enter via specialized niches requiring superior thermal or chemical resistance, such as advanced semiconductor packaging. Focus on developing biocompatible films for medical devices, where qualification cycles are extended but margins are robust. The most penetrable segment involves solvent-free hot melt films for automotive electronics, particularly ADAS modules. A strong go-to-market angle involves offering comprehensive application engineering support to OEMs.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized material science firms given the increasing demand for high-performance, compliant films in electronics and automotive. The long-term viability for bonding films remains strong across the next decade, driven by miniaturization and EV adoption. Target acquisition archetypes include mid-cap innovators with proprietary solvent-free or multi-functional film technologies. The signal to watch is the accelerated adoption rate of multi-functional films in compact 5G modules.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Multi-Functional Films | Integrates thermal conductivity and EMI shielding, simplifying 5G module assembly for electronics OEMs. |
| Capacity Expansion for Solvent-Free Films | Addresses strict VOC regulations from China's MEE, enabling compliant production in Shenzhen. |
| Strategic Partnerships with Automotive OEMs | Secures early integration of specialized films for ADAS sensors and EV battery cell bonding. |
| Investment in Biocompatible Film Development | Meets stringent regulatory requirements for medical devices, opening high-margin application areas. |
| Supply Chain Diversification for Polymer Resins | Mitigates raw material price volatility, ensuring consistent production for film manufacturers. |
Research Approach
Trade association data, regulatory filings from the US EPA, and customs records anchored secondary inputs for this analysis. Primary research involved interviews with R&D directors, procurement leads at electronics fabricators, and application engineers from major automotive OEMs in Germany. This approach combined bottom-up market sizing with top-down validation, incorporating insights from industry experts. Secondary data sources included company annual reports, technical journals, and government environmental agency publications.
Market volume and value were modeled at a granular level across product type, application, technology, and end-user segments. The analytical framework integrated historical growth patterns and projected technological adoption rates throughout the forecast period. Compound annual growth rates were derived from a synthesis of supply-side capacity expansions and demand-side consumption trends. Key industry-specific inputs included electronics miniaturization roadmaps and electric vehicle production forecasts.
Revisions become necessary when significant shifts in regulatory frameworks, such as new EU RoHS restrictions, or unforeseen raw material supply disruptions materialize. Forecasts reflect assumptions regarding technological advancements and macroeconomic stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Nano Sealers Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Disposable Barrier Sleeves Market