
 Micro-Perforated Food Packaging Market | 2026-2036
Micro-Perforated Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Perforated Food Packaging Market Analysis
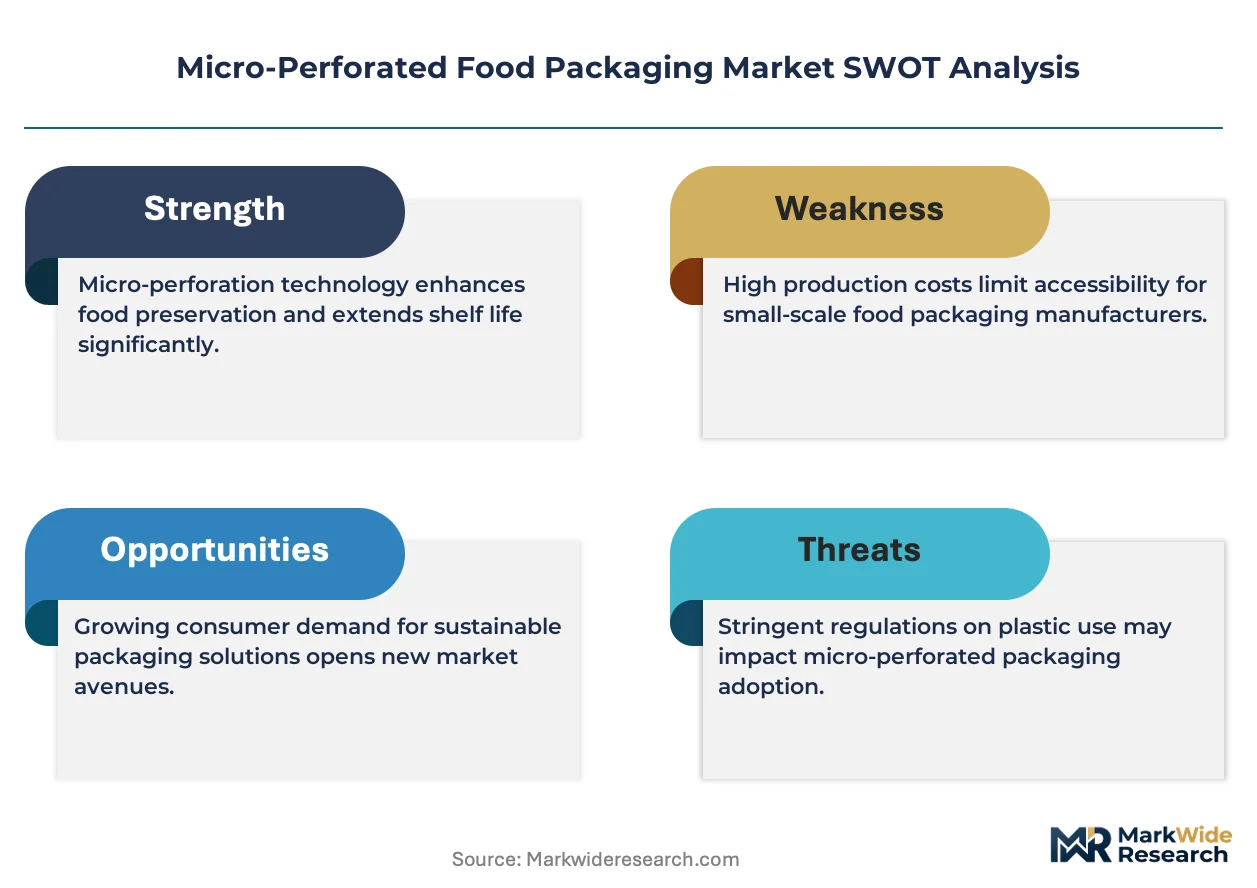
Fresh produce retail is pivoting toward micro-perforated formats as grocers seek to reduce shrink from respiring vegetables and fruits. Amcor plc leverages its global film manufacturing footprint to supply major European supermarket chains with customized perforation patterns. Sealed Air anchors North American demand through its Cryovac brand's controlled-atmosphere packaging systems for meat and bakery applications. Mondi Plc competes with integrated kraft paper and plastic hybrid solutions that target sustainability-focused retailers.
Micro-perforated food packaging refers to flexible or rigid materials containing laser- or mechanically-drilled holes ranging from 50 to 200 microns, engineered to balance oxygen ingress with moisture retention for respiring food products. The perforation density, typically measured in holes per square meter, determines the modified atmosphere achieved inside the package for specific produce respiration rates. Polyethylene films dominate volume due to their cost position and sealability, though PLA is gaining traction among food manufacturers responding to compostability mandates. Bags lead application share for loose produce, while trays capture higher margins in pre-cut vegetable and ready-to-eat meat segments where presentation and shelf-life extension command premium positioning.
The FDA regulates direct food contact materials through 21 CFR compliance requirements, while the EU F-Gas Regulation and REACH framework constrain fluorinated barrier chemistries and mandate substance disclosure for packaging films. BIS certification in India enforces migration limits that affect polyethylene and polypropylene formulations entering the food packaging supply chain. Stakeholders must monitor evolving extended producer responsibility schemes and perforation recyclability standards as mechanical recycling streams struggle with mixed-format packaging contamination.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is tightening material recovery targets across Europe, forcing converters to redesign perforation geometries that survive mechanical recycling streams without contamination. This regulatory pressure is compressing development timelines and reshaping R&D allocation across film suppliers.
Growth Catalysts
- REACH substance disclosure mandates:European film manufacturers accelerate reformulation of barrier chemistries to eliminate restricted fluorinated compounds, opening substitution demand for perforated mono-material structures.
- Fresh produce retail consolidation:Centralized distribution networks in Germany favor standardized perforated film formats that reduce SKU complexity and enable automated packing lines.
- Laser perforation precision:Beam-steering technology now achieves hole diameter consistency below 75 microns, extending shelf-life modulation to berries and delicate leafy greens previously excluded from modified atmosphere packaging.
Market Restraints
- Polyethylene resin price volatility:Feedstock fluctuations in naphtha and ethane markets compress converter margins and deter long-term supply contracts with produce distributors.
- Mechanical recycling contamination:Mixed-format packaging containing perforated films with adhesive labels or multilayer structures faces rejection by European mechanical recycling facilities under tightened EU sorting protocols.
- Paper-based barrier substitutes:Kraft paper and molded fiber packaging with breathable coatings threaten perforated plastic formats in premium produce segments where tactile sustainability signals command buyer attention.
Strategic Opportunities
- India FSSAI compliance pathways:Migration limit enforcement for polyethylene and polypropylene creates first-mover advantage for converters certifying perforated structures to BIS standards ahead of domestic competitor scaling.
- Pre-cut vegetable ready-to-eat trays:Premium positioning in convenience-oriented retail formats rewards perforation patterns optimized for cut-surface respiration rates, capturing margin expansion unavailable in bulk loose produce bags.
- Compostability mandate alignment:PLA perforation integration with industrial composting infrastructure responds to municipal organic waste diversion targets in France and Italy.
Industry Challenges
- Perforation pattern IP fragmentation:Proprietary laser drilling algorithms and respiration-rate mapping databases create licensing complexity for converters entering controlled-atmosphere segments.
- Multi-site certification coordination:FDA 21 CFR compliance for US-bound exports must align with EU F-Gas and REACH requirements, extending validation timelines for global film suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Perforated Food Packaging Market |
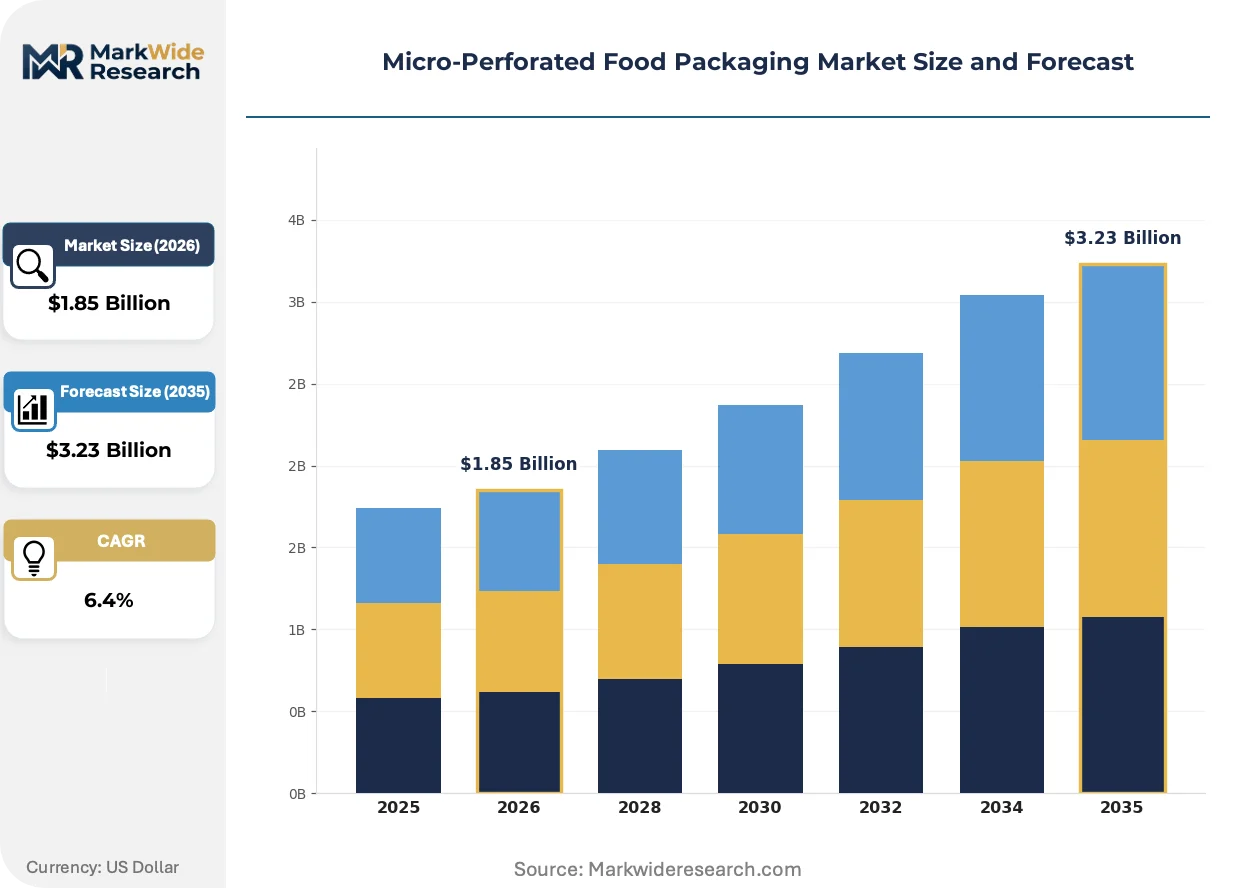
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Bags, Trays, Containers Material: Polyethylene, Polypropylene, PLA, PET End User: Food Manufacturers, Retailers, Distributors, Restaurants Application: Fruits, Vegetables, Meat, Bakery |
| Companies Covered | Amcor plc, Sealed Air, Mondi Plc, KM Packaging Services Ltd., Coveris, Uflex Limited, Huhtamaki, Constantia Flexibles, Specialty Polyfilms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Perforated Food Packaging Market Emerging Trajectories
Active modification of packaging architectures is reshaping competitive positioning in breathable films. Three developments dominate current investment priorities across converters and equipment suppliers.
Smart perforation systems are integrating real-time respiration monitoring through embedded colorimetric indicators that shift hue with internal atmosphere composition. Berry packers in California and the Netherlands deploy these structures to reduce quality claims from anaerobic fermentation. The technology is integrating predictive shelf-life algorithms into retail inventory management, compressing write-off rates for high-value soft fruit categories.
The EU F-Gas Regulation constrains hydrofluorocarbon use in barrier film manufacturing, accelerating migration to perforated mono-material polyethylene for modified atmosphere applications. German retail chains now specify fluorine-free structures in produce category tenders. Film converters respond by consolidating laser perforation investments in facilities serving pan-European supermarket networks.
Centralized produce procurement through vertically integrated retail groups is displacing fragmented wholesaler networks across Northern Europe. German and Dutch supermarket operators now specify perforation density standards in direct supplier agreements. This concentration compresses converter margins while rewarding scale investments in high-volume laser drilling capacity.
Micro-Perforated Food Packaging Market Segmentation
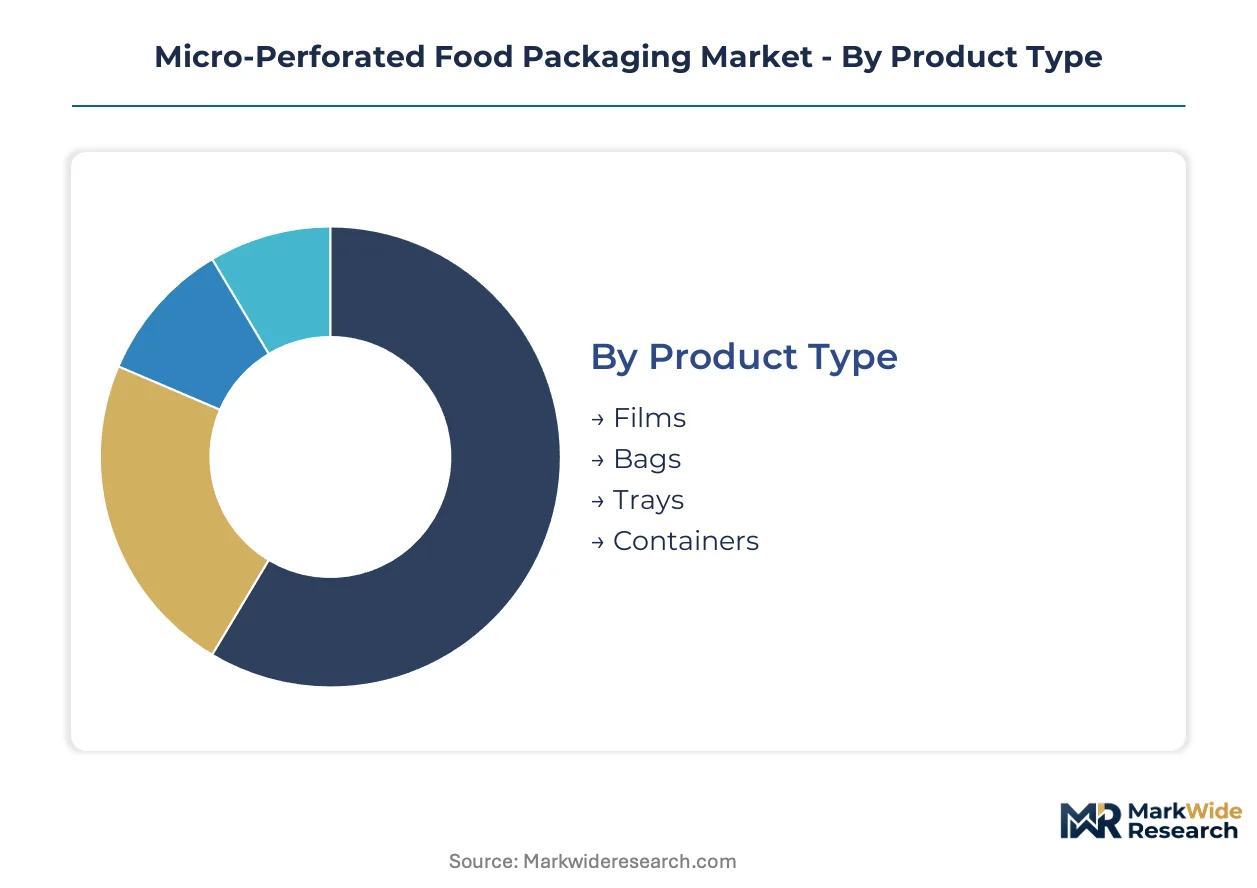
Micro-perforated food packaging segments reflect divergent technical requirements across respiration rates, barrier needs, and automated handling speeds. Buyers prioritize perforation precision, seal integrity, and recyclability compliance in distinct combinations by application.
Product Type:
Cost tier determines equipment compatibility and margin structure for converters serving produce supply chains.
- Films:Rollstock formats with laser-drilled perforation patterns ranging from 50 to 200 microns dominate high-volume automated packing lines. German retail procurement concentrates demand for standardized polyethylene film gauges that reduce changeover downtime in centralized distribution centers.
- Bags:Pre-formed pouches with integrated perforation zones capture loose produce volume in European supermarket chains. French and Italian compostability mandates are tilting material selection toward PLA structures in premium organic produce segments.
- Trays:Rigid thermoformed bases with lidded perforation arrays serve pre-cut vegetable ready-to-eat applications.
- Containers:Injection-molded or thermoformed rigid formats with breathable membranes address berry and cherry tomato segments.
Volume sits with Films; growth tilts toward Trays.
Material:
Application temperature range and end-of-life pathway drive procurement decisions across fresh produce categories.
- Polyethylene:Linear low-density and metallocene grades deliver cost-efficient sealability and puncture resistance for high-throughput produce packing. REACH substance disclosure mandates are accelerating reformulation away from fluorinated barrier additives in European converter operations.
- Polypropylene:Cast and oriented films offer higher temperature tolerance for hot-fill and steam-sterilized applications. Indian FSSAI migration limit enforcement is creating certification bottlenecks for polypropylene structures entering food contact supply chains.
- PLA:Bio-based polylactide integrates with industrial composting infrastructure in France and Italy.
- PET:Oriented polyester provides optical clarity and rigidity for premium produce presentation.
Polyethylene commands current volume; PLA climbs the fastest on compostability alignment.
End User:
Customer type dictates order scale, specification complexity, and technical service intensity for perforation suppliers.
- Food Manufacturers:Branded produce packers specify customized perforation densities mapped to specific respiration curves of cultivar varieties. California berry packers deploy smart perforation systems with colorimetric indicators to reduce anaerobic fermentation claims.
- Retailers:Vertically integrated supermarket operators in Germany and the Netherlands now mandate perforation standards in direct supplier agreements, compressing converter margins while rewarding scale investments.
- Distributors:Wholesaler networks in fragmented Southern European markets favor generic perforated bag formats.
- Restaurants:Foodservice procurement concentrates on bulk perforated formats for pre-portioned produce.
Retailers drive standardization; food manufacturers sustain premium positioning.
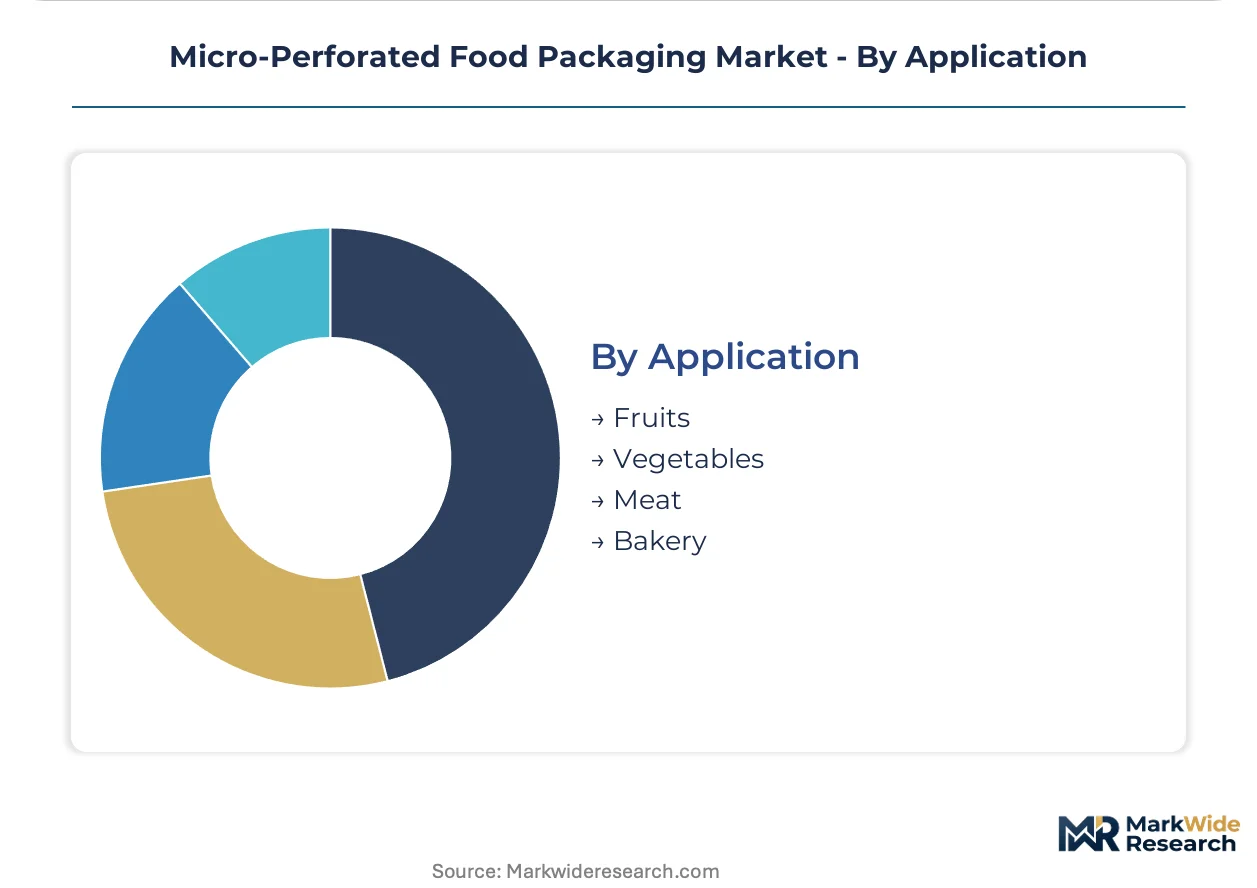
Application:
Respiration rate variance determines perforation engineering complexity and pricing differentiation across fresh categories.
- Fruits:Berry applications demand sub-75 micron laser precision to balance oxygen ingress with moisture retention for soft fruit shelf-life extension. Netherlands-based packers integrate predictive shelf-life algorithms with smart perforation inventory management.
- Vegetables:Leafy greens and brassicas require moderate perforation densities that accommodate elevated respiration post-harvest. Pre-cut vegetable trays in convenience-oriented formats command margin expansion unavailable in bulk loose produce.
- Meat:Modified atmosphere requirements for fresh meat constrain perforation adoption to specific case-ready applications.
- Bakery:Moisture equilibrium needs for artisan bread limit perforation to controlled-release applications.
Vegetables anchor current volume; fruits gain share fastest on berry precision demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and the Netherlands, while consumption spreads across retail networks in France, Italy, and the United Kingdom. This geographic split shapes converter investment patterns and regulatory compliance architectures.
Germany
Centralized retail distribution networks favor standardized perforated film formats that reduce SKU complexity. The EU F-Gas Regulation constrains fluorinated barrier chemistries, accelerating migration to mono-material polyethylene structures. Film converters in North Rhine-Westphalia consolidate laser perforation investments to serve pan-European supermarket procurement.
Netherlands
Vertically integrated retail operators mandate perforation density standards in direct supplier agreements. REACH substance disclosure requirements enforce reformulation of barrier additives across converter operations. Berry packers in the Westland region deploy smart perforation systems with colorimetric indicators to reduce anaerobic fermentation claims.
France
Compostability mandates in municipal organic waste diversion programs tilt material selection toward PLA structures. The EU Packaging and Packaging Waste Regulation tightens material recovery targets, forcing redesign of perforation geometries for mechanical recycling compatibility. Converters in the Île-de-France region align PLA perforation integration with industrial composting infrastructure.
Italy
Premium organic produce segments drive demand for certified compostable perforated bags. F-Gas Regulation constraints eliminate fluorinated barrier options for modified atmosphere applications. Packaging specialists in Emilia-Romagna develop perforated mono-material solutions for fresh-cut vegetable ready-to-eat formats.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for FDA-aligned exports and EU-bound shipments. Retail consolidation concentrates procurement power among supermarket operators specifying perforation standards. Film suppliers in the Midlands navigate dual certification requirements for 21 CFR and REACH frameworks.
Micro-Perforated Food Packaging Market Vendor Landscape
Top-tier vendors anchor global film manufacturing, while mid-scale converters compete on regional customization and laser perforation specialization. The vendor base separates into integrated multinational suppliers, regional film specialists, and equipment-technology licensors. Three archetypes dominate: scale-driven material suppliers, precision-perforation technology owners, and sustainability-focused hybrid solution providers. Competitive moves center on laser drilling capacity expansion and strategic partnerships with retail procurement networks.
Among integrated multinational suppliers, Amcor plc and Sealed Air occupy positions exemplifying scale-driven material supply and controlled-atmosphere system integration respectively. Mondi Plc represents the sustainability-focused archetype with integrated kraft paper and plastic hybrid offerings. These three companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air |
| Mondi Plc |
| KM Packaging Services Ltd. |
| Coveris |
| Uflex Limited |
| Huhtamaki |
| Constantia Flexibles |
| Specialty Polyfilms |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA 21 CFR-compliant export structures and domestic-only perforated films manifests in both pricing premiums and supply chain segregation. Buyers demanding REACH-aligned barrier chemistries and fluorine-free mono-materials face extended lead times and contracted volume commitments, while commodity polyethylene rollstock trades on spot resin indices with minimal technical service attachment.
Pricing Analysis
Short lead-time premiums dominate pricing architecture for customized laser perforation patterns mapped to specific cultivar respiration curves. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier, volume scale, and customization depth. Pricing pressure stems from polyethylene resin volatility in naphtha and ethane feedstock markets. Distributor networks in fragmented Southern European markets exhibit highest price sensitivity; German retail procurement functions show lowest elasticity due to specification lock-in.
Supply Chain Analysis
Reverse-logistics flows for perforated film scrap face rejection under tightened EU mechanical recycling protocols, forcing converters toward closed-loop regrind systems or energy recovery pathways. Supply concentrates in Germany, the Netherlands, and Italy. Raw material dependencies center on linear low-density polyethylene resin, laser drilling equipment, and fluorine-free barrier additives. Single-source vulnerability sits with specialized laser perforation head suppliers. Distribution runs through centralized retail procurement networks in Northern Europe and fragmented wholesaler channels in Southern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU F-Gas Regulation and REACH substance disclosure mandates erect barrier-to-entry moats favoring incumbents with validated certification pathways.
For Market Incumbents: Anchor market position through captive laser perforation capacity additions in North Rhine-Westphalia and Westland production clusters. Deepen backward integration into fluorine-free barrier additive formulation to offset REACH-driven substitution costs. Defend against kraft paper hybrid substitutes by accelerating PLA compostability certification for French and Italian municipal organic waste programs. For New Entrants and Emerging Players: Indian food manufacturers facing FSSAI migration limit enforcement represent the most penetrable buyer archetype for BIS-certified polyethylene and polypropylene structures. Target pre-cut vegetable ready-to-eat tray segments where perforation pattern IP fragmentation creates licensing gaps. Pursue equipment-technology licensing partnerships with European laser drilling specialists as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with precision-perforation technology owners given laser drilling capacity consolidation among pan-European retail networks. Long-term viability favors converters with validated multi-site certification coordination across FDA 21 CFR and REACH frameworks. Monitor EU Packaging and Packaging Waste Regulation enforcement timelines as the inflection signal for mechanical recycling-compatible perforation geometry demand.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Reformulation | REACH compliance eliminates fluorinated chemistries, opening substitution demand for mono-material structures. |
| Laser Perforation Capacity Expansion | German retail procurement concentration rewards scale investments in beam-steering precision below 75 microns. |
| PLA Compostability Certification | French and Italian municipal organic waste diversion targets create first-mover advantage in certified structures. |
| Smart Perforation System Integration | Colorimetric indicator deployment with California and Netherlands berry packers reduces anaerobic fermentation claims. |
| BIS Certification Pathway Development | FSSAI migration limit enforcement in India creates certification bottlenecks for first-mover converters. |
Methodological Framework
Multi-period observation of laser perforation equipment deployment, resin formulation shifts, and retail procurement specification changes anchored the trend analysis, supplemented by interviews with film converter operations managers, laser equipment technology directors, supermarket category buyers, regulatory compliance officers, and composting facility operators. Secondary validation drew from EU F-Gas Regulation implementation reports, REACH substance restriction updates, BIS certification registries, and polyethylene trade flow data. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Input-output matrix modeling connected raw material cost indices, perforation density specifications by application, and end-user procurement volume patterns across product type, material, and geography dimensions. CAGRs derived from segmented growth rate build-ups incorporating respiration-rate mapping adoption curves and regulatory compliance phase-in schedules. Industry-specific forecast inputs included laser drilling capacity utilization rates and centralized retail distribution network expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU mechanical recycling protocol revisions and PLA industrial composting infrastructure buildout rates. Practitioners should monitor EU Packaging and Packaging Waste Regulation material recovery target announcements and Indian FSSAI enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Pipe Insulation Film Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Global Stretch and Shrink Film Market
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Special Effects Laminate Films Market