
 Nano Sealers Market | 2026-2036
Nano Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Sealers Market Analytics
Specialty chemical distribution is narrowing as nano sealer producers bypass traditional coatings distributors to serve automotive OEMs and electronics contract manufacturers directly. PPG Industries leverages its automotive refinish network to push nano sealer penetration into electric vehicle battery pack sealing. Henkel AG & Co. KGaA anchors European industrial demand through its adhesives and sealants technical service infrastructure. Sika AG specializes in construction-grade formulations, competing on specification depth with European infrastructure contractors.
Nano sealers constitute thin-film protective coatings engineered with particle sizes below 100 nanometers, typically formulated from silica, alumina, or hybrid polymer matrices that penetrate substrates at the molecular level to create hydrophobic or oleophobic barriers. The primary commercial purpose centers on extending substrate lifespan while reducing maintenance cycles across built infrastructure, transportation equipment, and electronic assemblies. Floor sealers and surface sealers occupy the mature volume base where polymer-based formulations command stable specification positions in commercial construction. Anti-graffiti sealers represent the fastest-expanding product category as transit authorities and municipal asset managers adopt sacrificial nano-film systems for public infrastructure protection. Automotive sealers concentrate margin pools around epoxy and polyurethane chemistries specified for underbody and powertrain sealing in electric vehicle platforms.
REACH registration requirements in Europe and EPA toxic substance controls in the United States constrain fluorinated nano sealer chemistries, redirecting formulation investment toward silicone and waterborne polymer alternatives. China's GB standards for volatile organic compound emissions in building materials and Japan's METI chemical substance reporting framework shape product registration pathways and manufacturing location decisions for suppliers serving Asian electronics supply chains. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions to anticipate reformulation costs and qualification timelines.
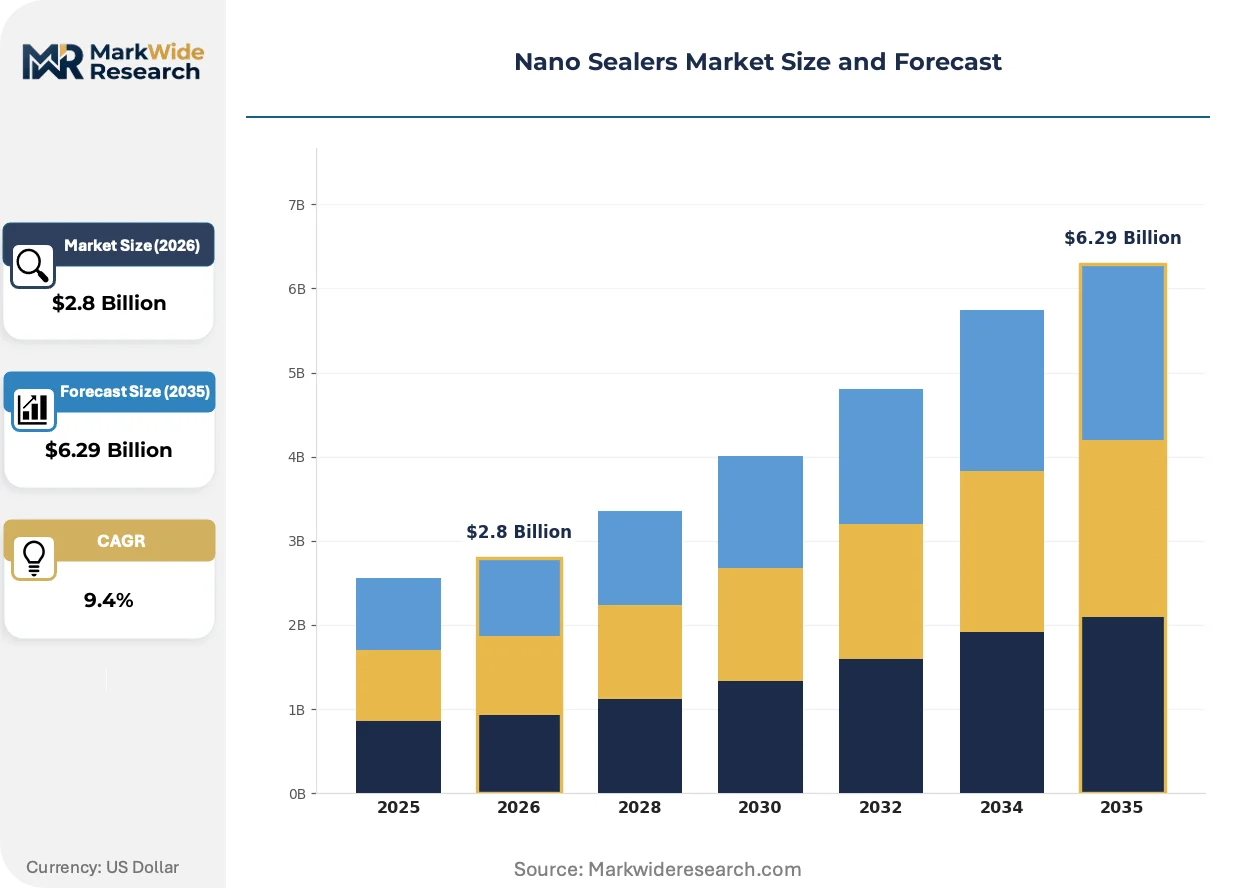
Market Dynamics
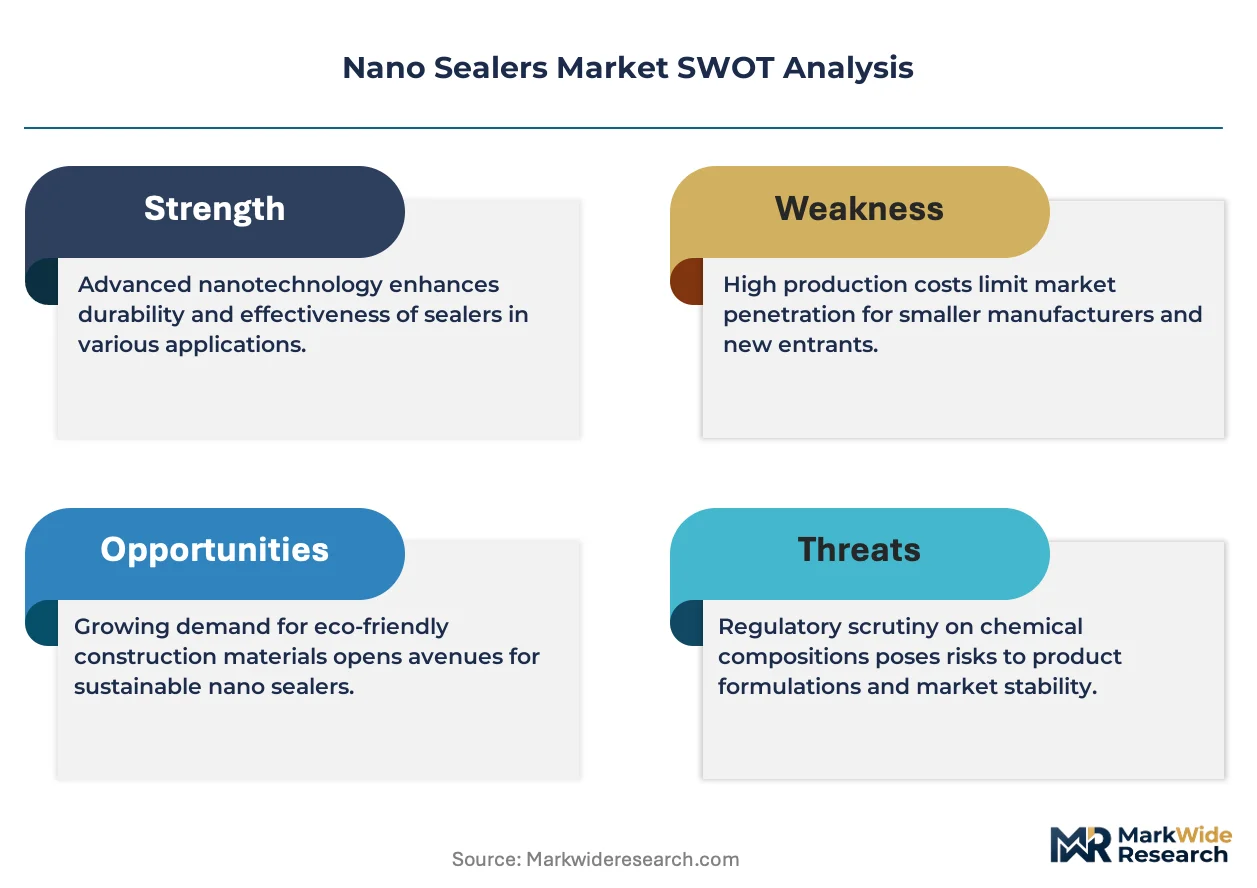
Fluorinated chemistry restrictions across REACH jurisdictions and EPA toxic substance frameworks are forcing wholesale reformulation toward silicone and waterborne polymer alternatives, compressing margins for incumbent suppliers while opening technical specification windows for compliant entrants.
Growth Catalysts
- EU Green Deal embodied carbon rules:German construction contractors are scaling nano sealer procurement for green building envelopes as tightening regulations mandate lower-carbon envelope materials.
- Consumer electronics moisture protection:Electronics OEMs in China's eastern coastal manufacturing clusters specify nano-sealed substrates for device reliability in humid operating environments.
- Electric vehicle battery pack sealing:Automotive OEMs require epoxy and polyurethane nano sealers for underbody and powertrain protection in EV platforms.
Market Restraints
- Per- and polyfluoroalkyl substance restrictions:REACH registration requirements and EPA toxic substance controls constrain fluorinated nano sealer chemistries, forcing costly reformulation cycles.
- Specialty monomer supply concentration:Silane precursors and hybrid polymer feedstocks concentrate among Asian petrochemical suppliers, creating input cost volatility.
- Qualification timeline compression:Japan's METI chemical substance reporting framework and China's GB standards for volatile organic compound emissions extend product registration pathways by 18-24 months.
Strategic Opportunities
- Anti-graffiti infrastructure protection:Transit authorities and municipal asset managers in North American and European cities are adopting sacrificial nano-film systems for public infrastructure.
- Direct-to-OEM distribution bypass:Nano sealer producers can circumvent traditional coatings distributors to serve automotive OEMs and electronics contract manufacturers through technical service partnerships.
- Waterborne polymer convergence:Hybrid formulations combining silica nanoparticles with waterborne polyurethane matrices address both regulatory compliance and performance specifications.
Industry Challenges
- Nanoparticle dispersion expertise shortage:Formulation chemists with sub-100 nanometer particle stabilization and substrate penetration optimization skills command premium compensation.
- Multi-jurisdiction registration synchronization:Suppliers must align REACH dossiers, EPA pre-manufacture notifications, and China's MEE chemical inventories simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Sealers Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Sealers, Surface Sealers, Anti-Graffiti Sealers, Automotive Sealers Application: Construction, Automotive, Electronics, Household Material: Polymer, Silicone, Polyurethane, Epoxy End User: Contractors, Manufacturers, DIY Enthusiasts, Commercial Users |
| Companies Covered | PPG Industries, Sherwin-Williams Company, Evonik Industries AG, Sika AG, 3M Company, Arkema, Wacker Chemie AG, Henkel AG & Co. KGaA, Nanovere Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Sealers Market Evolving Landscape
Formulation chemistry is pivoting decisively away from legacy fluorinated systems toward compliant alternatives, while distribution architectures fragment as technical service capabilities become the primary competitive differentiator.
Waterborne silica-polyurethane hybrid nano sealers penetrate concrete and stone substrates at molecular depth to create hydrophobic barriers without perfluorinated content. German infrastructure contractors and Chinese electronics assemblers specify these systems for 5-year performance warranties. The technology is rendering obsolete solvent-borne fluorinated sealers in commercial construction specifications.
REACH restrictions on per- and polyfluoroalkyl substances now cover the full carbon chain spectrum, eliminating grandfathered exemptions for short-chain chemistries. European coating formulators face 12-18 month requalification timelines for construction and automotive applications. Floor sealer and surface sealer categories are experiencing the fastest specification turnover as contractors preempt compliance deadlines.
Electronics contract manufacturers in Shenzhen and Dongguan clusters now require nano sealer technical data packages with full substance disclosure for Apple's Supplier Responsibility program and similar OEM mandates. Traditional coatings distributors lack the analytical documentation infrastructure to support these audits. Direct supplier-to-OEM technical partnerships are displacing multi-tier distribution for high-specification electronics substrates.
Nano Sealers Market Segmentation
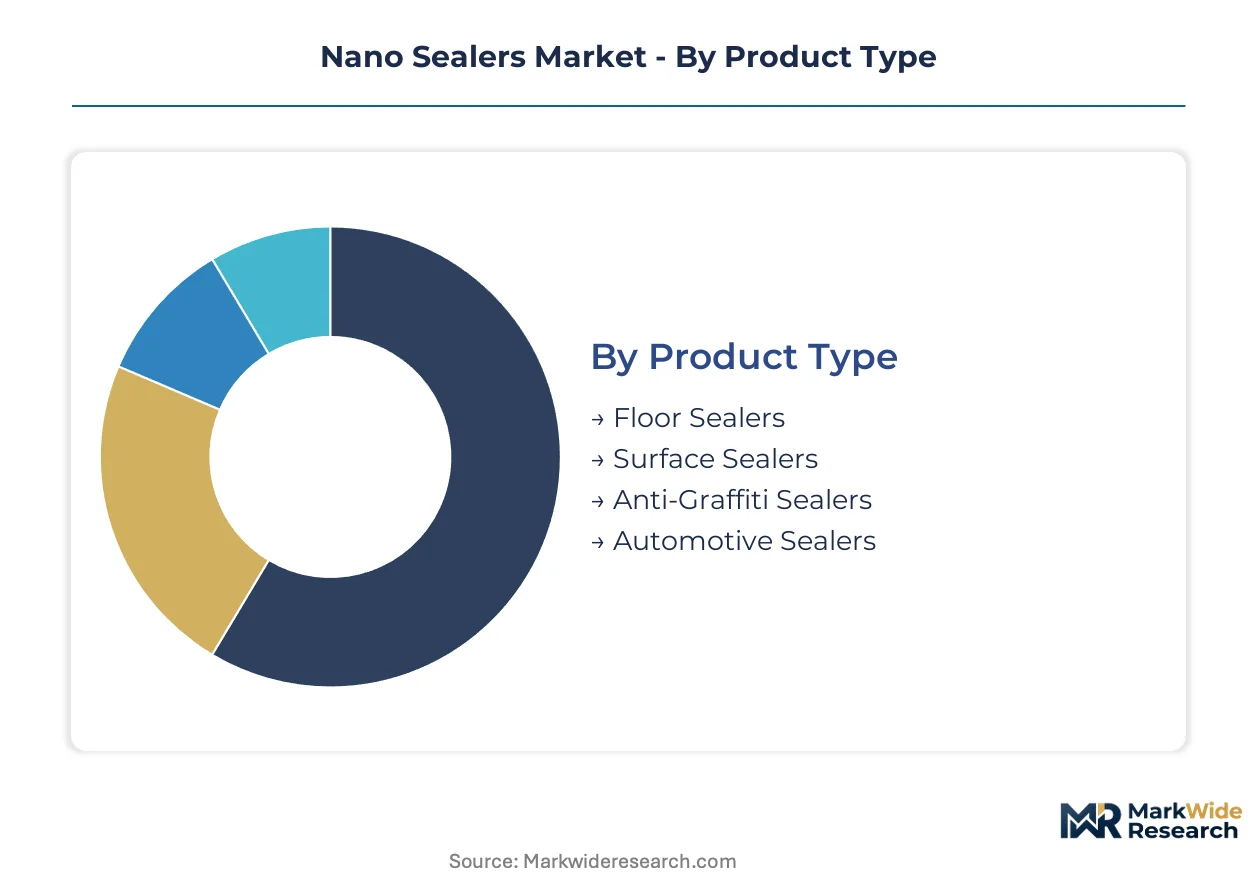
Nano sealer purchasing patterns diverge sharply across product chemistry, end-use durability requirements, and buyer technical sophistication. Specification depth and regulatory compliance thresholds determine margin capture within each segment cluster.
Product Type:
Application durability and substrate protection intensity define the cost-performance tiers across formulation categories.
- Floor Sealers:Polymer-based formulations dominate commercial construction specifications for concrete and terrazzo protection. German infrastructure contractors specify these systems for 5-year performance warranties on transit facility flooring.
- Anti-Graffiti Sealers:Sacrificial nano-film systems engineered with silica nanoparticles create removable barriers on porous stone and metal surfaces. Transit authorities in North American and European cities are adopting these for public infrastructure protection against vandalism.
- Surface Sealers:Hybrid polymer matrices penetrate stone and masonry at molecular depth for hydrophobic barriers.
- Automotive Sealers:Epoxy and polyurethane chemistries specified for underbody and powertrain sealing in electric vehicle platforms.
Floor sealers command the established base. The steepest expansion runs through anti-graffiti sealers.
Application:
End-use environments shape formulation requirements from structural durability to precision electronics protection.
- Construction:Building envelope applications demand hydrophobic and oleophobic barriers for concrete, stone, and facade materials. EU Green Deal embodied carbon rules are tightening specification standards for low-carbon envelope materials.
- Electronics:Moisture protection specifications concentrate in China's eastern coastal manufacturing clusters where OEMs require nano-sealed substrates for device reliability in humid operating environments.
- Automotive:Battery pack and underbody sealing applications drive epoxy and polyurethane formulation demand.
- Household:DIY-grade formulations emphasize application simplicity and lower VOC content for residential stone and tile protection.
Construction anchors volume demand. Electronics applications are climbing the fastest on OEM specification intensity.
Material:
Regulatory compliance trajectories and substrate compatibility determine chemistry selection across end-use segments.
- Silicone:Waterborne formulations displace fluorinated systems under REACH per- and polyfluoroalkyl substance restrictions. European coating formulators face extended requalification timelines for construction and automotive applications.
- Polymer:Silica-polyurethane hybrid systems combine nanoparticle penetration with film-forming durability for concrete and stone substrates.
- Polyurethane:Automotive underbody and powertrain sealing specifications favor these chemistries for chemical resistance and thermal stability.
- Epoxy:Battery pack sealing in electric vehicle platforms requires these high-crosslink density formulations.
Polymer formulations hold the mature specification base. Silicone alternatives are gaining share fastest on regulatory compliance.
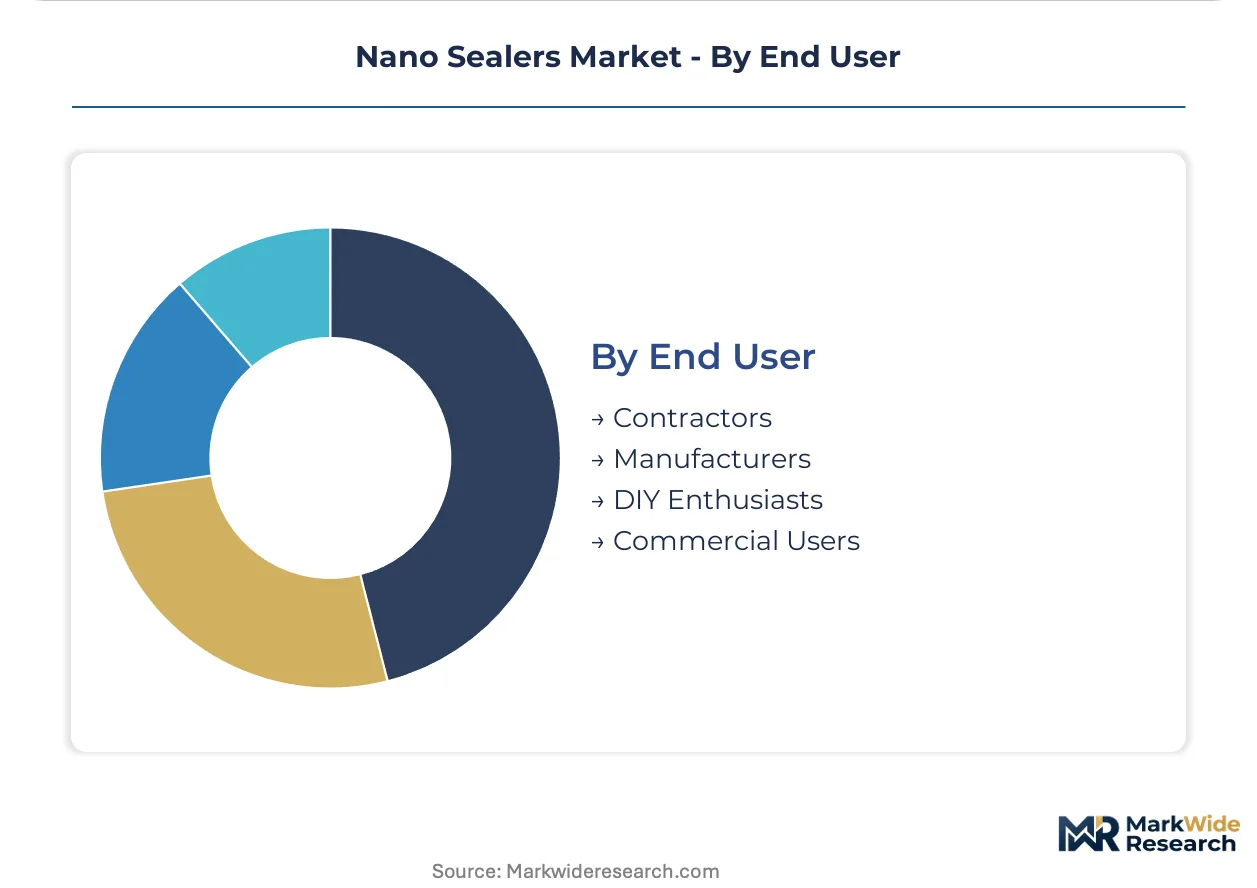
End User:
Technical service requirements and procurement scale separate professional specification from consumer-grade purchasing.
- Contractors:German construction contractors and European infrastructure specialists drive specification depth for green building envelopes and transit facility protection systems.
- Manufacturers:Electronics contract manufacturers in Shenzhen and Dongguan clusters require full substance disclosure data packages for OEM supplier responsibility audits.
- DIY Enthusiasts:Residential purchasers prioritize application convenience and low-odor formulations for interior stone and tile projects.
- Commercial Users:Facility managers and municipal asset managers specify anti-graffiti systems for public infrastructure maintenance cost reduction.
Contractors anchor the professional specification base. Manufacturers are expanding most quickly on direct supplier-to-OEM technical partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European nano sealer import capacity, while Shenzhen's electronics export corridors anchor Asian supply chain velocity for moisture-protective substrates.
United States
EPA toxic substance frameworks and state-level VOC regulations drive reformulation toward silicone alternatives in construction applications. The Inflation Reduction Act's clean building incentives accelerate specification of low-carbon envelope materials in commercial real estate. Houston's petrochemical corridor hosts hybrid polymer feedstock production serving automotive underbody sealing programs.
Germany
EU Green Deal embodied carbon rules tighten procurement standards for green building envelopes across federal infrastructure projects. REACH per- and polyfluoroalkyl substance restrictions eliminate grandfathered short-chain fluorinated chemistries, forcing 12-18 month requalification cycles. Bavarian automotive suppliers specify epoxy nano sealers for electric vehicle battery pack protection.
China
GB standards for volatile organic compound emissions in building materials extend product registration timelines for domestic and imported formulations. Dual carbon goals accelerate specification of waterborne polymer systems in state-backed construction projects. Dongguan electronics contract manufacturers demand full substance disclosure data packages for OEM supplier responsibility audits.
Japan
METI chemical substance reporting frameworks create multi-layer compliance requirements for nano sealer importers and domestic producers. JIS standards for construction materials specify performance warranties for hydrophobic barrier systems in commercial building envelopes. Nagoya's automotive manufacturing cluster drives polyurethane formulation demand for powertrain sealing applications.
South Korea
MFDS chemical safety assessments and KOSHA industrial exposure limits shape workplace handling protocols for nanoparticle formulations. Government green building certification programs specify low-VOC sealers for public infrastructure projects. Seoul Capital Area electronics assemblers require nano-sealed substrates for consumer device moisture protection in humid operating environments.
Nano Sealers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation chemistry and dispersion technology. The vendor base organizes around three strategic archetypes: diversified coatings conglomerates with automotive refinish networks, adhesives and sealants specialists with technical service infrastructure, and construction chemicals providers with specification depth. Consolidation pressure runs through direct-to-OEM distribution bypasses and waterborne polymer convergence investments.
Within the diversified coatings tier, PPG Industries and Sherwin-Williams Company occupy positions anchored by automotive and architectural distribution networks. Sika AG and Henkel AG & Co. KGaA exemplify the construction and industrial adhesives archetype with specification-driven technical service models. Evonik Industries AG represents the specialty chemical segment with silane precursor and hybrid polymer feedstock capabilities.
| Leading Market Players |
|---|
| PPG Industries |
| Sherwin-Williams Company |
| Evonik Industries AG |
| Sika AG |
| 3M Company |
| Arkema |
| Wacker Chemie AG |
| Henkel AG & Co. KGaA |
| Nanovere Technologies LLC |
| Others |
Value Network & Pricing Analysis
Asian petrochemical suppliers concentrate silane precursor and hybrid polymer feedstock production, anchoring margin pools with European automotive OEMs and Chinese electronics contract manufacturers who face volatile input cost pass-through. This upstream concentration forces downstream formulators to absorb margin compression or accelerate silicone alternative development.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specification-grade formulations for EV battery sealing from commercial construction volume and DIY residential products. Price differentiation hinges on REACH compliance certification and volume scale, with automotive OEM procurement commanding premium positioning. Cost compression in fluorinated legacy tiers is intensifying because reformulation cycles drain R&D budgets. DIY enthusiasts exhibit highest price sensitivity while German infrastructure contractors prioritize warranty-backed performance over unit economics.
Supply Chain Analysis
Electronics contract manufacturers in Shenzhen and Dongguan clusters hold dominant moisture-protection substrate capacity, with secondary concentration among German automotive Tier 1s and South Korean display assemblers. Nano sealer production draws from silane precursors, silica nanoparticles, and waterborne polyurethane resins. Single-source vulnerability concentrates in Asian petrochemical silane supply. Distribution runs through direct technical service partnerships displacing traditional coatings distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorinated chemistry restrictions across REACH jurisdictions are disrupting incumbent formulation portfolios faster than replacement timelines, compressing qualification windows for compliant alternatives.
For Market Incumbents: Insulate specification positions by accelerating waterborne polymer R&D investment and deepening captive supply of silane precursors through backward integration into Asian feedstock partnerships. PPG Industries and Henkel AG must preempt Chinese electronics OEM audits with full substance disclosure infrastructure before Apple's Supplier Responsibility program tightens further. For New Entrants and Emerging Players: Build out anti-graffiti sealer capabilities targeting North American transit authorities and European municipal asset managers where sacrificial nano-film adoption outpaces incumbent technical service coverage. Direct technical partnerships with Shenzhen electronics assemblers bypass distributor infrastructure gaps. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across waterborne polymer formulation as equipment repurposing from fluorinated lines reduces greenfield requirements. Acquire mid-cap specialists with nanoparticle dispersion expertise and existing REACH dossiers. Watch EPA pre-manufacture notification timelines as inflection signal for US market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | Captive supply from Asian petrochemical partners secures margin against feedstock volatility. |
| Waterborne Polymer R&D Scale-Up | REACH-compliant formulations penetrate German construction specifications ahead of fluorinated bans. |
| Direct-to-OEM Technical Partnership | Apple Supplier Responsibility audits favor suppliers with full substance disclosure infrastructure. |
| Anti-Graffiti Sealer Capacity Expansion | Transit authority procurement in Chicago and Berlin outpaces incumbent technical service reach. |
| Long-term Supply Agreement with EV Battery Producers | Bavarian automotive clusters specify epoxy nano sealers for platform-standardized battery packs. |
Research Methodology
Operator-level perspectives from coatings formulators, automotive OEM procurement leads, electronics contract manufacturing quality directors, and construction chemicals distribution managers anchored the qualitative base. Primary interview insights combined with secondary validation from ECHA REACH registration databases, EPA pre-manufacture notification filings, Chinese GB standards documentation, and customs trade flow records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed demand trajectories across product chemistry tiers, end-use durability requirements, and buyer technical sophistication segments throughout the forecast period. CAGRs derived from regression analysis against construction spending indices, EV production forecasts, and electronics OEM capex disclosures. Modeled inputs included EU Green Deal embodied carbon compliance timelines and METI chemical substance reporting pathway durations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical conglomerates would shift outcomes. Quarterly review of REACH restriction amendment proposals and EPA toxic substance control rulemakings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Bonding Films Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Hydrocolloid Coating Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Europe Barrier Coated Paper Market