
 Flexible Plastic Drinking Pouch Market | 2026-2036
Flexible Plastic Drinking Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Plastic Drinking Pouch Market Foresight
Buyer concentration is shifting as retail chains consolidate procurement while vending operators fragment into smaller regional networks. Amcor Plc leverages its global manufacturing footprint to serve multinational beverage accounts. Berry Global Group, Inc. anchors North American supply through specialized extrusion capabilities. Mondi Group competes on fiber-based hybrid structures that reduce plastic content.
Flexible plastic drinking pouches are multi-layer laminated containers, typically incorporating polyethylene or polypropylene with oxygen-barrier films such as EVOH, formed through blown film extrusion and converted via horizontal form-fill-seal lines. They serve primary commercial purposes in ambient and chilled beverage distribution where weight reduction and cube efficiency outperform rigid bottles. Stand-up pouch designs with integrated spouts command premium positioning in sports drinks and flavored water, while pillow formats dominate value-tier juice applications. Spouted configurations in energy drinks represent the fastest-growing design category as resealability becomes a functional requirement.
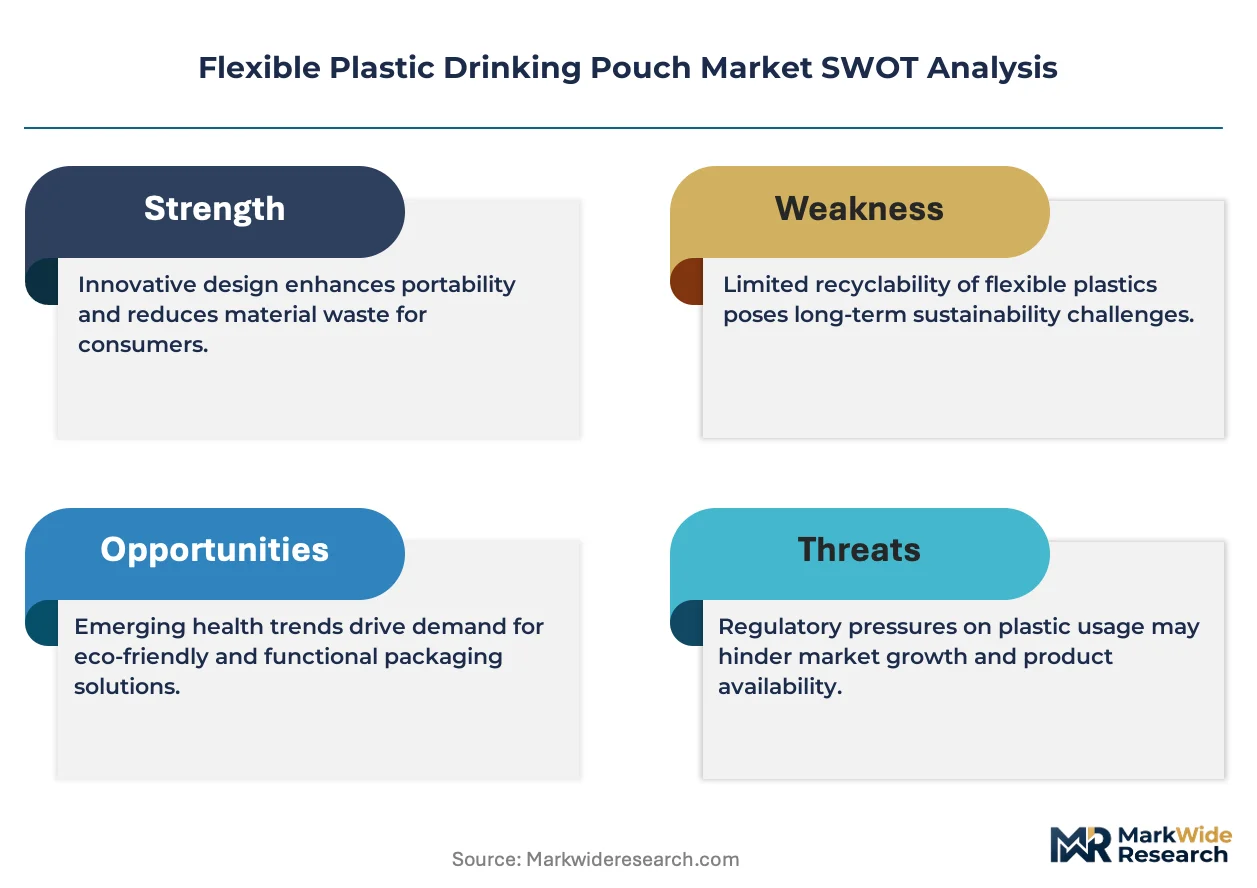
The EPA regulates food-contact substances under 21 CFR 177, while FDA sets migration limits for additives in polyethylene and polypropylene layers. Europe's REACH framework and EFSA food-contact assessments constrain phthalate and adhesive chemistries, reshaping material specifications for export-bound production. Stakeholders must monitor evolving extended producer responsibility schemes and decide between mono-material recyclability investments versus multi-layer performance advantages.
Market Dynamics
Europe's Single-Use Plastics Directive is forcing material reengineering across the value chain, compelling converters to abandon multi-layer barrier films in favor of recyclable mono-material polyethylene structures that sacrifice oxygen protection for circularity compliance.
Growth Catalysts
- REACH chemical restrictions:ECHA's tightening controls on phthalate plasticizers accelerate migration-compliant adhesive development, opening specification windows for European export-bound production.
- On-the-go consumption patterns:Sports drink brands are expanding spouted pouch formats for gym and outdoor retail channels where resealability commands functional premiums over rigid bottles.
- Tropical climate distribution:Southeast Asia's ambient retail infrastructure favors lightweight chilled pouches that reduce transport energy versus glass or PET alternatives.
Market Restraints
- EVOH barrier supply concentration:Ethylene vinyl alcohol film production clusters in Japan and South Korea, exposing converters to shipping cost volatility and currency fluctuation risk.
- Mono-material performance ceiling:Polyethylene-only structures cannot match multi-layer oxygen transmission rates, limiting shelf-stable juice applications to refrigerated distribution.
- Extended producer responsibility fees:Germany's VerpackG and France's Citeo schemes impose per-unit recycling contributions that compress margins on value-tier pillow pouch formats.
Strategic Opportunities
- Indian organized retail expansion:Reliance Retail and D-Mart are building cold-chain beverage sections in Tier-2 cities where pouch formats reduce breakage versus glass in humid monsoon conditions.
- Fiber-based hybrid structures:Mondi Group's paper-plastic laminates exploit EFSA approval pathways for reduced plastic content claims in premium positioned flavored waters.
- Deposit-return scheme alignment:Italy's CONAI framework rewards mono-material designs with lower eco-modulated fees, creating specification pull from export-oriented bottlers.
Industry Challenges
- Blown film technician scarcity:Specialized extrusion operators capable of maintaining EVOH layer thickness tolerances below 5 microns are concentrated in aging workforces across Midwestern US converting hubs.
- Horizontal form-fill-seal line reconfiguration:Retrofitting legacy equipment for mono-material seal temperatures requires capital outlays that mid-tier converters defer amid interest rate uncertainty.
- Migration testing backlog:FDA's 21 CFR 177 notification queue for novel adhesive chemistries stretches to 18 months, delaying product launches for reformulated barrier structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Plastic Drinking Pouch Market |
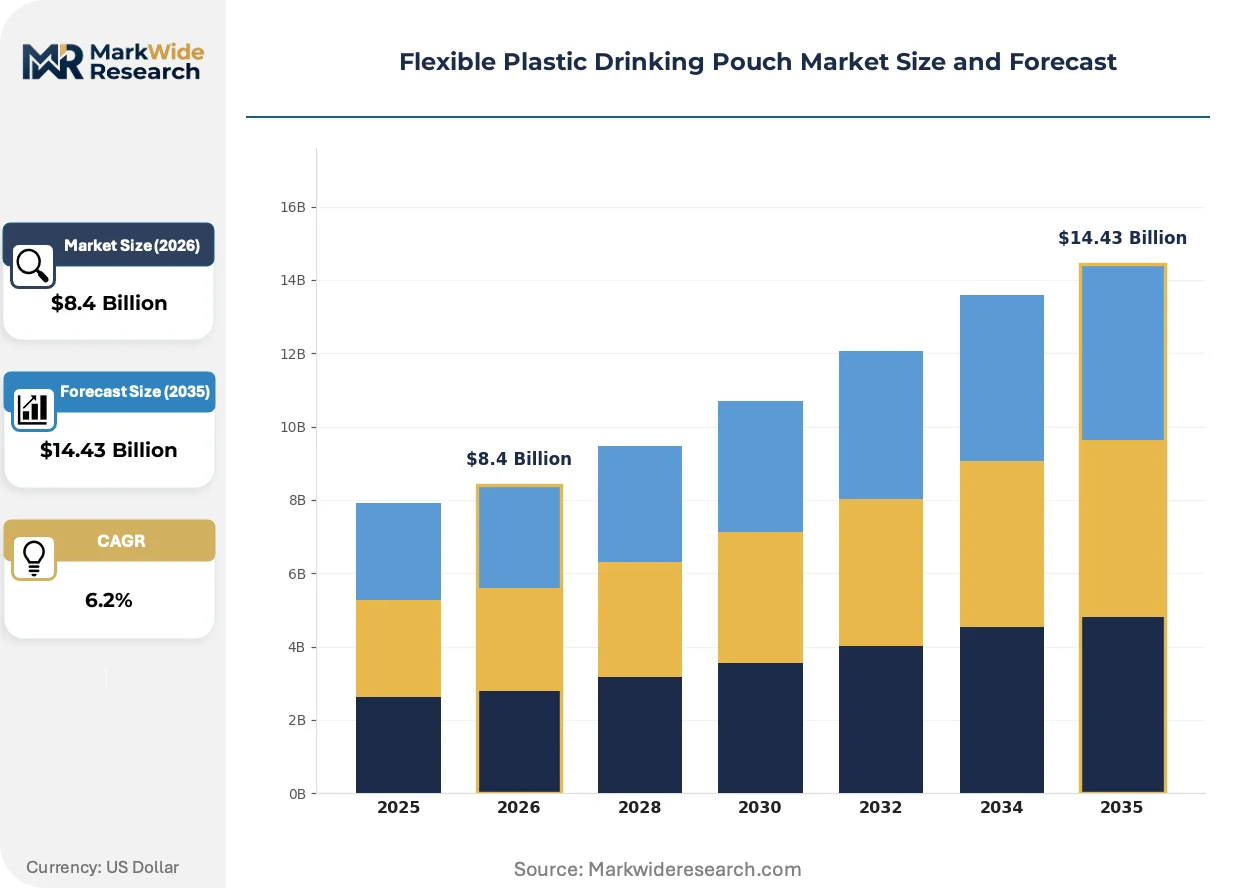
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Polyester, Nylon, EVOH, LDPE Pouch Design: Stand-up, Spouted, Flat Bottom, Gusseted, Four-side Seal, Pillow Beverage Type: Juice, Sports Drink, Flavored Water, Energy Drink, Tea, Coffee End User: Food & Beverage Manufacturers, Vending Operators, Event Organizers, Retail Chains, Hospitality Providers |
| Companies Covered | Amcor Plc, Berry Global Group, Inc, Mondi Group, Sealed Air Corporation, Sonoco Products Company, ProAmpac Holdings, Inc., Constantia Flexibles Group, Huhtamäki Oyj, Coveris Holdings S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Plastic Drinking Pouch Market Shifts & Advancements
Material science convergence with regulatory compliance is collapsing traditional trade-offs between barrier performance and recyclability, while digital printing and smart packaging integration create new value capture mechanisms beyond commodity container functions.
Mono-material polyethylene pouches with plasma-deposited silicon oxide barriers are modularizing the oxygen protection layer, enabling mechanical recycling compatibility without sacrificing six-month shelf stability. Sports drink brands in Germany and the Netherlands are specifying these structures for their premium lines. The technology is modularizing converter capabilities, allowing regional players to compete with multinational barrier film suppliers on specification compliance rather than capital intensity.
REACH Article 33 disclosure requirements for Substances of Very High Concern are forcing adhesive reformulation across European supply chains, eliminating solvent-based polyurethane chemistries in favor of waterborne alternatives with longer cure cycles. German converters report 15% throughput reductions during transition periods. Juice applications with acidic pH levels face the steepest requalification burdens, as EFSA migration limits for primary aromatic amines tighten testing protocols.
Direct-to-store delivery networks are compressing distributor tiers in North American convenience channels, with 7-Eleven and Circle K consolidating pouch procurement through centralized category managers rather than regional bottler arrangements. This concentration shifts negotiation leverage toward retail specification teams demanding customized spout geometries and private-label compatible print formats. The pattern is most visible in Texas and Florida metropolitan corridors where vending and cold-box placement density supports dedicated logistics fleets.
Flexible Plastic Drinking Pouch Market Segmentation
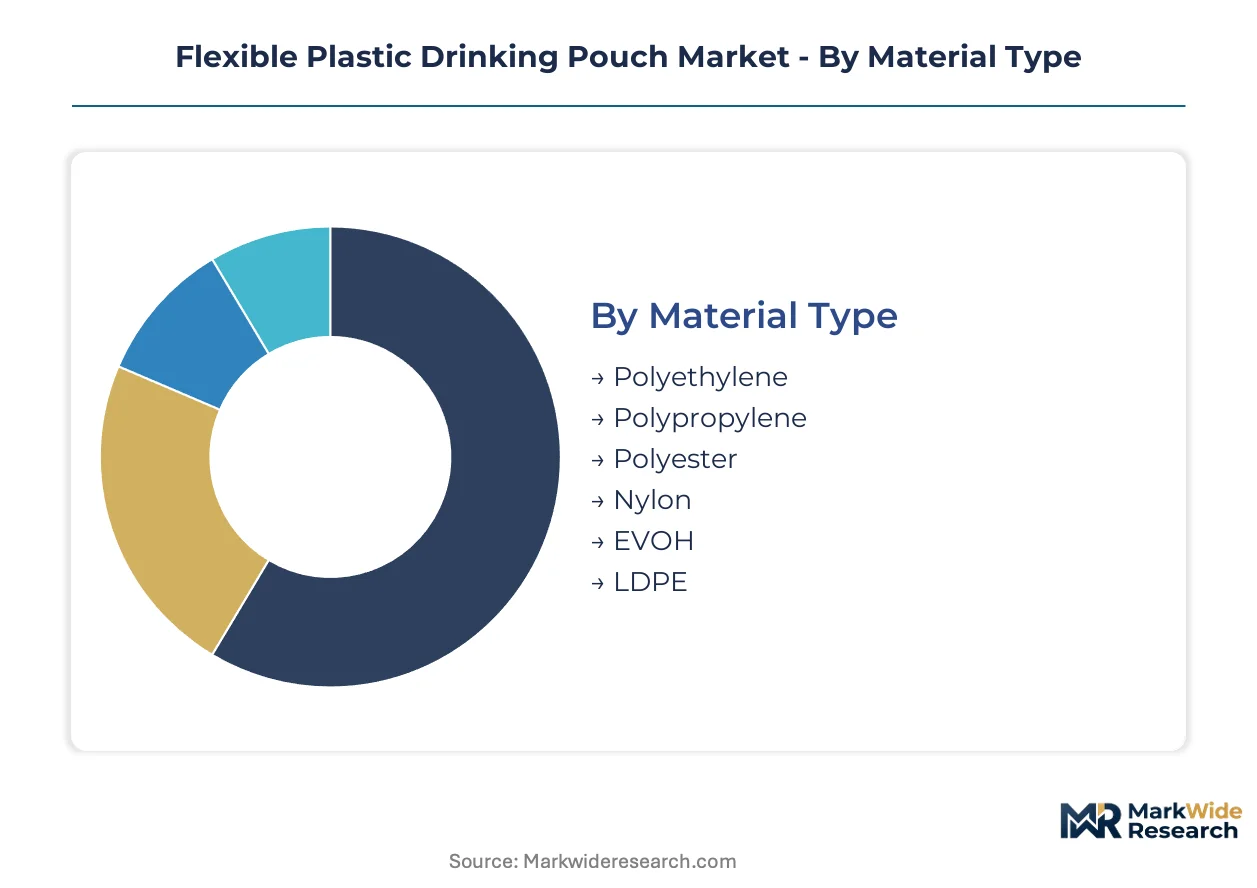
Material selection and pouch architecture determine oxygen barrier performance, recyclability compliance, and line speed economics. Design choices reflect channel-specific functional requirements from resealability to cube efficiency. Beverage chemistry and end-user procurement scale further stratify converter specialization and margin structures.
Material Type:
Converters differentiate by barrier sophistication versus circularity compliance, with European export orders demanding mono-material recyclability and tropical distribution requiring multi-layer oxygen protection.
- Polyethylene:Linear low-density and high-density grades dominate mono-material pouch structures compliant with Europe's Single-Use Plastics Directive. German beverage brands specify these for deposit-return scheme alignment despite 40% higher oxygen transmission versus EVOH laminates.
- EVOH:Ethylene vinyl alcohol coextrusions provide the oxygen barrier layer in multi-layer structures for six-month shelf-stable juice applications. Japanese and South Korean resin suppliers concentrate production, exposing converters to freight cost volatility on trans-Pacific supply.
- Polypropylene:Cast and oriented films offer higher temperature resistance for hot-fill tea and coffee applications. Clarity grades compete with glass in premium positioned still water segments.
- Polyester:PET laminates provide dimensional stability and print surface quality for high-definition graphics in private-label retail programs.
- Nylon:Polyamide layers puncture resistance for ice-filled distribution and rough-handling vending channels.
- LDPE:Low-density polyethylene sealant layers enable low-temperature sealing on legacy form-fill-seal equipment at mid-tier converters.
Volume sits with polyethylene; growth tilts toward EVOH as Southeast Asian juice brands expand shelf-stable distribution.
Pouch Design:
Structural geometry determines functional premium capture, with resealable configurations commanding specification pull from sports drink and energy drink brands while pillow formats defend value-tier positioning.
- Stand-up:Doyen-style bottom gussets create shelf presence and pallet stability for retail-ready beverage programs. 7-Eleven and Circle K centralized procurement teams specify customized geometries for cold-box placement density in Texas and Florida metropolitan corridors.
- Spouted:Integrated fitment structures with screw or snap closures enable resealability for gym and outdoor consumption occasions. Energy drink brands in Germany and the Netherlands are specifying these for premium line positioning.
- Flat Bottom:Box-pouch configurations maximize cube efficiency and shelf stability for club store multipack formats.
- Gusseted:Side-gusset structures expand volume capacity while maintaining narrow retail facings for convenience store cooler doors.
- Four-side Seal:Hermetic perimeter seals provide puncture resistance for ice-filled vending and event distribution channels.
- Pillow:Simple two-web seal configurations minimize material cost for value-tier juice and bulk institutional programs.
Specification density clusters around spouted designs; margin compression concentrates in pillow formats under extended producer responsibility fee pressure.
Beverage Type:
Acidity, carbonation, and thermal processing requirements stratify material specifications, with acidic juices demanding migration-compliant adhesives and sports drinks driving resealability innovation.
- Juice:Acidic pH levels below 4.5 impose the steepest EFSA requalification burdens under tightening primary aromatic amine migration limits. Waterborne adhesive transitions have reduced German converter throughput by 15% during qualification periods.
- Sports Drink:Isotonic formulations with electrolyte content require flavor barrier protection and resealable dispensing for on-the-go consumption. Plasma-deposited silicon oxide barriers on polyethylene substrates are modularizing converter capabilities for this segment.
- Flavored Water:Low-acidity clear formulations tolerate mono-material structures, enabling reduced plastic content claims through fiber-based hybrid laminates.
- Energy Drink:Caffeine and taurine stability requirements favor multi-layer barrier protection with metallic laminate options.
- Tea:Hot-fill and retort processing compatibility drives polypropylene and nylon specification for temperature resistance.
- Coffee:Oxygen scavenger integration and aroma barrier layers protect volatile compound retention in ready-to-drink formats.
Revenue concentration favors sports drinks; steepest expansion trajectory belongs to flavored water as health-positioned alternatives displace carbonated soft drinks.
End User:
Procurement scale and specification authority determine converter relationship structures, with retail chain consolidation shifting leverage toward centralized category managers and vending fragmentation preserving regional supplier relationships.
- Food & Beverage Manufacturers:Multinational bottlers with captive filling operations specify global material standards and audit converter facilities across multiple continents. Amcor's manufacturing footprint alignment serves these accounts.
- Retail Chains:Reliance Retail and D-Mart in India are building cold-chain beverage sections in Tier-2 cities where pouch formats reduce breakage versus glass in monsoon conditions.
- Vending Operators:Regional network fragmentation preserves relationships with specialized converters capable of small-batch customization and rapid spout geometry modification.
- Event Organizers:Seasonal demand spikes and ice-filled distribution requirements prioritize puncture-resistant four-side seal configurations.
- Hospitality Providers:Hotel and airline procurement teams specify portion-controlled formats with premium print quality for amenity programs.
Contract value aggregates with food and beverage manufacturers; specification velocity accelerates through retail chain centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Southeast Asia's tropical retail corridors and Europe's regulatory transition zones, while North American convenience channels consolidate procurement around spouted formats for on-the-go consumption.
United States
Convenience store chains in Texas and Florida metropolitan corridors drive spouted pouch specification for cold-box placement density. The EPA regulates food-contact substances under 21 CFR 177, constraining adhesive migration limits for polyethylene layers. Midwestern converting hubs in Illinois and Ohio face technician scarcity for blown film extrusion with EVOH tolerance maintenance.
Germany
Beverage brands specify mono-material polyethylene structures for deposit-return scheme alignment under the VerpackG framework. ECHA's REACH Article 33 disclosure requirements force waterborne adhesive transitions that reduce converter throughput during qualification periods. The Rhine-Ruhr industrial cluster hosts specialized extrusion operators serving premium sports drink lines with plasma-deposited silicon oxide barriers.
India
Reliance Retail and D-Mart expand cold-chain beverage sections in Tier-2 cities where pouch formats reduce breakage versus glass during monsoon conditions. FSSAI food-contact regulations govern migration limits for multilayer laminated structures in ambient juice distribution. Maharashtra and Gujarat industrial corridors attract converter investments for tropical climate packaging specifications.
Japan
Domestic resin suppliers concentrate EVOH film production for oxygen barrier layers in shelf-stable juice applications. METI guidelines on plastic resource circulation accelerate mono-material development for export-bound beverage packaging. The Kanto industrial basin around Tokyo maintains specialized coextrusion capabilities for high-definition print surface quality.
Netherlands
Sports drink brands specify resealable spouted configurations for gym and outdoor retail channels where functional premiums command specification pull. The country's extended producer responsibility framework under EU Single-Use Plastics Directive implementation rewards recyclable mono-material designs with lower eco-modulated fees. Rotterdam-Antwerp port logistics clusters support trans-European distribution of converted pouch stock.
Flexible Plastic Drinking Pouch Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fiber-based hybrid structures and plasma-deposited barrier technologies. The vendor base stratifies across three capability tiers: multinational converters with global manufacturing footprints, regional specialists in mono-material reengineering, and mid-tier operators dependent on legacy multi-layer equipment. Three archetypes dominate: barrier technology licensors, circularity-compliant material innovators, and private-label print format customizers. Competitive moves concentrate on M&A for extrusion asset consolidation and strategic partnerships for adhesive chemistry requalification.
Within the multinational converter tier, Amcor Plc and Berry Global Group, Inc. exemplify scale-driven positioning across beverage account categories. Mondi Group occupies a distinct position representing fiber-based hybrid innovation, reducing plastic content through paper-plastic laminate structures. These three anchors illustrate divergent strategic responses to Europe's Single-Use Plastics Directive: global manufacturing footprint alignment, regional extrusion specialization, and material substitution pathways respectively.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Group, Inc |
| Mondi Group |
| Sealed Air Corporation |
| Sonoco Products Company |
| ProAmpac Holdings, Inc. |
| Constantia Flexibles Group |
| Huhtamäki Oyj |
| Coveris Holdings S.A. |
| Others |
Supply & Pricing Matrix
Blown film technician scarcity across Midwestern US converting hubs in Illinois and Ohio widens labor-cost differentials between premium spouted configurations and commodity pillow formats. European extended producer responsibility fees under Germany's VerpackG and France's Citeo schemes compress margins on value-tier segments while mono-material compliance investments elevate pricing floors across export-bound production.
Pricing Analysis
Volume aggregates with polyethylene pillow pouches for institutional juice programs; margin capture concentrates in spouted stand-up configurations for sports drink brands. Three-tier pricing structure across premium, standard, and economy levels reflects oxygen barrier sophistication, with plasma-deposited silicon oxide barriers commanding functional premiums over basic mono-material structures. Cost compression in pillow formats intensifies because Citeo per-unit recycling contributions erode converter profitability. Value-tier juice applications exhibit highest price sensitivity; premium sports drink lines with resealable fitments demonstrate lowest sensitivity due to brand-driven specification authority.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean EVOH resin suppliers who concentrate ethylene vinyl alcohol film production for oxygen barrier layers. Raw material procurement draws from polyethylene grades in Saudi Arabia and the US Gulf Coast, adhesive chemistries from German specialty chemical producers, and silicon oxide deposition equipment from Dutch vacuum technology vendors. Tariff exposure on trans-Pacific EVOH shipments creates margin volatility for multi-layer juice applications. Distribution runs through centralized retail category managers at 7-Eleven and Circle K in Texas and Florida metropolitan corridors, bypassing traditional regional bottler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as Europe's Single-Use Plastics Directive forces capital-intensive mono-material reengineering that mid-tier converters cannot finance amid interest rate uncertainty.
For Market Incumbents: To counter plasma-deposited barrier technology modularization by regional competitors, Amcor and Berry Global should accelerate backward integration into specialized extrusion assets across the Rhine-Ruhr and Midwestern US industrial clusters. Captive adhesive chemistry requalification capabilities will compress FDA 21 CFR 177 notification timelines below the current 18-month backlog.
For New Entrants and Emerging Players: Fiber-based hybrid laminate technology offers white-space entry against Mondi Group's paper-plastic structures in premium flavored water segments. Target India's Tier-2 city cold-chain expansion where Reliance Retail and D-Mart procurement teams prioritize breakage reduction over barrier sophistication. Lead with FSSAI migration-compliant mono-material qualifications to bypass entrenched multinational converter relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with regional mono-material specialists given Italy's CONAI framework eco-modulation incentives accelerating specification pull from export-oriented bottlers. Five-to-ten year viability favors converters with plasma deposition equipment and waterborne adhesive throughput recovery. Watch for FDA notification queue clearance rates as inflection indicator for reformulated barrier structure launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Capacity Expansion | Enables VerpackG deposit-return scheme alignment for German beverage brands. |
| Plasma Deposition Technology Licensing | Modularizes oxygen barrier capabilities for regional converter competition. |
| Waterborne Adhesive Chemistry Partnership | Accelerates REACH Article 33 compliant reformulation for European export orders. |
| Direct-to-Store Distribution Integration | Bypasses fragmented vending networks for 7-Eleven and Circle K procurement consolidation. |
| Fiber-Based Hybrid Structure Development | Exploits EFSA approval pathways for reduced plastic content claims in premium waters. |
Research Methodology
Independent corroboration across blown film extrusion operators, retail category managers, and adhesive chemistry formulators underwrites the qualitative findings. Primary interviews with plant managers at Midwestern converting hubs, procurement leads at Southeast Asian juice bottlers, and regulatory affairs specialists navigating REACH compliance were validated against secondary sources including FDA 21 CFR 177 notification databases, ECHA SVHC disclosure registries, and customs records tracking EVOH resin shipments from Japan and South Korea. Bottom-up volume estimates from converter capacity utilization rates were triangulated with top-down demand projections from beverage brand packaging specifications.
Historical reference periods spanning pre-regulatory and post-directive implementation phases anchored the forecast window across the analysis window. The analytical framework modeled material type segmentation by barrier sophistication, pouch design by functional geometry, beverage chemistry by acidity and thermal processing requirements, and end-user procurement scale. CAGRs were derived from trend extrapolation of mono-material adoption curves and spouted configuration specification rates. Industry-specific inputs included EVOH supply concentration indices and extended producer responsibility fee schedules across European member states.
Several conditions sit outside the modeled scope, including unforeseen EFSA migration limit tightening beyond primary aromatic amines and abrupt FDA notification process acceleration. Forecasts reflect documented assumptions regarding adhesive cure cycle throughput recovery and plasma deposition equipment deployment timelines. Deviation in EVOH resin freight cost volatility or REACH SVHC list expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Standcap Pouch Market
Pouch
Spain Pouch Packaging Market
Pouch
Flexible Plastic Pouches Market
Pouch
Pouches Market
Pouch
Compostable Pouches Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Flat Bottom Pouch Market
Pouch
Russia Pouch Packaging Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
Retort Pouch Market
Pouch
Twist Wrap Packaging Market
Pouch
UAE Pouch Packaging Market
Pouch
Egypt Pouch Packaging Market
Pouch
Global Pouches Packaging Market
Pouch
Box Pouch Market
Pouch
Telemetry Pouch Market