
 Aluminum Barrier Laminate (ABL) Tubes Market | 2026-2036
Aluminum Barrier Laminate (ABL) Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Barrier Laminate (ABL) Tubes Market Analysis
CE marking under the EU Medical Device Regulation is reorganizing competitive access for pharmaceutical tube suppliers in Europe. Albéa Group leverages integrated laminate extrusion and printing capabilities across its French and Polish plants. Essel Propack Ltd. anchors volume production through dedicated facilities serving oral care and pharmaceutical clients in India and Europe. Hoffmann Neopac AG differentiates via precision-engineered small-diameter tubes for cosmetic and pharma applications.
Aluminum Barrier Laminate tubes consist of a multi-layer coextruded structure combining polyethylene, aluminum foil, and adhesive tie layers, typically achieving oxygen transmission rates below 0.01 cc per square meter per day. This barrier performance protects oxygen-sensitive contents including retinol formulations, hydrocortisone creams, and food-grade pastes from degradation during shelf life. Flip-Top tubes command premium positioning in cosmetics due to consumer convenience and dosing precision, while squeeze tubes dominate pharmaceutical volumes where cost-efficient barrier protection remains essential. Applicator tubes represent the fastest-growing design category as brands integrate sponge-tip and roller-ball dispensing for targeted skincare and wound-care products.
EMA guidelines on primary packaging materials for medicinal products, REACH restrictions on adhesive constituents, and FDA Type III drug master file requirements collectively elevate compliance costs and technical barriers for new entrants. ECHA scrutiny of fluorinated compounds in barrier coatings is accelerating migration toward polyethylene-based adhesive systems. Stakeholders must monitor evolving recyclability certifications under extended producer responsibility schemes to secure long-term material access and brand positioning.
Market Dynamics
The EU Green Deal and Packaging and Packaging Waste Regulation are forcing laminate producers to reengineer multi-layer structures for recyclability while maintaining sub-0.01 cc oxygen barrier performance, creating a technical squeeze between compliance and functional requirements.
Growth Catalysts
- Pharmaceutical packaging mandates:CE marking under the EU Medical Device Regulation is elevating barrier standards for ointment tubes, pulling demand toward certified ABL suppliers.
- Cosmetic serum expansion:Premium skincare brands are migrating retinol and vitamin C formulations into tube formats, requiring aluminum foil oxygen protection.
- Applicator innovation:Sponge-tip and roller-ball dispensing systems are opening wound-care and targeted skincare categories previously served by jars or pumps.
Market Restraints
- Aluminum foil cost volatility:Primary aluminum price swings directly compress converter margins on long-term supply contracts.
- German supply concentration:Pharmaceutical contract manufacturers cluster in southern Germany, creating geographic dependency for high-barrier tube sourcing.
- Multi-layer recyclability limits:Current mechanical separation cannot cleanly recover polyethylene and aluminum fractions, blocking circular economy certifications.
Strategic Opportunities
- Food-grade paste migration:Tomato paste and condiment brands are testing ABL alternatives to metal cans for portion-controlled formats.
- Indian pharmaceutical growth:CDSCO manufacturing quality upgrades are accelerating demand for barrier tubes among domestic generic producers.
- Polyethylene adhesive transition:ECHA fluorinated compound scrutiny is creating first-mover advantage for converters with PE-based tie-layer expertise.
Industry Challenges
- REACH compliance timelines:Adhesive constituent registration and restriction updates delay new product launches by 12-18 months.
- Extrusion-printing integration:In-line decoration capability requires capital-intensive equipment coordination that smaller converters cannot fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Barrier Laminate (ABL) Tubes Market |
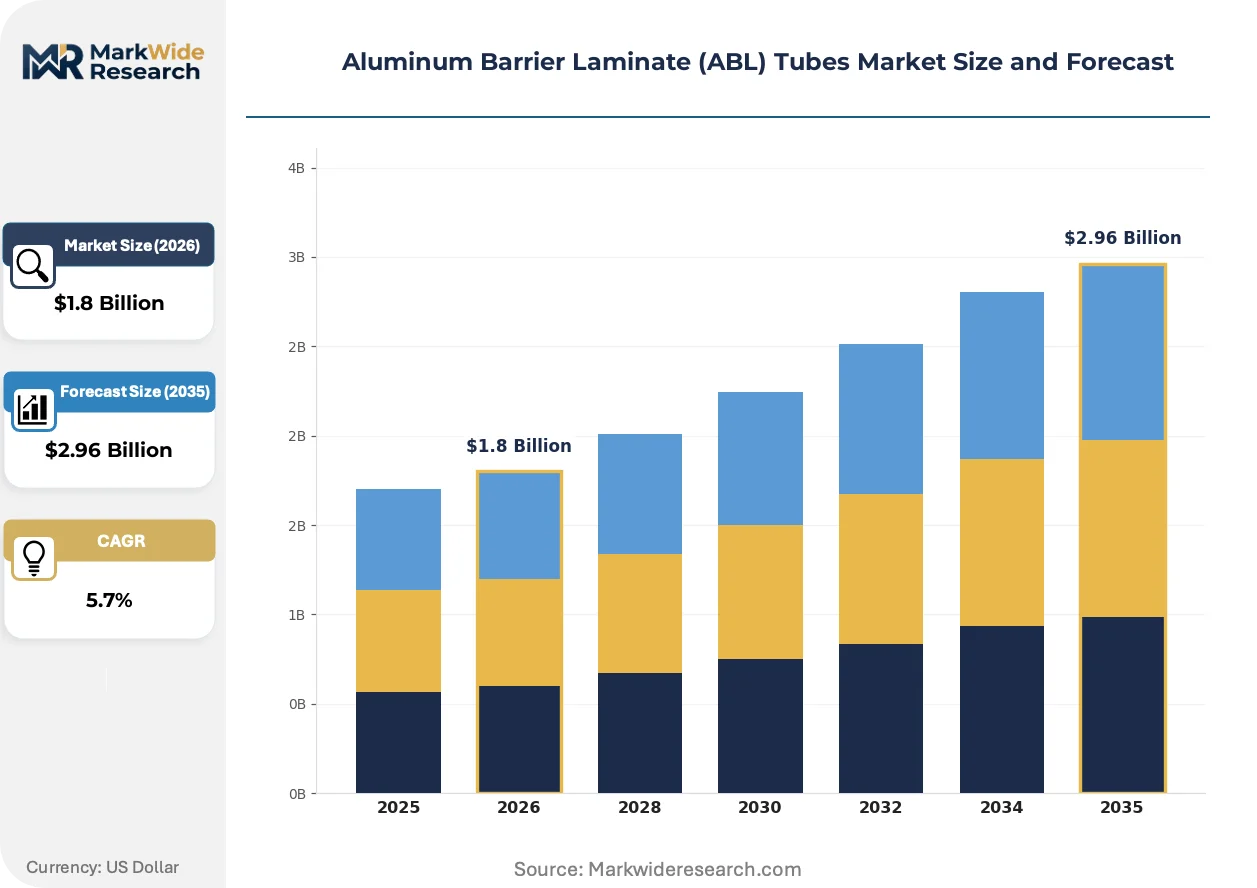
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tubes, Flip-Top Tubes, Squeeze Tubes, Applicator Tubes End User: Cosmetics, Pharmaceuticals, Food & Beverage, Personal Care Design Feature: Easy-Pour, Resealable, Tamper-Evident, Custom Shapes Distribution Channel: Online Retail, Supermarkets, Distributors, Specialty Stores |
| Companies Covered | Huhtamäki Oyj, Albéa Group, Essel Propack Ltd., Intrapac International Corporation, Montebello Packaging, Amcor plc, Hoffmann Neopac AG, Linhardt GmbH & Co. KG, The Berry Global Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Barrier Laminate (ABL) Tubes Market Emerging Trajectories
Material science advances and regulatory stringency are converging to reshape how barrier performance, recyclability, and consumer convenience coexist in tube packaging.
Polyethylene-based adhesive tie layers are supplanting fluorinated barrier coatings as converters respond to ECHA scrutiny of per- and polyfluoroalkyl substances. Mid-tier cosmetic brands in France and Poland are accelerating qualification of these reformulated laminates. The shift is compressing competitive advantage for converters with legacy fluorochemical expertise while rewarding polymer chemistry specialists.
EMA guidelines on primary packaging materials for medicinal products are tightening documentation requirements for extractables and leachables. Pharmaceutical tube suppliers must now submit enhanced stability data before securing formulation approvals. Oral care and dermal therapy segments in Germany and Switzerland are experiencing the longest certification delays.
Direct-to-clinic procurement models are consolidating purchasing power among pharmaceutical contract manufacturers. Distributors serving independent pharmacies are losing volume to centralized buying groups with technical specification teams. This concentration is most visible in the Benelux region where three buying cooperatives control majority ointment tube procurement.
Aluminum Barrier Laminate (ABL) Tubes Market Segmentation
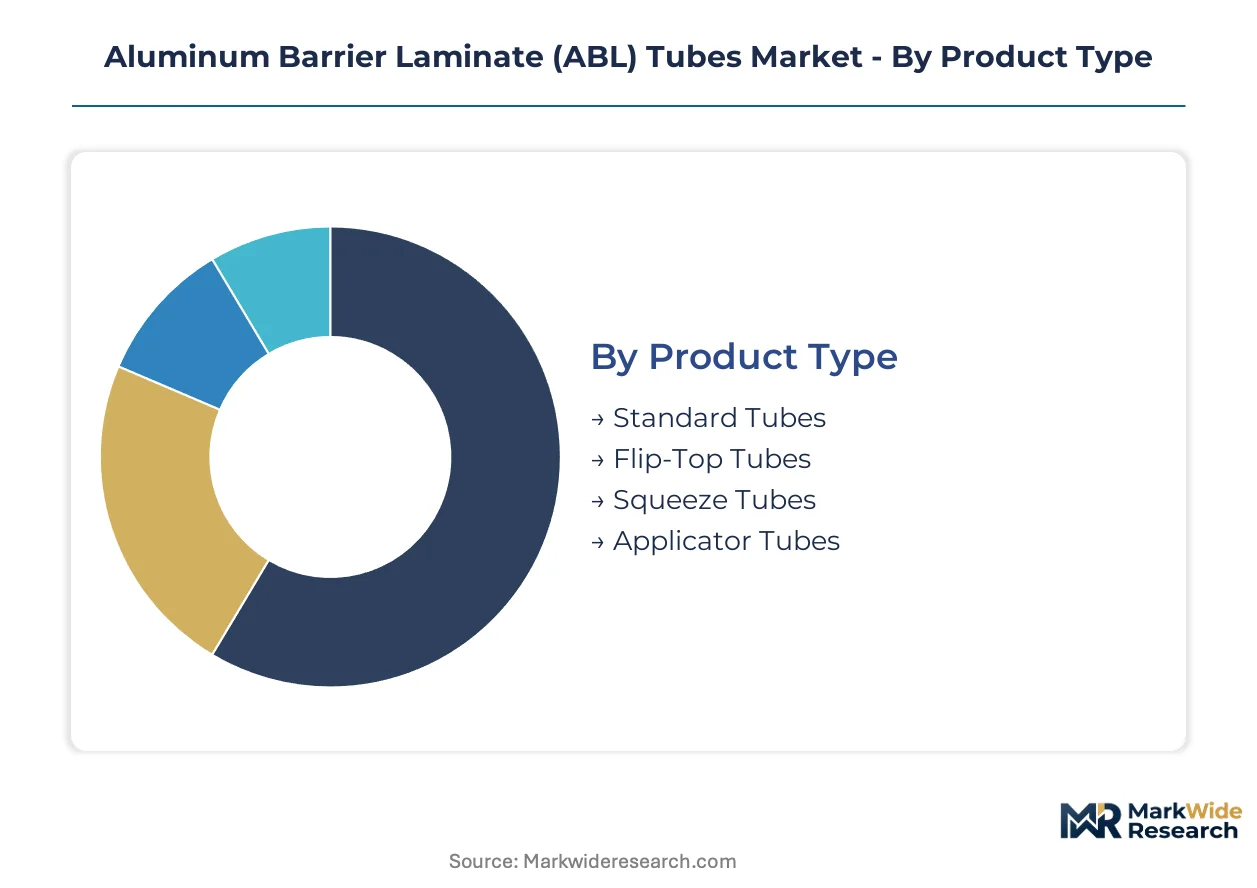
ABL tube segmentation reveals divergent margin profiles across product architectures and end-use specifications. Pharmaceutical and cosmetic applications impose distinct barrier, compliance, and decoration requirements that reshape converter economics.
Product Type:
Flip-Top and Applicator configurations command premium positioning through dosing precision and dispensing innovation.
- Flip-Top Tubes:Integrated hinge-lid closure systems enable single-handed dispensing with precise dose control. Premium skincare brands in France and Poland specify these for retinol and vitamin C serums where oxidation protection meets consumer convenience.
- Applicator Tubes:Sponge-tip, roller-ball, and brush-tip dispensing heads transform tube formats into targeted application tools. Wound-care clinics and dermal therapy centers in Germany and Switzerland are adopting these for hydrocortisone and antibiotic ointments.
- Standard Tubes:Conventional cylindrical formats with screw-cap or crimp seals serve cost-sensitive oral care and generic pharmaceutical volumes.
- Squeeze Tubes:Flexible body construction with flip-top or stand-up cap options dominates high-volume pharmaceutical contracts where barrier performance must balance unit economics.
Flip-Top tubes hold installed capacity. Applicator tubes are rotating up the share rankings.
End User:
Pharmaceutical certification burdens and cosmetic decoration demands create divergent capability requirements across customer bases.
- Pharmaceuticals:CE marking under EU Medical Device Regulation and EMA extractables documentation mandate validated manufacturing environments. Southern German contract manufacturers source exclusively from converters with dedicated cleanroom extrusion lines.
- Cosmetics:Premium skincare migration toward tube formats demands inline printing, hot-stamping, and metallization capabilities. Brands specify sub-0.01 cc oxygen transmission rates for retinol stability.
- Food & Beverage:Tomato paste and condiment brands are piloting ABL alternatives to metal cans for portion-controlled formats, requiring food-grade adhesive compliance under EFSA standards.
- Personal Care:Oral care volumes concentrate among established converters with high-speed lamination and dedicated toothpaste tube lines serving Indian and European markets.
Pharmaceuticals anchor capacity utilization. Cosmetics is climbing the fastest as serum brands migrate from jars.
Design Feature:
Tamper-evidence and resealability specifications align with end-use liability exposure and consumer safety priorities.
- Tamper-Evident:Break-ring seals, shrink bands, and induction-sealed membranes protect pharmaceutical integrity. EMA guidelines on primary packaging materials mandate demonstration of seal integrity across shelf life.
- Resealable:Screw-cap, snap-fit, and click-lock closures extend product usability for multi-dose food pastes and cosmetic creams. Food-grade applications under EU Packaging and Packaging Waste Regulation face recyclability scrutiny for multi-component closures.
- Easy-Pour:Controlled-flow neck geometries and flexible body construction assist dispensing of viscous dermal preparations and wound-care gels.
- Custom Shapes:Oval, triangular, and ergonomic profiles differentiate cosmetic shelf presence but require specialized mandrel and forming tooling.
Tamper-Evident dominates pharmaceutical procurement. Resealable is gaining share in food-grade pilot programs.
Distribution Channel:
Channel concentration shapes order patterns, specification complexity, and converter margin structures.
- Distributors:Pharmaceutical buying cooperatives in Benelux and southern Germany consolidate technical specification power, squeezing independent pharmacy supply chains.
- Online Retail:Direct-to-consumer cosmetic brands demand shorter runs with rapid artwork changeover, favoring converters with digital printing and agile lamination scheduling.
- Supermarkets:Mass-market oral care and personal care volumes concentrate among retailers with private-label programs and centralized packaging procurement.
- Specialty Stores:Prestige cosmetic boutiques and pharmacy chains require premium decoration, gift-box compatibility, and regional language customization.
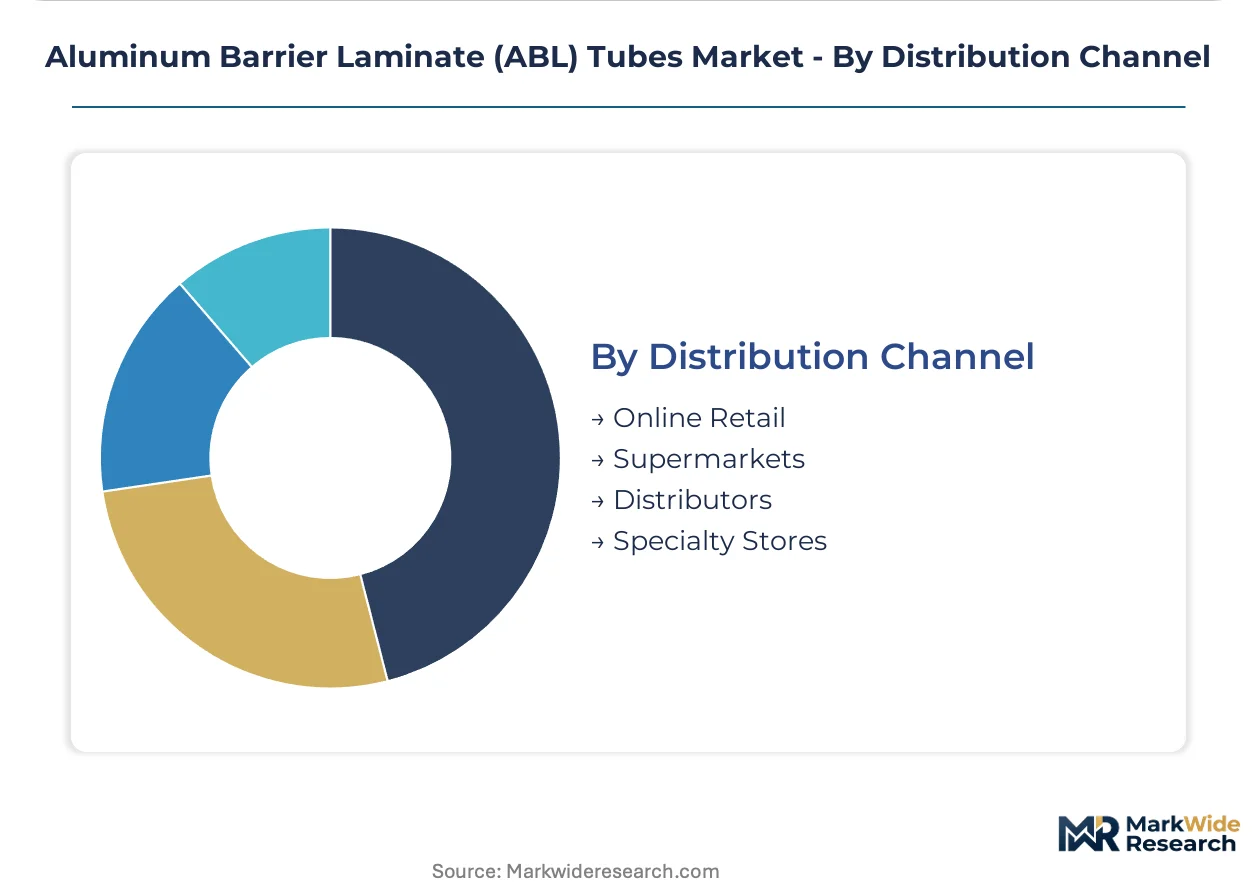
Distributors hold legacy volume concentration. Online Retail is expanding most quickly as DTC skincare brands proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal recyclability mandates and FDA Type III drug master file requirements are redirecting laminate investment toward jurisdictions with established pharmaceutical certification infrastructure and adhesive reformulation capabilities.
Germany
Pharmaceutical contract manufacturers in Bavaria and Baden-Württemberg source high-barrier tubes for ointment delivery under EU Medical Device Regulation CE marking requirements. EMA extractables documentation mandates delay new supplier qualification by 12-18 months. The Stuttgart-Munich corridor hosts dedicated cleanroom extrusion lines serving southern German pharma clusters.
India
CDSCO manufacturing quality upgrades accelerate demand for barrier tubes among domestic generic producers in Maharashtra and Gujarat. BIS standards for pharmaceutical packaging materials are tightening alignment with ICH Q3D guidelines on elemental impurities. Mumbai-Pune pharmaceutical zones concentrate oral care and dermal therapy tube procurement.
United States
Tomato paste and condiment brands in California and Illinois pilot ABL alternatives to metal cans for portion-controlled formats under FDA food-contact notification requirements. EPA scrutiny of fluorinated barrier coatings pushes converters toward polyethylene-based adhesive systems. Chicago-area food packaging R&D centers validate laminate shelf-life performance for acidic contents.
France
Premium skincare brands in Île-de-France specify flip-top tubes for retinol and vitamin C serums requiring sub-0.01 cc oxygen transmission rates. ANSM pharmaceutical packaging guidelines enforce stability data submission for primary materials. The Paris cosmetics cluster drives qualification of fluorine-free laminates ahead of ECHA restriction timelines.
Switzerland
Dermal therapy centers in Basel and Zurich adopt applicator tubes with sponge-tip dispensing for hydrocortisone and antibiotic ointments. Swissmedic technical documentation requirements exceed EMA baselines for wound-care packaging. The Basel pharmaceutical hub sources precision-engineered small-diameter tubes from neighboring German and French converters.
Aluminum Barrier Laminate (ABL) Tubes Market Vendor Landscape
Player mix skews toward integrated laminate converters with dedicated pharmaceutical certification capabilities and mid-tier specialists with decoration agility for cosmetic short-runs. Consolidation pressure concentrates among European and Indian facilities serving oral care volumes. Three archetypes dominate: vertically integrated multinational converters with captive extrusion-printing lines; regional specialists with pharma-cleanroom assets; and agile decorators serving direct-to-consumer cosmetic brands. Capacity expansion and adhesive reformulation partnerships constitute the primary competitive vectors.
Within the integrated multinational tier, Albéa Group and Essel Propack Ltd. exemplify archetypes with extrusion-printing coordination across multiple jurisdictions. Hoffmann Neopac AG occupies a position among precision-engineering specialists targeting small-diameter pharmaceutical and cosmetic applications. These three anchors illustrate how certification depth, geographic footprint, and product architecture specialization segment competitive access.
| Leading Market Players |
|---|
| Huhtamäki Oyj |
| Albéa Group |
| Essel Propack Ltd. |
| Intrapac International Corporation |
| Montebello Packaging |
| Amcor plc |
| Hoffmann Neopac AG |
| Linhardt GmbH & Co. KG |
| The Berry Global Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with London Metal Exchange aluminum indexation lock in converter margins while exposing buyers to price volatility pass-through. German pharmaceutical contract manufacturers negotiate these structures to secure dedicated cleanroom extrusion capacity across the Stuttgart-Munich corridor.
Pricing Analysis
Cost-plus contracts with LME aluminum indexation dominate converter-buyer relationships. Price differentiation separates CE-marked pharmaceutical grades from cosmetic decoration tiers and food-grade pilot volumes. Pricing pressure stems from primary aluminum spot volatility compressing margins on legacy contracts. Generic pharmaceutical buyers exhibit highest price sensitivity while premium skincare brands absorb decoration premiums for flip-top and applicator configurations.
Supply Chain Analysis
Cleanroom-grade aluminum foil supply from Austria and Germany underwrites barrier performance for pharmaceutical certification. Raw material dependencies center on primary aluminum ingot, polyethylene resin, and adhesive tie-layer formulations. Single-source vulnerability concentrates in Austrian foil rolling capacity serving EMA-compliant tube producers. Distribution runs through pharmaceutical buying cooperatives in Benelux and southern Germany consolidating technical specification power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorinated compound phase-out under ECHA scrutiny is disrupting incumbent converter chemistry and opening first-mover windows for polyethylene adhesive specialists.
For Market Incumbents: Consolidate fluorine-free laminate qualification ahead of REACH restriction timelines. Secure backward integration into polyethylene tie-layer resin production to offset adhesive reformulation cost inflation. Defend southern German cleanroom capacity against emerging Indian pharmaceutical tube producers. For New Entrants and Emerging Players: Lead with applicator tube engineering for wound-care clinics in Switzerland and Germany where precision dispensing commands premium positioning. Target food-grade condiment pilots in the United States where FDA food-contact notification requirements create qualification barriers for established pharmaceutical-focused converters. For Investors and Strategic Acquirers: Regional specialists with pharma-cleanroom assets and pending CE marking approvals present asymmetric upside. Monitor EMA extractables documentation backlogs as inflection signal for supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Laminate Qualification | ECHA scrutiny of PFAS compounds accelerates polyethylene adhesive transition ahead of restriction deadlines. |
| Cleanroom Extrusion Capacity Expansion | EU Medical Device Regulation CE marking mandates pull investment toward Bavaria and Baden-Württemberg clusters. |
| Applicator Tube Engineering Partnerships | Sponge-tip and roller-ball dispensing systems open wound-care categories previously served by jars. |
| Direct-to-Consumer Digital Printing Investment | Online retail channels demand agile artwork changeover for DTC skincare brand proliferation. |
| Food-Grade Adhesive Compliance Certification | EFSA standards for tomato paste and condiment pilots create new volume category beyond pharma and cosmetics. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with laminate extrusion plant managers, pharmaceutical packaging procurement leads, and cosmetic brand supply chain directors; and secondary validation through EMA packaging guidelines, REACH substance restriction updates, FDA Type III drug master file databases, and customs trade records for aluminum foil and polyethylene resin. Bottom-up volume triangulation across product architectures and end-use segments was cross-checked against top-down converter capacity estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including tube design feature, barrier certification tier, decoration complexity, and regional regulatory cluster. CAGRs were derived from installed capacity utilization rates, new product launch pipelines, and substitution elasticity estimates for alternative packaging formats. Forecast inputs incorporated ECHA fluorinated compound restriction timelines and CDSCO manufacturing quality upgrade trajectories.
The analysis sits within stated boundaries; outcomes outside EMA documentation backlog resolution or aluminum price volatility bands would require recalibration. Practitioners should keep alternative scenarios live as EU Packaging and Packaging Waste Regulation recyclability mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market