
 Protective Films Market | 2026-2036
Protective Films Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Films Market Analysis
Asian polyethylene film producers are shifting capacity toward multi-layered coextrusion lines to serve electronics and automotive OEMs. Avery Dennison leverages its pressure-sensitive adhesive portfolio to dominate North American automotive paint protection channels. Tesa SE anchors European supply through precision-coated films for electronics assembly, while 3M competes across medical and industrial segments with silicone-acrylic hybrid platforms.
Protective films are thin polymer membranes, typically 25–150 micrometers thick, applied to surfaces to prevent abrasion, contamination, or UV degradation during manufacturing, transit, or end-use. PET films command the highest value per square meter due to optical clarity and dimensional stability in electronics applications, while PE films sustain volume leadership in construction and general industrial masking where cost sensitivity prevails. Pressure-sensitive technology captures the broadest application footprint, though multi-layered structures are gaining share in premium automotive and medical segments where removability without residue defines performance.
REACH restrictions on volatile organic compounds and the EU F-Gas Regulation on fluorinated polymers are reshaping adhesive formulation requirements across European supply chains. The FDA enforces biocompatibility standards for medical-grade films in the United States, while China's GB standards and SAMR oversight govern domestic electronics and automotive component specifications. Stakeholders must monitor evolving substance restrictions and regional certification divergence when configuring product platforms for cross-border supply.
Market Dynamics
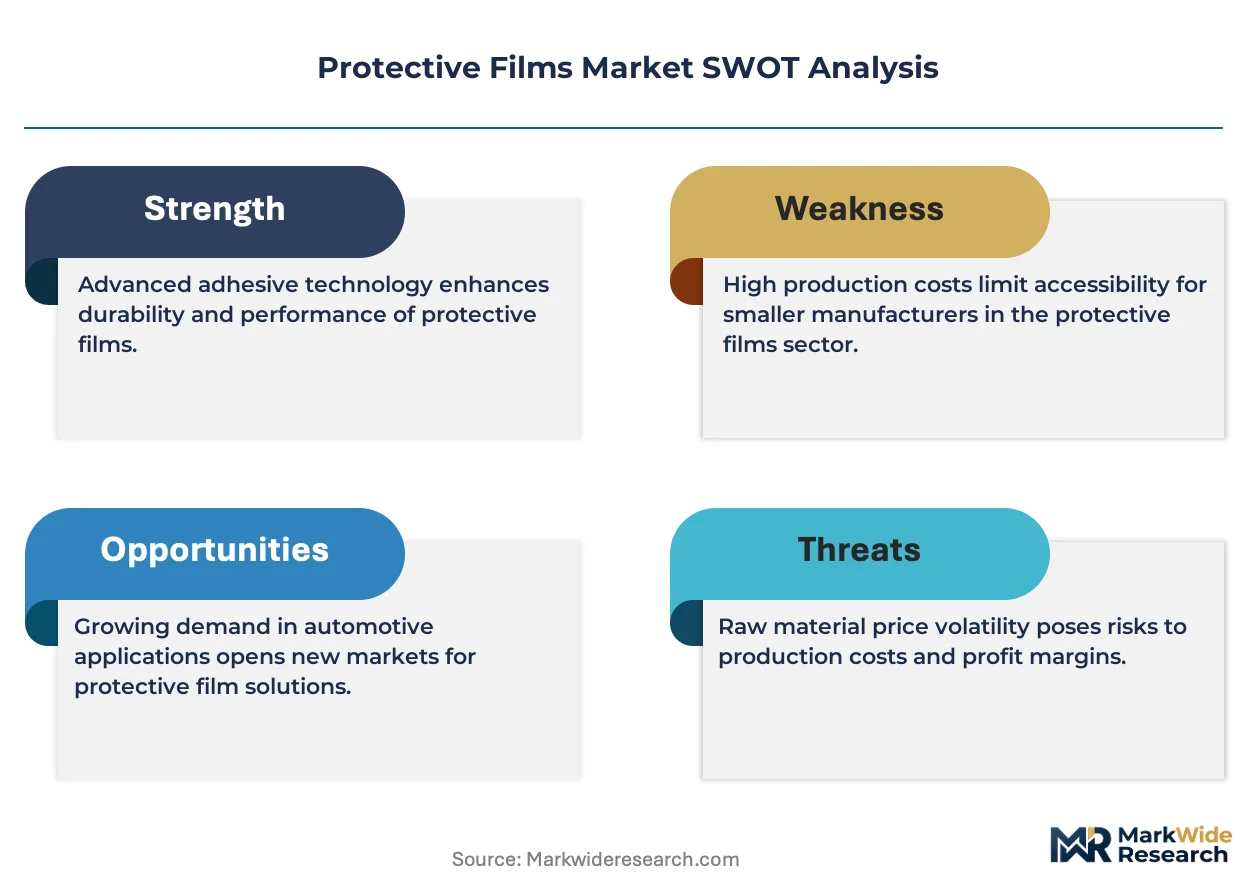
Adhesive formulation chemistry sits at the center of competitive differentiation as electronics OEMs demand residue-free removability alongside optical-grade clarity. Water-based and UV-cured systems are displacing solvent platforms under regulatory pressure, forcing reformulation investments across the supply base.
Growth Catalysts
- EU REACH substance restrictions:Solvent-based adhesive phase-outs are accelerating adoption of compliant water-based and UV-cured alternatives among European film coaters.
- Flat-panel display fabrication:South Korean and Taiwanese electronics manufacturers are scaling procurement of adhesive-coated PET films for OLED and LCD panel production.
- Multi-layer coextrusion:Asian polyethylene producers are redirecting capacity toward sophisticated multi-layer lines serving automotive paint protection and medical device packaging.
Market Restraints
- Petrochemical input volatility:Crude oil and purified terephthalic acid price swings compress margins for commodity PE and PET film extruders.
- East Asian supply concentration:Overreliance on Chinese and South Korean adhesive and substrate producers exposes buyers to logistics disruption and trade policy friction.
- Optical-grade PET technical barriers:Sub-micron thickness uniformity and haze control requirements limit qualified suppliers for premium electronics applications.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication are creating fresh demand for contamination-control films.
- Medical-grade film certification:FDA biocompatibility standards and EU MDR compliance are opening premium pricing tiers for silicone-acrylic hybrid platforms in wound care and device packaging.
- UV-cured adhesive convergence:Crosslinking chemistry advances are enabling faster line speeds and lower energy consumption versus thermal drying systems.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in pressure-sensitive adhesive polymer science remains concentrated among a narrow cohort of specialists in Germany, Japan, and the United States.
- Cleanroom certification timelines:ISO 14644 compliance for medical and semiconductor-grade film production extends facility qualification periods by 12-18 months.
- Legacy solvent line stranded assets:European coaters face write-down pressure as REACH deadlines approach for volatile organic compound elimination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Films Market |
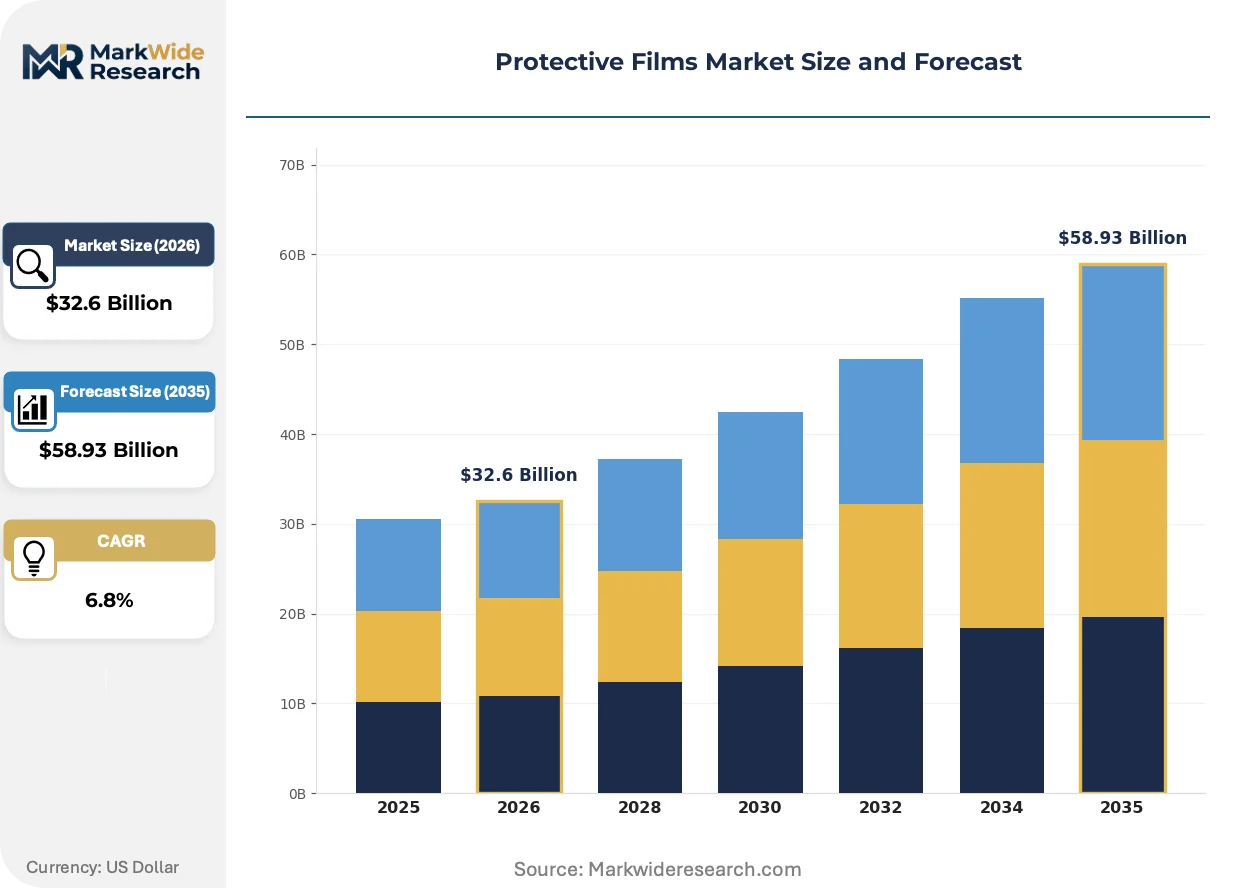
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $58.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PE Films, PVC Films, PET Films, Polycarbonate Films Application: Automotive, Construction, Electronics, Medical End User: Manufacturers, Retailers, Consumers, Distributors Technology: Pressure-sensitive, Adhesive-coated, Heat-shrinkable, Multi-layered |
| Companies Covered | Avery Dennison, Tesa SE, 3M, LLumar, Suntek, Eastman Chemical Company, Nitto Denko, Tredegar Surface Protection, XPEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Films Market Emerging Trajectories
Coating and curing technologies are converging with substrate engineering to enable thinner, higher-performance films. Three interconnected developments are redefining product architecture and procurement criteria across electronics, automotive, and medical verticals.
Silicone-acrylic hybrid adhesives combine the temperature resistance of silicone with the optical clarity of acrylic systems. Automotive paint protection film installers and medical device manufacturers are specifying these platforms for residue-free removability after extended dwell times. This chemistry is expanding into semiconductor wafer dicing tapes where thermal stability during high-temperature processing prevents adhesive transfer.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and other solvent carriers are compelling European coaters to validate water-based dispersion systems. The industrial consequence is extended drying line retrofits and reformulation partnerships with specialty chemical suppliers. Electronics-grade PET film producers in Germany and the Netherlands are most affected, with qualification cycles for new adhesive systems stretching customer approval timelines.
Consolidated procurement by South Korean display panel fabricators is compressing supplier qualification windows and demanding dedicated production lines. Direct OEM relationships are displacing distributor-mediated supply for optical-grade films, with Samsung Display and LG Display negotiating multi-year volume commitments. This concentration is most visible in Gyeonggi Province cluster procurement, where three buyers account for the majority of regional adhesive-coated PET consumption.
Protective Films Market Segmentation
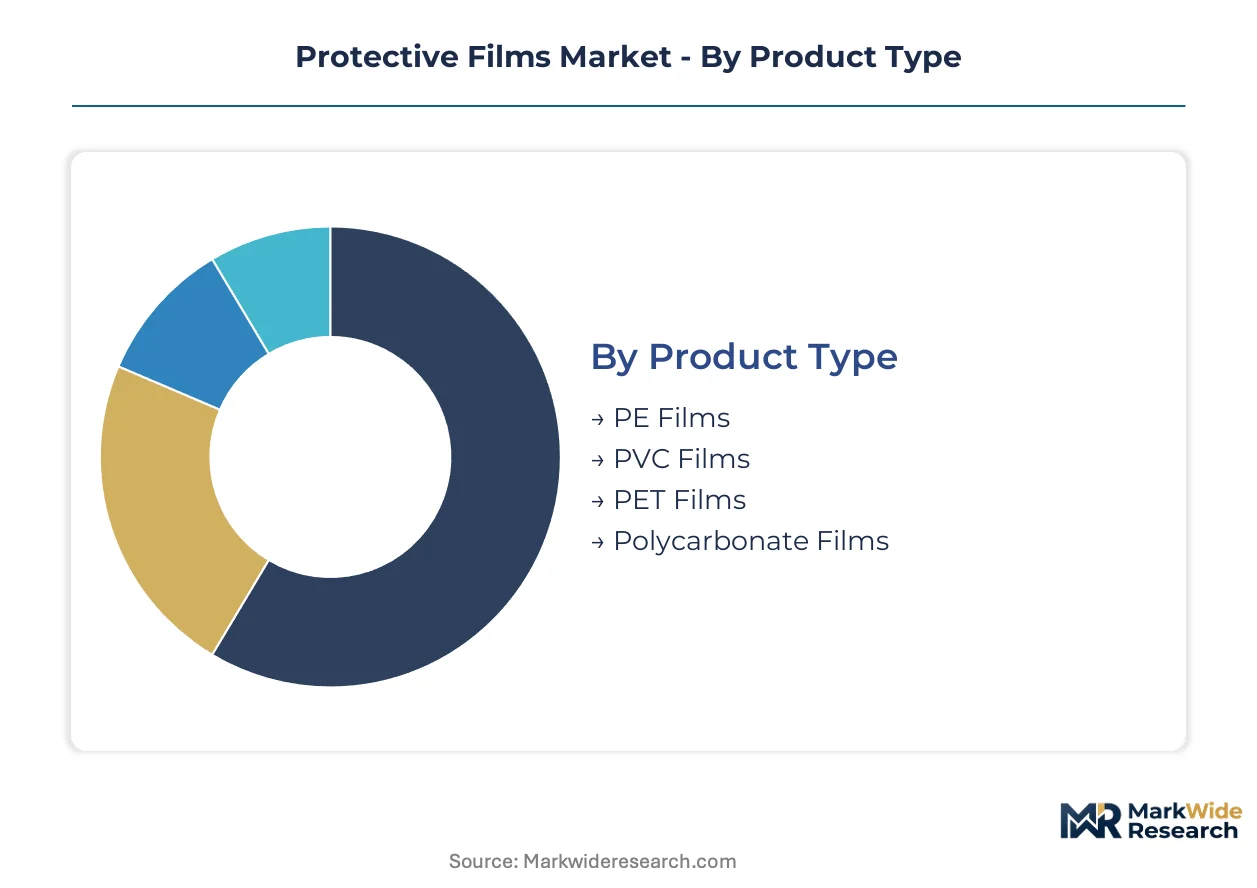
Protective films exhibit sharp performance stratification across substrate chemistry and adhesive technology. Electronics OEMs specify optical-grade PET with sub-micron tolerances, while construction contractors prioritize cost-optimized PE for temporary surface masking.
Product Type:
Standardization dominates commodity polyethylene, whereas polycarbonate and optical PET demand intensive coater qualification and dedicated production lanes.
- PET Films:Biaxially oriented polyester delivers dimensional stability and haze values below 0.5% for display panel lamination. Samsung Display and LG Display in Gyeonggi Province specify adhesive-coated variants for OLED fabrication, with residue-free removability mandatory after high-temperature processing.
- PE Films:Blown and cast polyethylene sustain volume leadership through multi-layer coextrusion advances. Asian producers redirect commodity capacity toward automotive paint protection and construction masking where 25-75 micrometer thickness ranges balance cost against puncture resistance.
- Polycarbonate Films:High-impact substrates serve medical device face shields and automotive interior trim with superior thermoformability versus PET.
- PVC Films:Plasticized vinyl retains niche presence in static-cling applications and temporary signage where low-tack adhesion suffices.
Most installed capacity flows through PE Films. Expansion is steepest in PET Films.
Application:
Margin structures diverge dramatically between contamination-control electronics and price-sensitive construction verticals.
- Electronics:Flat-panel display fabrication consumes adhesive-coated PET with ISO 14644 cleanroom certification. Taiwanese and South Korean panel makers consolidate procurement through direct OEM contracts, compressing supplier qualification windows to 6-9 months.
- Automotive:Paint protection film installers specify 150-200 micrometer multi-layer TPU/PE constructions with self-healing topcoats. OEMs mandate 5-7 year UV resistance warranties for dealer-applied programs.
- Construction:Temporary surface masking for glass, flooring, and countertops drives high-volume PE consumption. Contractors prioritize low-tack removability over extended outdoor durability.
- Medical:FDA biocompatibility and EU MDR compliance open premium tiers for silicone-acrylic hybrid platforms in wound care, device packaging, and surgical drape applications.
Electronics commands the highest value per square meter. Construction sustains the largest absolute tonnage.
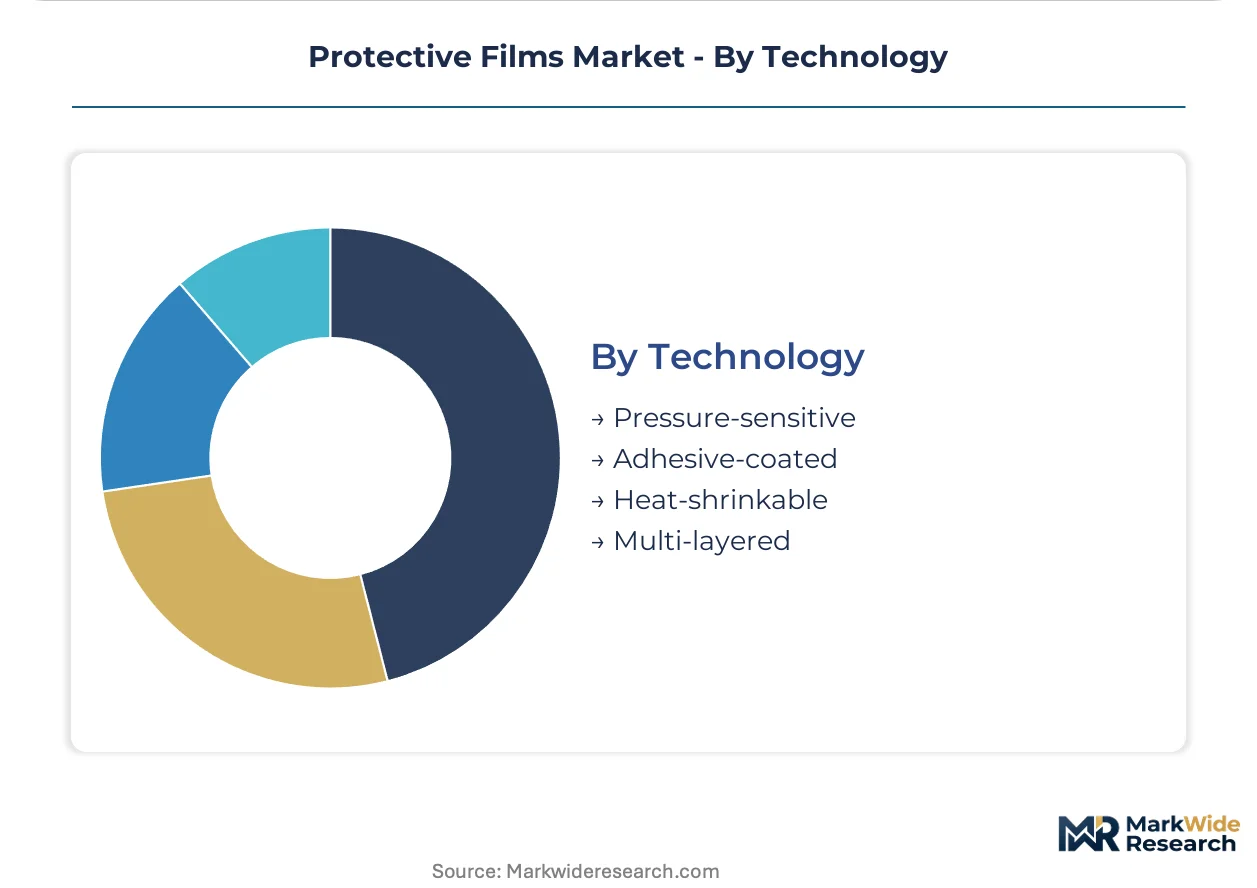
Technology:
Regulatory pressure on volatile organic compounds is fragmenting the installed base between legacy solvent coaters and compliant UV-cured lines.
- Pressure-sensitive:Acrylic and rubber-based adhesives dominate general industrial masking with immediate tack and clean removability. Avery Dennison and Tesa SE anchor supply through precision-coated film portfolios spanning 20-150 micrometer thickness ranges.
- Adhesive-coated:Thermal and UV-cured systems serve electronics and automotive applications where dwell times exceed 12 months. REACH Annex XVII restrictions on N-methyl-2-pyrrolidone are forcing European coaters into extended reformulation cycles.
- Multi-layered:Coextruded structures combine distinct functional layers—UV-stabilized skin, impact-modified core, release-coated backing—within single-pass production.
- Heat-shrinkable:Crosslinked PE formulations conform to complex geometries during transit and storage, serving industrial equipment and palletized goods protection.
Pressure-sensitive technology retains the broadest application footprint. UV-cured adhesive-coated platforms are climbing the fastest.
End User:
Procurement authority concentrates among large manufacturers with direct coater relationships, while distributor networks fragment demand across small contractors and consumers.
- Manufacturers:Electronics and automotive OEMs negotiate multi-year volume commitments with dedicated production line guarantees. Samsung Display, LG Display, and tier-one automotive suppliers specify lot-level traceability and statistical process control documentation.
- Distributors:Regional industrial supply houses aggregate demand from mid-sized fabricators and maintenance contractors. Inventory breadth and same-day availability determine competitive positioning.
- Retailers:Home improvement chains and automotive aftermarket stores stock consumer-grade paint protection and surface masking SKUs with private-label penetration rising.
- Consumers:DIY installation of smartphone screen protectors and vehicle paint protection films sustains e-commerce velocity with instructional content driving purchase decisions.
Manufacturers capture the highest revenue per transaction. Distributors mediate the greatest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between REACH-compliant Europe and less stringent Asian jurisdictions is redirecting investment toward multi-layer coextrusion capacity in China and South Korea, where solvent-based adhesive formulations face fewer phase-out deadlines.
China
Domestic electronics OEMs and automotive manufacturers drive PET film consumption for display lamination and paint protection applications. GB standards issued by SAMR govern optical-grade film specifications for consumer electronics. The Yangtze River Delta cluster around Suzhou and Wuxi hosts the densest concentration of adhesive coaters serving Samsung and BOE panel fabrication facilities.
South Korea
Samsung Display and LG Display consolidate procurement of adhesive-coated PET films for OLED production lines. The MFDS regulates medical-grade film biocompatibility for wound care exports. Gyeonggi Province's display fabrication corridor consumes the majority of regional optical-grade film output through direct OEM contracts with dedicated production guarantees.
Germany
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and volatile organic compounds force coaters into water-based and UV-cured adhesive reformulations. ECHA enforcement timelines compress supplier qualification windows. The Rhine-Ruhr industrial region maintains precision coating operations for automotive and medical device applications despite compliance cost premiums.
United States
FDA biocompatibility standards for medical-grade films and EPA VOC regulations shape adhesive formulation requirements. Automotive OEMs specify paint protection films with 5-7 year UV resistance warranties for dealer-applied programs. Michigan and Ohio manufacturing corridors sustain demand for industrial masking and surface protection applications.
India
PLI scheme incentives for semiconductor and display fabrication are creating fresh demand for contamination-control films in emerging electronics clusters. BIS certification requirements govern domestic product specifications. Tamil Nadu and Karnataka are developing dedicated supplier ecosystems to serve Foxconn and Tata Electronics assembly operations.
Protective Films Market Vendor Landscape
East Asian producers anchor the volume tier through multi-layer coextrusion scale; European specialists hold premium positioning via precision coating capabilities and regulatory compliance expertise. The vendor base stratifies across three tiers: integrated chemical conglomerates with captive resin supply, independent coaters with formulation IP, and regional converters serving construction and general industrial masking. Strategic moves center on M&A to secure adhesive formulation technology and capacity expansion in India and Vietnam to bypass tariff exposure.
Among diversified materials conglomerates, 3M exemplifies the hybrid-platform archetype spanning medical, industrial, and electronics segments. Tesa SE and Avery Dennison occupy positions within the precision-coated film tier, with the former anchoring European electronics assembly supply and the latter dominating North American automotive channels. These three entities represent distinct competitive postures: technology licensing leverage, regional market entrenchment, and vertical integration into pressure-sensitive adhesive chemistry.
| Leading Market Players |
|---|
| Avery Dennison |
| Tesa SE |
| 3M |
| LLumar |
| Suntek |
| Eastman Chemical Company |
| Nitto Denko |
| Tredegar Surface Protection |
| XPEL |
| Others |
Supply Flow & Price Mechanics
Purified terephthalic acid and crude oil derivatives cascade through PET and PE resin tiers, translating petrochemical volatility into margin compression for commodity film extruders while premium optical-grade substrates command pricing power through qualified supplier scarcity.
Pricing Analysis
Distributor margins absorb the steepest compression as electronics OEMs negotiate direct-to-manufacturer contracts that bypass traditional channel markups. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14644-certified cleanroom films from general industrial masking grades, with certification tier and volume scale as primary differentiation drivers. Pricing pressure stems from Asian overcapacity in commodity PE extrusion, while construction contractors exhibit highest price sensitivity versus medical device manufacturers accepting premium tiers for FDA biocompatibility assurance.
Supply Chain Analysis
Cleanroom certification and adhesive qualification timelines gate supplier entry, extending facility validation to 12-18 months for medical and semiconductor-grade production. Manufacturing concentrates in China, South Korea, and Germany, with substrate supply drawing from purified terephthalic acid, ethylene feedstocks, and specialty adhesive polymers. Single-source vulnerability concentrates in East Asian electronics clusters where Samsung Display and LG Display consolidate procurement, while distribution runs through direct OEM contracts for premium tiers and regional industrial distributors for construction masking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protective films function as a regulatory compounder where REACH Annex XVII solvent restrictions and EU F-Gas Regulation compliance deadlines are accelerating formulation transitions and reshaping competitive viability across European supply chains.
For Market Incumbents: Extend formulation IP advantages by consolidating water-based and UV-cured adhesive capabilities ahead of REACH phase-out deadlines, while adding dedicated cleanroom capacity in India to serve PLI-scheme electronics manufacturing and offset tariff exposure from Chinese supply concentration.
For New Entrants and Emerging Players: Begin with contamination-control film supply to India's emerging semiconductor clusters in Tamil Nadu and Karnataka, where Foxconn and Tata Electronics assembly operations lack qualified domestic suppliers and procurement runs through first-mover qualification windows.
For Investors and Strategic Acquirers: Consolidation pressure builds where solvent-based coaters face stranded asset write-downs as ECHA enforcement timelines compress. Target precision-coating specialists with existing FDA or EU MDR certification platforms, watching adhesive formulation patent filings as the inflection signal for technology-driven acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Reformulation | REACH Annex XVII compliance secures European electronics supply continuity for German and Dutch coaters. |
| Cleanroom Capacity Expansion | ISO 14644 certification opens medical-grade and semiconductor wafer dicing tape revenue tiers. |
| Backward Integration into Resin | Captive PET supply insulates margin pressure from purified terephthalic acid price volatility. |
| Direct OEM Contracting | Samsung Display and LG Display procurement consolidation rewards dedicated production line guarantees. |
| Geographic Diversification to India | PLI scheme incentives for display fabrication create qualified supplier scarcity in emerging clusters. |
Methodological Framework
Coverage spans East Asia, Europe, and North America, with primary inputs from each region combining interviews with adhesive formulation chemists, electronics procurement managers at display panel fabricators, automotive paint protection film distributors, and medical device packaging engineers, validated against customs trade data, SEC filings of listed materials companies, ECHA substance restriction notifications, and FDA 510(k) device filings, with bottom-up substrate demand modeling triangulated against top-down adhesive consumption estimates.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon, with segmentation modeling across substrate chemistry, adhesive technology, application vertical, and end-user procurement channel. CAGRs derive from adhesive consumption intensity per square meter of display panel output, automotive paint protection film installation rates, and construction activity indices, with cross-validation against resin producer capacity announcements and coater equipment order backlogs.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to REACH Annex XVII substance lists, abrupt trade policy shifts affecting Chinese substrate exports, and breakthrough substrate technologies displacing PET in flexible electronics. Forecasts reflect documented assumptions regarding cleanroom certification timelines and adhesive qualification cycles. A model refresh is warranted upon material change in ECHA enforcement priorities or South Korean display panel capital expenditure plans.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Heat Transfer Films Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
Hydrocolloid Coating Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Heat Insulating Films Market