
 Functional Films Market | 2026-2036
Functional Films Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Films Market Analysis
The EU Green Deal is shifting procurement criteria across European packaging and electronics supply chains toward recyclable and lower-carbon film substrates. BASF leverages its polymer science portfolio to develop bio-based barrier formulations for food packaging clients. Eastman Chemical Company sustains leadership in copolyester films through backward integration into specialty resin production. Toray Industries anchors its competitive position in optical films for liquid crystal and OLED displays through captive manufacturing in Japan and Korea.
Functional films are engineered polymer or inorganic layers, typically 1–500 micrometers thick, deposited through extrusion, solution casting, or vapor-phase processes to deliver controlled permeability, optical transmittance, or electrical conductivity for industrial applications. Barrier films command the largest revenue pool due to their essential role in extending shelf life for sensitive pharmaceuticals and perishable foods, though conductive films are expanding fastest as electric vehicle battery pack manufacturers specify flame-retardant separator films with enhanced ionic transport. Optical films retain mature profitability in display stack applications where Mitsubishi Polyester Film and 3M compete on anti-reflective and brightness-enhancement specifications for premium television and monitor panels.
REACH in Europe, FDA food-contact regulations in the United States, and China's GB standards for packaging materials collectively shape product formulation roadmaps, testing protocols, and market access requirements for functional film exporters. Japan's METI enforces energy-efficiency labeling that drives adoption of high-performance insulation films in building retrofits. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate recycling infrastructure investments to align capacity planning with compliance timelines and circular-economy procurement shifts.
Market Dynamics
Foldable display manufacturing is compressing development cycles for ultra-thin barrier films, forcing substrate suppliers to co-locate with panel fabs in Korea and China while meeting simultaneously tightening EU packaging waste directives.
Growth Catalysts
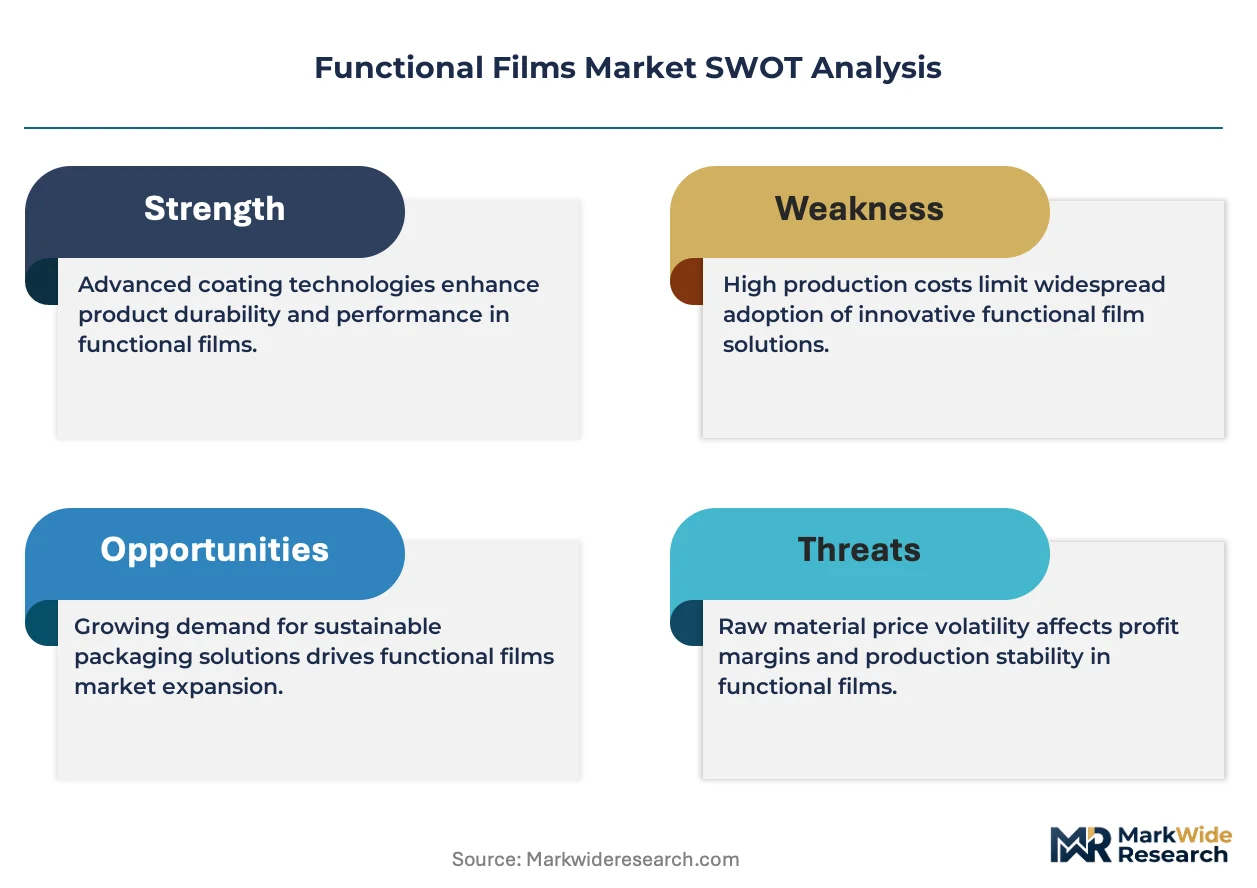
- Photovoltaic module expansion:Bifacial solar cell architectures require transparent backsheet films with enhanced UV resistance, pulling capacity toward Southeast Asia module assembly clusters.
- EU Green Deal packaging mandates:Extended producer responsibility frameworks in Germany and France are mandating recyclable multi-layer structures, accelerating bio-based substrate qualification timelines.
- Battery separator film specifications:Electric vehicle manufacturers specify ceramic-coated polyolefin separators with shutdown functionality, creating dedicated extrusion lines at polymer film specialists.
Market Restraints
- Specialty resin supply concentration:Cyclo-olefin polymer and fluorinated monomer production concentrates in Japan and limited US Gulf Coast facilities, exposing film coaters to force majeure vulnerability.
- REACH authorization bottlenecks:ECHA's sunset date enforcement for phthalate plasticizers forces reformulation of legacy flexible PVC films without drop-in replacements at equivalent cost.
- Technical thickness floors:Mechanical integrity requirements for high-barrier food packaging prevent migration below 12-micrometer substrates, blocking cost reduction pathways achieved in other polymer segments.
Strategic Opportunities
- India electronics manufacturing:PLI scheme subsidies for display and semiconductor fabrication create first-mover advantage for barrier film suppliers establishing local metallization capabilities.
- Building-integrated photovoltaics:Semi-transparent organic photovoltaic modules require wavelength-selective optical films, merging construction and energy sector procurement channels.
- Digital printing substrate compatibility:Water-based ink adhesion on untreated polyester opens short-run flexible packaging markets previously locked into gravure-printed rotogravure films.
Industry Challenges
- Cleanroom capital intensity:Class 1000 manufacturing environments for optical-grade films require 18-24 month construction timelines, constraining capacity response to demand spikes.
- Multi-jurisdiction food-contact certification:Simultaneous FDA, EFSA, and GB standard compliance demands parallel toxicology studies, extending product launch cycles by 8-14 months.
- Legacy coating line retrofit complexity:Solvent-based adhesive laminators face MEE air emission enforcement in China, requiring thermal oxidizer investments that erode margin on commodity film grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Films Market |
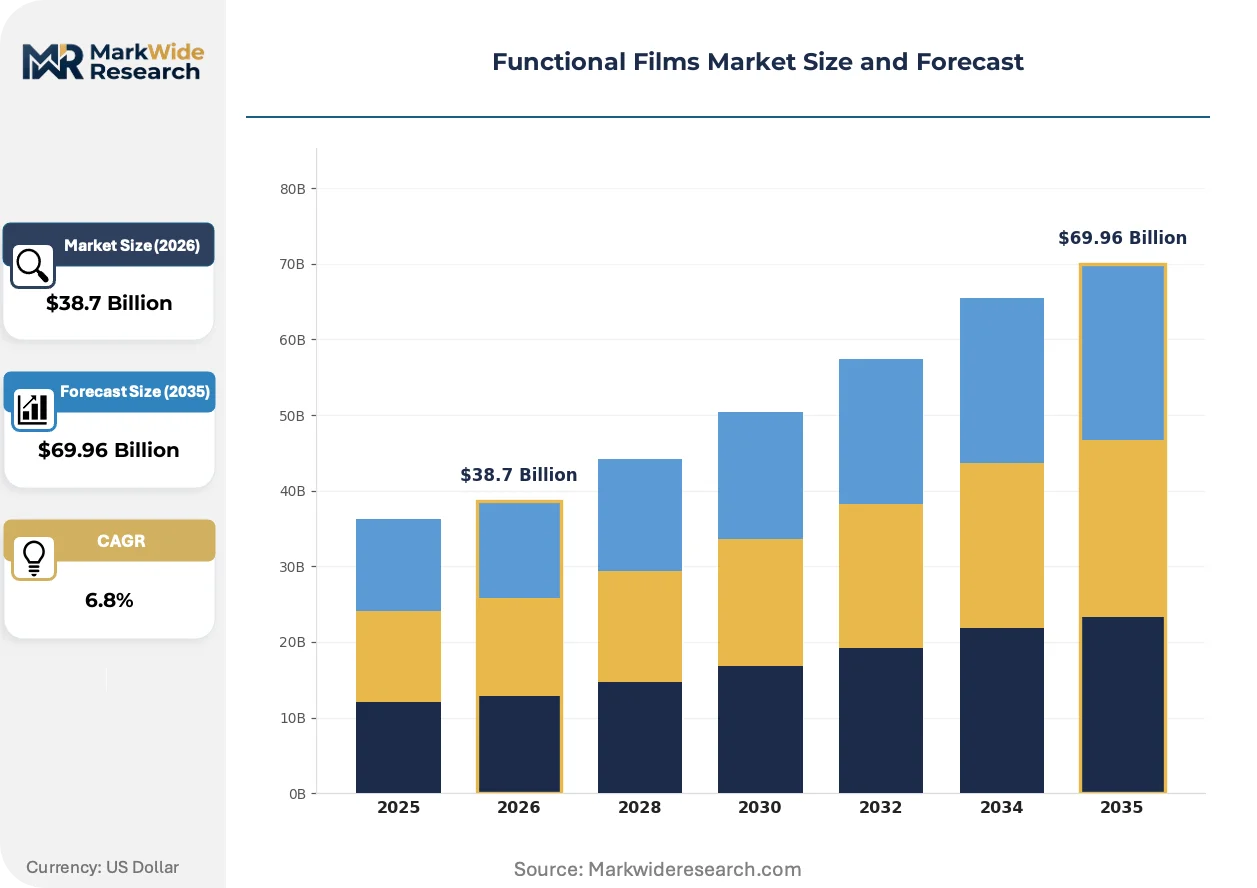
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barrier Films, Optical Films, Conductive Films, Adhesive Films End User: Packaging, Electronics, Automotive, Construction Form: Rolled, Sheet, Laminated, Coated Application: Display, Insulation, Protection, Solar Energy |
| Companies Covered | BASF, Eastman Chemical Company, 3M, Honeywell, Avery Dennison, Toray Industries, Mitsubishi Polyester Film, Saint-Gobain, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Films Market Emerging Trajectories
Atomic layer deposition is crossing from semiconductor equipment into roll-to-roll film manufacturing, enabling nanometer-scale barrier layers that were previously achievable only through thicker, less flexible multi-layer coextrusion.
Atomic layer deposition is rewriting the economics of single-layer barrier performance. Automotive battery pack manufacturers in Korea specify ALD-coated separators for next-generation solid-state cell architectures. The technology compresses the traditional multi-layer film stack, threatening incumbent coextrusion equipment suppliers.
REACH restriction proposals on per- and polyfluoroalkyl substances are forcing fluoropolymer film producers to accelerate short-chain chemistry transitions. Medical device manufacturers dependent on PTFE membranes face 2025 authorization deadlines. German chemical regulators are driving substitution toward silicone and hydrocarbon-based alternatives in implantable applications.
Buyer consolidation among European supermarket chains is collapsing supplier counts for private-label flexible packaging. Aldi and Lidl's combined purchasing power now dictates substrate specifications across Central European converting markets. Film producers respond with dedicated product platforms certified for direct food contact without secondary lamination steps.
Functional Films Market Segmentation
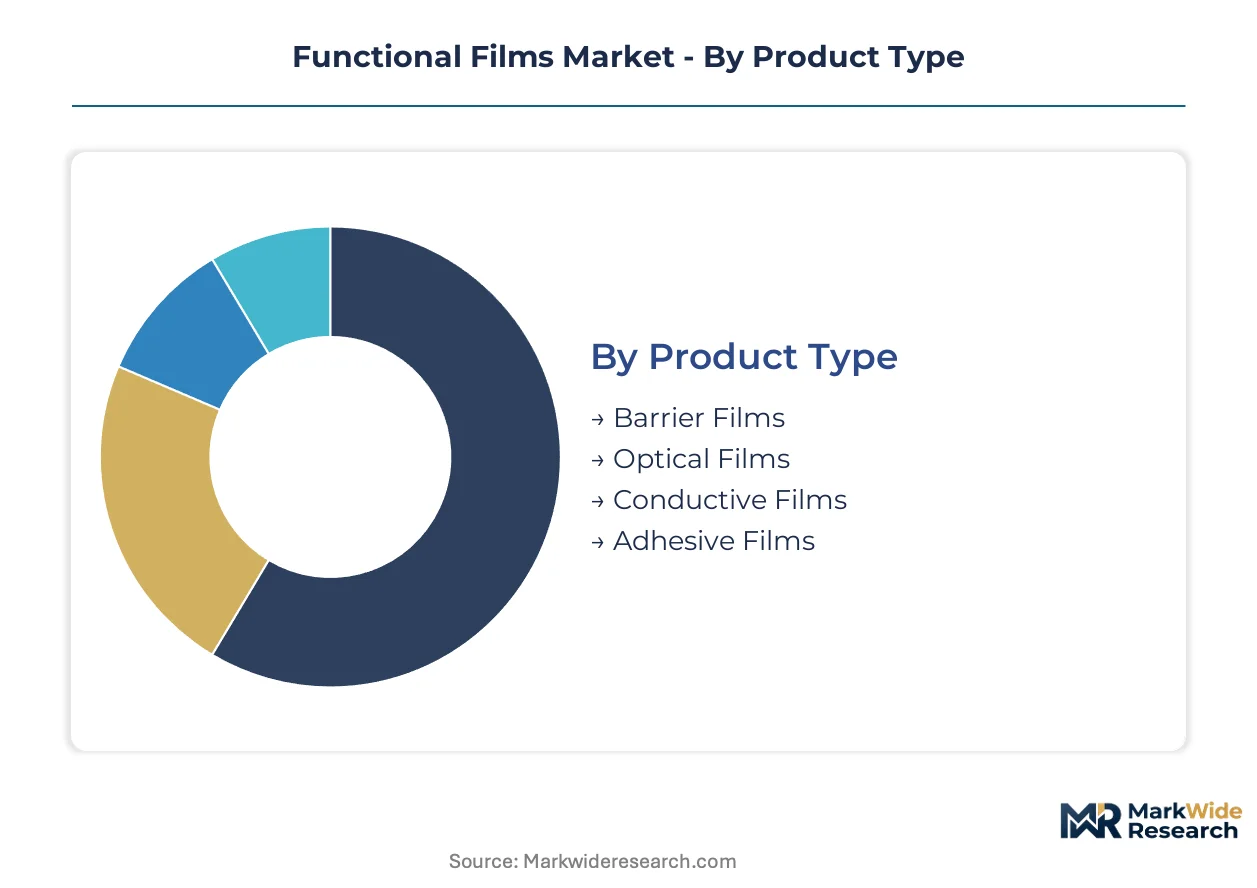
Functional films demand fragments across incompatible performance specifications, forcing producers to maintain parallel extrusion and coating assets. Segmentation reveals where capital intensity concentrates and where formulation flexibility unlocks margin.
Product Type:
Barrier films absorb the highest unit volumes. Optical and conductive grades command premium pricing through tighter thickness tolerances and cleanroom manufacturing requirements.
- Barrier Films:Multi-layer coextrusions or metallized polymers engineered to block oxygen, moisture, and UV transmission. Food and pharmaceutical packaging in Germany and France absorbs capacity under EU Green Deal extended producer responsibility mandates. Technical floors near 12 micrometers prevent further downgauging cost reduction.
- Optical Films:Polyester and polyimide substrates with controlled birefringence, anti-reflective coatings, or brightness-enhancement microstructures. Display panel fabs in Korea and China specify ultra-thin grades for foldable OLED stacks. Atomic layer deposition is displacing thicker multi-layer alternatives.
- Conductive Films:Transparent electrode layers of indium tin oxide or silver nanowires on flexible substrates. Electric vehicle battery manufacturers specify ceramic-coated separators with shutdown functionality.
- Adhesive Films:Pressure-sensitive or heat-activated bonding layers with controlled tack and thermal stability. Medical device lamination and automotive interior assembly drive qualification cycles.
Mature deployment sits with barrier films. Newer deployment is concentrated in conductive films for solid-state battery architectures.
End User:
Electronics and packaging split the revenue base. Automotive and construction represent conversion opportunities from mature polymer applications.
- Packaging:Flexible food, pharmaceutical, and industrial wrapping requiring oxygen transmission rates below 0.1 cc/m²/day. German supermarket chains now mandate recyclable mono-material structures without secondary lamination.
- Electronics:Display substrates, battery separators, and circuit protection films with cleanliness specifications down to Class 1000. Korea's panel fabs co-locate with optical film coaters to compress logistics cycles.
- Automotive:Interior bonding, battery thermal management, and exterior protection films with flame-retardant and weathering resistance. OEMs specify ceramic-coated separators for next-generation cell architectures.
- Construction:Vapor barriers, window insulation films, and building-integrated photovoltaic encapsulants. Japan's METI energy-efficiency labeling accelerates high-performance insulation retrofits.
Volume leadership belongs to packaging. Steepest expansion trajectory is appearing in automotive electrification applications.
Form:
Rolled formats dominate continuous processing economics. Sheet and laminated structures serve batch manufacturing and performance-critical niches.
- Rolled:Continuous wound substrates from 100mm to 3000mm width for high-speed converting lines. Flexible packaging converters in China run solvent-free laminators at 400+ meters per minute.
- Sheet:Cut-to-size panels for membrane switch fabrication, medical device lamination, and architectural glazing interlayers. Thickness precision within ±2 micrometers commands premium positioning.
- Laminated:Multi-ply structures combining barrier, structural, and sealant layers through adhesive or thermal bonding. REACH authorization bottlenecks for phthalate plasticizers force reformulation of legacy flexible PVC constructions.
- Coated:Surface-functionalized films with release, anti-fog, or hardcoat layers applied via roll-to-roll slot die or gravure methods. Cleanroom capital intensity constrains capacity response to demand spikes.
High-throughput deployment centers on rolled formats. Precision-critical adoption is concentrating in sheet formats for medical and aerospace qualification.
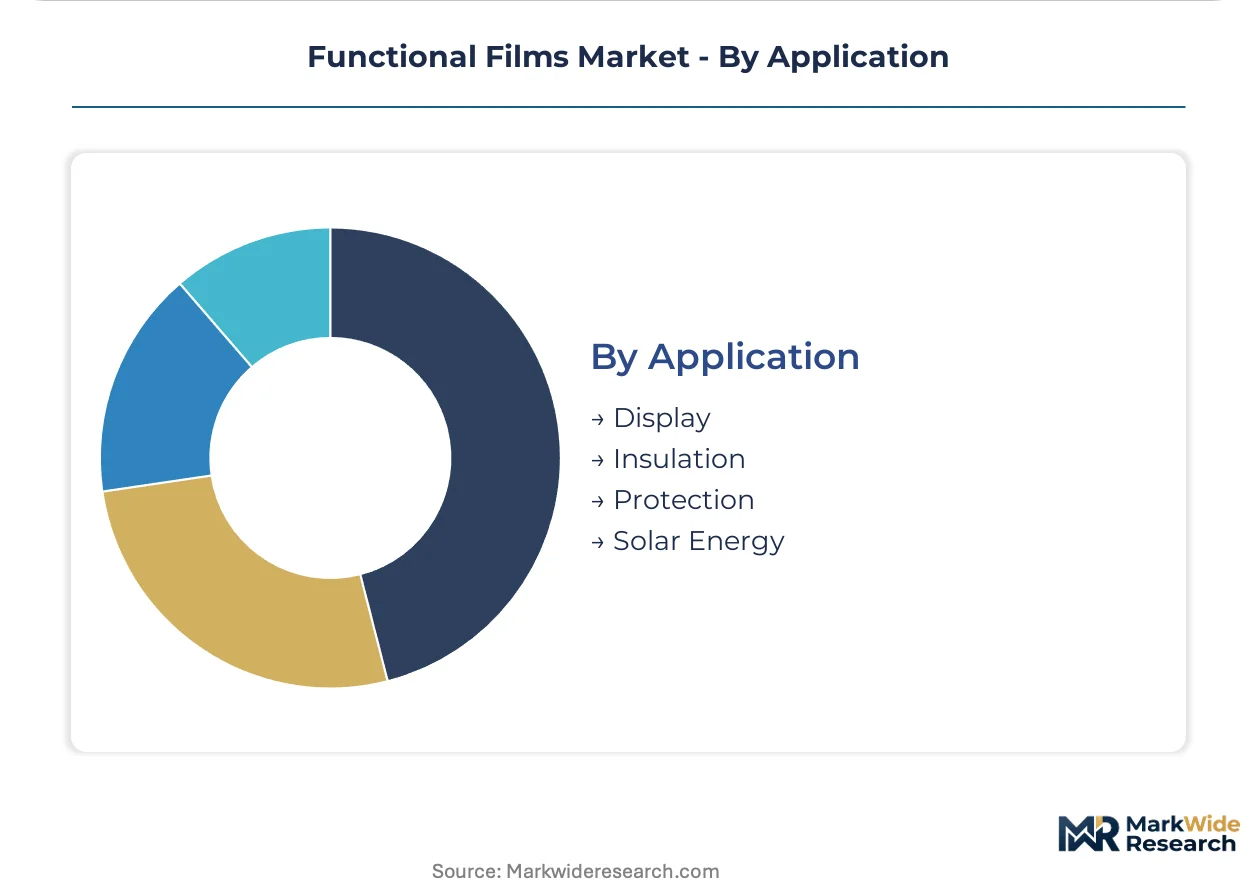
Application:
Display and solar energy applications pull technology investment. Insulation and protection serve replacement markets with lower growth but steadier margins.
- Display:Polarizer substrates, brightness enhancement films, and touch sensor electrodes for LCD, OLED, and microLED panels. Foldable form factors compress development cycles for ultra-thin barrier specifications.
- Insulation:Thermal and acoustic management films for building envelopes, HVAC systems, and industrial equipment. Japan's retrofit mandates sustain demand for high-R-value vapor barriers.
- Protection:Temporary and permanent surface guards against abrasion, chemical exposure, and environmental degradation. Automotive paint protection films specify self-healing polyurethane constructions.
- Solar Energy:Bifacial module backsheets, encapsulant films, and frontsheet barriers with 25-year UV stability warranties. Southeast Asia module assembly clusters pull transparent backsheet capacity from China and Korea.
Established revenue bases sit with insulation and protection. Emerging deployment is concentrating in solar energy as bifacial architectures expand addressable module area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chungcheongnam-do anchors Asia's functional films manufacturing corridor, where display-grade optical film coaters cluster within 50 kilometers of Korea's leading panel fabrication complexes.
China
Domestic polyester and polyimide film production serves both local electronics supply chains and export markets. GB standards for packaging materials shape product formulation roadmaps for functional film exporters. The Yangtze River Delta concentrates metallization and coating capacity for photovoltaic backsheet films.
Germany
Extended producer responsibility frameworks mandate recyclable multi-layer structures, accelerating bio-based substrate qualification timelines. ECHA's sunset date enforcement for phthalate plasticizers forces reformulation of legacy flexible PVC films. The Rhine-Ruhr corridor hosts specialized extrusion lines for high-barrier pharmaceutical packaging.
Japan
METI enforces energy-efficiency labeling that drives adoption of high-performance insulation films in building retrofits. Captive manufacturing in Kansai and Chubu regions anchors competitive positions in optical films for liquid crystal and OLED displays. Nagoya-based polymer specialists maintain cyclo-olefin polymer production for specialty resin supply.
South Korea
Foldable display manufacturing compresses development cycles for ultra-thin barrier films, forcing substrate suppliers to co-locate with panel fabs. Battery separator film specifications from electric vehicle manufacturers specify ceramic-coated polyolefin separators with shutdown functionality. Chungcheongnam-do's cleanroom manufacturing environments constrain capacity response to demand spikes.
United States
FDA food-contact regulations shape testing protocols and market access requirements for functional film exporters. Solvent-based adhesive laminators face air emission enforcement, requiring thermal oxidizer investments that erode margin on commodity film grades. The US Gulf Coast concentrates fluorinated monomer production, exposing film coaters to force majeure vulnerability.
Functional Films Market Vendor Landscape
Premium-margin players sit above commodity-margin players across thickness tolerance and cleanroom certification tiers. The vendor base stratifies into three tiers: integrated polymer producers with captive resin supply, specialized film coaters with roll-to-roll deposition expertise, and regional converters serving packaging end-users. Two strategic archetypes dominate: backward-integrated chemical conglomerates controlling specialty resin production, and precision coaters co-located with display panel fabrication clusters. Capacity expansion and strategic partnerships represent the dominant competitive moves, with M&A activity concentrating on coating line assets and regional distribution networks.
Within the integrated chemical tier, BASF and Eastman Chemical Company exemplify backward-integrated positioning through specialty resin production. Toray Industries occupies a position among precision optical film specialists with captive manufacturing in Japan and Korea. 3M represents the diversified materials archetype, sitting within premium-tier pricing through anti-reflective and brightness-enhancement specifications.
| Leading Market Players |
|---|
| BASF |
| Eastman Chemical Company |
| 3M |
| Honeywell |
| Avery Dennison |
| Toray Industries |
| Mitsubishi Polyester Film |
| Saint-Gobain |
| DuPont |
| Others |
Supply Flow & Price Mechanics
Backward integration into specialty resin production anchors competitive positioning for integrated polymer producers, granting captive supply control over cyclo-olefin polymers and fluorinated monomers that film coaters without upstream assets cannot replicate. This structural choice concentrates pricing power among BASF and Eastman Chemical Company while exposing non-integrated coaters to force majeure vulnerability from Japan and US Gulf Coast monomer suppliers.
Pricing Analysis
Yield-guaranteed pricing structures dominate optical and conductive film tiers, where display panel fabs and battery manufacturers contract for zero-defect throughput rather than per-meter substrate costs. Three-tier pricing structure across premium, standard, and economy levels separates Class 1000 cleanroom-certified optical films from commodity barrier grades. Pricing pressure stems from EU Green Deal mandates accelerating bio-based substrate qualification timelines without equivalent cost structures. Packaging converters exhibit highest price sensitivity, while automotive battery manufacturers absorb premium positioning for ceramic-coated separators.
Supply Chain Analysis
India's PLI scheme domestic-content requirements are reshaping sourcing patterns for display and semiconductor fabrication inputs, pulling metallization capacity toward Maharashtra and Gujarat. Raw material dependencies center on polyester and polyimide resin feedstocks from China, specialty monomers from Japan, and ceramic coating precursors from Germany. Single-source vulnerability concentrates in cyclo-olefin polymer production anchored in Nagoya-based facilities. Distribution runs through regional converting clusters in the Yangtze River Delta, Chungcheongnam-do, and the Rhine-Ruhr corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around cleanroom-certified capacity and captive resin supply, with REACH authorization bottlenecks and MEE air emission enforcement forcing sub-scale coaters toward exit or acquisition.
For Market Incumbents: Hedge against fluoropolymer substitution risk by accelerating silicone and hydrocarbon-based barrier formulations ahead of ECHA's per- and polyfluoroalkyl substance restrictions. Deepen backward integration into bio-based polymer feedstocks to defend margin position as German supermarket chains mandate recyclable mono-material structures without secondary lamination premiums. For New Entrants and Emerging Players: Launch via direct qualification with India's PLI-subsidized display fabs, targeting barrier film metallization capacity gaps in Maharashtra before incumbent Korean suppliers establish local cleanroom operations. Focus initial penetration on water-based ink-compatible polyester substrates for short-run flexible packaging, exploiting gravure-to-digital conversion pressure among European private-label converters. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking roll-to-roll coating assets and regional distribution networks. Five-to-ten year viability hinges on ALD equipment adoption curves displacing incumbent coextrusion lines. Watch atomic layer deposition adoption rates in Korean solid-state battery separator specifications as the inflection signal for coating technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive cyclo-olefin polymer supply insulates BASF and Eastman from Japan force majeure exposure. |
| Cleanroom Capacity Expansion | Class 1000 manufacturing environments in Chungcheongnam-do compress logistics cycles for Korean panel fabs. |
| Bio-based Substrate Qualification | EU Green Deal extended producer responsibility mandates accelerate BASF barrier formulation development timelines. |
| Atomic Layer Deposition Adoption | ALD-coated separators threaten incumbent coextrusion equipment suppliers in Korean battery supply chains. |
| India PLI Localization | Domestic metallization capabilities in Maharashtra capture first-mover advantage for display barrier films. |
Methodological Framework
Multi-period observation of cleanroom certification tiers, resin supply concentration, and regulatory sunset dates anchored the trend analysis, supplemented by interviews with optical film coating line managers, polymer plant engineers at integrated chemical producers, procurement leads at Korean display panel fabs, and flexible packaging converters in Germany. Secondary validation drew from ECHA authorization databases, FDA food-contact substance inventories, SEC 10-K disclosures by listed chemical conglomerates, and MIIT capacity registration filings. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers across electronics, packaging, and automotive end-uses.
Segment-weighting approaches modeled demand fragmentation across barrier, optical, conductive, and adhesive product types, with further disaggregation by rolled versus sheet formats and Class 1000 versus standard manufacturing environments. CAGRs were derived from slope analysis of historical capacity utilization and forward-projected qualification timelines for bio-based and ALD-enabled substrates. Industry-specific forecast inputs incorporated GB standards evolution for packaging materials, METI energy-efficiency labeling adoption curves, and PLI scheme disbursement schedules.
Regulatory enforcement delays, raw material force majeure events, and technology substitution curves are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding cleanroom construction timelines, ECHA sunset date adherence, and resin supply diversification progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Side Pour Caps Market
Packaging
Cushion Case Liner Market
Packaging
Europe Luxury Packaging Market
Packaging
Corrugated Packaging Software Market
Packaging
Graduated Sample Bottle Market
Packaging
Tear-Tab Lids Market
Packaging
India Biodegradable Tableware & Packaging Products Market
Packaging
Can Seamers Market
Packaging
Foam Protective Packaging Market
Packaging
Europe Metal Caps and Closures Market
Packaging
Oral Dose Packaging Market
Packaging
High Barrier Lidding Film Market
Packaging
Tube Filling Machine Market
Packaging
Milk Powder Packaging Market
Packaging
Insulated Box Liner Market
Packaging
Fiber Lids Market