
 Hygiene Packaging Films Market | 2026-2036
Hygiene Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Hygiene Packaging Films Market Foresight
A capital-intensity divergence between multilayer coextrusion specialists and commodity film converters is reorganizing competitive tiers in hygiene packaging. Amcor plc leverages its global extrusion footprint to sustain supply agreements with major diaper brands across North America and Western Europe. Berry Global Inc. anchors its position through vertical integration into resin compounding, which controls formulation costs for breathable backsheet films. Clöckner Pentaplast differentiates via laser-perforation technology leadership, occupying premium niches in ultra-thin personal care laminates.
Hygiene packaging films are multilayer polymeric structures, typically 12–50 microns thick, engineered from polyethylene, polypropylene, or polyester substrates with controlled moisture vapor transmission rates between 800–8000 g/m²/day to manage skin health in absorbent products. These films serve as liquid-impermeable yet breathable outer barriers in disposable hygiene articles, preventing leakage while reducing dermatological irritation. Polyethylene dominates volume across diaper and sanitary napkin applications due to its sealability and cost position, though polypropylene is gaining share in premium adult incontinence segments where softer hand feel commands margin. The wipes application category is expanding fastest structurally, as wet wipe format diversification drives demand for alcohol-resistant film substrates with enhanced chemical stability.
The FDA regulates skin-contact materials under 21 CFR 177.1520 for olefin polymers used in hygiene articles, while the EU REACH framework restricts phthalate plasticizers and mandates substance-of-very-high-concern disclosure across film supply chains. India's BIS certification requirements for imported plastic raw materials are tightening compliance burdens for converters sourcing PE resin from Middle Eastern suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and Asia-Pacific, as fee structures for post-consumer film recovery will increasingly influence substrate selection and regional manufacturing location decisions.
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand for conventional polyethylene films while accelerating converter migration toward bio-based substrates and mechanical recycling streams. This regulatory pivot is restructuring raw material procurement patterns across European diaper and sanitary napkin supply chains.
Growth Catalysts
- Geriatric Demographics:Aging populations in Germany and Japan are expanding adult incontinence film volumes. Manufacturers are commissioning higher-MVTR barrier specifications for skin-sensitive applications.
- REACH SVHC Disclosure Mandates:ECHA substance-of-very-high-concern rules are pushing converters toward phthalate-free plasticizer systems. Film suppliers with certified clean formulations are capturing premium supply agreements.
- Wet Wipe Format Diversification:Alcohol-resistant coextruded substrates are penetrating personal care segments. Chemical stability specifications are tightening as disinfectant-loaded wipes multiply.
Market Restraints
- Ethylene Feedstock Volatility:Naphtha-cracker economics in the Middle East are transmitting price instability to PE resin contracts. Converters lack hedging instruments for six-month formulation planning.
- Multilayer Coextrusion Equipment Concentration:Precision die-head manufacturing is concentrated among German and Austrian machinery suppliers. Lead times for nine-layer systems now exceed fourteen months.
- Mechanical Recycling Contamination Limits:Post-consumer hygiene films carry adhesive and absorbent core residues that exceed current sorting technology thresholds. Circular economy targets face technical barriers.
Strategic Opportunities
- Indian Diaper Manufacturing Scale-Up:Domestic personal care brands in Maharashtra and Gujarat are localizing backsheet film sourcing. Joint ventures with Middle Eastern resin suppliers are securing feedstock positions.
- Laser Perforation Convergence:Precision micro-hole patterning is merging with breathable adhesive lamination. Ultra-thin personal care laminates are opening margin-rich premium niches.
- BIS Import Certification Gaps:India's tightening standards for PE resin imports are creating captive demand for domestic compounding capacity. Local formulation control is becoming a strategic anchor.
Industry Challenges
- Coextrusion Process Engineering Talent:Nine-layer die design and layer-thickness uniformity control require specialized expertise that outpaces vocational training pipelines in emerging manufacturing clusters.
- Extended Producer Responsibility Fee Modeling:European post-consumer film recovery cost structures remain undefined. Substrate selection decisions are stalled pending clarity on polyethylene versus bio-based liability exposure.
- MVTR Testing Protocol Harmonization:Inconsistent moisture vapor transmission rate measurement standards between ASTM and JIS methods are complicating cross-border specification negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hygiene Packaging Films Market |
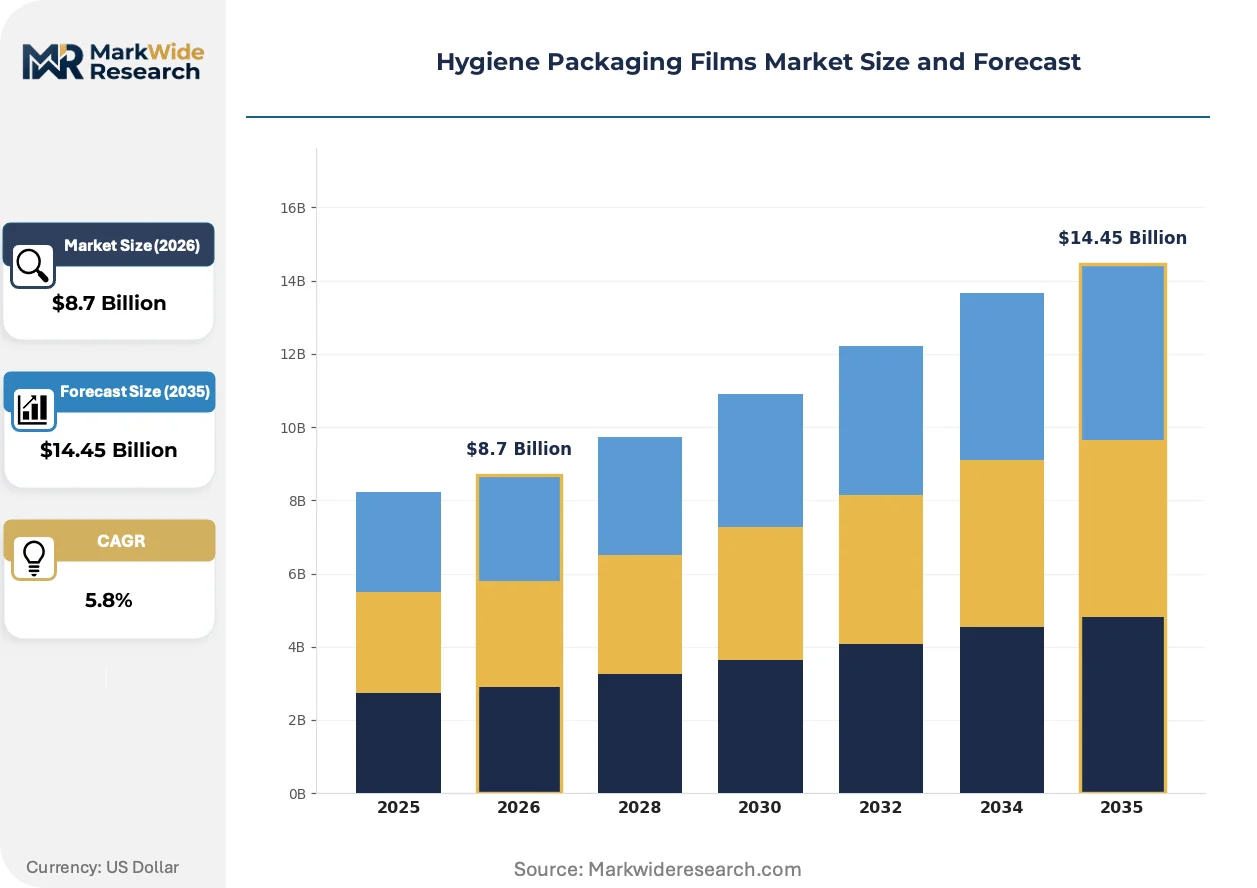
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyester, Polyvinyl Chloride End User: Personal Care, Medical, Food, Industrial Application: Diapers, Adult Incontinence, Sanitary Napkins, Wipes Size: Small, Medium, Large, Extra Large |
| Companies Covered | Amcor plc, Berry Global Inc., Sealed Air Corporation, Kimberly-Clark, WestRock, DuPont de Nemours, Inc., Clöckner Pentaplast, Mondi plc, Toray Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hygiene Packaging Films Market Shifts & Advancements
Bio-based polyethylene feedstocks are decomposing the conventional fossil-resin value chain while laser-perforation systems enable micro-scale breathability control. Regulatory frameworks and procurement patterns are simultaneously rewriting technical specifications and supplier qualification criteria.
Cast coextrusion with metallocene polyethylene is decomposing blown-film dominance in premium backsheet applications. Adult incontinence manufacturers in Japan are adopting these substrates for softer hand-feel and precise MVTR targeting. The technology is decomposing commodity converter margins by concentrating volume among specialists with metallurgy-controlled die-gap precision.
REACH substance-of-very-high-concern disclosure thresholds are forcing formulation transparency across European hygiene film supply chains. Converters must now document plasticizer chemistry through three tiers of subcontracting. Small and mid-scale suppliers without in-house analytical laboratories face compliance cost disadvantages against integrated compounders.
Direct mill relationships are replacing distributor intermediation among large diaper manufacturers seeking resin traceability. Procter & Gamble and Essity are contracting Middle Eastern ethylene producers for certified bio-based content. This disintermediation is most visible in Germany where sustainability auditing requirements demand batch-level carbon accounting.
Hygiene Packaging Films Market Segmentation
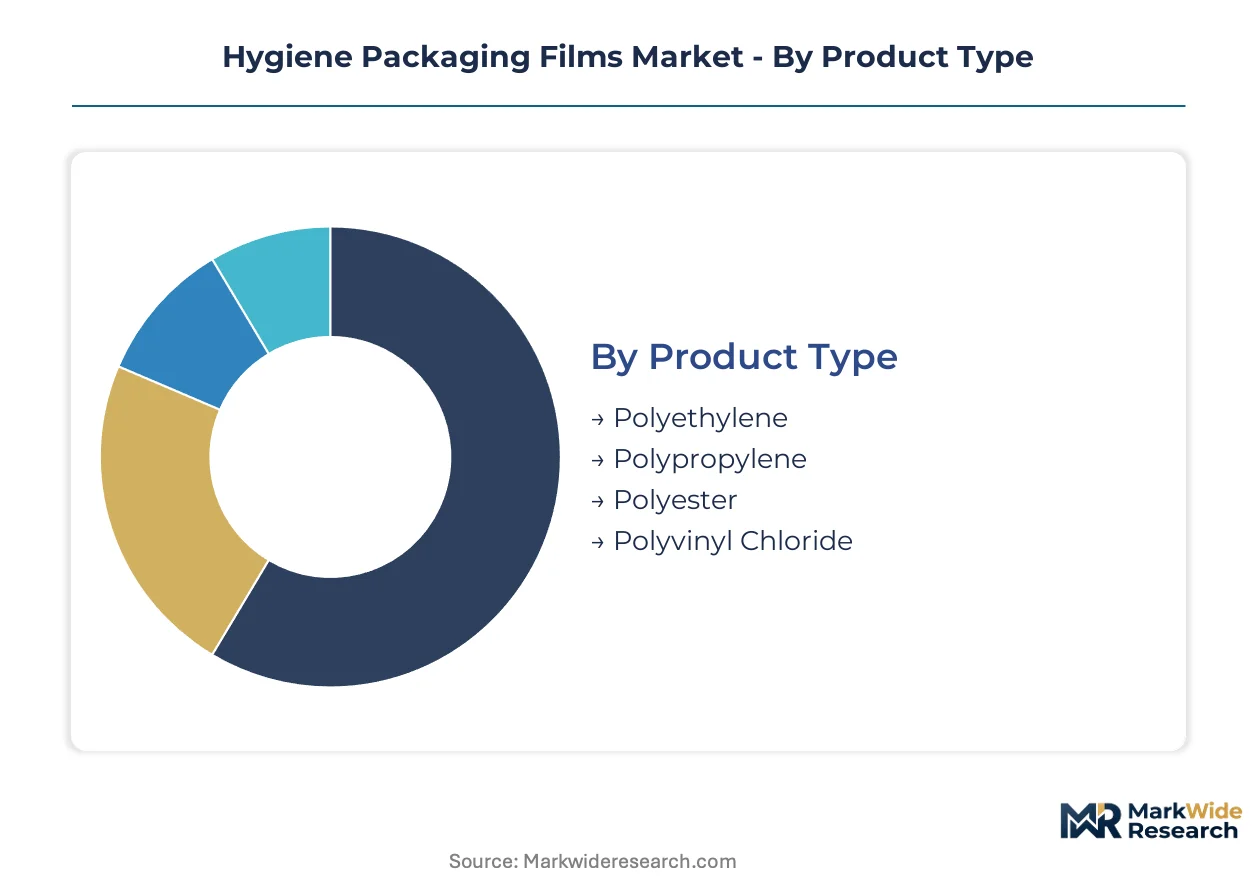
Segmentation in hygiene packaging films separates commodity polyethylene converters from precision substrate specialists. Each dimension—material chemistry, end-use performance, application format, and sizing—creates distinct margin tiers and capability requirements.
Product Type:
Margin pools concentrate in metallocene-modified substrates where breathability precision commands premium pricing.
- Polyethylene:Linear low-density and metallocene grades dominate diaper backsheet production through controlled sealability and cost-efficient processing. Demand concentrates in India's Maharashtra and Gujarat clusters where domestic diaper manufacturing is scaling rapidly, though converters face BIS certification burdens on imported resin.
- Polypropylene:Cast film configurations deliver softer hand-feel for adult incontinence segments in Japan. Higher crystallinity enables precise moisture vapor transmission targeting, attracting premium supply agreements from German manufacturers serving skin-sensitive applications.
- Polyester:Biaxially oriented films provide dimensional stability for wet wipe packaging requiring alcohol resistance.
- Polyvinyl Chloride:Flexible calendered grades persist in legacy medical pouch applications despite REACH plasticizer restrictions.
Polyethylene holds installed capacity. Polypropylene is rotating up the share rankings.
End User:
Volume distribution tracks absorbent hygiene manufacturing clusters rather than geographic consumption patterns.
- Personal Care:Diaper and sanitary napkin backsheet films require 800–8000 g/m²/day MVTR specifications with liquid-impermeable barrier function. Demand concentrates in Western Europe where EU Single-Use Plastics Directive compliance costs are accelerating converter consolidation.
- Medical:Sterile barrier films for surgical drapes and isolation gowns demand validated seal integrity and bioburden control. FDA 21 CFR 177.1520 compliance dominates procurement qualification in North American supply chains.
- Food:Modified atmosphere packaging films leverage similar coextrusion equipment but divergent regulatory pathways.
- Industrial:Protective masking and surface protection films compete on throughput scale rather than technical specification.
Personal Care captures the dominant share of precision extrusion capacity. Medical is climbing the fastest on regulatory compliance premiums.
Application:
Format-specific performance requirements fragment converter specialization across breathability, chemical resistance, and mechanical strength vectors.
- Diapers:Backsheet films balance leakage prevention with skin health through microporous or monolithic breathable structures. Demand concentrates in North America where Procter & Gamble and Essity maintain direct mill relationships for resin traceability and batch-level carbon accounting.
- Wipes:Alcohol-resistant coextruded substrates with enhanced chemical stability are expanding most quickly as disinfectant-loaded formats multiply. Wet wipe diversification in European personal care is tightening specifications for substrate solvent resistance.
- Adult Incontinence:Higher-MVTR barrier specifications address aging population skin sensitivity in Germany and Japan.
- Sanitary Napkins:Ultra-thin laminate requirements favor laser-perforation technology for micro-scale breathability control.
Diapers command the deepest installed coextrusion capacity. Wipes is gaining share fastest on format innovation velocity.
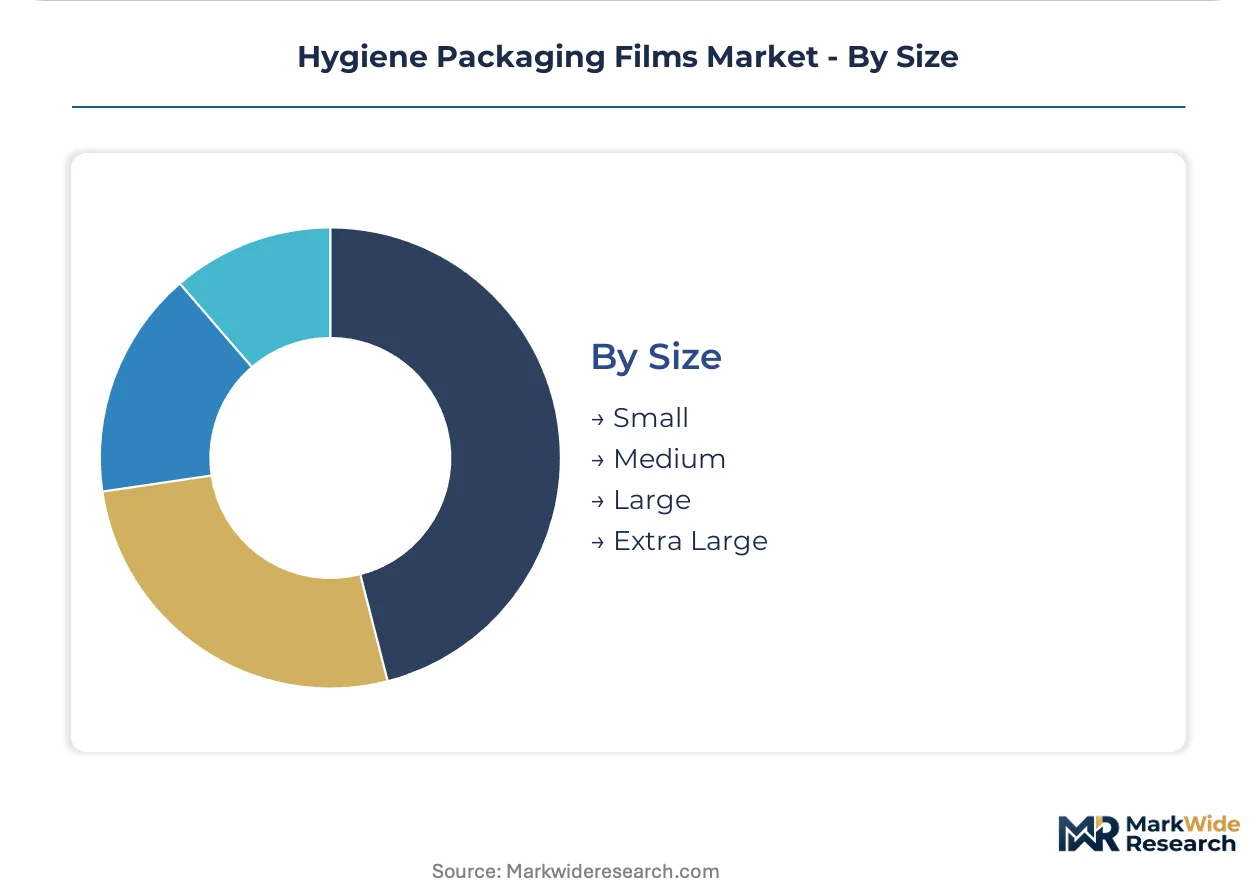
Size:
Width and roll diameter configurations align with converting equipment gauge and end-user slitting economics.
- Small:Narrow-web rolls serve specialty wipe converters and regional diaper manufacturers with limited slitting infrastructure.
- Medium:Standard backsheet widths match high-speed diaper line requirements across European and North American production facilities.
- Large:Jumbo rolls minimize changeover frequency for integrated hygiene manufacturers with captive film slitting.
- Extra Large:Mill-direct formats support continuous extrusion-to-converting operations at major absorbent hygiene producers.
Medium formats hold the broadest installed base. Extra Large is rotating up on integrated manufacturing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command premium pricing for metallocene-modified substrates, while Indian manufacturers compete on volume throughput for standard polyethylene backsheet grades. This pricing-power asymmetry reflects divergent regulatory burdens and technical capability concentrations across manufacturing clusters.
Germany
Adult incontinence film demand from aging demographics drives specialty substrate volumes. ECHA REACH substance-of-very-high-concern disclosure mandates enforce phthalate-free formulation transparency. The North Rhine-Westphalia industrial corridor hosts precision coextrusion specialists serving skin-sensitive barrier specifications.
Japan
Cast coextrusion with metallocene polyethylene penetrates premium adult incontinence segments for softer hand-feel. METI circular economy guidelines accelerate mechanical recycling infrastructure investments. The Kansai region around Osaka concentrates breathable film converting for elderly care product supply chains.
United States
Direct mill relationships between diaper manufacturers and Middle Eastern resin suppliers disintermediate traditional distribution channels. FDA 21 CFR 177.1520 compliance dominates skin-contact material qualification. The Midwest manufacturing belt integrates captive film slitting at major absorbent hygiene production facilities.
India
Domestic diaper manufacturing scale-up in Maharashtra and Gujarat drives backsheet film localization. BIS certification requirements for imported PE resin tighten compliance burdens on converters sourcing from Middle Eastern suppliers. The Pune-Ahmedabad industrial corridor attracts joint ventures securing captive resin compounding capacity.
China
Wet wipe format diversification accelerates demand for alcohol-resistant coextruded substrates. MIIT standards for plastic product quality enforcement tighten substrate chemical stability specifications. The Yangtze River Delta manufacturing cluster concentrates precision die-head processing equipment for multilayer hygiene films.
Hygiene Packaging Films Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the hygiene packaging films sector. The market structure organizes around three tiers: integrated multinational compounders with resin traceability capabilities, regional specialists commanding laser-perforation precision, and commodity converters competing on throughput scale. Strategic moves concentrate on backward integration into resin sourcing and geographic expansion through joint ventures in high-growth manufacturing clusters.
Within the integrated multinational tier, Amcor plc and Berry Global Inc. represent archetypes of global extrusion footprint scale. Clöckner Pentaplast occupies a specialist position exemplifying premium technology differentiation. These three anchors demonstrate how competitive positioning separates through upstream control over formulation costs versus precision engineering capabilities in micro-scale breathability systems.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Sealed Air Corporation |
| Kimberly-Clark |
| WestRock |
| DuPont de Nemours, Inc. |
| Clöckner Pentaplast |
| Mondi plc |
| Toray Industries Inc. |
| Others |
Supply & Pricing Matrix
Metallocene polyethylene substitution for conventional LLDPE grades is simultaneously shifting supply geography toward German and Austrian machinery corridors and compressing margin pools among commodity converters lacking die-gap precision capabilities. This material transition concentrates pricing power with specialists who control metallurgy-controlled coextrusion systems while standard backsheet film producers face cost compression from Middle Eastern resin volatility.
Pricing Analysis
The customization-premium spread separates laser-perforated breathable laminates from commodity diaper backsheet films by a factor of three to four on per-kilogram contract terms. Pricing stratifies across premium metallocene-modified substrates, standard LLDPE backsheet grades, and economy recycled-content films, with differentiation driven by MVTR precision certification and direct mill relationship status. Pricing pressure stems from ethylene feedstock volatility transmitted through naphtha-cracker economics in the Middle East, eroding six-month formulation planning stability. Large diaper manufacturers with direct resin contracts exhibit lowest price sensitivity, while regional wipe converters in India face highest sensitivity due to BIS certification burdens on imported PE.
Supply Chain Analysis
Germany and Austria anchor precision multilayer coextrusion equipment manufacturing, with nine-layer die-head suppliers commanding fourteen-month lead times that constrain global capacity expansion. Raw material dependencies center on Middle Eastern ethylene production, Southeast Asian metallocene catalyst supply, and Indian domestic compounding capacity under BIS tightening. Single-source vulnerability concentrates in German-Austrian machinery corridors where specialized process engineering talent outpaces training pipelines. Distribution runs through direct mill relationships disintermediating traditional resin distributors, with Procter & Gamble and Essity contracting Middle Eastern producers for batch-level carbon accounting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based polyethylene interoperability with existing coextrusion infrastructure is creating platform-economics inflection, where substrate certification systems and extended producer responsibility frameworks become the governing interoperability layer for supplier qualification.
For Market Incumbents: Consolidate formulation control through backward integration into resin compounding, particularly in India where BIS certification gaps create captive demand for domestic capacity. Amcor plc and Berry Global Inc. archetypes must secure Middle Eastern bio-based feedstock positions before direct mill relationships fully disintermediate distributor channels. Laser-perforation technology leadership at Clöckner Pentaplast demonstrates how precision engineering capabilities defend margin position against commodity converter encroachment. For New Entrants and Emerging Players: Service-layer gaps in REACH SVHC disclosure documentation and three-tier formulation transparency create white-space entry points for analytical laboratory-equipped compounders. The most penetrable segment sits in Indian domestic diaper manufacturing clusters in Maharashtra and Gujarat, where local backsheet film sourcing scales rapidly but BIS compliance burdens stall import-dependent converters. A go-to-market angle anchored in certified phthalate-free formulation disclosure captures premium supply agreements from European personal care manufacturers facing ECHA mandates. For Investors and Strategic Acquirers: EU Single-Use Plastics Directive implementation reshapes the acquisition landscape toward bio-based substrate specialists with validated mechanical recycling pathways. Long-term viability across the analysis window favors integrated compounders with in-house analytical capabilities over pure-play converters exposed to resin price volatility. The signal to watch is clarity on extended producer responsibility fee structures, which will determine liability exposure differentials between polyethylene and bio-based substrate positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | BIS certification requirements in India create captive demand for domestic formulation control. |
| Laser Perforation Technology Acquisition | Precision micro-hole patterning captures premium niches in ultra-thin personal care laminates. |
| Joint Venture in Indian Manufacturing Corridor | Maharashtra and Gujarat clusters localize backsheet supply for scaling domestic diaper brands. |
| Bio-based Feedstock Supply Agreement | Direct mill relationships with Middle Eastern producers secure batch-level carbon accounting. |
| REACH Compliance Documentation Platform | SVHC disclosure capabilities capture premium supply agreements from European converters. |
Research Methodology
Desk research of customs and trade data, SEC filings from packaging converters, and ECHA regulatory databases preceded structured interviews with coextrusion equipment specialists, resin procurement leads at major diaper manufacturers, hygiene film R&D directors, and regulatory compliance officers across German and Indian manufacturing clusters. Primary fieldwork with plant managers in North Rhine-Westphalia and the Pune-Ahmedabad corridor combined with secondary validation from FDA 21 CFR guidance documents and BIS certification records. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across material chemistry and application format dimensions.
Variance decomposition across the projection horizon isolates volume drivers by segmentation dimension: material chemistry shifts between polyethylene, polypropylene and bio-based substrates; end-use concentration in personal care versus medical applications; application format evolution in wipes versus diaper backsheet demand; and regional manufacturing cluster development in India and Germany. CAGRs derive from fitted growth curves anchored to demographic projections for adult incontinence demand and regulatory implementation timelines for EU Single-Use Plastics Directive compliance. Industry-specific forecast inputs include MVTR specification tightening rates and laser-perforation technology penetration curves.
Underlying assumptions cover sustained ethylene feedstock availability, REACH SVHC disclosure threshold stability, and Indian BIS certification enforcement continuity, with deviation risk concentrated in Middle Eastern naphtha-cracker economics and European extended producer responsibility fee structure finalization. Recalibration cycles align with material shifts in regulatory implementation timelines and bio-based substrate cost parity milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Cling Films Market