
 Special Effects Laminate Films Market | 2026-2036
Special Effects Laminate Films Market Size, Share, and Industry Trends Forecast 2026-2036
Special Effects Laminate Films Market Analytics
Aftermarket specialty finishing services is tilting margin pools away from commodity thermal lamination toward value-added holographic and textured effects. Nobelus leverages its North American distribution network to control channel access for premium optical finishes. Derprosa specializes in soft-touch and scuff-resistant formulations that anchor its position in European graphic arts. Cosmo Films Ltd. dominates BOPP-based special effects substrates through backward integration into resin compounding and metallization.
Special effects laminate films are multi-layer polymer or paper substrates engineered with diffraction gratings, metallic deposition layers, or tactile coatings, typically ranging from 12 to 250 microns in caliper, designed to impart visual distinction and surface protection to printed goods. Their primary commercial purpose is to elevate perceived product value while extending print durability in high-wear environments. Polyester-based holographic laminates command the thickest margin pools due to tooling complexity and brand-guarded pattern libraries. Digital printing compatibility represents the fastest-growing technology segment as short-run personalization collapses minimum order thresholds for embellished packaging.
The EPA regulates volatile organic compound emissions from solvent-based adhesive lamination processes, pushing converters toward waterborne and UV-cured coating systems. REACH compliance in Europe restricts certain phthalate plasticizers in PVC decorative films, reshaping formulation roadmaps for suppliers serving the EU. FDA indirect food contact standards govern special effects laminates deployed in premium food packaging applications. Stakeholders must monitor how dual regulatory pressure on chemical composition and carbon intensity reshapes raw material qualification timelines and regional sourcing strategies.
Market Dynamics
Digital printing compatibility is collapsing minimum order thresholds for embellished packaging, fragmenting demand into short-run personalization jobs that reward agile converters over scale-dependent holographic tooling houses.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material traceability mandates for decorative laminates are accelerating converter investment in certified supply chains and blockchain-tracked substrates.
- Cosmetics sector procurement:Premium beauty brands are expanding holographic and iridescent finish specifications to differentiate shelf presence in duty-free and specialty retail channels.
- UV-cured coating systems:EPA volatile organic compound restrictions on solvent-based adhesive lamination are pulling technical investment toward waterborne and energy-cured alternatives with faster line speeds.
Market Restraints
- Metallized PET tooling concentration:Master shim origination for diffraction gratings clusters among a handful of European and Japanese optical security firms, creating chokepoint vulnerability.
- Phthalate formulation lockout:REACH restrictions on plasticizers in PVC decorative films force reformulation cycles that extend raw material qualification timelines by 12-18 months.
- Aluminum deposition cost volatility:Vacuum metallization energy intensity exposes margin structures to European natural gas price swings and carbon border adjustment exposure.
Strategic Opportunities
- Indian pharmaceutical blister packaging:CDSCO track-and-trace mandates for export-oriented generics create demand for tamper-evident holographic laminates with integrated authentication features.
- Textile heat-transfer convergence:Sublimation-compatible special effects films are opening apparel and soft-goods decoration channels beyond traditional graphic arts.
- California SB 54 implementation:Extended producer responsibility frameworks for single-use packaging incentivize mono-material recyclable laminates with decorative functionality.
Industry Challenges
- Diffractive optics talent scarcity:Master origination engineers with electron-beam lithography expertise are retiring faster than apprenticeship pipelines replenish, constraining pattern library expansion.
- Dual certification burden:FDA indirect food contact validation combined with EU REACH compliance creates parallel testing tracks that delay product launches by 8-14 months.
- Legacy thermal lamination asset stranding:Converters with sunk investment in solvent-based coating lines face write-down pressure as brand owners mandate carbon footprint disclosures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Effects Laminate Films Market |
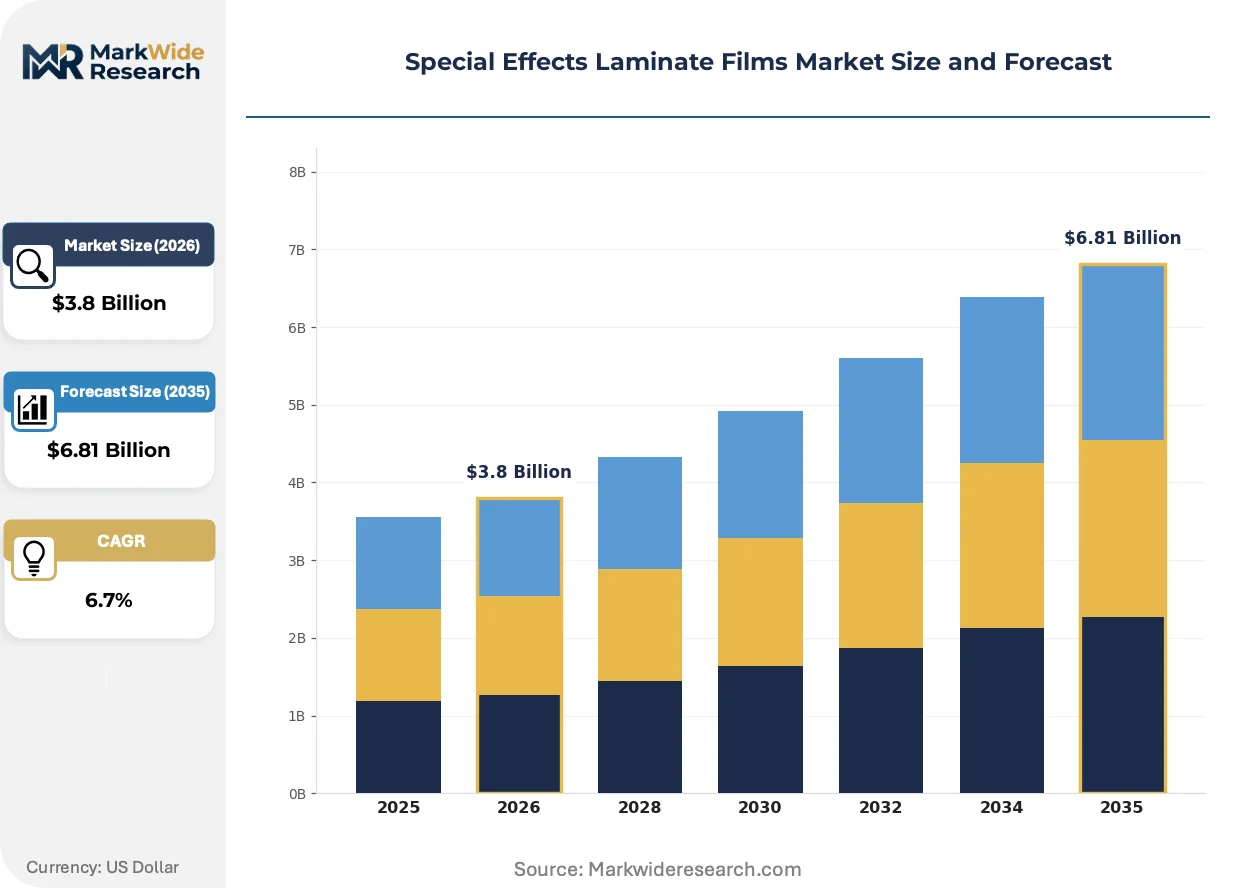
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, PVC, BOPP, Paper Application: Graphic Arts, Packaging, Automotive, Construction End User: Printing Companies, Manufacturers, Retailers, Designers Technology: Digital Printing, Flexographic Printing, Gravure Printing, Others |
| Companies Covered | Nobelus, Aqua Aura, Vivid Laminating Technologies Ltd, Hilton Laminating, Derprosa, Cosmo Films Ltd., D&K Group, Inc., Flex Films, Transilwrap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Effects Laminate Films Market Evolving Landscape
Active reshaping in special effects laminates centers on three vectors: digital workflow integration, regulatory chemistry transformation, and procurement model compression toward just-in-time embellishment.
Electron-beam-cured tactile coatings are migrating from rotary screen analog deposition to inkjet-compatible formulations that enable variable texture across a single printed web. Short-run book cover and invitation printers in North America are adopting these systems to offer embossed-feel finishes without fixed tooling costs. The shift is compressing job turnaround from weeks to days while fragmenting order economics toward micro-batches previously uneconomical for holographic effects.
REACH authorization requirements for chromium trioxide in electroplated master shims are forcing origination houses toward nickel sulfamate and pulse-plating alternatives with reduced environmental health risks. German and Austrian optical security suppliers are absorbing capital costs for closed-loop wastewater recovery systems to maintain pattern development capacity. The regulatory pressure is concentrating master origination among facilities with integrated effluent treatment, excluding smaller toolrooms from premium security-grade work.
Brand owner sustainability scorecards are collapsing traditional spot-buying relationships into multi-year preferred supplier agreements with carbon accounting requirements. Cosmetic and luxury goods packaging managers in France and Italy are consolidating laminate procurement among converters with Science Based Targets initiative commitments. The behavioral shift is disintermediating independent trade finishers lacking verified scope 3 emissions data from premium account access.
Special Effects Laminate Films Market Segmentation
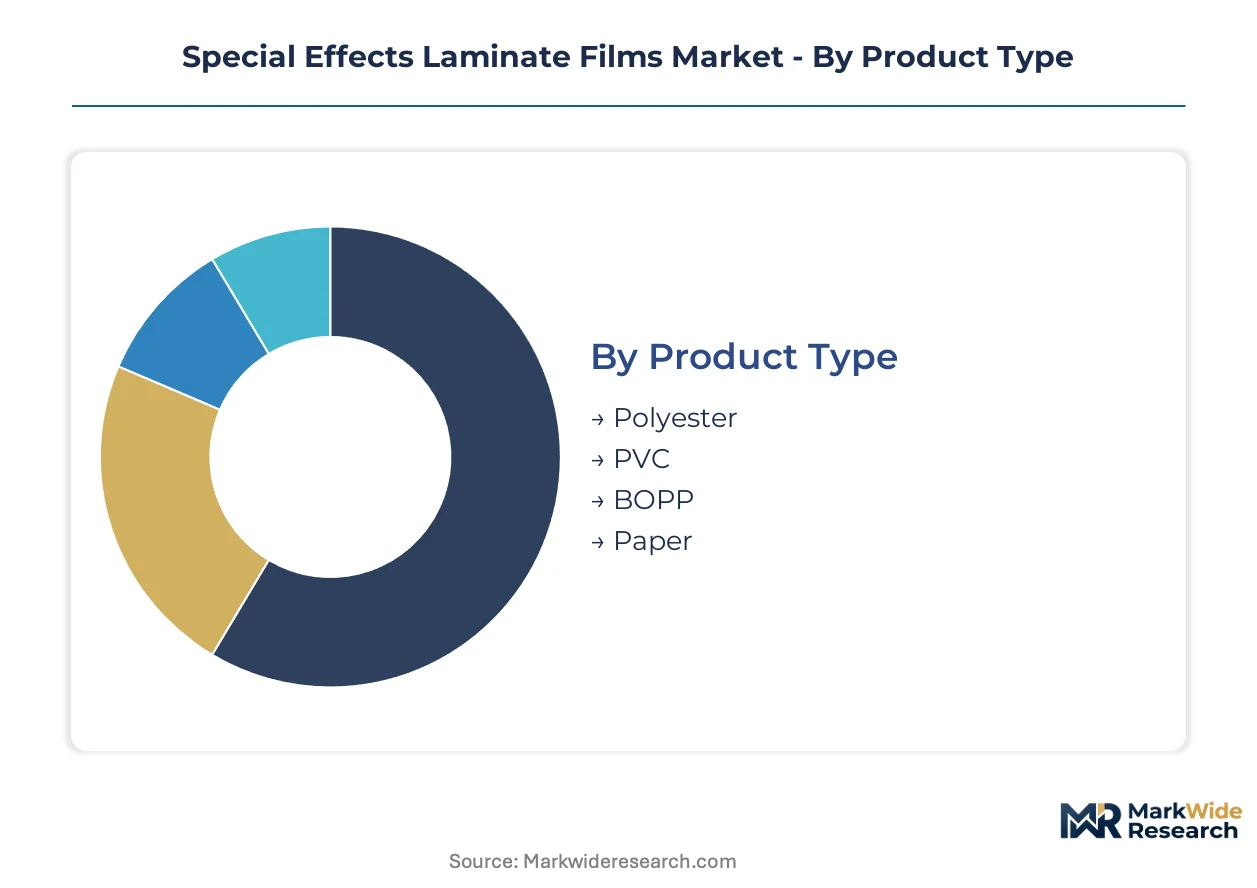
Segmentation in special effects laminate films reveals how technical specifications, print compatibility, and end-use durability requirements fragment procurement patterns across converter tiers and brand owner categories. Understanding these divisions exposes where margin pools concentrate and which substrate-technology combinations reward specialized investment.
Product Type:
After-sales service intensity varies sharply by substrate chemistry, with metallized PET demanding optical defect remediation and holographic pattern recalibration that polyester suppliers bundle into technical service contracts.
- Polyester:Biaxially oriented PET substrates with aluminum vacuum deposition and embossed diffraction gratings dominate security-grade applications. German premium print finishing houses around Düsseldorf specify 23-micron holographic PET for cosmetics packaging, driven by EU Packaging and Packaging Waste Regulation traceability mandates that favor established supply chains with certified origination documentation.
- PVC:Plasticized vinyl films with soft-touch coatings and metallic overprint compatibility anchor European graphic arts finishing. REACH phthalate restrictions force reformulation cycles that extend raw material qualification timelines, compressing addressable margin pools for converters lacking in-house polymer compounding capabilities.
- BOPP:Oriented polypropylene with heat-sealable coextrusion layers serves high-volume food and confectionery wrapping where moisture barrier properties outweigh optical complexity.
- Paper:Saturated cellulose substrates with tactile varnish overlays occupy invitation and premium stationery segments sensitive to substrate rigidity and edge-curl resistance.
Polyester holds the largest share; momentum sits with BOPP as mono-material recyclability claims gain traction in French and Italian cosmetic packaging procurement.
Application:
Cost tier stratification separates commodity protective lamination from value-added embellishment, with premium finishing commanding 3-4x substrate cost multiples justified by shelf differentiation metrics.
- Graphic Arts:Book covers, annual reports, and marketing collateral requiring scuff-resistant tactile coatings and spot holographic accents. North American short-run printers are adopting electron-beam-cured inkjet-compatible textures to offer embossed-feel finishes without fixed tooling investments.
- Packaging:Folding cartons, labels, and flexible pouches integrating iridescent and holographic effects for cosmetics and luxury goods. Duty-free retail channels in Germany and France are expanding holographic finish specifications to differentiate shelf presence.
- Automotive:Interior trim films with metallic deposition and abrasion-resistant topcoats for dashboard and door panel applications.
- Construction:Decorative surfacing films for architectural panels and furniture laminates requiring UV stability and chemical resistance.
Packaging commands the deepest margin pools; graphic arts exhibits the steepest expansion trajectory as digital workflow integration collapses minimum order thresholds.
End User:
Customer type determines whether procurement flows through converter intermediaries or direct substrate specification, with brand owner sustainability scorecards consolidating supplier relationships among vertically integrated film manufacturers.
- Printing Companies:Commercial and specialty converters operating thermal and UV lamination equipment, increasingly pressured by carbon footprint disclosure requirements from cosmetics and luxury goods brand owners.
- Manufacturers:Consumer goods producers with captive finishing operations or toll-coating arrangements, concentrated in German industrial corridors around Stuttgart.
- Retailers:Private-label packaging managers specifying decorative laminates for house-brand cosmetics and premium food lines.
- Designers:Creative agencies and brand consultants influencing substrate selection through specification authority over visual identity systems.
Printing companies represent the largest procurement volume; manufacturers are gaining share fastest as backward integration into finishing displaces outsourced converter relationships.
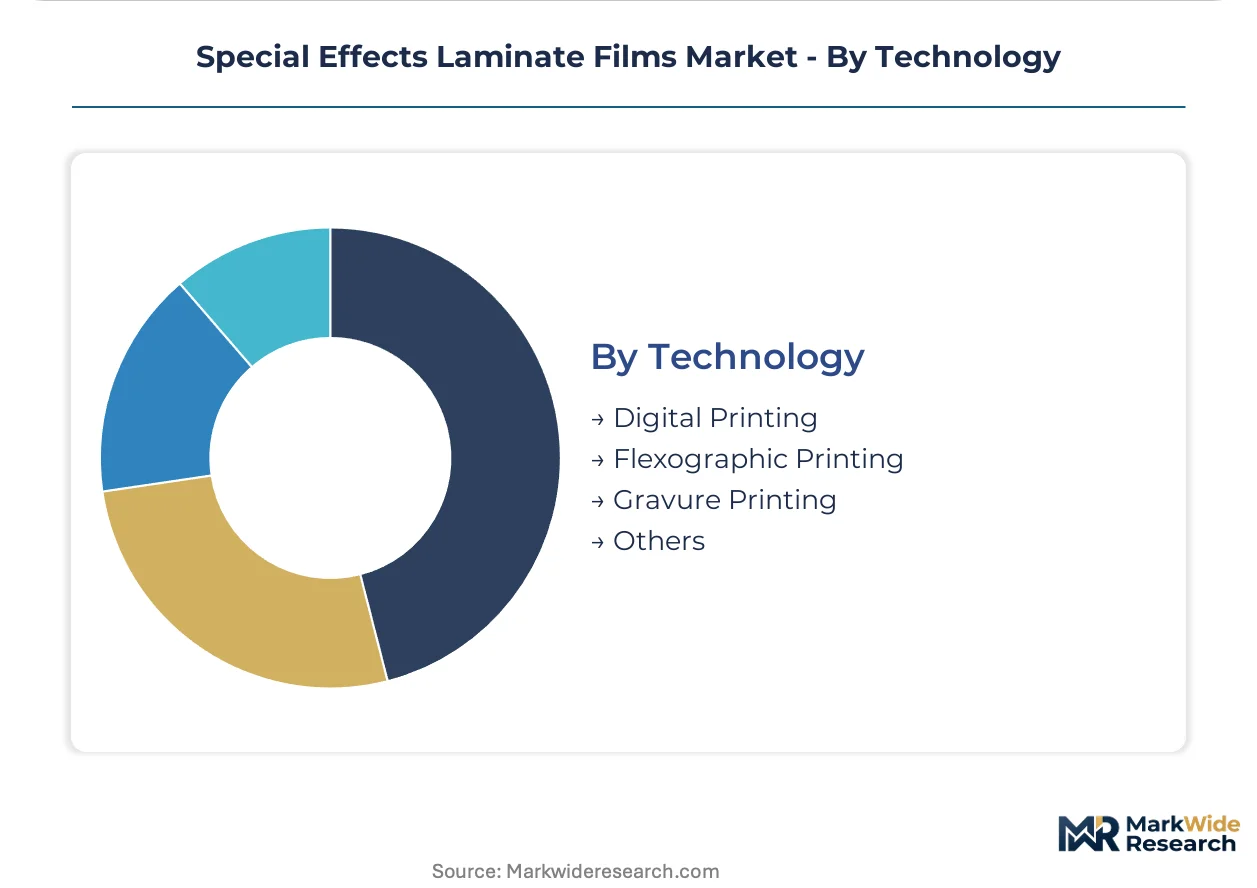
Technology:
Volume concentration in long-run gravure and flexographic workflows is fragmenting under pressure from short-run personalization demand, with digital print compatibility emerging as the decisive substrate qualification criterion.
- Digital Printing:Inkjet and electrophotographic systems with UV-curable or aqueous inksets requiring surface energy-matched laminates for adhesion and rub resistance. The technology is collapsing minimum order thresholds for embellished packaging, fragmenting demand into micro-batches previously uneconomical for holographic tooling.
- Flexographic Printing:Central impression cylinder presses with water-based or solvent ink systems for medium-run label and flexible packaging production.
- Gravure Printing:Engraved cylinder rotogravure for high-volume publication and decorative laminate applications with consistent ink film weights.
- Others:Screen printing and hybrid analog-digital workflows for specialty tactile and metallic effects.
Gravure retains the largest installed base; digital printing is climbing the fastest as converter investment pivots toward agile embellishment capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity toward commodity BOPP laminates, while German and French cosmetics brands absorb substantial premiums for holographic PET with certified origination documentation.
Germany
Premium print finishing houses cluster around Düsseldorf and Stuttgart, driving concentrated procurement of 23-micron holographic PET for luxury cosmetics packaging. The EU Packaging and Packaging Waste Regulation tightens material traceability mandates, accelerating converter investment in blockchain-tracked substrates. Stuttgart industrial corridors host manufacturers with captive finishing operations displacing outsourced converter relationships.
United States
North American short-run printers adopt electron-beam-cured inkjet-compatible textures for book covers and invitations, collapsing turnaround from weeks to days. EPA volatile organic compound restrictions on solvent-based adhesive lamination pull technical investment toward UV-cured coating systems. California SB 54 extended producer responsibility frameworks incentivize mono-material recyclable laminates with decorative functionality.
France
Duty-free retail channels in Paris and Nice expand holographic finish specifications to differentiate shelf presence in premium beauty segments. Cosmetic packaging managers consolidate laminate procurement among converters with Science Based Targets initiative commitments. Lyon and Marseille converters face disintermediation pressure without verified scope 3 emissions data.
India
CDSCO track-and-trace mandates for export-oriented pharmaceutical generics create demand for tamper-evident holographic laminates with integrated authentication features. Mumbai and Ahmedabad pharmaceutical blister packaging lines source specialized substrates from domestic metallizers. Price compression dominates procurement for commodity food-grade BOPP with basic iridescent effects.
Japan
Master shim origination for diffraction gratings concentrates among optical security firms with electron-beam lithography expertise. METI industrial policy supports closed-loop wastewater recovery systems at origination facilities. Osaka and Nagoya industrial zones retain premium security-grade pattern development capacity as smaller toolrooms exit the market.
Special Effects Laminate Films Market Competitive Landscape
Backward-integrated film manufacturers and specialized optical finishing houses split the market between scale-driven substrate supply and pattern-guarded premium effects. Consolidation pressures concentrate among European holographic tooling providers facing REACH authorization requirements for electroplated master shims. Three archetypes dominate: resin-compounding metallizers controlling BOPP substrate supply, optical security firms with proprietary pattern libraries, and agile North American distributors managing channel access for premium finishes. Competitive moves center on captive resin supply integration and carbon accounting certification to secure multi-year preferred supplier agreements.
Among the named players, Nobelus exemplifies the distribution-centric archetype leveraging North American channel control for premium optical finishes. Derprosa represents European specialists in soft-touch and scuff-resistant formulations anchoring graphic arts positions. Cosmo Films Ltd. occupies the backward-integrated tier through captive resin compounding and metallization capabilities. These three illustrate how substrate chemistry mastery, regional regulatory compliance, and distribution density constitute distinct competitive moats in a fragmenting demand environment.
| Leading Market Players |
|---|
| Nobelus |
| Aqua Aura |
| Vivid Laminating Technologies Ltd |
| Hilton Laminating |
| Derprosa |
| Cosmo Films Ltd. |
| D&K Group, Inc. |
| Flex Films |
| Transilwrap |
| Others |
Value Network & Pricing Analysis
Aluminum deposition cost volatility determines both pricing tier spreads and supply chain shape in special effects laminate films. Vacuum metallization energy intensity exposes margin structures to European natural gas price swings, compressing standard-grade BOPP margins while insulating premium holographic PET through pattern-guarded scarcity.
Pricing Analysis
After-sales service contracts for optical defect remediation and holographic pattern recalibration drive lifetime value for polyester substrate suppliers. Three-tier pricing structure across premium holographic PET, standard metallized BOPP, and economy-grade PVC decorative films reflects certification grade and volume scale differentiation. Cost compression in commodity thermal lamination intensifies because Indian and Southeast Asian buyers exhibit acute price sensitivity toward basic iridescent BOPP. Brand owners in German and French cosmetics segments absorb substantial premiums for certified origination documentation, while pharmaceutical blister packagers in India prioritize authentication features over optical complexity.
Supply Chain Analysis
Contract manufacturing for master shim origination concentrates among electron-beam lithography facilities in Japan, Germany, and Austria with integrated effluent treatment systems. Raw material flows draw from aluminum ingot suppliers, polymer resin compounders, and optical coating chemical specialists. Single-source vulnerability sits with the handful of European and Japanese optical security firms controlling diffraction grating tooling. Distribution runs through specialty packaging converters in cosmetics and luxury goods sectors, with premium print finishing houses clustering around Düsseldorf and Stuttgart.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retirement velocity of master origination engineers with electron-beam lithography expertise exceeds apprenticeship pipeline replenishment, creating a widening capability gap that determines competitive access to security-grade pattern libraries.
For Market Incumbents: Pre-empt talent scarcity by capturing retiring electron-beam lithography engineers through advisory contracts and structured knowledge-transfer programs. Deepen backward integration into resin compounding to offset REACH plasticizer reformulation delays. Defend against agile North American distributors by locking multi-year preferred supplier agreements with Science Based Targets initiative commitments from French and Italian cosmetic brand owners. For New Entrants and Emerging Players: Pursue textile heat-transfer convergence for sublimation-compatible special effects films in apparel and soft-goods decoration channels beyond traditional graphic arts. Target Indian pharmaceutical blister packaging where CDSCO track-and-trace mandates create demand for tamper-evident holographic laminates with integrated authentication features. Lead with digital print compatibility as the decisive substrate qualification criterion for short-run personalization workflows. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation traceability mandates reshape the acquisition landscape toward converters with blockchain-tracked substrate capabilities and certified supply chains. Long-term viability centers on facilities with closed-loop wastewater recovery systems that maintain master origination capacity as REACH authorization requirements exclude smaller toolrooms. The signal to watch is consolidation velocity among European holographic tooling providers facing electroplated master shim reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Cosmo Films Ltd. controls BOPP substrate supply through captive polymer production. |
| Closed-Loop Wastewater Recovery Installation | German and Austrian optical security suppliers maintain REACH-compliant master origination capacity. |
| Digital Print Compatibility Certification | Electron-beam-cured inkjet-compatible textures enable North American short-run printer adoption. |
| Science Based Targets Initiative Alignment | French and Italian cosmetic packaging managers consolidate procurement among verified carbon accounting suppliers. |
| Blockchain-Tracked Substrate Implementation | EU Packaging and Packaging Waste Regulation accelerates converter investment in certified supply chains. |
Research Methodology
Operator-level perspectives from specialty packaging converters, premium print finishing house technical directors, cosmetic brand packaging managers, and optical security firm master origination engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, SEC filings from backward-integrated film manufacturers, and EU regulatory documentation on REACH authorization and Packaging and Packaging Waste Regulation implementation. Bottom-up demand modeling across substrate chemistry tiers triangulated with top-down supply-side capacity assessments.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, application, end user, and technology compatibility. Modeled variables included digital print adoption velocity, regulatory compliance timeline acceleration, and mono-material recyclability transition pace. CAGRs derived from volume-weighted average growth across substrate-technology combinations, with industry-specific inputs incorporating electron-beam lithography capacity constraints and aluminum deposition energy cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in European natural gas pricing, aluminum commodity volatility, or REACH enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding converter capital investment cycles and brand owner sustainability procurement consolidation. Quarterly review of master origination facility closure announcements, CDSCO track-and-trace mandate implementation progress, and California SB 54 extended producer responsibility rulemaking is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Barrier Coatings for Packaging Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Global Stretch and Shrink Film Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Release Coatings Market