
 Global Shrink Films Market | 2026-2036
Global Shrink Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shrink Films Market Foresight
Asset-light leasing models for extrusion equipment are reshaping competitive entry in the shrink films sector, enabling mid-tier converters to scale capacity without heavy balance-sheet commitments. Sealed Air Corporation leverages its global service infrastructure to anchor long-term contracts with food processors and logistics providers. Berry Global Inc. sustains manufacturing scale across multiple polymer platforms, while Mondi plc differentiates through integrated pulp-to-film operations that tighten quality control across the value chain.
Shrink films are thermoplastic polymer sheets engineered to contract tightly around products when exposed to controlled heat, typically achieving 40-70% shrinkage in either single-axis or biaxial orientation depending on resin formulation and stretching protocol during extrusion. These films serve primarily to unitize goods, protect against environmental contamination, and create tamper-evident seals across distribution networks. Polyolefin films lead in food-contact applications due to superior clarity and seal strength, while polyethylene dominates palletizing and bundling where cost efficiency and puncture resistance outweigh optical requirements. EVOH barrier layers represent the fastest-growing structural segment as processors target extended shelf-life packaging for proteins and prepared meals.
The U.S. FDA governs indirect food-additive compliance for shrink films contacting edible products, while the EU REACH framework restricts phthalate plasticizers and mandates substance disclosure across PVC and polyolefin supply chains. China's SAMR enforces GB standards for packaging material safety that exporters must satisfy to access domestic food and pharmaceutical channels. Stakeholders should monitor evolving extended-producer-responsibility schemes and polymer-recycling infrastructure investments, as these will determine which material platforms retain cost-competitive market access across major economies.
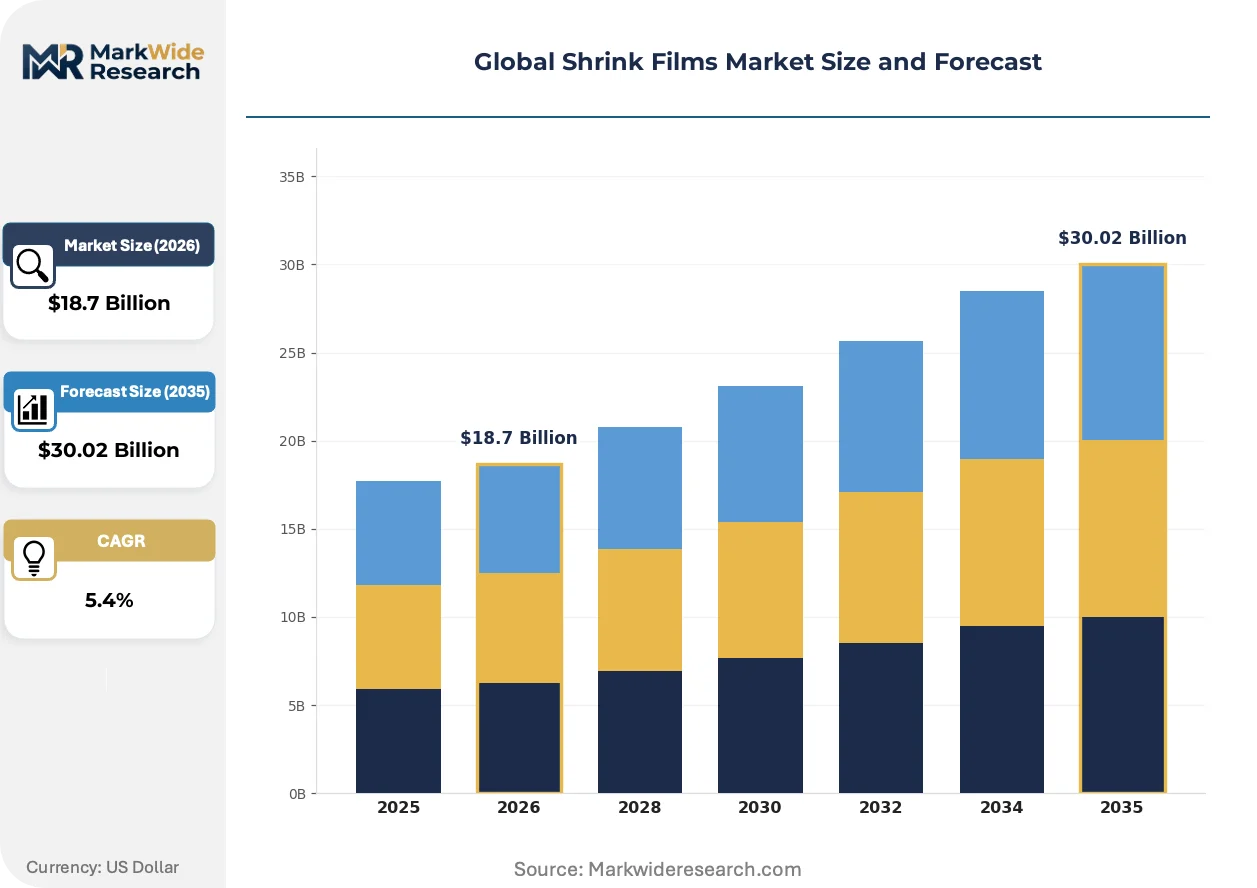
Market Dynamics
Asset-light equipment leasing is compressing capital barriers for mid-tier converters, while the EU Packaging and Packaging Waste Regulation forces rapid material transitions toward recyclable substrates. These dual pressures are fragmenting competitive advantage away from pure scale toward formulation agility and regulatory compliance speed.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for recyclable packaging accelerate bio-based and mono-material film adoption across European food retail chains, creating compliant supplier preference.
- E-commerce fulfillment networks:Automated palletizing and bundling operations in Germany, China, and the United States consume high volumes of polyethylene shrink films for unitization.
- EVOH barrier integration:Multi-layer coextrusion incorporating ethylene vinyl alcohol extends protein and prepared meal shelf life, driving premium film specification in fresh food segments.
Market Restraints
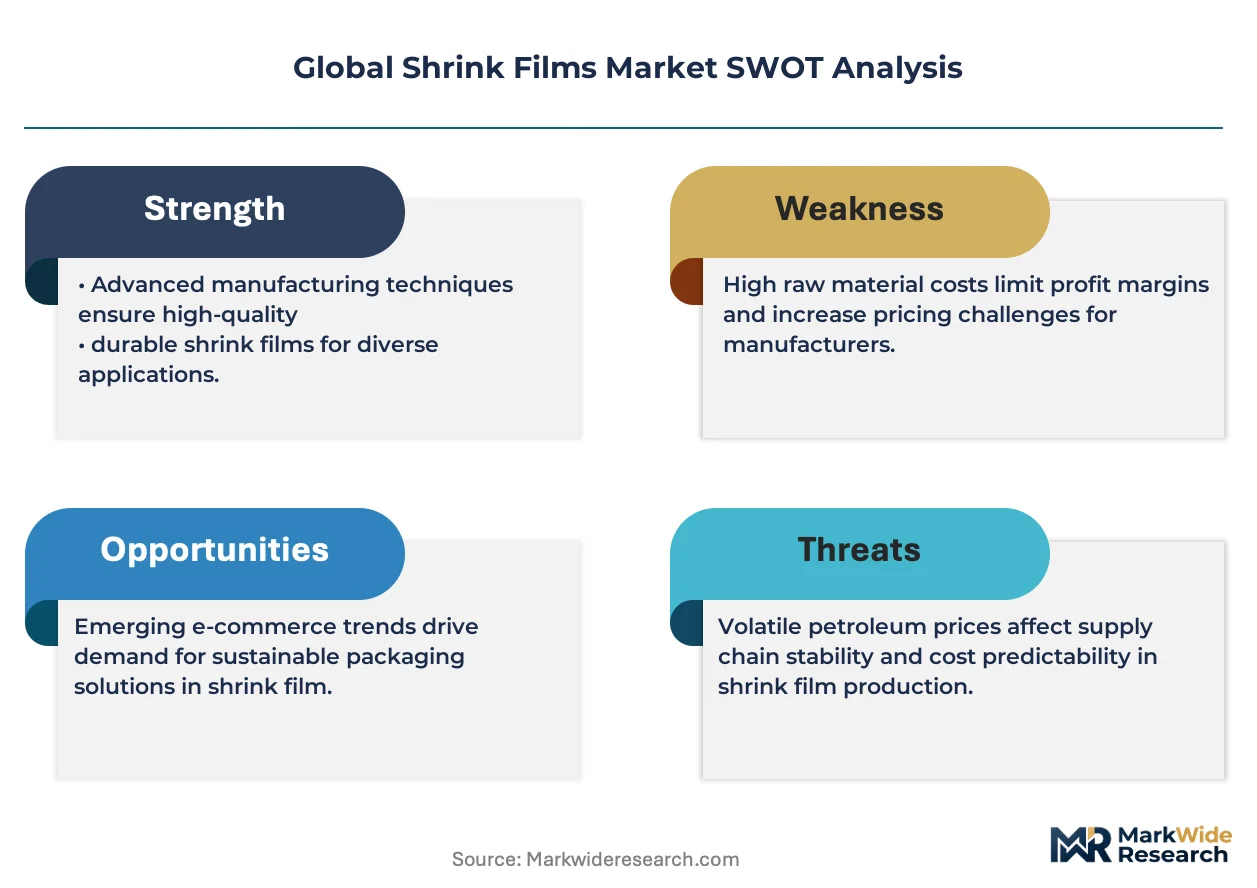
- Polymer feedstock volatility:Ethylene and propylene price swings compress converter margins, particularly for commodity polyethylene formulations used in bulk palletizing.
- Mechanical recycling incompatibility:Multi-layer structures containing EVOH or adhesive tie layers disrupt conventional polyethylene recycling streams, limiting post-consumer circularity claims.
- China GB standard compliance:Exporters face testing and certification costs to satisfy SAMR packaging safety requirements for food and pharmaceutical market access.
Strategic Opportunities
- India food processing expansion:Cold chain infrastructure investment and organized retail growth create demand for shelf-life-extending barrier shrink films in protein and dairy packaging.
- Chemical recycling partnerships:Pyrolysis and depolymerization of mixed plastic waste enables circular feedstock claims for polyolefin shrink films, differentiating premium offerings.
- Digital printing compatibility:Surface-treated shrink films accepting high-resolution inkjet and toner printing support brand customization for short-run e-commerce packaging.
Industry Challenges
- Coextrusion technician scarcity:Specialized knowledge of layer distribution control and gauge uniformity in multi-layer blown film lines limits production ramp speed for new entrants.
- Extended producer responsibility fees:Packaging waste levies in Germany, France, and Italy require operational systems for fee calculation, reporting, and compliance verification.
- Legacy equipment retrofit costs:Converting existing mono-layer extrusion lines to handle five- and seven-layer structures demands substantial capital for die heads, cooling systems, and haul-off modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shrink Films Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Polyethylene, Polyolefin, PVC, Polypropylene, EVOH End Use Industry: Food Packaging, Pharmaceuticals, Consumer Goods, Electronics, Personal Care Application: Bundling, Containment, Labeling, Tamper Protection, Palletizing Packaging Format: Rolls, Bags, Sleeves, Tubes, Custom Shapes |
| Companies Covered | Berry Global Inc., Amcor plc, Sealed Air Corporation, Coveris Holdings, Winpak Ltd., Sigma Plastics Group, AEP Industries Inc., Mondi plc, Intertape Polymer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shrink Films Market Shifts & Advancements
Shrink film technology is converging around sustainability verification and functional performance, with material science advances enabling thinner gauges without sacrificing puncture resistance or optical clarity.
Polyolefin shrink films are hybridizing with bio-based and recycled content streams, blending conventional petroleum-derived resins with mass-balance certified circular feedstocks. Major European retailers and brand owners now specify minimum recycled content thresholds in procurement tenders. This hybridization is compressing the price premium between virgin and sustainable grades, forcing converters to secure certified supply chains or lose contract eligibility.
REACH restrictions on phthalate plasticizers in PVC formulations are accelerating polyolefin substitution in food-contact and toy packaging applications. The industrial consequence is expanded blown film capacity for POF and cross-linked polyolefin grades previously serving narrower premium segments. German and French converters are most affected, responding with rapid formulation certification and customer migration programs to maintain shelf placement.
Brand owners now specify shrink films with embedded digital watermarking or marker technologies to enable automated sortation in recycling facilities. This specification shift disrupts commodity procurement patterns, replacing pure price-based sourcing with technical compliance verification. The change is most visible in European beverage and personal care packaging, where extended producer responsibility schemes reward demonstrably recyclable design.
Global Shrink Films Market Segmentation
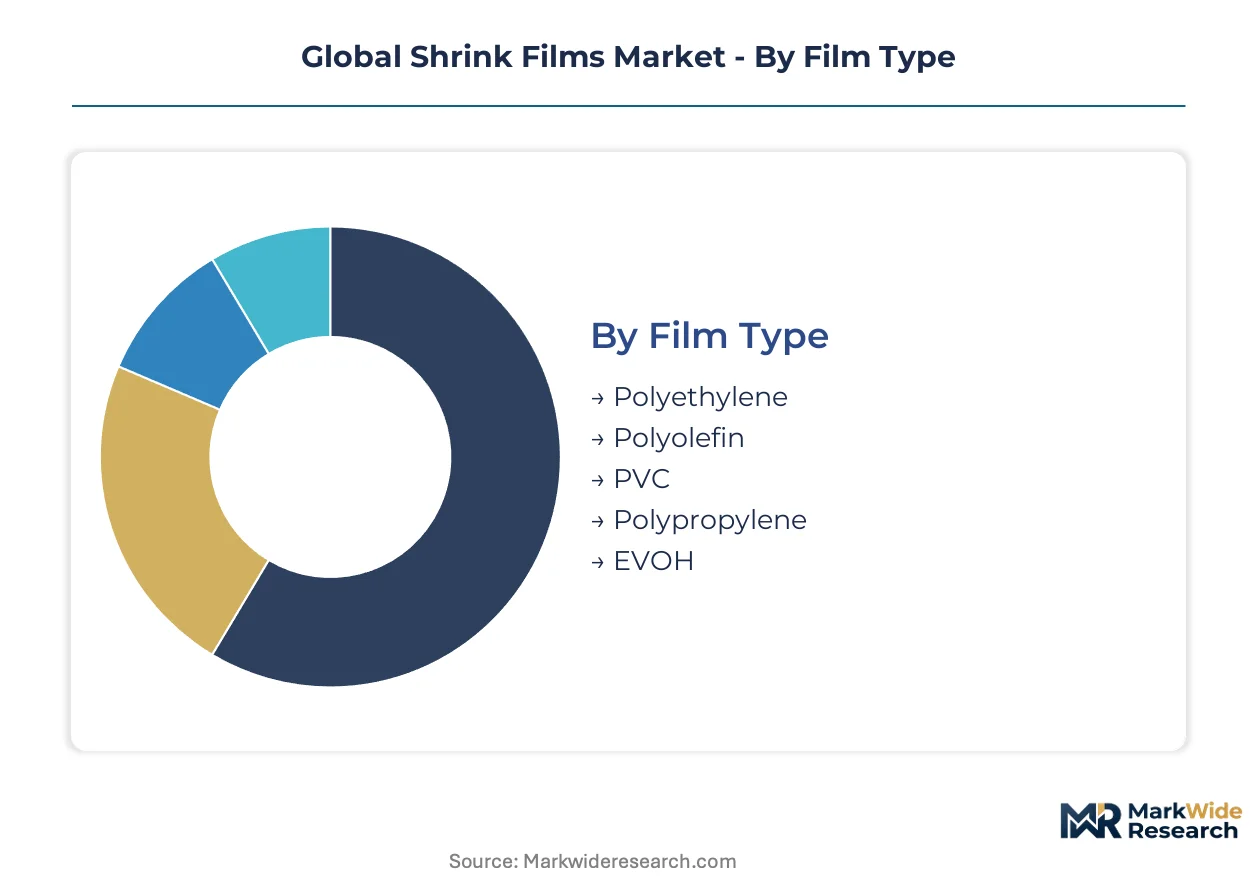
Shrink film segmentation reveals divergent margin structures across material platforms and end-use applications. Film type determines resin cost exposure and recyclability compliance burden, while application specificity drives volume concentration in automated fulfillment versus manual packaging operations.
Film Type:
Polyethylene formulations turn inventory fastest in bulk palletizing contracts, while specialty barrier films carry longer production cycles tied to food-processor qualification protocols.
- Polyethylene:Linear low-density and high-density grades dominate palletizing and bundling for e-commerce fulfillment centers in Germany and the United States. Cost efficiency and puncture resistance outweigh optical requirements in these high-volume applications, though ethylene feedstock volatility compresses converter margins during price spikes.
- Polyolefin:Cross-linked and non-cross-linked polyolefin films deliver superior clarity and seal strength for food-contact applications across European retail chains. REACH compliance requirements for phthalate-free formulations accelerate substitution from PVC in fresh produce and bakery packaging segments.
- PVC:Legacy presence in industrial bundling and construction materials persists where clarity and low-temperature shrink performance justify regulatory compliance costs.
- Polypropylene:Biaxially oriented variants serve high-stiffness applications in printed labels and multi-pack collation for beverage producers.
- EVOH:Ethylene vinyl alcohol barrier layers extend protein and prepared meal shelf life through oxygen transmission rate control.
Polyethylene dominates installed base. EVOH is where expansion concentrates.
End Use Industry:
Customer procurement patterns separate commodity spot buyers from contract-anchored food processors with multi-year formulation lock-ins.
- Food Packaging:Multi-layer coextrusion incorporating EVOH and adhesive tie layers protects proteins, dairy, and prepared meals across cold chain networks in China and the United States. EU Packaging and Packaging Waste Regulation mandates force rapid transitions toward mono-material recyclable structures.
- Pharmaceuticals:High-barrier specifications and tamper-evident requirements demand validated manufacturing processes with batch traceability for FDA and EMA compliance.
- Consumer Goods:Printed shrink sleeves and multi-pack bundling support brand differentiation in household products and toys.
- Electronics:Anti-static formulations and precision gauge control protect sensitive components during distribution.
- Personal Care:Surface-treated films accept high-resolution digital printing for short-run customization in cosmetics and premium toiletries.
Food Packaging commands revenue concentration. Pharmaceuticals is climbing the fastest on margin per kilogram.
Application:
Automation intensity separates high-throughput palletizing from labor-intensive manual bundling operations.
- Bundling:Multi-pack collation for beverages and household products consumes polyethylene and polyolefin films in high-speed wrapping equipment deployed across German and Chinese manufacturing plants.
- Containment:Unitization of irregular shapes in furniture and appliance distribution demands high-tear resistance and controlled shrink force.
- Labeling:Shrink sleeve labels conform to contoured containers in personal care and beverage segments, replacing adhesive labels for 360-degree graphics coverage.
- Tamper Protection:Banding and cap seals verify product integrity for pharmaceuticals and food items with regulatory compliance requirements.
- Palletizing:Automated stretch hood and shrink wrap systems unitize pallet loads for warehouse distribution and export containerization.
Palletizing anchors volume throughput. Labeling is gaining share fastest on premium decoration demand.
Packaging Format:
Converter equipment configuration determines format specialization, with blown film lines optimized for rolls versus bag-making machinery for finished pouches.
- Rolls:Master rolls for downstream converting and in-house packaging operations at food processors and logistics providers in the United States and China.
- Bags:Pre-formed pouches with sealed bottoms serve manual and semi-automatic packaging lines in small-to-medium enterprises.
- Sleeves:Pre-cut bands for tamper-evident applications and multi-pack bundling in beverage and consumer goods.
- Tubes:Continuous seamless cylinders for form-fill-seal equipment in high-speed food packaging operations.
- Custom Shapes:Die-cut and pre-formed configurations for irregular product geometries in electronics and industrial components.
Rolls dominate converter feedstock. Sleeves is where specification premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-format retail and e-commerce fulfillment networks concentrate shrink film procurement in Germany, China, and the United States, where automated palletizing and bundling operations drive polyethylene and polyolefin consumption.
United States
Amazon and Walmart distribution centers in Texas and California consume massive polyethylene volumes for pallet unitization. FDA indirect food-additive compliance governs films contacting edible products. Chicago-area converters supply barrier-grade polyolefins to Midwest meat processors extending protein shelf life.
Germany
Aldi and Lidl retail chains mandate recyclable mono-material packaging from suppliers. Extended producer responsibility fees under the Packaging Act require operational compliance systems. The Rhine-Ruhr industrial corridor hosts blown film specialists serving automotive parts bundling and chemical logistics.
China
JD.com and Alibaba fulfillment networks in the Yangtze River Delta drive shrink film demand for e-commerce parcel consolidation. SAMR enforces GB standards for packaging material safety in food and pharmaceutical channels. Shenzhen converters supply electronics manufacturers with anti-static formulations for component protection.
India
Reliance Retail and BigBasket expansion creates demand for shelf-life-extending barrier films in protein and dairy packaging. FSSAI regulations govern food-contact material safety for organized retail supply chains. Maharashtra's Thane-Bhiwandi industrial belt hosts emerging blown film capacity serving Mumbai's cold chain infrastructure.
Japan
Convenience store chains Lawson and 7-Eleven specify high-clarity polyolefin films for prepared meal packaging. METI promotes plastic resource circulation targets affecting material selection. The Chubu region around Nagoya concentrates precision film converters serving automotive and electronics OEMs.
Global Shrink Films Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three tiers. Integrated multinational converters anchor long-term contracts with food processors and logistics providers through global service infrastructure. Regional specialists capture share in premium barrier formulations and digital-print-compatible surfaces. Competitive moves concentrate on formulation agility for regulatory compliance and equipment leasing partnerships that compress capital barriers for mid-tier converters.
Among the integrated multinational tier, Berry Global Inc., Sealed Air Corporation, and Mondi plc exemplify scale-driven positioning. Berry Global sustains manufacturing breadth across multiple polymer platforms. Sealed Air leverages service infrastructure to anchor contractual relationships. Mondi represents integrated pulp-to-film operations that tighten quality control. These three occupy positions that regional specialists challenge through formulation specialization and faster regulatory response.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor plc |
| Sealed Air Corporation |
| Coveris Holdings |
| Winpak Ltd. |
| Sigma Plastics Group |
| AEP Industries Inc. |
| Mondi plc |
| Intertape Polymer Group |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr industrial corridor anchors European polyolefin capacity, where blown film specialists leverage proximity to Aldi and Lidl procurement headquarters to command premium pricing for REACH-compliant formulations. This geographic concentration creates asymmetric power dynamics: converters within 200 kilometers of Düsseldorf capture specification premiums, while distant competitors absorb logistics penalties or concede margin.
Pricing Analysis
Cost-plus contracts with ethylene indexation dominate polyethylene palletizing agreements, tying converter margins to feedstock volatility rather than value capture. Price differentiation separates EVOH barrier grades from commodity bundling films based on oxygen transmission certification and food-processor qualification status. Pricing pressure stems from asset-light leasing models that compress capital barriers and expand spot-market supply. E-commerce fulfillment centers exhibit highest price sensitivity, accepting clarity trade-offs for puncture resistance, while pharmaceutical buyers prioritize batch traceability over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among German, Chinese, and American blown film specialists with dedicated five-layer and seven-layer coextrusion lines. Raw material sourcing draws from ethylene crackers in Texas, naphtha-fed complexes in Rotterdam, and coal-to-olefins operations in Ningbo. Single-source vulnerability persists for EVOH resin, where Kuraray and Mitsubishi Chemical anchor global supply. Distribution runs through master roll shipments to downstream converters, with just-in-time delivery contracts penalizing inventory carrying costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Aldi and Lidl's harmonized recyclable packaging mandates, which force supplier consolidation as smaller converters forfeit contract eligibility. This retail procurement consolidation fragments legacy volume-based competitive advantage.
For Market Incumbents: Build formulation agility moats through rapid REACH compliance certification and mono-material structure development. Berry Global and Sealed Air should anchor backward integration into bio-based resin supply chains to defend against feedstock volatility. Securing long-term service contracts with JD.com and Amazon fulfillment networks locks out regional challengers lacking global logistics infrastructure. For New Entrants and Emerging Players: India's Thane-Bhiwandi corridor offers underpenetrated cold chain infrastructure where Reliance Retail and BigBasket procurement lacks qualified barrier film suppliers. Target protein and dairy packaging with EVOH-integrated coextrusion capabilities absent in domestic converters. Partner with European equipment lessors to bypass capital intensity and accelerate SAMR GB standard certification for pharmaceutical channel access. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Packaging and Packaging Waste Regulation enforcement will displace non-compliant capacity faster than replacement supply emerges. Acquire mid-tier converters with certified multi-layer production and established food-processor relationships. Monitor chemical recycling partnership announcements as inflection signals for circular feedstock cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | Secures mass-balance certified feedstock for Aldi and Lidl compliance mandates. |
| Multi-Layer Coextrusion Capacity Expansion | Captures EVOH barrier premiums from Midwest meat processors and Yangtze Delta cold chains. |
| Chemical Recycling Partnership | Enables circularity claims for polyolefin films under extended producer responsibility schemes. |
| Digital Print Surface Treatment Development | Supports short-run customization for cosmetics and premium toiletries in European personal care. |
| Equipment Leasing Program Launch | Compresses capital barriers for mid-tier converters targeting India food processing expansion. |
Research Methodology
Desk research of trade association filings, customs records, and SEC 10-K disclosures preceded structured interviews with blown film plant managers, food processor procurement leads, retail category buyers, and chemical distribution channel partners. Primary fieldwork validated secondary estimates through bottom-up capacity assessments and top-down demand triangulation across polymer platforms and end-use segments.
Forecast assumptions held fixed the EU Packaging and Packaging Waste Regulation enforcement trajectory and SAMR GB standard compliance costs, while varying ethylene feedstock price scenarios and chemical recycling capacity buildout timing. The analytical framework modeled film type, end-use industry, application method, and packaging format dimensions across the projection horizon. CAGRs derived from volume-weighted average growth rates applied to segment-level baseline estimates, incorporating EVOH barrier adoption curves and e-commerce fulfillment network expansion.
Practitioners should monitor polymer feedstock volatility, extended producer responsibility fee escalations, and chemical recycling offtake agreement announcements for early signals of forecast revision. Quarterly review of SAMR certification backlogs, REACH substance restriction updates, and Amazon-Walmart distribution center buildout schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
Tray Liners Market