
 Metalized Barrier Film Packaging Market | 2026-2036
Metalized Barrier Film Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Metalized Barrier Film Packaging Market Foresight
Aftermarket technical service and film reclamation is rewriting margin capture across the value chain. Amcor leverages captive metallization lines and recycling infrastructure to sustain pricing power in European pharmaceutical contracts. Toray Plastics anchors North American demand through ultra-high-barrier PET film specialization for electronic moisture protection. Jindal Poly Films dominates South Asian flexible packaging with backward integration into BOPET resin production.
Metalized barrier film packaging denotes flexible or rigid substrates—typically PET, PP, or PE—vacuum-coated with aluminum or oxide layers measuring 30–100 nanometers, engineered to block oxygen, moisture, and UV transmission below 0.1 cc/m²/day. Flexible film leads volume due to its dominance in snack and confectionery wrap, though laminated film commands premium margins in pharmaceutical blister applications where thermoformability and seal integrity must satisfy FDA 21 CFR 177.1390 compliance. Electronic packaging represents the fastest-growing application segment as semiconductor manufacturers specify ultra-low WVTR films for wafer-level chip scale packaging.
The FDA regulates direct food-contact barrier films under 21 CFR 177, while REACH restricts phthalate plasticizers and heavy-metal pigments in European-sourced films, forcing reformulation of adhesive laminates. EMA's Annex 1 revisions on sterile medicinal product packaging are elevating demand for certified cleanroom-grade metalized films with validated particulate and bioburden controls. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, which will determine whether metallized multi-layer structures qualify for circular-economy labeling or face disposal surcharges.
Market Dynamics
EU Green Deal compliance deadlines are forcing metallized film producers to eliminate halogenated chemistries and redesign multi-layer structures for mechanical recycling compatibility, compressing formulation timelines while elevating R&D budgets.
Growth Catalysts
- Cold-chain biologics expansion:Pharmaceutical manufacturers are specifying ultra-high-barrier metalized films for temperature-sensitive mRNA therapies, with EMA Annex 1 revisions mandating validated particulate controls for sterile medicinal packaging.
- Semiconductor wafer packaging:Electronics manufacturers specify ultra-low WVTR metalized films for chip-scale packaging as node sizes shrink below 7nm, concentrating demand in cleanroom-grade film categories.
- REACH substitution mandates:ECHA restrictions on phthalate plasticizers and heavy-metal pigments are accelerating reformulation of adhesive laminates toward halogen-free barrier chemistries.
Market Restraints
- Aluminum vapor deposition capacity concentration:Vacuum metallization equipment requires specialized vacuum chambers and roll-to-roll handling systems, with production gravity centering on German and Japanese equipment suppliers facing 18-month order backlogs.
- Multi-layer recycling incompatibility:PET-aluminum-PE laminates lack established mechanical recycling streams under EU Green Deal circular-economy frameworks, exposing producers to extended producer responsibility surcharges in France and Italy.
- Oxide barrier performance gaps:Silicon oxide and aluminum oxide coatings achieve inferior oxygen barrier versus metallized aluminum at equivalent thickness, limiting substitution in pharmaceutical blister applications requiring sub-0.1 cc/m²/day performance.
Strategic Opportunities
- Pharmaceutical contract packaging clusters:Germany's Rhineland and Bavaria regions host dense concentrations of FDA- and EMA-certified contract packers seeking qualified cleanroom-grade film suppliers with validated bioburden documentation.
- Mechanical recycling infrastructure:Advanced delamination and aluminum recovery processes are enabling closed-loop reclamation of post-industrial metallized scrap, with EU Green Deal funding accelerating pilot facilities in the Netherlands.
- Electronic moisture protection:5G base station and automotive radar module manufacturers are specifying metalized barrier pouches for component shipping, creating specification pull from semiconductor capital equipment supply chains.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 Class 7 film slitting and conversion requires 12-18 month validation cycles with pharmaceutical customers, compressing product launch windows for new film constructions.
- Adhesive laminate reformulation complexity:Eliminating halogenated flame retardants while maintaining seal integrity and thermoformability demands concurrent redesign of substrate, coating, and adhesive layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metalized Barrier Film Packaging Market |
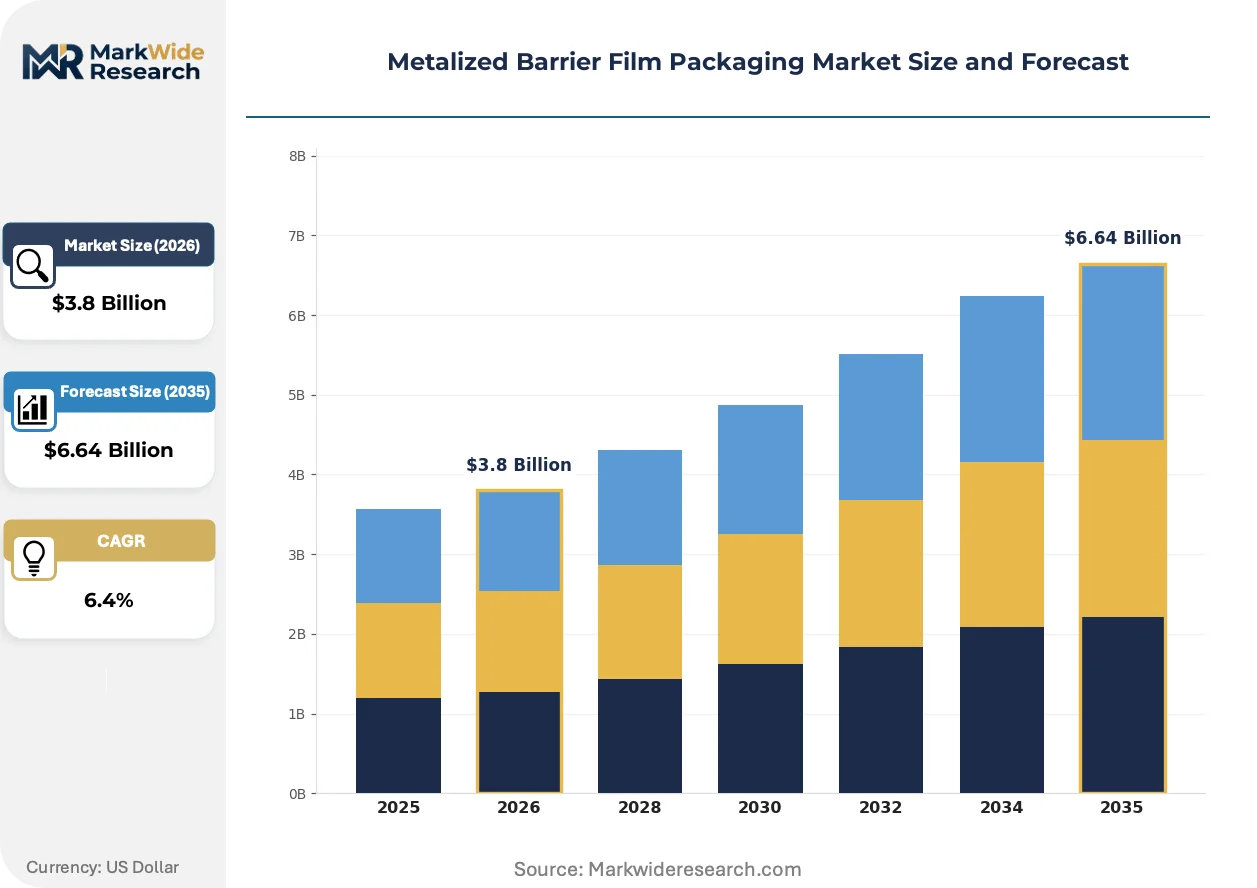
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Film, Rigid Film, Laminated Film, Coated Film Application: Food Packaging, Pharmaceutical Packaging, Electronic Packaging, Industrial Packaging Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales End User: Manufacturers, Distributors, Retailers, Exporters |
| Companies Covered | Amcor, Toray Plastics, Jindal Poly Films, Uflex, Cosmo Films, Berry Global, Mondi Group, Polyplex, Taghleef Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metalized Barrier Film Packaging Market Shifts & Advancements
Digital process control and inline quality verification are compressing defect rates and enabling lot-level traceability demanded by pharmaceutical and electronics customers. These shifts are restructuring supplier qualification protocols and capital allocation priorities.
Inline spectroscopic thickness monitoring is digitizing vacuum metallization processes, replacing offline抽样 testing with real-time aluminum deposition control. Pharmaceutical contract packers in Germany and Switzerland are mandating this capability for supplier qualification. The technology is digitizing quality documentation workflows and compressing batch release timelines from days to hours.
EMA Annex 1 revisions on sterile medicinal product packaging are elevating particulate and bioburden testing requirements for primary barrier materials. Film converters must implement validated environmental monitoring and personnel gowning protocols. The regulation is most affecting suppliers to parenteral drug packaging segments, who are consolidating supplier bases toward certified cleanroom operators.
Specification-driven procurement is consolidating pharmaceutical film buying around qualified suppliers with validated change-control procedures. Large molecule drug manufacturers are reducing approved vendor lists from 12-15 to 3-4 strategic partners. This concentration is most visible in Germany and Switzerland, where contract packaging clusters favor integrated film-converter relationships over spot purchasing.
Metalized Barrier Film Packaging Market Segmentation
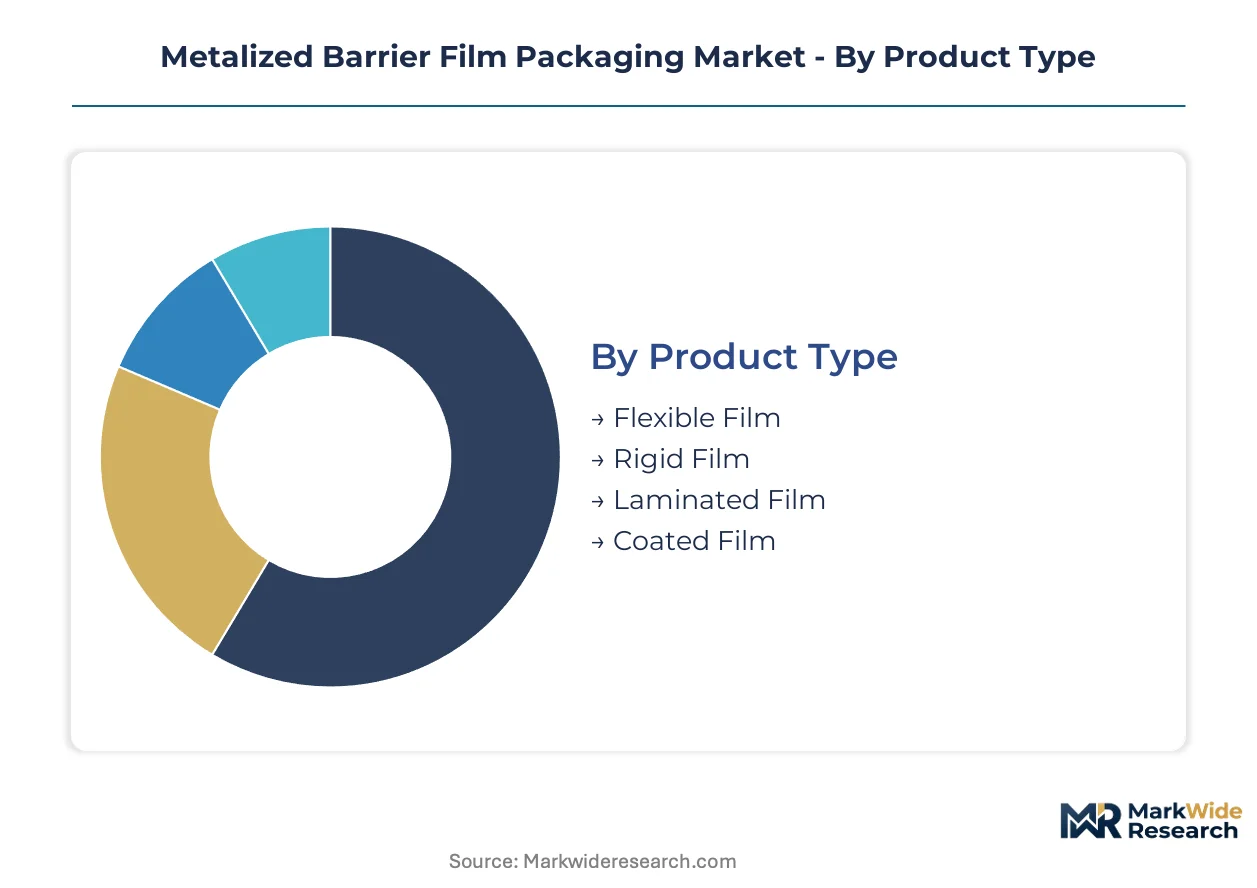
Segmentation in metalized barrier film packaging reveals how substrate engineering, barrier performance tiers, and regulatory compliance requirements fragment demand across pharmaceutical, electronics, and food end-uses. Understanding these divisions exposes where formulation investments concentrate and which conversion technologies command qualification premiums.
Product Type:
Flexible film spans snack wrap, pharmaceutical pouches, and electronic moisture barriers, while rigid and laminated variants serve thermoformed blister packs and high-integrity sterile applications.
- Flexible Film:PET, PP, or PE substrates vacuum-coated with 30–100 nanometer aluminum layers achieve oxygen transmission below 0.1 cc/m²/day. Demand concentrates in German pharmaceutical contract packaging clusters where EMA Annex 1 compliance mandates validated particulate controls for sterile medicinal products.
- Laminated Film:Multi-layer PET-aluminum-PE constructions deliver thermoformability and seal integrity for FDA 21 CFR 177.1390 pharmaceutical applications. Electronics manufacturers in Japan and South Korea specify these for ultra-low WVTR wafer-level chip scale packaging as semiconductor node sizes shrink below 7nm.
- Rigid Film:Thermoformable APET or CPET bases with metallized barriers serve modified atmosphere food trays and medical device blisters requiring dimensional stability.
- Coated Film:Silicon oxide and aluminum oxide vapor-deposited layers offer halogen-free alternatives, though oxygen barrier performance trails metallized aluminum at equivalent thickness.
The dominant share belongs to Flexible Film, while Laminated Film is closing the gap fastest.
Application:
End-use differentiation tracks barrier performance thresholds, with pharmaceutical and electronic segments imposing the strictest transmission specifications and cleanroom handling protocols.
- Pharmaceutical Packaging:Cold-chain biologics and mRNA therapies drive ultra-high-barrier specifications. EMA Annex 1 revisions mandate validated bioburden and particulate documentation, compressing supplier qualification to 3-4 strategic partners per large molecule manufacturer.
- Electronic Packaging:Semiconductor wafer shipping and 5G base station component protection require cleanroom-grade films with inline spectroscopic thickness monitoring. Japanese and South Korean electronics manufacturers anchor this segment's specification pull.
- Food Packaging:Snack and confectionery wrap dominates volume, with EU Green Deal compliance forcing redesign of multi-layer structures for mechanical recycling compatibility.
- Industrial Packaging:Chemical and agricultural barrier applications emphasize cost-optimized metallized PE constructions with moderate oxygen and moisture protection.
Food Packaging retains volume leadership, though Electronic Packaging exhibits the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects order scale, certification requirements, and the need for technical service integration in pharmaceutical and electronics procurement.
- Direct Sales:Pharmaceutical and electronics manufacturers source through qualified supplier relationships with validated change-control procedures, bypassing intermediaries for cleanroom-grade film categories.
- Wholesale:Food and industrial packaging buyers leverage distributors for volume aggregation and regional logistics, particularly in South Asian flexible packaging markets.
- Online Retail:Standardized metallized film grades for small-batch industrial and artisanal food producers, with limited penetration in certified pharmaceutical segments.
- Offline Retail:Local film converters and packaging suppliers serving fragmented food service and specialty chemical end-uses.
Direct Sales commands the premium tier, while Wholesale handles the highest transaction volumes.
End User:
User type determines specification authority, with manufacturers holding primary influence over barrier performance requirements and certification documentation.
- Manufacturers:Pharmaceutical drug makers and semiconductor fabricators define material specifications and approved vendor lists, driving consolidation toward integrated film-converter relationships.
- Distributors:Regional packaging material wholesalers manage inventory and logistics for food and industrial end-uses, with limited influence on technical specifications.
- Retailers:Private-label food brands and pharmacy chains specify barrier performance indirectly through contract packer agreements.
- Exporters:Cross-border traders of packaged goods must reconcile FDA, REACH, and destination-country regulations, favoring multi-certified film suppliers.
Manufacturers control specification authority, while Distributors mediate the broadest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes metalized barrier films predominantly for pharmaceutical sterile packaging, while Japan and South Korea anchor electronics-grade demand for semiconductor protection. The United States splits consumption across food flexible packaging and emerging biologics cold-chain applications.
Germany
Rhineland and Bavaria host dense pharmaceutical contract packaging clusters demanding EMA Annex 1-compliant cleanroom-grade films. REACH restrictions on halogenated chemistries force reformulation of adhesive laminates toward recyclable barrier structures. Munich-based film converters are consolidating supplier relationships from 12-15 vendors to 3-4 strategic partners per large molecule manufacturer.
United States
FDA 21 CFR 177.1390 compliance drives premium laminated film adoption for pharmaceutical blister packs, while snack food wrap dominates flexible film volume. California and New York state-level extended producer responsibility laws are determining whether metallized multi-layer structures qualify for circular-economy labeling. The Pacific Northwest is piloting advanced delamination facilities for post-industrial metallized scrap recovery.
Japan
Semiconductor manufacturers specify ultra-low WVTR films for wafer-level chip scale packaging as node sizes shrink below 7nm. METI industrial standards govern electronic packaging material specifications, concentrating demand in cleanroom-grade categories. Nagoya and Osaka industrial corridors are deepening vacuum metallization equipment partnerships with German and Japanese machinery suppliers facing 18-month order backlogs.
South Korea
5G base station and automotive radar module manufacturers are specifying metalized barrier pouches for component shipping, creating specification pull from semiconductor capital equipment supply chains. MFDS pharmaceutical packaging regulations align with EMA standards for sterile medicinal products. Seoul-Incheon manufacturing clusters are integrating inline spectroscopic thickness monitoring for supplier qualification by Japanese electronics customers.
India
Flexible packaging for snack and confectionery dominates volume, with BOPET resin backward integration supporting cost-competitive metallized film production. CDSCO pharmaceutical regulations are elevating documentation requirements for primary barrier materials used in domestic drug packaging. Gujarat and Maharashtra industrial belts are expanding vacuum metallization capacity to serve South Asian export markets.
Metalized Barrier Film Packaging Market Competitive Landscape
Capability concentration sits with integrated film-converter specialists; scale advantage sits with diversified packaging conglomerates. The vendor base separates into three tiers: multinational material science groups with captive metallization lines, regional flexible packaging specialists with backward resin integration, and equipment-dependent toll coaters serving spot markets. Consolidation is accelerating through pharmaceutical vendor list reduction and EU Green Deal compliance investments.
Among diversified packaging groups, Amcor exemplifies the integrated archetype with European pharmaceutical contract positioning. Toray Plastics occupies a specialist position in North American electronics-grade film categories. Jindal Poly Films represents the regional scale-driven model with South Asian market anchoring. These three patterns illustrate how competitive positioning splits between certification-heavy sterile packaging, specification-driven electronics protection, and volume-optimized flexible food wrap.
| Leading Market Players |
|---|
| Amcor |
| Toray Plastics |
| Jindal Poly Films |
| Uflex |
| Cosmo Films |
| Berry Global |
| Mondi Group |
| Polyplex |
| Taghleef Industries |
| Others |
Supply & Pricing Matrix
German Rhineland metallization clusters command downstream pricing leverage through captive vacuum deposition capacity and qualified pharmaceutical contract relationships. REACH-driven reformulation costs and 18-month equipment backlogs from Japanese machinery suppliers compress margin elasticity for non-integrated converters.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical procurement, with EMA Annex 1-certified cleanroom-grade films commanding premium positioning over spot-market flexible food wrap. Price differentiation hinges on ISO 14644 Class 7 validation status and inline spectroscopic thickness monitoring capability. Cost compression in standard-grade snack packaging intensifies as South Asian BOPET resin integration feeds volume competition. Electronic semiconductor buyers exhibit lowest price sensitivity due to specification-locked vendor lists, while industrial chemical end-users drive aggressive spot-market negotiation.
Supply Chain Analysis
Export control regimes on vacuum metallization equipment from Germany and Japan restrict capacity expansion timelines and concentrate technical sourcing power. Raw material flows draw from Saudi petrochemical feedstock for BOPET resin, Chinese aluminum ingot supply, and South Korean oxide precursor chemicals. Single-source vulnerability runs through specialized roll-to-roll vacuum chamber manufacturers facing extended order backlogs. Distribution runs through direct sales channels for pharmaceutical and electronics qualification, with wholesale aggregators mediating South Asian flexible packaging volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as large molecule drug manufacturers collapse approved vendor lists from 12-15 suppliers to 3-4 strategic partners per therapeutic category.
For Market Incumbents: Entrench positioning through backward integration into BOPET resin production and captive aluminum recovery infrastructure. Oxide barrier substitution threats from halogen-free coating technologies demand concurrent certification maintenance in cleanroom-grade categories. Capacity addition in Bavaria pharmaceutical clusters anchors relationship density with EMA-compliant contract packers. For New Entrants and Emerging Players: Pursue mechanical recycling infrastructure partnerships in Netherlands pilot facilities as EU Green Deal funding accelerates post-industrial scrap reclamation. Electronic moisture protection for 5G base station components represents the most penetrable specification tier, with automotive radar module manufacturers lacking established film supplier relationships. Go-to-market execution should leverage inline quality verification technology as a qualification accelerator against incumbent validation timelines. For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because EMA Annex 1 and FDA 21 CFR compliance create multi-year supplier lock-in with pharmaceutical contract packers. Acquisition targets should display integrated film-converter capabilities with validated bioburden documentation and existing relationships with German Rhineland packaging clusters. The signal to watch is state-level extended producer responsibility law progression in California and New York, which will determine circular-economy labeling eligibility and disposal surcharge exposure for metallized multi-layer structures.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Investment | ISO 14644 Class 7 validation compresses pharmaceutical supplier qualification timelines from months to weeks. |
| Backward Resin Integration | In-house BOPET production anchors cost position against South Asian volume competitors in flexible food wrap. |
| Mechanical Recycling Partnership | EU Green Deal-funded delamination pilots in Netherlands enable closed-loop aluminum recovery from post-industrial scrap. |
| Inline Spectroscopic Monitoring | Real-time deposition control satisfies Japanese electronics manufacturer specifications for wafer-level chip scale packaging. |
| Adhesive Laminate Reformulation | Halogen-free barrier chemistry development addresses REACH substitution mandates while maintaining FDA seal integrity compliance. |
Research Methodology
The analysis maps flexible film, laminated film, rigid film, and coated film sub-sectors, each validated through film converter operations directors, pharmaceutical packaging procurement managers, semiconductor materials engineers, and vacuum metallization equipment specialists. Primary interview intelligence triangulates against customs trade data, EMA Annex 1 guidance documents, FDA 21 CFR filings, and REACH restriction candidate lists. Bottom-up capacity modeling and top-down demand segmentation converge on volume and value estimates.
Assumptions held fixed include current EU Green Deal compliance deadlines, EMA Annex 1 revision implementation timelines, and semiconductor node size progression rates across the analysis window. Segmentation dimensions span product type, application end-use, distribution channel, and geographic regulatory cluster. CAGRs derive from weighted average growth across pharmaceutical cold-chain expansion, electronics moisture protection specification pull, and food packaging volume replacement cycles. Forecast inputs incorporate vacuum metallization equipment order backlogs and aluminum vapor deposition capacity utilization rates.
Sensitivities concentrate around REACH restriction scope expansion, state-level extended producer responsibility law adoption in the United States, and oxide barrier performance breakthroughs that could displace metallized aluminum in sub-0.1 cc/m²/day applications. Cross-checking against pharmaceutical contract packaging cluster capacity announcements and semiconductor capital equipment spending disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Heat Transfer Films Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market