
 Canada Renewable Energy Market | 2026-2036
Canada Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Renewable Energy Market Analysis
CSA Group certification for grid-connected inverters is collapsing the vendor pool to a handful of qualified suppliers. Brookfield Renewable Partners leverages its hydroelectric base to anchor long-term power purchase agreements with provincial utilities. Innergex Renewable Energy specializes in run-of-river hydro and wind hybrids that navigate terrain constraints in British Columbia and Quebec. Canadian Solar controls module supply chains that extend from polysilicon through project development, insulating margins against tariff volatility.
Canada renewable energy encompasses electricity generation from solar photovoltaics, onshore wind, biomass combustion, and run-of-river hydroelectric systems with typical capacity factors ranging from 15% for solar to 35-45% for modern wind turbines, primarily serving grid decarbonization mandates and corporate sustainability targets. Wind technology dominates installed capacity across the Prairie provinces where sustained gust corridors align with transmission trunk lines. Solar deployment accelerates fastest in Alberta's merchant power market where merchant developers exploit peak pricing hours. Utility-scale projects command the deepest capital pools while distributed generation segments attract agricultural and Indigenous community participation through shared ownership structures.
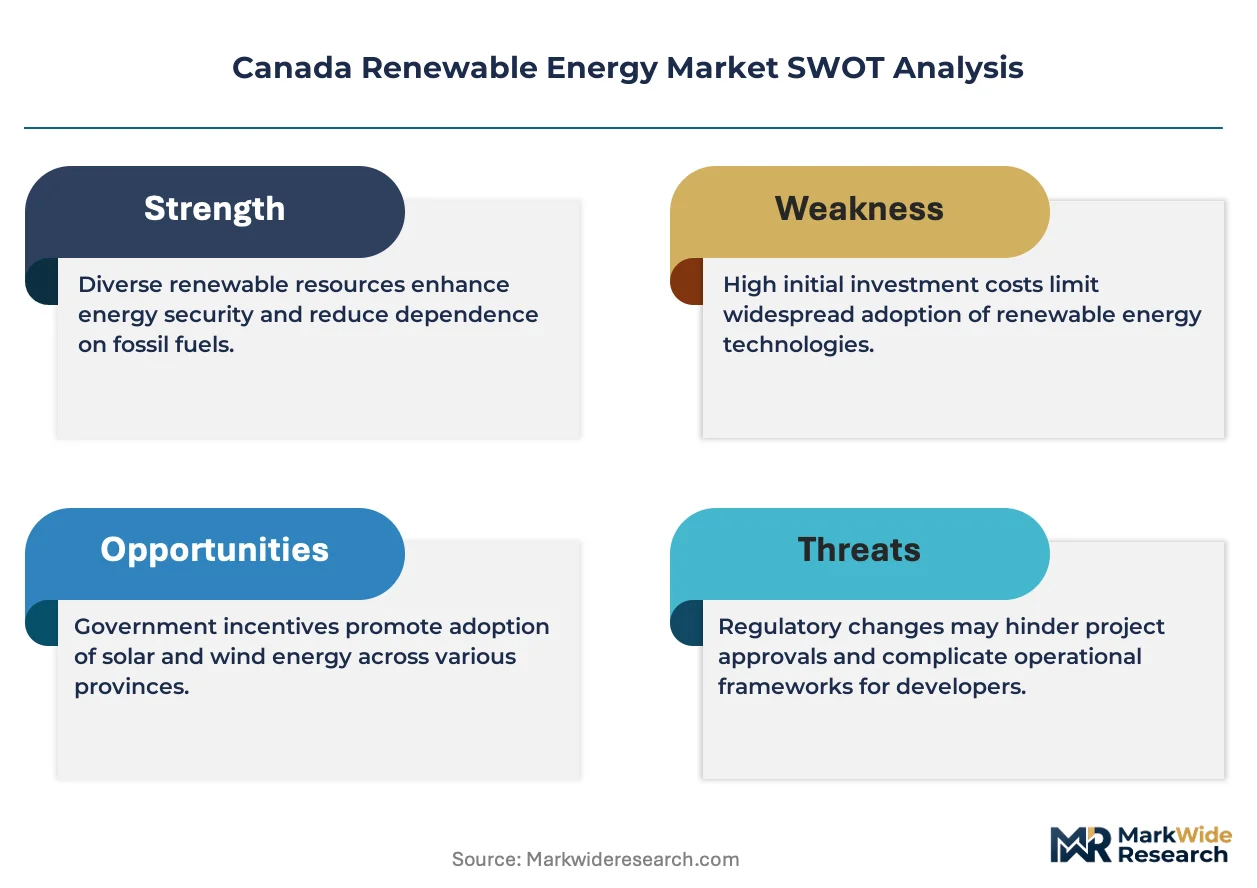
Natural Resources Canada, the Canadian Environmental Assessment Agency, and provincial regulators including the Alberta Utilities Commission shape project timelines through cumulative effects assessment requirements and interconnection queue management. Federal clean electricity regulations and provincial renewable portfolio standards tighten emission intensity thresholds that determine which projects qualify for green bond financing. Stakeholders must monitor interconnection backlogs and evolving Indigenous consultation protocols as these constraints increasingly determine project viability more than technology cost curves.
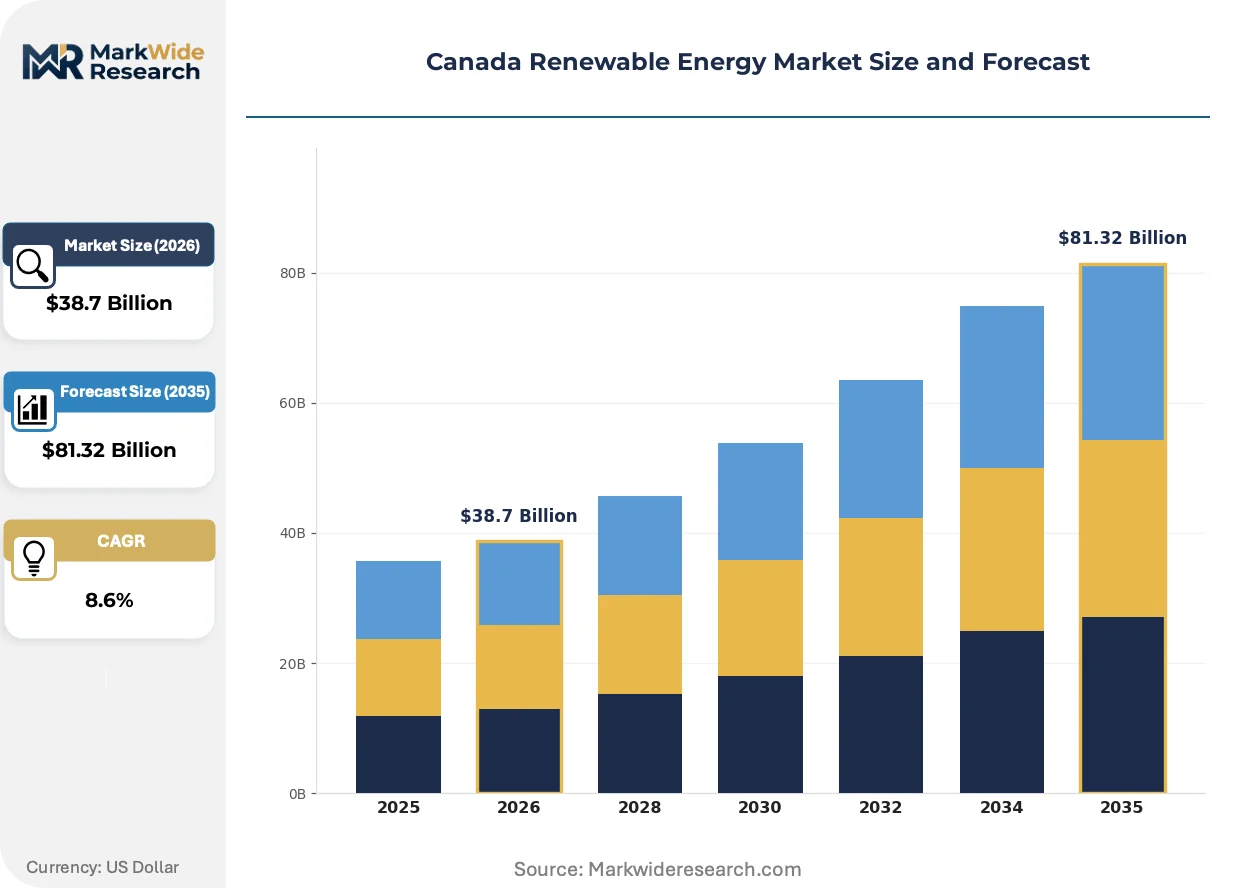
Market Dynamics
Alberta's merchant power market is compressing development timelines as developers chase capture prices during peak demand hours, forcing provincial utilities in Saskatchewan and British Columbia to accelerate procurement schedules to retain load.
Growth Catalysts
- Federal Carbon Pricing:The federal carbon pricing regime escalates operating costs for fossil generators, redirecting capital toward wind and solar assets that qualify for green bond financing under tightened emission intensity thresholds.
- Coal Phase-Out Deadlines:Alberta and Saskatchewan face hard deadlines for coal retirement, creating immediate replacement demand that concentrates procurement activity in the Prairie provinces where transmission trunk lines already exist.
- Corporate Sustainability Targets:Industrial off-takers in mining and oil sands operations are executing direct power purchase agreements to hedge carbon exposure and meet Scope 2 reduction commitments.
Market Restraints
- Interconnection Queue Congestion:Natural Resources Canada and provincial regulators manage cumulative effects assessments that extend project timelines, with backlogs in Alberta and British Columbia now stretching multiple years for grid access.
- CSA Group Certification Bottleneck:Grid-connected inverter certification requirements have collapsed the qualified vendor pool to a handful of suppliers, concentrating supply risk and limiting procurement flexibility for project developers.
- Polysilicon Tariff Volatility:Module supply chains face margin pressure from trade policy uncertainty, though vertically integrated manufacturers with captive polysilicon production maintain cost advantages.
Strategic Opportunities
- Indigenous Community Partnerships:Shared ownership structures for distributed generation projects unlock agricultural and First Nations participation, creating new capital pools outside traditional utility finance.
- Run-of-River Wind Hybrids:Terrain-constrained regions in British Columbia and Quebec favor hybrid configurations that combine run-of-river hydro with complementary wind generation to firm output profiles.
- Alberta Merchant Market Expansion:The province's deregulated power pool rewards flexible dispatch, attracting developers who can optimize solar output against real-time price signals without long-term offtake contracts.
Industry Challenges
- Indigenous Consultation Protocol Evolution:Project viability now depends on navigating evolving duty-to-consult requirements, with inconsistent timelines across provincial jurisdictions creating execution uncertainty.
- Grid Integration Complexity:High renewable penetration in Alberta and Saskatchewan strains balancing authority capabilities, requiring coordinated investment in transmission and storage that outpaces current rate-base mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Renewable Energy Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydro Application: Grid Power, Off-grid Solutions, Heating, Transportation End User: Residential, Commercial, Industrial, Government Deployment: Distributed Generation, Utility-scale, Microgrid, Hybrid Systems |
| Companies Covered | Boralex, Innergex Renewable Energy, Brookfield Renewable Partners, AMP.ENERGY, Northland Power, Canadian Solar, TransAlta Renewables, Enbridge, Algonquin Power & Utilities, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Renewable Energy Market Emerging Trajectories
Technology trajectories and procurement models are diverging across Canada's provincial markets, with merchant exposure in Alberta driving innovation in forecasting and dispatch optimization while regulated utilities elsewhere prioritize cost certainty through long-term contracts.
Bifurcation characterizes solar module procurement as domestic content requirements under the federal Investment Tax Credit clash with cost minimization pressures. Large-scale developers in Alberta are qualifying domestic supply chains to capture full incentives, while distributed projects in rural Quebec and the Maritimes prioritize lowest unit cost through Asian sourcing. The technology stack is bifurcating into premium domestic-tracked arrays versus standard imported fixed-tilt configurations.
The Canadian Environmental Assessment Agency has streamlined federal review timelines for renewable projects under the Impact Assessment Act, compressing the average regulatory phase from thirty-six to twenty-four months for designated projects. This acceleration most benefits utility-scale wind developments in Saskatchewan, where provincial crown utilities now synchronize procurement windows with federal assessment cycles to reduce development risk.
Industrial offtakers are unbundling energy procurement from carbon attribute acquisition, creating parallel markets for physical power and renewable energy certificates. Mining operations in northern Ontario and oil sands facilities near Fort McMurray now contract separately for firming capacity and green tags, with Alberta's merchant pool enabling this separation through transparent hourly pricing. This behavioral shift concentrates in jurisdictions with liquid wholesale markets and established certificate tracking systems.
Canada Renewable Energy Market Segmentation
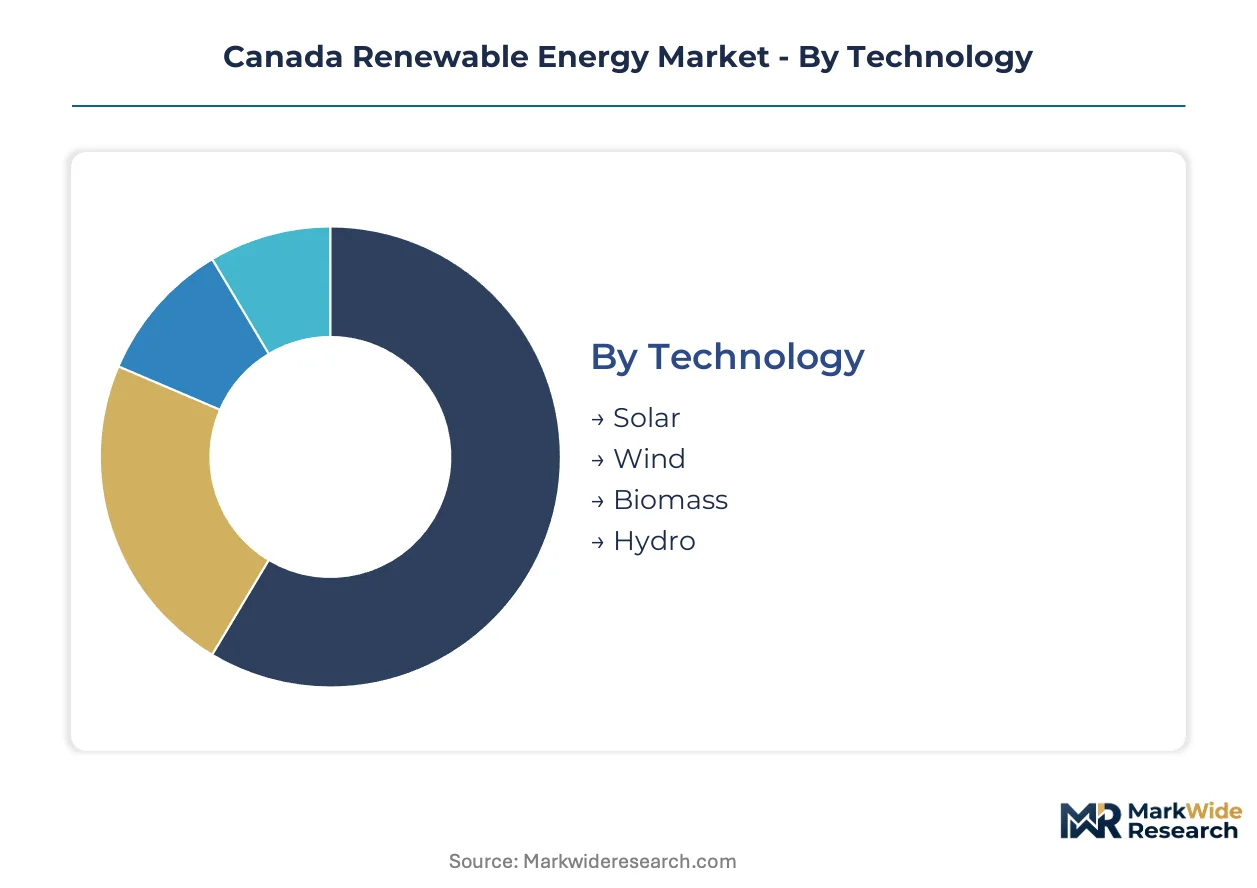
Technology diversity across Canada's provincial markets creates distinct investment profiles, with deployment scale and end-use requirements fragmenting procurement strategies. Regulatory frameworks at both federal and provincial levels segment opportunity sets by resource availability, interconnection capacity, and Indigenous partnership structures.
Technology:
Wind and solar deployment concentrates in Alberta and Saskatchewan where merchant markets reward variable generation, while hydroelectric assets anchor capacity in British Columbia and Quebec. Biomass applications remain concentrated in forest-product regions with established feedstock logistics.
- Wind:Modern turbines achieve 35-45% capacity factors across Prairie provinces where sustained gust corridors align with existing transmission trunk lines. Saskatchewan's crown utilities and Alberta's merchant developers drive procurement volumes to meet coal phase-out deadlines.
- Solar:Photovoltaic arrays exploit peak pricing hours in Alberta's deregulated power pool, with deployment accelerating fastest where real-time price signals reward flexible dispatch. CSA Group certification requirements constrain inverter vendor selection.
- Biomass:Combustion systems serve industrial heat applications in forest-dependent regions, with feedstock proximity determining project economics.
- Hydro:Run-of-river configurations navigate terrain constraints in British Columbia and Quebec, often paired with complementary wind generation to firm output profiles.
Wind holds the largest share; momentum sits with solar as Alberta's merchant market rewards peak-hour generation.
Application:
Cost tiers separate capital-intensive grid-connected assets from distributed solutions serving remote or Indigenous communities. Federal clean electricity regulations tighten emission thresholds that determine green bond eligibility across application types.
- Grid Power:Utility-scale wind and solar assets feed provincial transmission networks, with interconnection queue backlogs in Alberta and British Columbia now stretching multiple years. Crown utilities in Saskatchewan synchronize procurement with federal assessment cycles.
- Off-grid Solutions:Diesel displacement projects serve remote mining camps and northern Indigenous communities where transmission extension proves uneconomical. Natural Resources Canada shapes timelines through cumulative effects assessments.
- Heating:Biomass combustion addresses industrial process heat in forest-product regions and district heating networks in municipal applications.
- Transportation:Renewable electricity supports fleet electrification mandates, with charging infrastructure deployment concentrated in urban corridors.
Grid power commands the deepest capital pools; off-grid solutions are climbing the fastest as remote community partnerships unlock non-traditional finance.
End User:
Customer type determines contract structure, with industrial offtakers unbundling energy procurement from carbon attribute acquisition in liquid wholesale markets.
- Industrial:Mining operations in northern Ontario and oil sands facilities near Fort McMurray execute direct power purchase agreements to hedge carbon exposure and meet Scope 2 reduction commitments. Merchant market access enables separate contracting for firming capacity and renewable energy certificates.
- Commercial:Corporate sustainability targets drive procurement of physical power and green tags through Alberta's transparent hourly pricing mechanism.
- Residential:Distributed generation participation expands through shared ownership structures attracting agricultural and Indigenous community investment.
- Government:Provincial utilities and federal agencies anchor long-term contract volumes that provide development certainty outside merchant exposure.
Industrial offtakers hold the largest share; residential distributed generation is gaining share fastest through community ownership models.
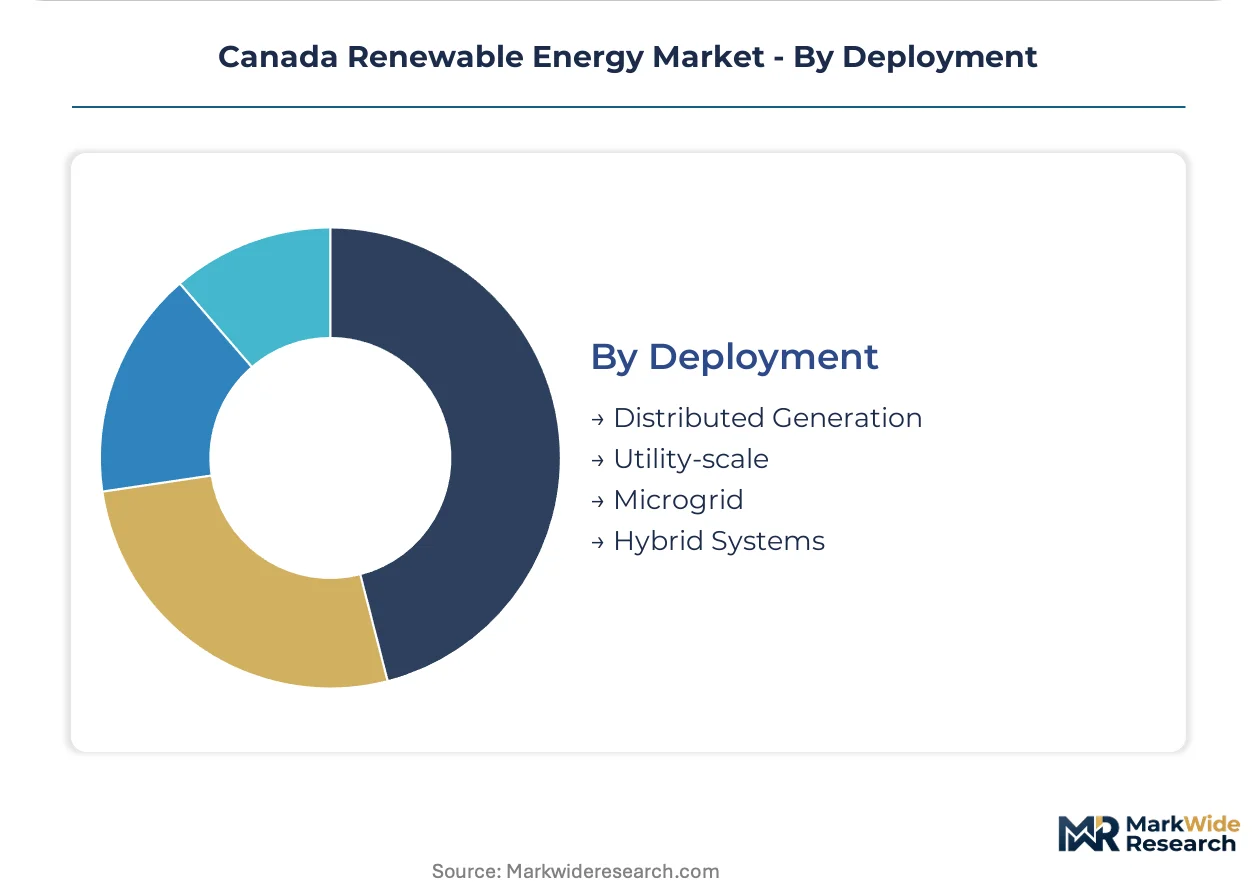
Deployment:
Supply concentration varies by scale, with utility-scale projects commanding established EPC capacity while microgrid deployment depends on specialized integrators serving remote applications.
- Utility-scale:Wind and solar farms exceeding 50 MW capacity feed provincial grids, with procurement concentrated in Alberta and Saskatchewan where coal retirement deadlines create immediate replacement demand.
- Distributed Generation:Agricultural and First Nations participation expands through shared ownership structures that create capital pools outside traditional utility finance.
- Microgrid:Islanded systems serve remote communities and industrial camps, with diesel displacement economics improving as battery costs decline.
- Hybrid Systems:Run-of-river hydro paired with wind generation firms output profiles in terrain-constrained regions of British Columbia and Quebec.
Utility-scale deployment holds the largest share; hybrid systems show the steepest expansion trajectory as developers optimize complementary resource pairing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal carbon pricing and provincial renewable portfolio standards are redirecting capital toward wind and solar assets across Canadian provinces, with interconnection capacity and Indigenous consultation protocols determining project viability.
Alberta
The merchant power market rewards flexible solar dispatch during peak pricing hours, accelerating development timelines for independent power producers. The Alberta Utilities Commission manages interconnection queues that now stretch multiple years, constraining project completions. Calgary anchors procurement activity as oil sands operators execute direct power purchase agreements to hedge carbon exposure.
Saskatchewan
Hard coal phase-out deadlines create immediate replacement demand concentrated in Prairie wind corridors where sustained gusts align with transmission trunk lines. SaskPower synchronizes procurement windows with federal assessment cycles under the Impact Assessment Act. Crown utility contracts provide development certainty outside merchant market volatility.
British Columbia
Terrain constraints favor run-of-river hydro paired with complementary wind generation to firm output profiles in mountainous terrain. The British Columbia Utilities Commission shapes timelines through cumulative effects assessment requirements. Vancouver and interior valleys host hybrid project development targeting corporate sustainability procurement.
Quebec
Hydroelectric dominance from provincial crown corporations creates niche opportunities for distributed wind and agricultural solar through shared ownership structures. Hydro-Québec's interconnection standards influence technology selection for grid-connected assets. Rural communities and First Nations partnerships unlock non-traditional capital pools outside utility finance.
Ontario
Industrial load concentration in mining and manufacturing drives corporate procurement of renewable energy certificates separate from physical power contracting. The Independent Electricity System Operator manages capacity auctions that influence merchant developer economics. Northern Ontario mining camps anchor off-grid and microgrid deployment for diesel displacement.
Canada Renewable Energy Market Vendor Landscape
Listed renewable power producers compete with private infrastructure specialists across capital access and contract tenor dimensions, creating a tiered structure where scale determines procurement eligibility for utility-scale auctions. The vendor base concentrates around hydroelectric incumbents with existing provincial relationships, merchant developers optimizing Alberta price signals, and integrated manufacturers controlling module supply chains. Strategic moves center on securing long-term power purchase agreements with crown utilities and qualifying domestic content requirements for federal Investment Tax Credit capture.
Within the hydroelectric-anchor tier, Brookfield Renewable Partners and Innergex Renewable Energy occupy positions leveraging existing provincial utility relationships to secure contract certainty. Canadian Solar exemplifies the integrated manufacturer archetype with control extending from polysilicon through project development. Among Prairie-focused merchant developers, Northland Power and TransAlta Renewables represent the price-signal optimization strategy in Alberta's deregulated power pool.
| Leading Market Players |
|---|
| Boralex |
| Innergex Renewable Energy |
| Brookfield Renewable Partners |
| AMP.ENERGY |
| Northland Power |
| Canadian Solar |
| TransAlta Renewables |
| Enbridge |
| Algonquin Power & Utilities |
| Others |
Supply Flow & Price Mechanics
Utility-scale capacity utilization above 80 percent in Alberta's merchant market concentrates procurement leverage among developers with secured interconnection positions, compressing price floors for new entrants while elevating margins for incumbent asset holders with operational fleets. This scale asymmetry feeds directly into supply chain concentration, where module procurement tilts toward vertically integrated manufacturers capable of absorbing tariff volatility through captive polysilicon production.
Pricing Analysis
Certification level creates the primary spread, with CSA Group-certified inverters commanding 15-20 percent premiums over uncertified alternatives due to collapsed vendor pools. Project-based long-term offtake contracts dominate regulated utility procurement in Saskatchewan and British Columbia, while Alberta's merchant pool rewards hourly price optimization without contractual price floors. Cost compression in standard-tier fixed-tilt solar arrays is intensifying as Asian module sourcing undercuts domestic qualification requirements. Industrial offtakers in oil sands and mining operations show lowest price sensitivity due to carbon hedge value, whereas agricultural co-investors in distributed generation prioritize lowest unit capital cost.
Supply Chain Analysis
China and Southeast Asia anchor crystalline silicon module manufacturing, with South Korea and Taiwan supplying premium-grade wafers for domestic-content-tracked projects. Polysilicon, aluminum framing, and power electronics constitute critical input dependencies, with logistics concentrated through Vancouver and Prince Rupert ports for western deployment. Single-source vulnerability concentrates in inverter supply where CSA Group certification has collapsed qualified vendors to a handful of suppliers. Distribution runs through provincial utility procurement desks for utility-scale assets, while distributed generation segments rely on regional EPC integrators with Indigenous partnership capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's renewable energy market requires substitution defense against firming capacity alternatives including natural gas peakers and emerging long-duration storage, as grid operators confront balancing challenges from high renewable penetration. Incumbents must navigate this threat through strategic positioning that secures dispatch priority and interconnection access.
For Market Incumbents: Compound interconnection queue positions through early-stage development partnerships that secure transmission rights ahead of regulatory approval cycles. Prioritize backward integration into energy storage or demand response capabilities to firm output profiles and capture capacity market premiums. Defensive consolidation of development pipelines in Alberta and Saskatchewan hedges against merchant price volatility while crown utility relationships in British Columbia and Quebec provide contract certainty.
For New Entrants and Emerging Players: Anchor in Indigenous community partnership structures for distributed generation and microgrid deployment, where shared ownership models unlock non-traditional capital pools and navigate duty-to-consult requirements with execution certainty. Target agricultural solar and remote diesel displacement applications in northern Ontario and Quebec, where transmission extension economics favor distributed solutions. Go-to-market positioning as specialized integrators with First Nations joint venture structures differentiates against utility-scale incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with secured interconnection rights and long-term power purchase agreement coverage, as merchant exposure concentrates risk among price-takers without contractual revenue floors. Acquisition targeting should prioritize hybrid hydro-wind portfolios in British Columbia and Quebec with complementary generation profiles that reduce firming costs. The signal to watch is interconnection queue reform announcements from Natural Resources Canada and provincial regulators, which would reset development timelines and reprime capital deployment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Execution | Long-term contracts with SaskPower and BC Hydro de-risk development capital against merchant volatility. |
| Indigenous Partnership Structuring | Shared ownership models with First Nations unlock federal incentive eligibility and streamline consultation protocols. |
| CSA Certification Investment | Qualifying inverters for grid connection expands addressable procurement pools in provincial utility auctions. |
| Hybrid System Deployment | Run-of-river hydro paired with wind generation firms output profiles and elevates capacity value in BC and Quebec. |
| Merchant Market Optimization | Real-time dispatch algorithms in Alberta's power pool capture peak pricing hours without long-term offtake dependency. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, project development databases, and utility procurement disclosures. Primary interviews engaged utility planning officers at provincial crown corporations, independent power producer development executives, EPC contractors with western Canada specialization, and grid operators managing interconnection queues. Secondary validation drew from Natural Resources Canada publications, provincial utility integrated resource plans, Alberta Utilities Commission regulatory records, and federal clean electricity regulation impact assessments. Bottom-up project pipeline aggregation triangulates against top-down capacity and investment flow estimates.
Segmentation dimensions modeled span fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type across the projection horizon. Technology trajectories for wind, solar, hydro, and biomass capacity factors inform output assumptions, while provincial carbon pricing schedules and coal phase-out deadlines anchor demand-side drivers. CAGRs derive from regression-based capacity buildout curves calibrated to historical procurement volumes and announced utility targets.
Material uncertainties — interconnection queue reform timing, Indigenous consultation protocol evolution, and federal Investment Tax Credit domestic content rule finalization — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained federal carbon pricing escalation and provincial renewable portfolio standard maintenance. Recalibration cycles align with material shifts in regulatory approval timelines and crown utility procurement window announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Lighting System Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Belarus Renewable Energy Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Green Power Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Republic of Ireland Renewable Energy Market