
 India Hydrogen Market | 2026-2036
India Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
India Hydrogen Market Insights
Green hydrogen project finance through viability-gap funding and sovereign green bonds is rewriting competitive entry rules for capital-intensive electrolyzer builds. Reliance Industries leverages its Jamnagar refining complex to anchor pilot-scale electrolysis integration. GAIL (India) sustains pipeline infrastructure advantages by repurposing existing natural gas networks for hydrogen blending trials. NTPC competes through utility-scale renewable-hybrid electrolyzer projects at its Gujarat and Rajasthan solar parks.
Hydrogen in India denotes a color-coded energy carrier produced through electrolysis, steam methane reforming, or biomass gasification, with purity grades ranging from industrial to fuel-cell specifications exceeding 99.97 percent. Its primary commercial purpose centers on decarbonizing hard-to-abate sectors where direct electrification proves technically or economically impractical. Steam methane reforming currently dominates installed production capacity, though electrolysis captures the fastest expansion trajectory as renewable electricity tariffs compress operating costs. Industrial processes command the largest application share, while fuel cell vehicles represent an emerging but policy-backed consumption node with concentrated pilot deployments.
BIS certification requirements for hydrogen purity and storage vessel integrity shape product standards, while CEA grid-connectivity rules govern electrolyzer power sourcing and renewable purchase obligations. The PLI scheme for electrolyzer manufacturing redirects capital toward domestic supply chain buildout, tightening import dependency for stack components. Stakeholders must monitor tariff rationalization for interstate hydrogen transport and the evolving mandate scope under the National Hydrogen Mission.
Market Dynamics
The National Hydrogen Mission is compressing project timelines through viability-gap funding and sovereign green bond issuance, forcing capital reallocation toward electrolyzer manufacturing clusters in Gujarat and Rajasthan.
Growth Catalysts
- PLI scheme for electrolyzer manufacturing:Domestic production incentives under India's production-linked incentive framework redirect capital toward stack assembly and balance-of-plant components, tightening import dependency for critical membranes and catalysts.
- Steel sector decarbonization mandates:Hard-to-abate metallurgical processes in Odisha and Jharkhand are piloting hydrogen direct reduction furnaces as blast furnace retrofits face mounting emission intensity scrutiny.
- Jamnagar refining complex:Western India's dense concentration of catalytic crackers and hydrotreaters creates concentrated offtake demand for merchant hydrogen supply, anchoring electrolyzer deployment at scale.
Market Restraints
- Renewable electricity tariff volatility:Grid-connected electrolyzer economics remain exposed to interstate transmission charges and open-access regulatory friction, compressing green hydrogen cost parity timelines against steam methane reforming.
- Stack component import concentration:Proton exchange membranes and iridium catalysts originate from concentrated East Asian and European supply bases, exposing project developers to currency fluctuation and logistics bottlenecks.
- BIS certification timelines:Hydrogen purity standards and pressure vessel integrity testing protocols create extended product qualification cycles, delaying commercial offtake agreements for early-mover electrolyzer manufacturers.
Strategic Opportunities
- Port-based hydrogen export hubs:Mundra and Hazira terminals offer liquefaction and ammonia cracking infrastructure for Middle East and Southeast Asian offtake, positioning Gujarat as a regional hydrogen trading node.
- Fertilizer sector feedstock switching:Ammonia plant retrofits at Sindri and Nangal complexes present captive demand for green hydrogen integration under nutrient-based subsidy reform trajectories.
- Alkaline-PEM hybrid electrolyzer architectures:Technology convergence between mature alkaline stacks and proton exchange membrane responsiveness enables load-following designs optimized for India's solar generation profiles.
Industry Challenges
- Electrolyzer commissioning specialist scarcity:Field engineering capacity for megawatt-scale stack installation and membrane electrode assembly replacement remains concentrated with European and Japanese service providers, constraining domestic deployment velocity.
- Natural gas pipeline repurposing complexity:Hydrogen embrittlement assessment and compressor station retrofit requirements for GAIL's existing transmission network demand extended metallurgical testing protocols under Petroleum and Natural Gas Regulatory Board oversight.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Hydrogen Market |
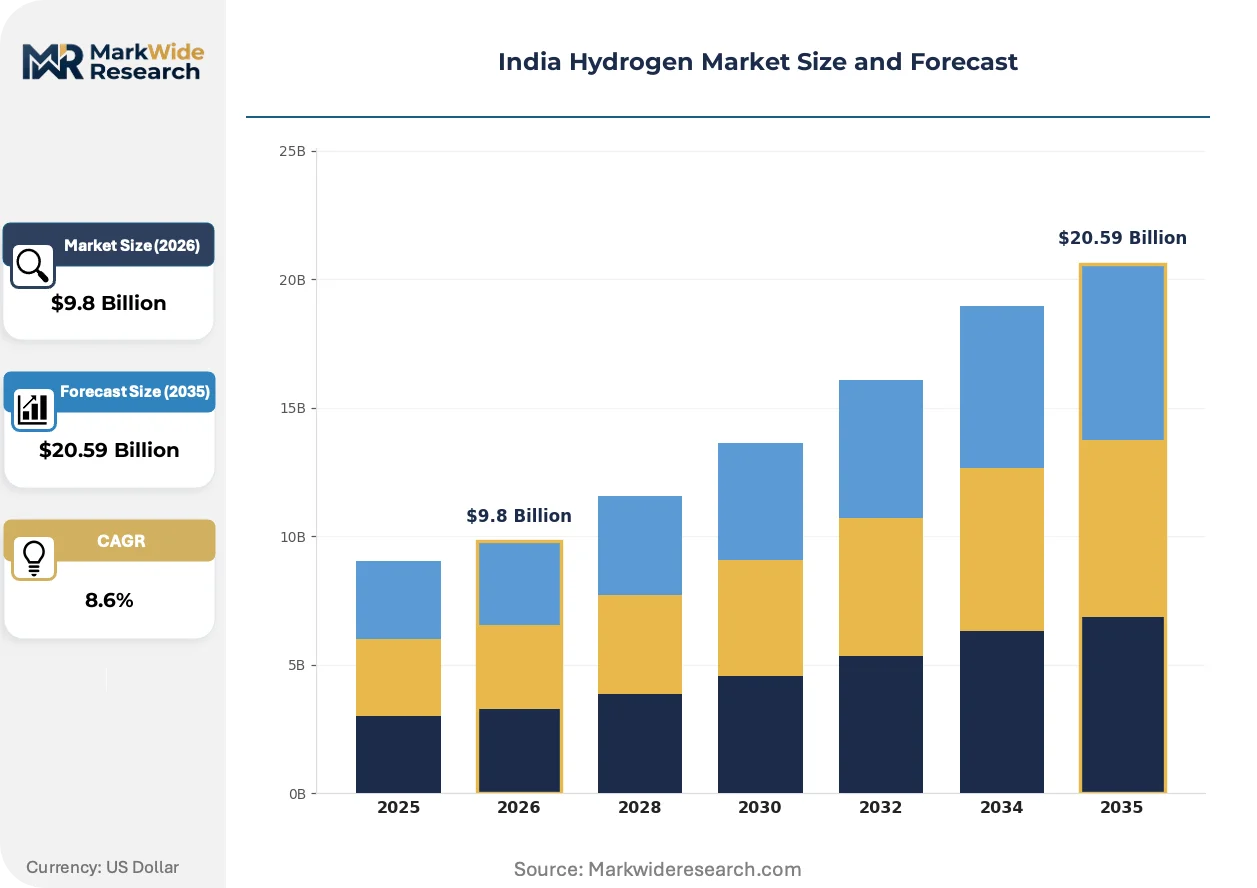
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.59 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fuel Cell Vehicles, Industrial Processes, Power Generation, Chemical Manufacturing Technology: Electrolysis, Steam Methane Reforming, Biomass Gasification, Chemical Looping End User: Transportation, Energy Sector, Manufacturing, Utilities Distribution Channel: Pipelines, Compressed Gas Stations, Liquid Hydrogen Stations, Onsite Production |
| Companies Covered | Oil & Natural Gas Corporation, GAIL (India), Reliance Industries, JSW Energy, Bharat Petroleum Corporation, Indian Oil Corporation, Larsen & Toubro, Adani Power, NTPC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Hydrogen Market Trends and Innovations
Electrolyzer cost curves and renewable hybrid configurations are actively compressing green hydrogen production economics, while regulatory mandates harden emission intensity thresholds for hard-to-abate sectors.
Modular alkaline electrolyzer stacks with enhanced current density designs are collapsing the capital cost differential against fossil-derived hydrogen. Refinery operators in Gujarat are deploying 10-20 MW pilot units for hydrotreater feedstock substitution. This technology trajectory is collapsing merchant hydrogen pricing benchmarks and forcing steam methane reforming assets toward carbon capture retrofits or early retirement.
CEA renewable purchase obligation amendments now recognize green hydrogen production as a compliance pathway for obligated entities. Grid-connectivity rules for electrolyzer installations are tightening dispatch priority and banking provisions. Western Indian solar parks are responding with dedicated transmission infrastructure and time-of-day tariff structures optimized for continuous hydrogen production.
Long-term offtake contracting is displacing spot merchant sales as the dominant procurement model for industrial hydrogen buyers. Ammonia and methanol producers are negotiating 10-15 year take-or-pay agreements with electrolyzer developers to secure project finance. This shift is most visible in Rajasthan, where renewable-hybrid hydrogen parks anchor fertilizer sector feedstock switching commitments.
India Hydrogen Market Segmentation
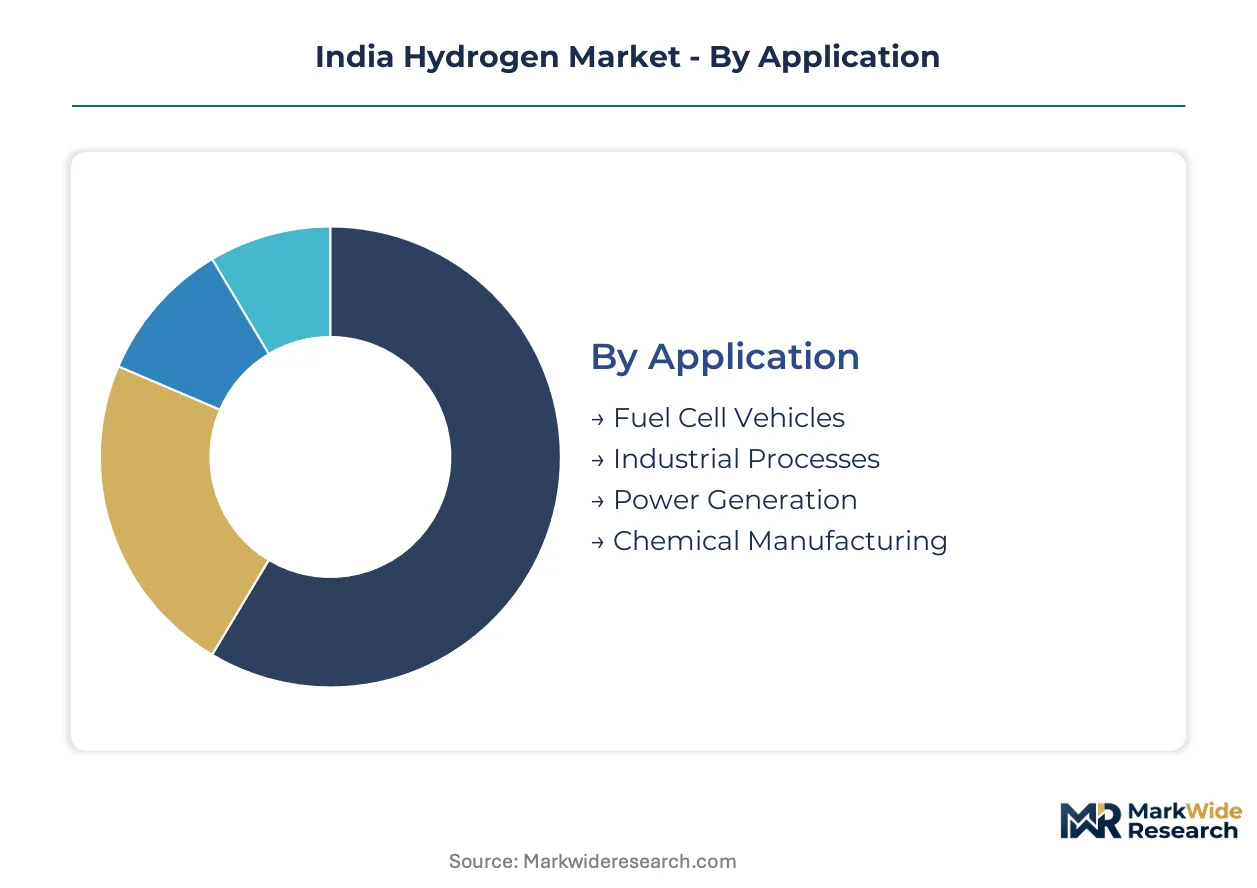
India's hydrogen market segments reflect divergent maturity levels across production technologies and consumption modes. Application patterns concentrate in western industrial corridors, while distribution infrastructure remains unevenly developed across states.
Application:
Mature industrial offtake contrasts with nascent mobility applications across India's hydrogen economy.
- Industrial Processes:Hydrogen serves hydrotreater feedstock substitution and direct reduction furnaces in Gujarat and Odisha metallurgical clusters. Refinery desulfurization at Jamnagar and Hazira complexes anchors concentrated demand, with BIS purity standards governing merchant supply contracts.
- Chemical Manufacturing:Ammonia synthesis and methanol production at Sindri and Nangal fertilizer complexes constitute captive consumption nodes. Nutrient-based subsidy reforms are redirecting feedstock procurement toward electrolyzer-derived hydrogen under National Hydrogen Mission mandates.
- Fuel Cell Vehicles:Pilot bus deployments and heavy-duty trucking trials concentrate in Delhi-Mumbai industrial corridors with policy-backed procurement quotas.
- Power Generation:Turbine blending trials and grid-balancing applications remain experimental, limited by CEA dispatch priority frameworks and storage cost economics.
Industrial Processes handles the majority of throughput; Chemical Manufacturing is the fastest mover on share.
Technology:
Cost tier stratification separates established fossil-derived methods from capital-intensive electrolyzer builds.
- Steam Methane Reforming:Natural gas feedstock conversion dominates installed capacity through refinery-integrated production at Gujarat petrochemical complexes. Carbon intensity exposure under evolving emission norms is forcing carbon capture retrofits or asset retirement timelines.
- Electrolysis:Alkaline and PEM stack configurations capture the steepest expansion trajectory as PLI scheme incentives compress domestic manufacturing costs. Rajasthan and Gujarat solar parks anchor renewable-hybrid deployments with dedicated transmission infrastructure.
- Biomass Gasification:Agricultural residue conversion trials in Punjab and Haryana face feedstock logistics constraints and gas cleanup cost barriers.
- Chemical Looping:Experimental oxygen carrier systems for inherent carbon capture remain pre-commercial, with pilot units limited to research institution partnerships.
Steam Methane Reforming retains volume dominance; Electrolysis is expanding most quickly as tariff structures favor renewable coupling.
End User:
Customer type segmentation reveals divergent procurement sophistication across public and private offtake channels.
- Manufacturing:Steel, cement, and refinery operators in western India negotiate long-term take-or-pay agreements to secure electrolyzer project finance. Emission intensity scrutiny under sectoral decarbonization mandates is hardening hydrogen procurement specifications.
- Energy Sector:Oil marketing companies and power utilities pilot blending trials and storage integration, constrained by pipeline repurposing complexity under Petroleum and Natural Gas Regulatory Board oversight.
- Transportation:State transport undertakings and logistics operators face infrastructure chicken-and-egg constraints with limited refueling station networks.
- Utilities:Grid operators explore hydrogen for seasonal storage and renewable curtailment management, though commercial viability remains unproven under current tariff regimes.
Manufacturing commands procurement volume leadership; Energy Sector is gaining share fastest through utility-scale electrolyzer partnerships.
Distribution Channel:
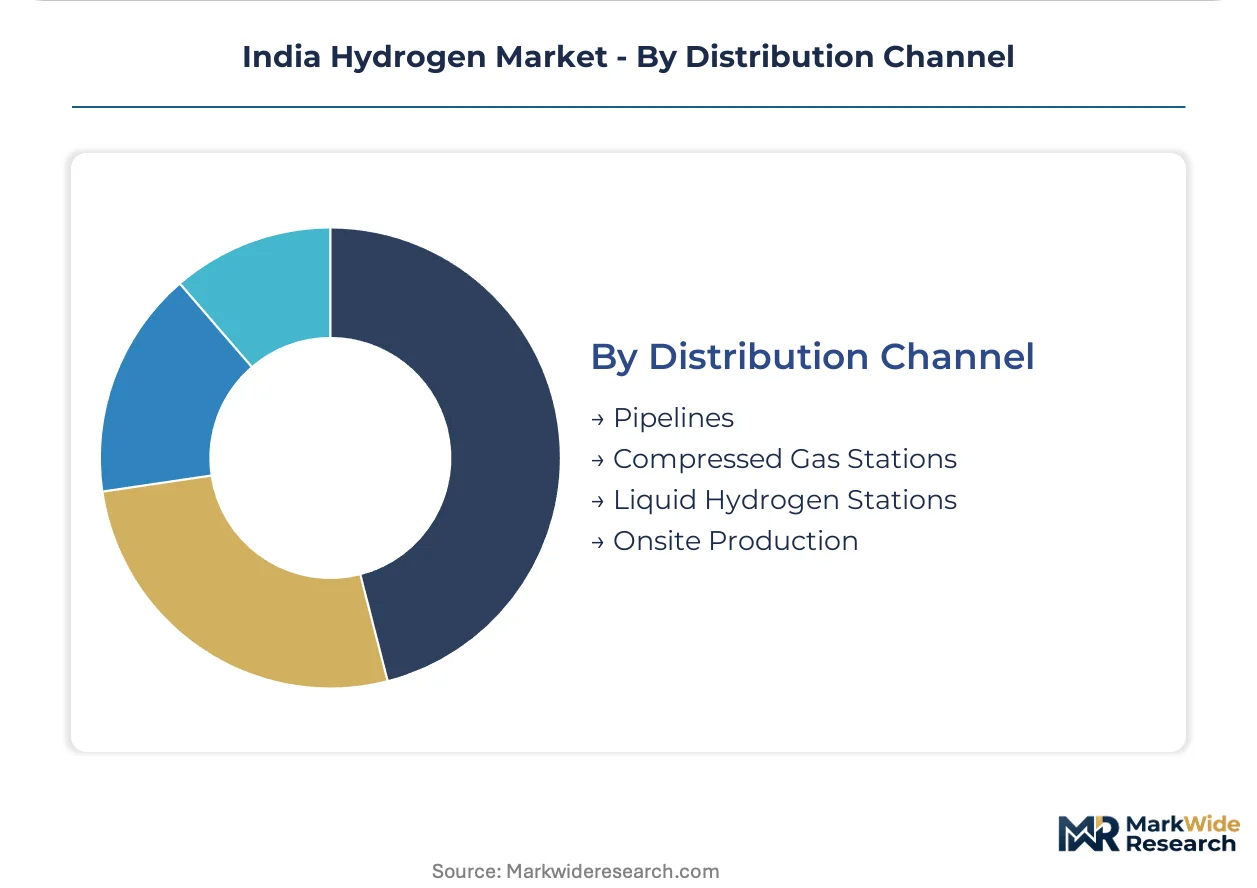
Supply concentration in pipeline infrastructure shapes regional accessibility patterns across Indian states.
- Pipelines:GAIL's existing natural gas network offers repurposing potential for hydrogen blending trials, pending metallurgical embrittlement assessment and compressor station retrofits. Western India corridor density favors initial deployment concentration.
- Onsite Production:Captive electrolyzer installations at refinery and fertilizer complexes eliminate transport costs, with BIS certification timelines governing commercial commissioning schedules.
- Compressed Gas Stations:Tube trailer delivery networks serve dispersed industrial offtake in Maharashtra and Tamil Nadu with limited pipeline reach.
- Liquid Hydrogen Stations:Cryogenic liquefaction infrastructure at Mundra and Hazira ports targets export-oriented ammonia cracking and maritime bunkering applications.
Pipelines handle the majority of throughput potential; Onsite Production is climbing the fastest as captive projects bypass transport logistics entirely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's hydrogen economy tilts toward import substitution in western industrial corridors while export-oriented liquefaction infrastructure takes shape at Gujarat ports. The geographic concentration reflects deliberate policy clustering under the National Hydrogen Mission.
Gujarat
Jamnagar's refining complex drives concentrated hydrotreater demand for merchant hydrogen supply. The state anchors PLI scheme manufacturing incentives for electrolyzer stack assembly. Hazira and Mundra ports host pilot ammonia cracking terminals targeting Middle East offtake.
Rajasthan
Solar park renewable-hybrid configurations power utility-scale electrolyzer deployments at Bhadla and Phased. CEA grid-connectivity rules recognize green hydrogen production under renewable purchase obligations. Jodhpur-Jaisalmer belt concentrates dedicated transmission infrastructure for continuous hydrogen production.
Maharashtra
Mumbai-Pune industrial corridor sustains refinery desulfurization demand at lower capacity factors than Gujarat. The state transport undertaking pilots fuel cell bus procurement with limited refueling station density. Taloja and Panvel clusters explore captive electrolyzer installations for chemical manufacturing feedstock.
Tamil Nadu
Coimbatore-Salem manufacturing belt experiments with compressed gas tube trailer delivery where pipeline infrastructure remains undeveloped. State industrial policy offers capital subsidies for electrolyzer manufacturing facilities. Chennai port evaluates small-scale liquefaction for maritime bunkering trials.
Odisha
Angul-Jharsuguda metallurgical cluster pilots hydrogen direct reduction furnaces under steel sector decarbonization mandates. Captive demand from aluminum smelters and sponge iron units creates niche offtake opportunities. BIS certification timelines delay commercial commissioning for early electrolyzer installations.
India Hydrogen Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: integrated energy conglomerates with refining footprints, state-owned pipeline operators repurposing gas infrastructure, and renewable-utility hybrids developing dedicated electrolyzer parks. Competitive positioning crystallizes through long-term offtake contracting, sovereign-backed project finance access, and electrolyzer manufacturing localization under PLI scheme incentives. Players defend position through backward integration into renewable generation assets and strategic port infrastructure control.
Within the integrated energy tier, Reliance Industries anchors refining-anchored electrolyzer pilots, while GAIL (India) exemplifies pipeline repurposing strategies for hydrogen blending trials. NTPC occupies a position in utility-scale renewable-hybrid deployment at western solar parks. These three represent divergent pathways to scale: refinery integration, infrastructure leverage, and greenfield renewable coupling.
| Leading Market Players |
|---|
| Oil & Natural Gas Corporation |
| GAIL (India) |
| Reliance Industries |
| JSW Energy |
| Bharat Petroleum Corporation |
| Indian Oil Corporation |
| Larsen & Toubro |
| Adani Power |
| NTPC |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Gujarat's electrolyzer manufacturing corridor is compressing supplier margins while simultaneously accelerating price discovery for long-term offtake contracts. This utilization dynamic rewards early movers with sovereign-backed project finance access and punishes late entrants with extended BIS certification timelines.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with ten-to-fifteen-year take-or-pay agreements displacing spot merchant sales as the dominant procurement model. Price differentiation rests on BIS certification grade and renewable purchase obligation compliance status, with grid-connected electrolyzer output commanding premiums over fossil-derived alternatives. Cost compression in alkaline-PEM hybrid configurations is intensifying because PLI scheme incentives compress domestic stack assembly costs. Steel and refinery operators exhibit lowest price sensitivity due to emission intensity mandates, while compressed gas tube trailer buyers in Tamil Nadu remain most exposed to transport cost volatility.
Supply Chain Analysis
Proton exchange membrane import concentration between Japan and Germany dominates supply chain risk exposure for Indian electrolyzer developers. Critical inputs draw from concentrated East Asian and European supply bases: iridium catalysts, titanium bipolar plates, and perfluorinated membranes. Single-source vulnerability in membrane electrode assembly production exposes project timelines to logistics bottlenecks and currency fluctuation. Distribution runs through GAIL's repurposed natural gas pipeline network, with western corridor density favoring initial hydrogen blending trials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story. BIS certification timelines and CEA renewable purchase obligation amendments create switching costs that cement early-mover positions.
For Market Incumbents: Build pipeline infrastructure moats by accelerating GAIL network repurposing ahead of Petroleum and Natural Gas Regulatory Board metallurgical testing completion. Secure backward integration into Rajasthan solar park generation assets to isolate electrolyzer economics from interstate transmission charge volatility. Threat: emerging pure-play electrolyzer manufacturers with PLI scheme cost advantages. Lever: captive renewable-hybrid deployment at utility scale. For New Entrants and Emerging Players: Pursue captive onsite production contracts at Odisha metallurgical clusters where hydrogen direct reduction furnace pilots face limited merchant supply alternatives. Target fertilizer sector feedstock switching at Sindri and Nangal complexes under nutrient-based subsidy reform trajectories. White-space: compressed gas tube trailer delivery networks in Maharashtra and Tamil Nadu pipeline gaps. Go-to-market: technology licensing partnerships with European stack specialists to bypass field engineering capacity constraints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrolyzer developers with ten-year offtake agreements from steel sector decarbonization mandates. Long-term viability hinges on tariff rationalization for interstate hydrogen transport and sovereign green bond issuance continuity. Acquisition archetype: alkaline-PEM hybrid technology holders with demonstrated load-following designs. Signal to monitor: CEA amendments recognizing green hydrogen production under renewable purchase obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Steel sector offtake contracts at Angul-Jharsuguda clusters anchor project finance viability. |
| Backward Integration | Renewable-hybrid solar park control at Bhadla and Phased isolates electrolyzer cost structures. |
| Capacity Expansion | PLI scheme manufacturing scale-up in Gujarat tightens import dependency for stack components. |
| Joint Venture | European membrane electrode assembly partnerships address domestic commissioning specialist scarcity. |
| Green Certification Program | BIS hydrogen purity standards govern commercial eligibility for refinery hydrotreater feedstock substitution. |
Research Methodology
Operator-level perspectives from electrolyzer project developers, GAIL pipeline operations engineers, CEA grid-connectivity officers, and steel sector procurement leads anchored the qualitative base. Secondary validation drew from Petroleum and Natural Gas Regulatory Board filings, CEA renewable purchase obligation amendments, BIS certification timelines, and sovereign green bond issuance disclosures. Bottom-up electrolyzer deployment tallies triangulated against top-down National Hydrogen Mission capacity targets.
Scenario-bracketing framed projections across conservative, baseline, and accelerated adoption pathways. Segmentation dimensions modeled include production technology, application mode, end-user procurement sophistication, and distribution channel infrastructure maturity. CAGRs derived from electrolyzer cost curve trajectories and renewable electricity tariff compression rates. Industry-specific inputs encompassed PLI scheme incentive phase-out schedules and BIS certification backlog estimates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play electrolyzer manufacturers or international stack suppliers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Storage Tank Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Purification Units Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Hydrogen Energy Electrolyzer Market
Hydrogen Energy
Liquid Hydrogen Tank Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Hydrogen Purification Market