
 PEM Water Electrolytic Hydrogen Production System Market | 2026-2036
PEM Water Electrolytic Hydrogen Production System Market Size, Share, and Industry Trends Forecast 2026-2036
PEM Water Electrolytic Hydrogen Production System Market Insights
Long-term service contracts for membrane replacement and stack refurbishment is rebalancing how OEMs capture lifetime value from PEM electrolyzer deployments. Siemens Energy leverages its turbine service infrastructure to bundle electrolyzer maintenance with existing power plant contracts. Nel ASA anchors Nordic project pipelines through integrated hydrogen delivery agreements. ITM Power competes by specializing in gigawatt-scale manufacturing architectures that compress stack assembly timelines.
A PEM water electrolytic hydrogen production system dissociates water into hydrogen and oxygen using a solid polymer electrolyte membrane, typically Nafion, operating at 50-80°C with current densities exceeding 1.5 A/cm² and differential pressures up to 30 bar; its primary purpose is to generate high-purity hydrogen for industrial feedstock or energy carrier applications without carbon emissions. Proton exchange membrane systems command premium pricing due to rapid response times suited to variable renewable input, while solid oxide electrolyzer variants occupy a nascent position where higher thermal integration yields superior efficiency at elevated temperatures. Fuel cell vehicle applications sustain early demand volumes, though industrial processes and energy storage represent deepening margin pools as offtake contracts lengthen.
The EU Green Deal and delegated acts under the Renewable Energy Directive establish product-level thresholds for green hydrogen certification that filter market access across European project pipelines. Japan's METI governs subsidy allocation through its Green Innovation Fund, directing capital toward domestic electrolyzer manufacturing scale-up. China's GB standards and dual carbon goals from MEE impose efficiency benchmarks that shape import eligibility and local procurement patterns. Stakeholders must track how certification regimes diverge across jurisdictions before committing to stack designs or offtake structures.
Market Dynamics
Industrial offtake agreements for green hydrogen are compressing project development timelines and forcing electrolyzer OEMs to restructure delivery contracts around guaranteed output volumes rather than equipment-only sales.
Growth Catalysts
- EU Green Deal Delegated Acts:Certification thresholds for renewable hydrogen filter European project pipelines toward electrolytic production routes, locking in demand visibility for stack manufacturers.
- Japan's Green Innovation Fund:METI-directed capital accelerates domestic electrolyzer manufacturing scale-up, creating anchored demand for component suppliers and system integrators.
- Ammonia feedstock switching:Fertilizer producers in Germany and South Korea are signing long-term hydrogen purchase agreements that de-risk electrolyzer deployment financing.
Market Restraints
- Iridium supply concentration:South African and Russian mining operations control over 80% of global iridium output, exposing membrane electrode assembly costs to geopolitical supply shocks.
- Proton exchange membrane technical limitations:Nafion-based stacks degrade under thermal cycling above 80°C, constraining integration with industrial waste heat recovery systems.
- China's GB standards efficiency benchmarks:Import eligibility restrictions under MEE dual carbon goals create regulatory friction for non-domestic stack designs seeking Chinese project participation.
Strategic Opportunities
- Underpenetrated Indian project pipeline:PLI scheme allocations for electrolyzer manufacturing remain below committed capacity, creating first-mover positioning for technology licensors.
- Grid balancing services convergence:Coupling PEM stacks with battery storage enables frequency regulation revenue streams beyond pure hydrogen sales.
- Green hydrogen offtake in South Korea:Government-mandated blending requirements for city gas networks generate contracted demand volumes through 2030.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized stack design and catalyst coating expertise concentrates among a limited pool of researchers, constraining OEM expansion.
- CE marking timeline compression:Pressure equipment directive compliance for 30-bar differential pressure systems extends certification cycles beyond project financing deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PEM Water Electrolytic Hydrogen Production System Market |
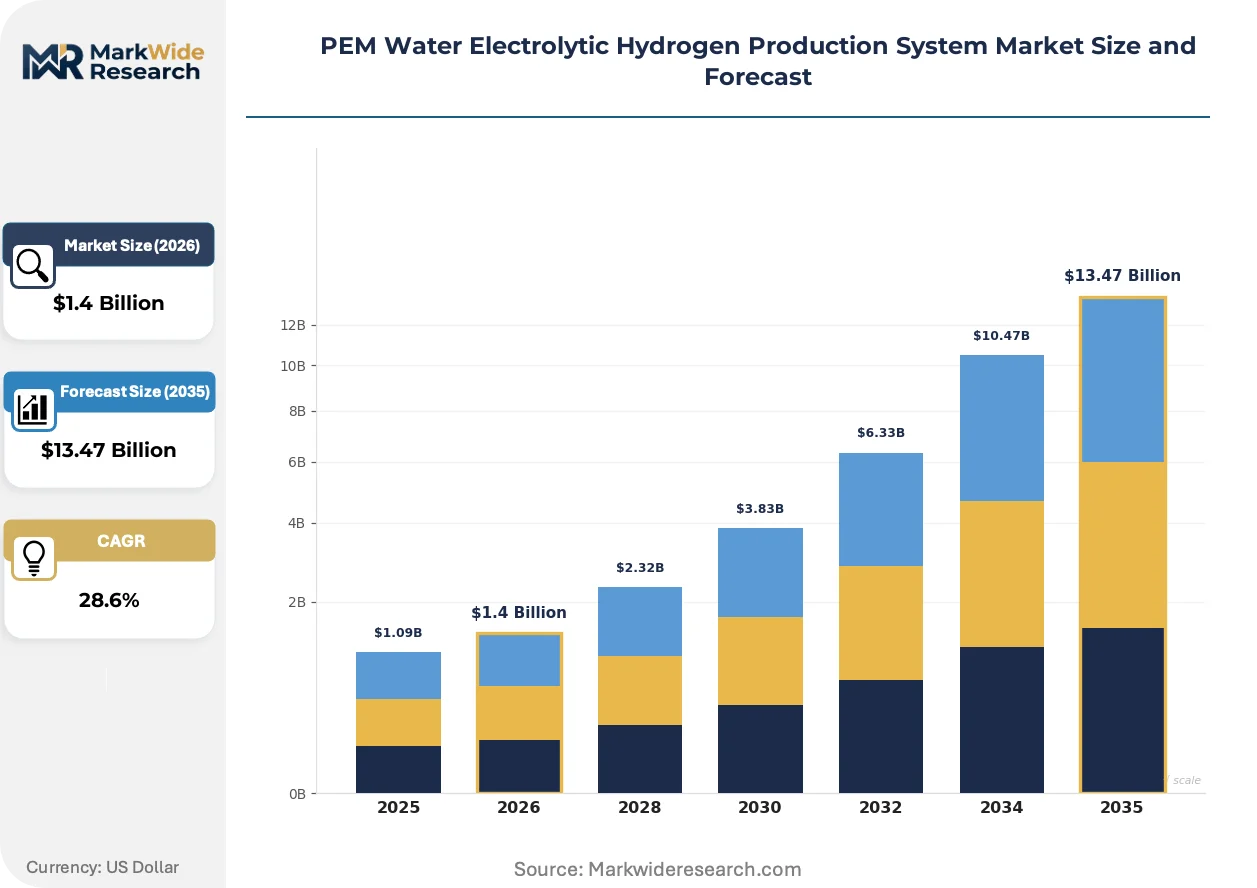
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $13.47 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Alkaline Electrolyzer, Solid Oxide Electrolyzer, Others End User: Industrial, Automotive, Power Generation, Research Institutions Technology: Electrolysis, Renewable Energy Integration, Advanced Control Systems, Water Management Application: Fuel Cell Vehicles, Electricity Generation, Industrial Processes, Energy Storage |
| Companies Covered | Nel ASA, ITM Power, Siemens Energy, Proton On-Site, Teledyne Energy Systems, McPhy Energy, Elogen, Plug Power, Cummins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PEM Water Electrolytic Hydrogen Production System Market Trends and Innovations
Membrane electrode assembly architectures are converging toward thinner catalyst layers and reinforced perfluorinated membranes that compress capital intensity while extending operational lifetimes.
Thin-film catalyst deposition is consolidating manufacturing economics across the electrolyzer supply chain. Stack assemblers in Germany and Japan are adopting atomic layer deposition for platinum group metal reduction. This consolidation is compressing catalyst loadings from 0.5 mg/cm² toward 0.2 mg/cm² without sacrificing current density performance.
REACH regulation amendments on perfluorinated substance restrictions are forcing membrane suppliers to accelerate alternative polymer development. Industrial chemical producers face substance authorization deadlines that threaten Nafion supply continuity. European OEMs are responding by qualifying hydrocarbon-based membrane prototypes for 2026 pipeline insertion.
Long-term service unbundling from equipment sales is restructuring buyer-supplier relationships. Industrial hydrogen purchasers in ammonia and refining now demand availability guarantees covering 15-year operational horizons. This shift is most visible in German project tenders where OEMs compete on levelized hydrogen production cost rather than stack capital expenditure alone.
PEM Water Electrolytic Hydrogen Production System Market Segmentation
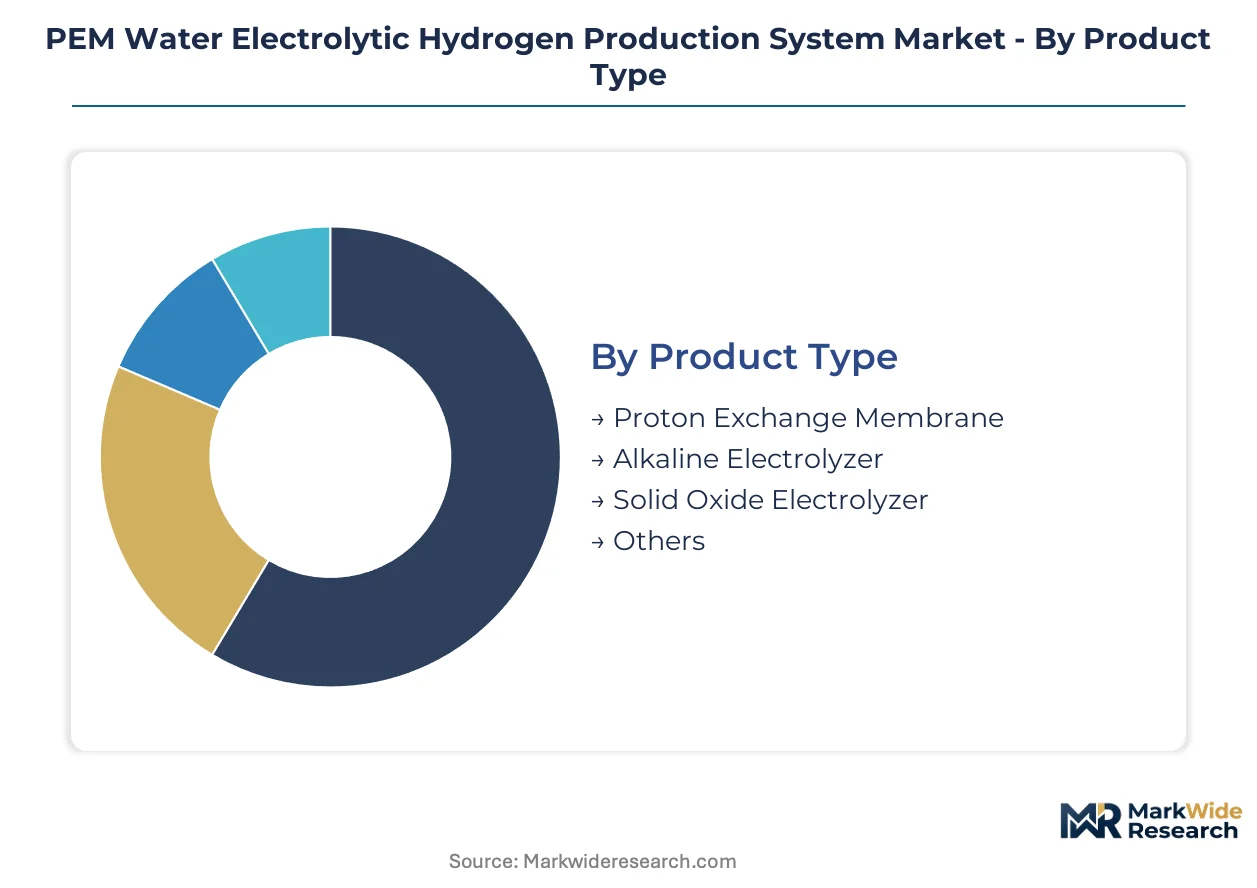
Stack architecture and membrane chemistry determine capital efficiency and operational lifetime for electrolyzer buyers. Segmentation reveals where premium pricing commands durable margins versus where volume manufacturing compresses unit economics.
Product Type:
Proton exchange membrane systems capture premium pricing through rapid response capability, while alkaline and solid oxide variants compete on capital intensity and thermal integration respectively.
- Proton Exchange Membrane:Nafion-based solid polymer electrolyte operates at 50-80°C with current densities exceeding 1.5 A/cm². Demand concentrates in Germany and Japan where variable renewable input requires sub-second ramp rates for grid balancing.
- Alkaline Electrolyzer:Liquid potassium hydroxide electrolyte in asbestos-free diaphragm configurations dominates Chinese manufacturing scale. Cost-sensitive industrial hydrogen buyers in ammonia feedstock switching favor this architecture where response time flexibility is less critical.
- Solid Oxide Electrolyzer:Yttria-stabilized zirconia ceramic electrolyte at 700-900°C enables steam electrolysis with superior thermal efficiency.
- Others:Emerging anion exchange membrane and proton-conducting ceramic variants occupy pre-commercial validation phases.
Today's leader: Proton Exchange Membrane. Tomorrow's challenger: Solid Oxide Electrolyzer.
End User:
Industrial procurement scales through long-term offtake agreements, while automotive demand tracks fuel cell vehicle deployment timelines.
- Industrial:Ammonia synthesis and petroleum refining operations in Germany and South Korea anchor contracted hydrogen volumes. METI subsidy allocation and EU Green Deal certification thresholds filter procurement toward electrolytic routes with guaranteed renewable origin.
- Automotive:Fuel cell vehicle refueling infrastructure in Japan and South Korea sustains megawatt-scale electrolyzer deployment. Government-mandated blending requirements for city gas networks generate anchored demand through 2030.
- Power Generation:Grid-connected electrolysis for synthetic methane and power-to-gas applications.
- Research Institutions:National laboratory and university pilot installations for stack performance validation.
Industrial offtake contracts lock in revenue visibility. Automotive deployment timelines remain policy-dependent.
Technology:
Renewable energy integration capabilities separate premium system architectures from commodity stack assemblies.
- Electrolysis:Core electrochemical cell stacks with membrane electrode assemblies and bipolar plate configurations.
- Renewable Energy Integration:Direct coupling with solar PV and wind turbine output through power conditioning and buffering systems. German project pipelines prioritize this capability for grid balancing revenue stacking.
- Advanced Control Systems:Model predictive control and digital twin architectures optimize stack degradation management. Japanese OEMs embed these systems to compress maintenance intervals and extend membrane replacement cycles.
- Water Management:Deionization, demineralization, and closed-loop circulation subsystems.
Control system sophistication determines operational expenditure differentials. Renewable integration capability opens ancillary service revenue streams.
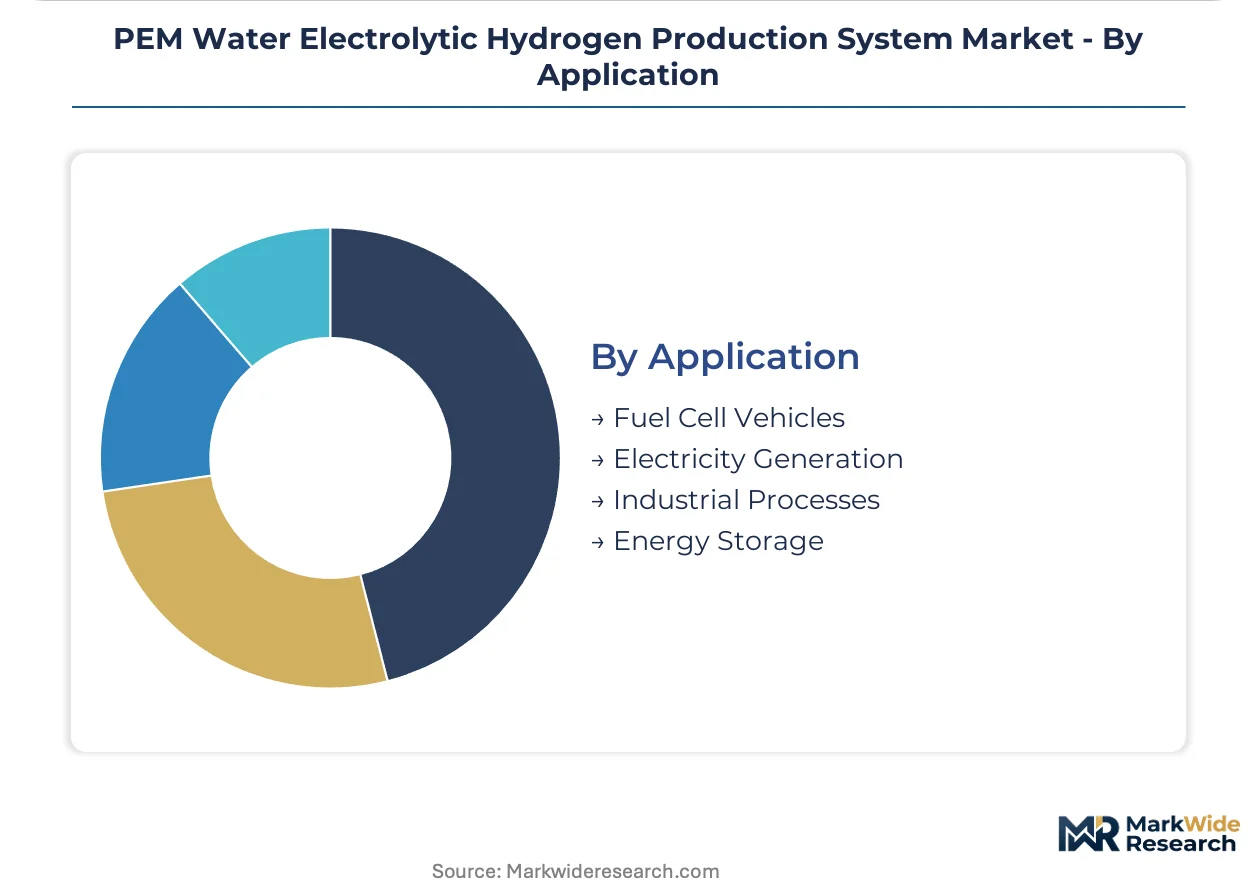
Application:
Fuel cell vehicle hydrogen supply commands early volumes, while industrial process feedstock and energy storage represent deepening margin pools.
- Fuel Cell Vehicles:High-purity hydrogen at 350-700 bar for passenger and heavy-duty transportation. South Korean city gas blending mandates and Japanese refueling network expansion sustain deployment.
- Industrial Processes:Ammonia synthesis, steel direct reduction, and petroleum hydrotreating. German fertilizer producers and refining operations sign 10-15 year purchase agreements that de-risk electrolyzer financing.
- Electricity Generation:Reversible fuel cell and turbine co-firing applications for seasonal storage.
- Energy Storage:Power-to-gas and synthetic fuel production for long-duration grid balancing.
Industrial feedstock applications expand most quickly as offtake contract structures mature. Fuel cell vehicle demand stabilizes at regional deployment ceilings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan pursue divergent hydrogen procurement models, with Berlin emphasizing industrial feedstock switching while Tokyo prioritizes fuel cell vehicle infrastructure deployment. South Korea bridges both approaches through mandated city gas blending requirements. China leverages domestic alkaline electrolyzer manufacturing scale to compress unit economics for cost-sensitive buyers.
Germany
Fertilizer producers in the Rhineland and Hamburg anchor contracted green hydrogen volumes for ammonia synthesis. EU Green Deal delegated acts under the Renewable Energy Directive filter project pipelines toward certified electrolytic production routes. The North German hydrogen cluster around Rostock and Lübeck concentrates stack deployment for refinery feedstock switching.
Japan
Fuel cell vehicle refueling networks in Kanto and Kansai sustain megawatt-scale electrolyzer procurement. METI's Green Innovation Fund directs subsidy capital toward domestic electrolyzer manufacturing scale-up. The Fukushima Hydrogen Energy Research Field exemplifies integrated renewable-to-hydrogen demonstration at utility scale.
South Korea
Petrochemical complexes in Ulsan and Yeosu sign long-term purchase agreements for refinery hydrotreating applications. Government-mandated blending requirements for city gas networks generate contracted demand through 2030. The Incheon-Gyeonggi industrial corridor hosts concentrated electrolyzer deployment for steel direct reduction pilots.
China
State-owned ammonia producers in Ningxia and Inner Mongolia drive alkaline electrolyzer procurement at capital-sensitive price points. GB standards and MEE dual carbon goals impose efficiency benchmarks that shape import eligibility for foreign stack designs. The Yangtze River Delta cluster around Shanghai concentrates PEM system assembly for export-oriented manufacturing.
United States
Texas and California hydrogen hubs anchor utility-scale electrolyzer deployment for industrial process feedstock. IRA production tax credits de-risk project financing for renewable hydrogen facilities. The Gulf Coast petrochemical corridor around Houston concentrates offtake contracting for refinery and ammonia applications.
PEM Water Electrolytic Hydrogen Production System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors capturing premium pricing in European project pipelines while component suppliers penetrate cost-sensitive Asian markets. Market structure consolidates around three tiers: full-stack OEMs with captive membrane electrode assembly capacity, system integrators licensing core cell technology, and regional assemblers sourcing bipolar plates and power electronics from distributed supplier networks. Dominant competitive moves include long-term service contract unbundling from equipment sales and strategic partnerships between electrolyzer OEMs and renewable developers to secure pipeline visibility.
Among Nordic and UK-based specialists, Nel ASA and ITM Power exemplify divergent scale strategies within the PEM electrolyzer segment, with the former anchoring integrated hydrogen delivery agreements and the latter occupying gigawatt-scale manufacturing architecture development. Siemens Energy represents the diversified industrial conglomerate archetype, leveraging existing turbine service infrastructure to bundle electrolyzer maintenance with power plant contracts. These three entities collectively illustrate how geographic origin and legacy capability shape competitive positioning without predetermining market share outcomes.
| Leading Market Players |
|---|
| Nel ASA |
| ITM Power |
| Siemens Energy |
| Proton On-Site |
| Teledyne Energy Systems |
| McPhy Energy |
| Elogen |
| Plug Power |
| Cummins |
| Others |
Pricing and Supply Chain Analysis
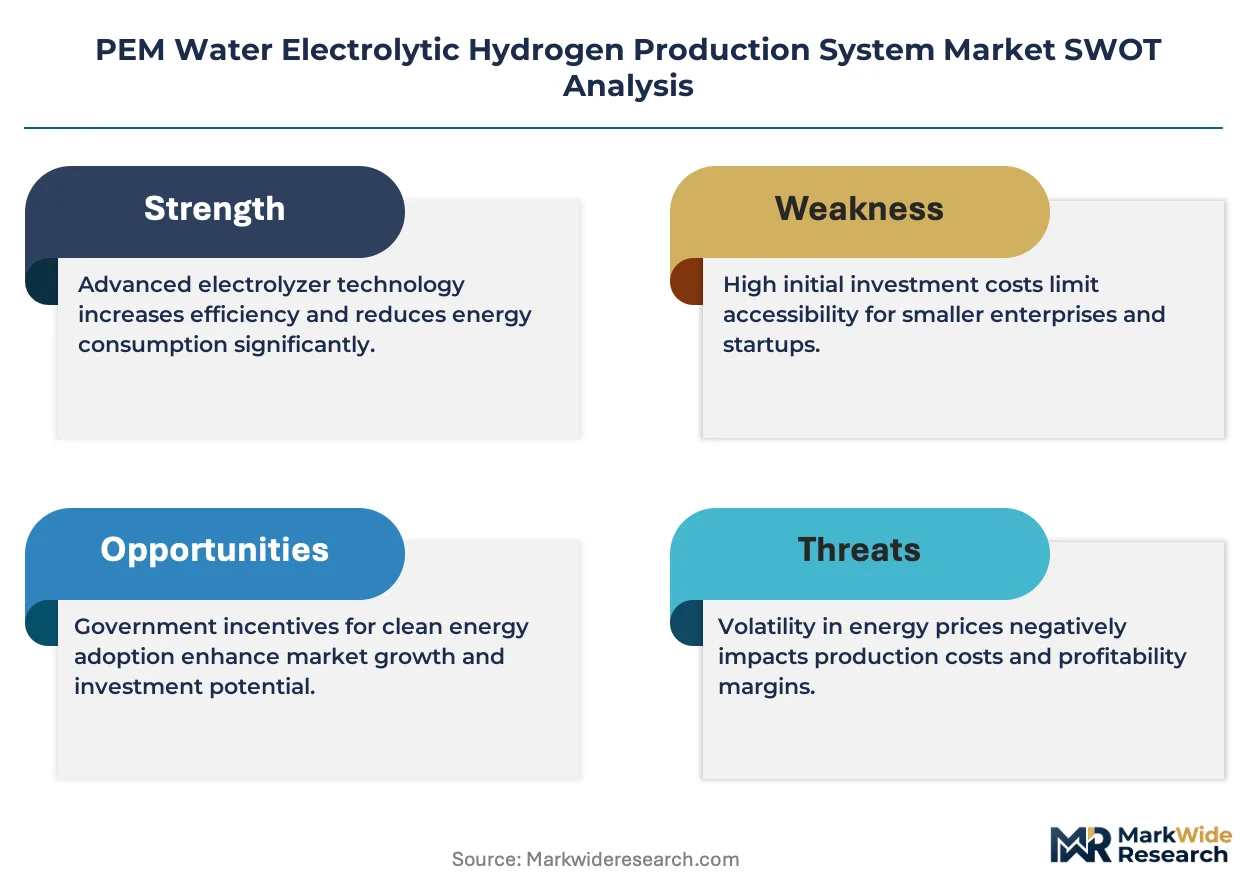
EU Green Deal delegated acts under the Renewable Energy Directive gate qualified supply access for PEM electrolyzer manufacturers, restricting premium-tier pricing to stack designs meeting renewable hydrogen certification thresholds. German industrial buyers now demand 15-year availability guarantees that bundle membrane replacement and refurbishment into levelized cost contracts, compressing equipment-only margins while elevating service-anchored pricing power.
Pricing Analysis
Capacity additions in China are reshaping price floors for alkaline electrolyzer variants, forcing PEM OEMs to differentiate through rapid-response capability and grid-balancing revenue stacking. Three-tier pricing structure across premium, standard, and economy levels separates membrane electrode assembly quality grades, with iridium loading density and Nafion membrane thickness driving differentiation. Cost compression in standard tiers intensifies because Chinese state-owned ammonia producers leverage domestic alkaline manufacturing scale. Cost-sensitive industrial hydrogen buyers in ammonia feedstock switching exhibit highest price sensitivity; German refinery operators securing EU Green Deal certification demonstrate lowest sensitivity due to offtake contract de-risking.
Supply Chain Analysis
Refurbishment flows for membrane electrode assemblies and bipolar plate stacks are consolidating around Siemens Energy's turbine service infrastructure and Nel ASA's Nordic maintenance hubs. Iridium and platinum group metal sourcing concentrates in South Africa and Russia; Nafion membrane production rests on Chemours' US and Belgian manufacturing facilities. Single-source vulnerability in iridium supply exposes membrane electrode assembly costs to geopolitical disruption. Distribution runs through project-specific EPC contractors and renewable developer partnerships rather than stocked inventory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PEM electrolyzer procurement has shifted toward premium specifications as industrial offtake agreements lengthen beyond 10 years, making late-cycle quality differentiation the decisive competitive variable.
For Market Incumbents: Anchor service contract unbundling as the primary defensive mechanism against alkaline electrolyzer cost competition from Chinese manufacturers. Deepen backward integration into membrane electrode assembly capacity to secure iridium loading reduction through atomic layer deposition. METI subsidy allocation and EU Green Deal certification timelines compress delivery windows, making captive catalyst coating expertise essential for margin defense. For New Entrants and Emerging Players: Indian fertilizer producers under PLI scheme allocations represent the most penetrable buyer archetype, with committed manufacturing capacity trailing announced targets by substantial margins. Target grid balancing service bundling as a differentiated go-to-market angle, coupling PEM stacks with battery storage for frequency regulation revenue beyond pure hydrogen sales. Technology licensing to domestic assemblers offers lower capital intensity than full-stack manufacturing entry. For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers with proven atomic layer deposition capabilities and iridium reduction IP. Long-term viability across the projection horizon hinges on membrane chemistry diversification beyond Nafion as REACH perfluorinated substance restrictions tighten. The signal to watch is qualification timelines for hydrocarbon-based membrane prototypes in European OEM 2026 pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Contract Unbundling | Siemens Energy leverages turbine service infrastructure to bundle electrolyzer maintenance with existing power plant contracts. |
| Backward Integration into Catalyst Coating | Atomic layer deposition adoption compresses platinum group metal loadings from 0.5 mg/cm² toward 0.2 mg/cm². |
| Membrane Chemistry Diversification | European OEMs qualify hydrocarbon-based prototypes as REACH amendments threaten Nafion supply continuity. |
| Grid Balancing Service Bundling | Coupling PEM stacks with battery storage enables frequency regulation revenue streams beyond hydrogen sales. |
| Technology Licensing to Domestic Assemblers | Indian PLI scheme gaps create first-mover positioning for licensors avoiding full-stack manufacturing capital. |
Research Methodology
Multiple input streams — electrolyzer OEM engineering directors, utility-scale project developers, membrane supplier technical leads, and industrial hydrogen procurement managers — were reconciled against secondary validation from EU Green Deal delegated acts, METI Green Innovation Fund disclosures, and customs trade data. Primary fieldwork captured stack degradation management practices and membrane replacement cycle economics. Secondary sources included FERC filings for US hydrogen hub developments, IEA hydrogen project databases, and SEC 10-K equipment manufacturer disclosures. Bottom-up stack shipment aggregation and top-down hydrogen demand modeling were triangulated to constrain variance.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through multi-dimensional segmentation: membrane chemistry tier, end-use application, renewable integration architecture, and regional regulatory cluster. CAGRs were derived from fitted adoption curves calibrated to offtake contract announcement velocities. Industry-specific forecast inputs included iridium price volatility bands and CE marking timeline distributions for 30-bar differential pressure systems.
Inputs from OEM engineering directors and utility project developers were available through the study window; gaps in proprietary membrane degradation rate data introduce uncertainty bands around operational lifetime assumptions. Forecasts reflect documented assumptions regarding METI subsidy allocation continuity and EU Green Deal certification threshold stability. Practitioners should monitor REACH perfluorinated substance authorization deadlines and South African mining output disruptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Hydrogen Energy Storage Market
Hydrogen Energy
Hydrogen Powered Engine Market