
 High-Pressure Hydrogen Tanks Market | 2026-2036
High-Pressure Hydrogen Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
High-Pressure Hydrogen Tanks Market Insights
China is rewriting the supply landscape through aggressive capacity build-outs for carbon fiber-wrapped pressure vessels. Worthington Enterprises leverages its North American manufacturing footprint to anchor regional logistics and heavy-transport contracts. Hexagon Purus specializes in Type IV composite systems and extends its position through European fuel-cell bus deployments. Luxfer Group dominates aluminum-lined cylinder architectures and sustains margins via aerospace qualification pathways.
High-pressure hydrogen tanks are cylindrical pressure vessels engineered to store hydrogen gas at operating pressures typically ranging from 350 to 700 bar, constructed from aluminum or polymer liners overwrapped with carbon fiber or glass fiber composites to achieve strength-to-weight ratios critical for mobile applications. Their primary purpose centers on enabling gaseous hydrogen storage and delivery for fuel-cell electric vehicles, industrial feedstock supply, and stationary energy buffering systems. Composite Tanks command the dominant value share due to material substitution trends favoring carbon fiber over metal in weight-sensitive mobility applications, while Type IV Tanks represent the fastest-growing product architecture as fully linerless polymer designs achieve cost-down trajectories through automated filament winding. The Automotive end-user segment concentrates current procurement volumes, though Energy Sector installations for grid-scale storage and hydrogen hub buffering are expanding the addressable demand pool.
DOT-FCV and UN-ECR-134 standards govern North American and European tank certification cycles, while China's GB/T 35544 and NMPA alignment with UN protocols shape product homologation timelines for regional market entry. The EU AI Act and CSRD disclosure mandates are beginning to extend into hydrogen supply chain traceability requirements, pressuring manufacturers to document embedded carbon in composite precursor materials. Stakeholders must monitor evolving tank-recycling regulations and fiber-reuse mandates as jurisdictions tighten circular-economy compliance for composite pressure equipment.
Market Dynamics
Carbon fiber supply concentration and automated filament winding cost curves are compressing Type IV tank economics faster than legacy aluminum-lined architectures can defend incumbent positions.
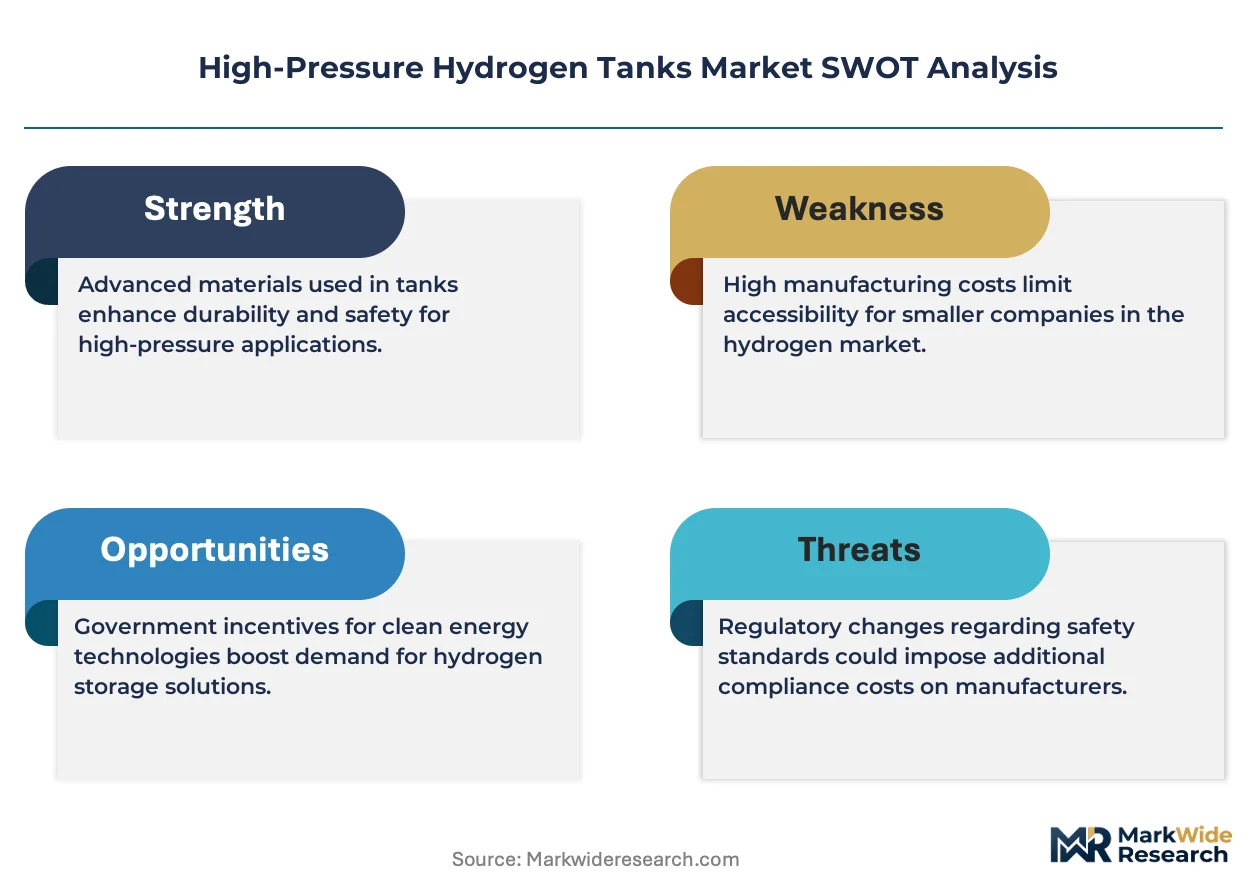
Growth Catalysts
- EU Green Deal Binding Targets:Renewable hydrogen mandates for heavy-duty transport fleets are accelerating refueling infrastructure deployment across Germany, Netherlands, and Denmark.
- Automated Filament Winding:Robotics integration in composite overwrapping is slashing labor content and cycle times for Type IV pressure vessel production.
- Japan METI Roadmaps:Fuel cell commercialization timelines anchor near-term procurement volumes from automotive OEMs and bus fleet operators.
Market Restraints
- Carbon Fiber Precursor Concentration:PAN-based fiber supply clusters in China and Japan, exposing tank fabricators to single-source risk and export control friction.
- DOT-FCV Certification Timelines:North American homologation cycles extend 18-24 months, freezing product iteration speed for non-incumbent suppliers.
- Liquid Hydrogen Storage Competition:Cryogenic tank architectures for maritime and aviation applications threaten to displace compressed gas systems in weight-insensitive segments.
Strategic Opportunities
- Grid-Scale Hydrogen Buffering:Energy sector installations for renewable curtailment storage represent underpenetrated demand outside mobility applications.
- CSRD Supply Chain Traceability:EU disclosure mandates on embedded carbon create first-mover advantage for manufacturers with verified fiber precursor documentation.
- India PLI Scheme Alignment:Domestic hydrogen hub incentives under the National Hydrogen Mission open localization pathways for composite vessel assembly.
Industry Challenges
- Composite Recycling Infrastructure:End-of-life carbon fiber recovery lacks scaled industrial pathways, exposing manufacturers to future circular-economy compliance penalties.
- Filament Winding Technician Scarcity:Automated systems still require skilled operators for machine programming and quality validation, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Pressure Hydrogen Tanks Market |
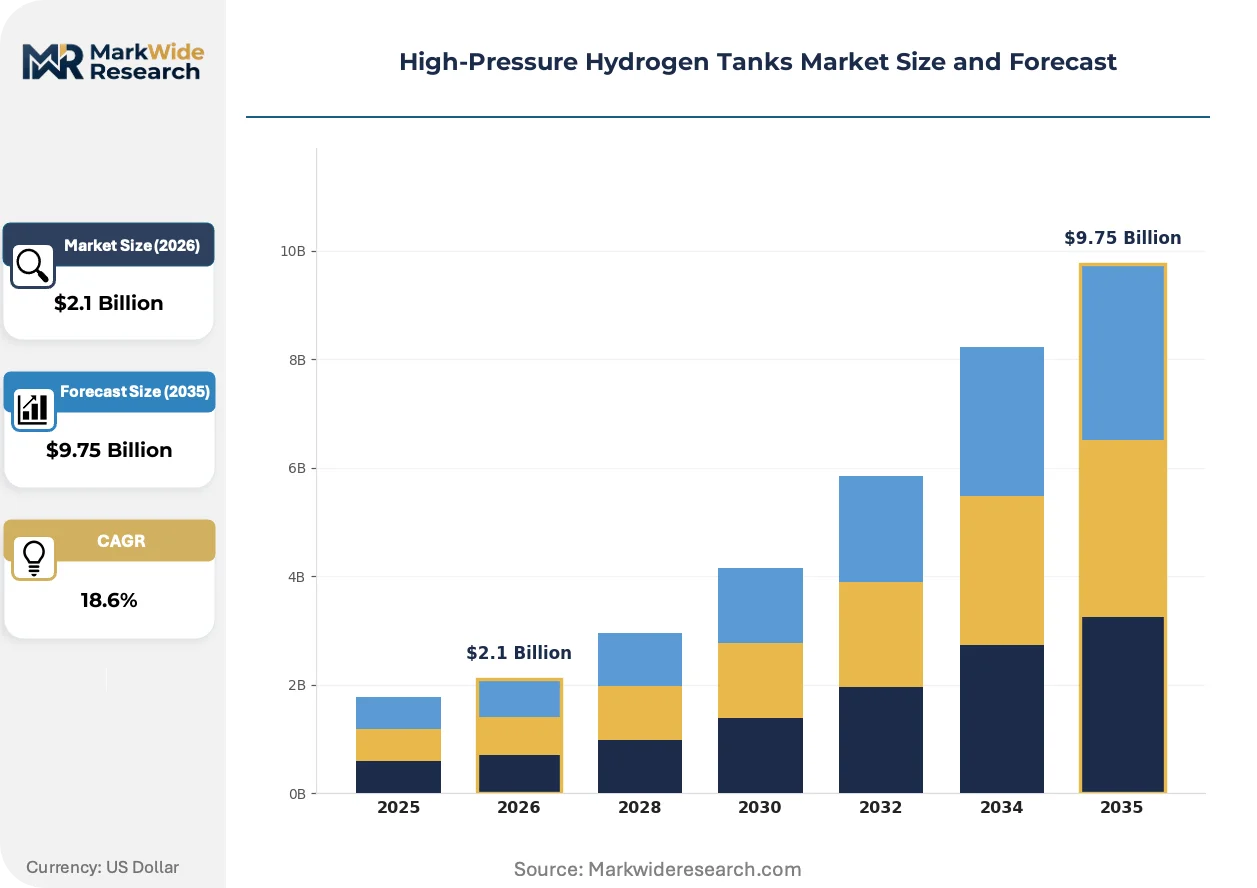
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.75 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Tanks, Metal Tanks, Type IV Tanks, Type III Tanks Application: Hydrogen Storage, Transportation, Fuel Cells, Industrial Use End User: Automotive, Aerospace, Energy Sector, Research Institutions Installation: Onshore, Offshore, Mobile, Stationary |
| Companies Covered | Worthington Enterprises, Luxfer Group, Hexagon Purus, Quantum Fuel Systems LLC, Faber Industrie S.p.A., Everest Kanto Cylinder Ltd., Beining Tianhai Industry Co. Ltd., NPROXX, Composite Advanced Technologies, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Pressure Hydrogen Tanks Market Trends and Innovations
Digital thread integration across design-to-manufacture workflows is compressing tank development cycles while regulatory pressure on embodied carbon forces material provenance transparency.
Automated in-situ monitoring systems using embedded fiber optic sensors are digitizing real-time pressure and strain telemetry for operational safety validation. Fleet operators in European fuel-cell bus deployments are mandating these systems for predictive maintenance contracts. The technology is digitizing warranty risk allocation between tank fabricators and vehicle integrators.
China's GB/T 35544 alignment with UN-ECR-134 protocols is harmonizing test protocols for pressure cycling and permeation rates. This convergence reduces duplicate certification costs for suppliers serving both domestic and export markets. Japanese and Korean automotive OEMs are accelerating homologation timelines for dual-certified tank architectures.
Buyers are consolidating procurement under long-term supply agreements with embedded volume commitments and price corridors. Heavy-duty trucking fleet operators are displacing spot-market purchasing with 5-7 year offtake contracts tied to hydrogen delivery guarantees. This pattern is most visible in German and Dutch logistics corridors where refueling infrastructure density supports committed fleet conversions.
High-Pressure Hydrogen Tanks Market Segmentation
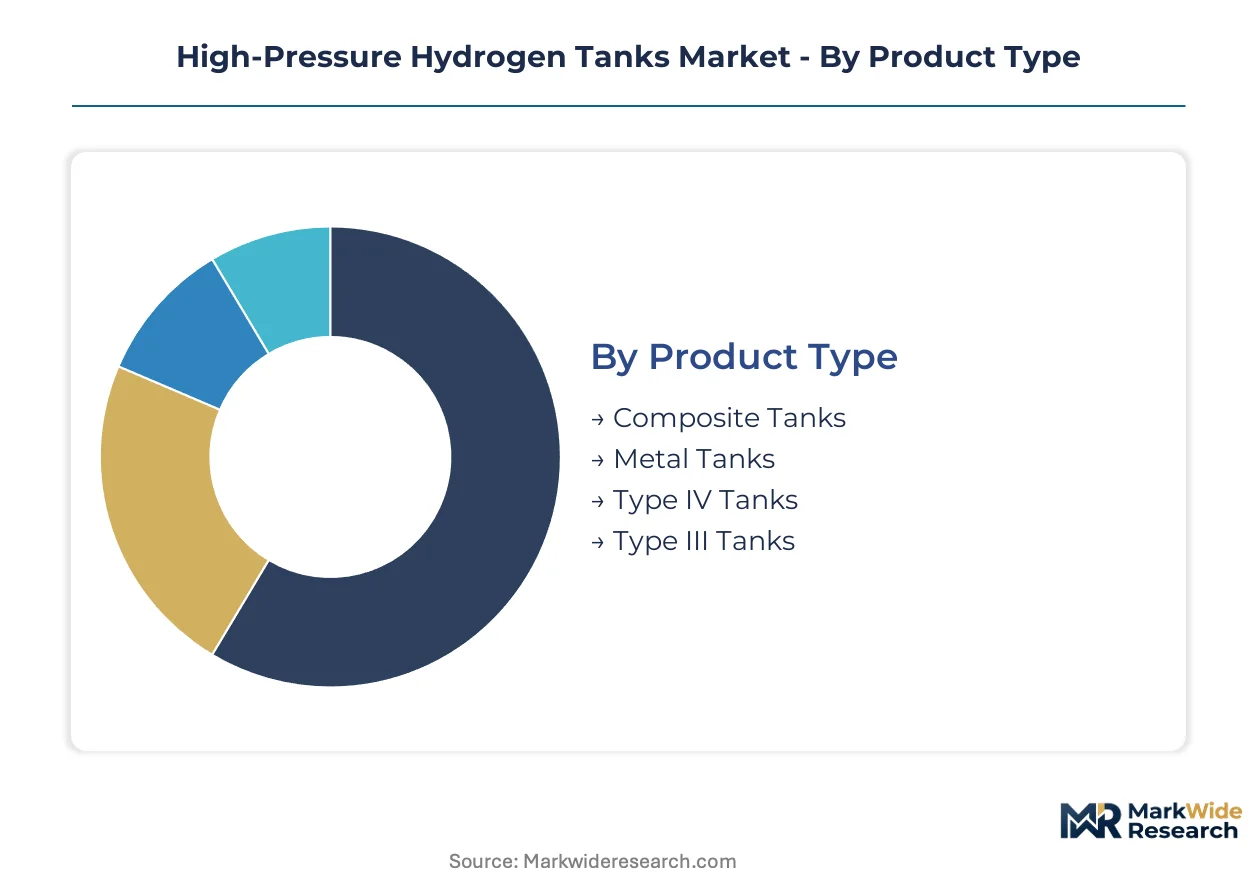
Segmentation in high-pressure hydrogen tanks determines certification pathways, manufacturing scale economics, and service lifecycle intensity. Tank architecture choices cascade into filament winding automation requirements and regional homologation strategies.
Product Type:
After-sales service intensity varies sharply across liner technologies, with composite-overwrapped systems demanding specialized inspection protocols and fiber-optic monitoring recalibration.
- Composite Tanks:Carbon fiber or glass fiber overwrap on aluminum or polymer liners delivers strength-to-weight ratios exceeding 700 bar operating pressure. Heavy-duty trucking fleets in Germany specify these for fuel-cell electric tractors under EU Green Deal procurement mandates.
- Type IV Tanks:Fully linerless polymer designs eliminate metal fatigue pathways and enable automated filament winding at scale. Japanese automotive OEMs anchor near-term procurement through METI-backed commercialization roadmaps.
- Metal Tanks:Aluminum or steel monolithic construction persists in stationary industrial buffering where weight penalties are tolerable.
- Type III Tanks:Aluminum-lined carbon fiber overwrap occupies intermediate positions in aerospace qualification pathways.
By volume, Composite Tanks lead. By growth pace, Type IV Tanks are climbing the fastest.
Application:
Application segmentation maps directly to pressure cycling frequency and regulatory scrutiny intensity.
- Fuel Cells:Onboard vehicle storage at 350-700 bar demands permeation rates below 6 NmL/hr/L and embedded sensor telemetry for predictive maintenance. Korean bus fleet operators mandate real-time pressure validation for warranty coverage.
- Transportation:Tube trailer and maritime container systems prioritize volumetric efficiency and rapid fill protocols. Dutch logistics corridors are scaling dedicated hydrogen delivery infrastructure under binding renewable targets.
- Hydrogen Storage:Stationary buffering for renewable curtailment operates at lower pressure tiers with extended cycle lifetimes.
- Industrial Use:Refinery feedstock and chemical process supply chains specify legacy certification frameworks with longer replacement horizons.
Fuel Cells concentrate current procurement spend. Transportation applications are expanding most quickly as heavy-duty fleet conversions accelerate.
End User:
End user segmentation reveals divergent qualification burdens and volume concentration patterns.
- Automotive:Passenger and commercial vehicle OEMs drive standardization through UN-ECR-134 and DOT-FCV harmonization efforts. Chinese manufacturers are scaling Type IV capacity for domestic fuel-cell vehicle programs aligned with GB/T 35544.
- Energy Sector:Grid-scale hydrogen hubs and renewable storage installations represent emerging demand outside mobility applications. German utility operators are piloting 100MWh buffering arrays for seasonal electricity shifting.
- Aerospace:FAA and EASA qualification pathways sustain premium pricing for aluminum-lined architectures with extensive test documentation.
- Research Institutions:Specialized geometries and custom pressure ratings serve laboratory and demonstration project requirements.
Automotive commands installed base volume. Energy Sector installations are gaining share fastest as hydrogen hub deployments multiply.
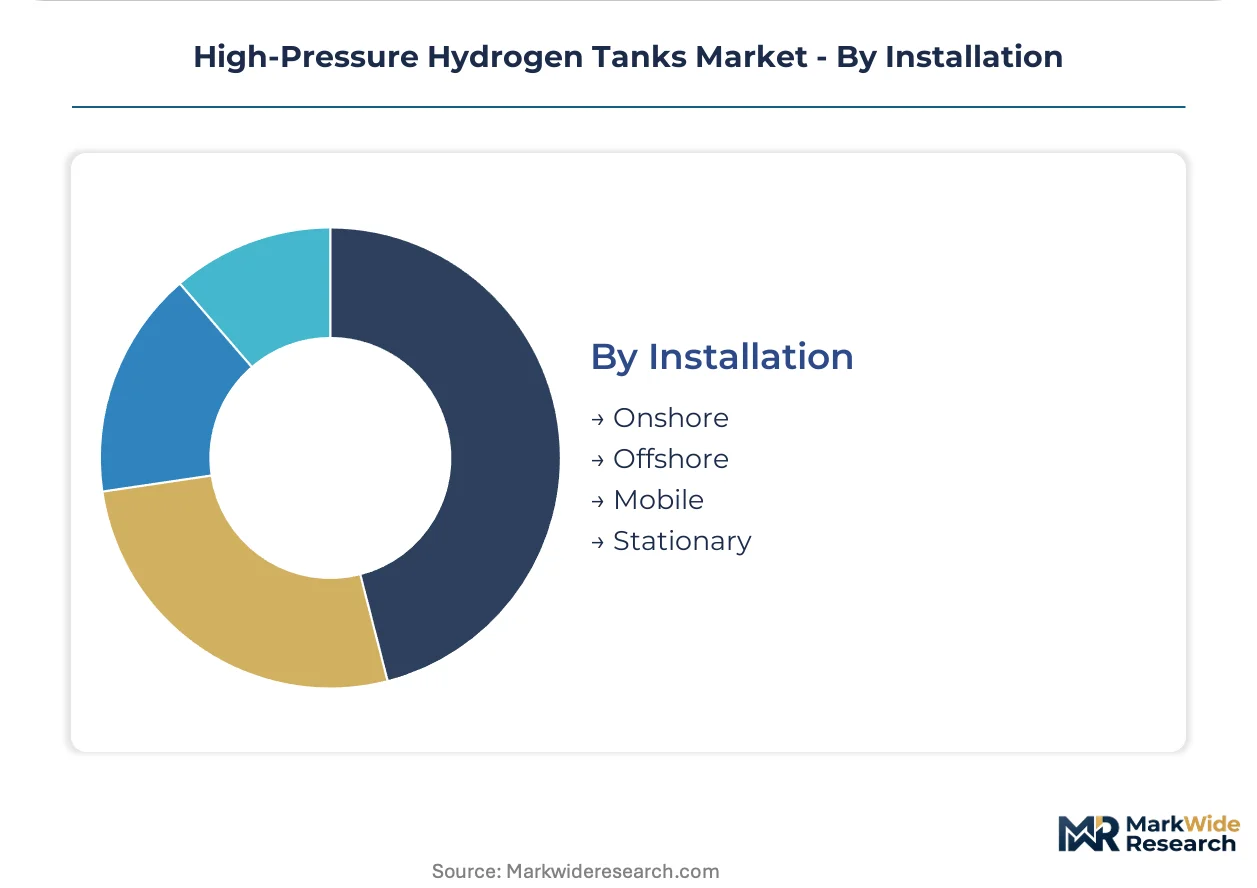
Installation:
Installation mode determines environmental exposure, inspection accessibility, and replacement logistics.
- Mobile:Vehicle-integrated systems face vibration, thermal cycling, and crash safety validation under UN-ECR-134. European fuel-cell bus fleets are mandating embedded fiber optic monitoring for operational telemetry.
- Stationary:Fixed installations at refueling stations and industrial sites prioritize volumetric density and automated pressure management.
- Onshore:Land-based tube trailers and buffering systems dominate current logistics infrastructure.
- Offshore:Maritime and subsea applications face corrosion-resistant material specifications and specialized certification timelines.
Mobile installations lead by unit volume. Stationary systems are expanding most quickly as refueling infrastructure density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber precursor manufacturing clusters in China and Japan concentrate upstream supply, while European demand accelerates under binding renewable hydrogen mandates. German logistics corridors and Japanese automotive OEMs anchor near-term procurement volumes. Regional certification divergence persists despite UN-ECR-134 harmonization efforts.
China
Domestic capacity build-outs for carbon fiber-wrapped pressure vessels are scaling under GB/T 35544 alignment with UN protocols. The National Medical Products Administration and MIIT coordinate test protocol harmonization to reduce duplicate certification costs for export-bound suppliers. Yangtze River Delta manufacturing clusters near Shanghai are automating filament winding lines for Type IV tank production.
Germany
Heavy-duty trucking fleets are converting under EU Green Deal binding targets for renewable hydrogen in transport. The KBA governs tank homologation cycles while ECHA tracks embedded carbon in composite precursors under REACH extension pathways. Dutch-German logistics corridors between Rotterdam and Duisburg are scaling dedicated refueling infrastructure with committed fleet offtake contracts.
Japan
Automotive OEMs anchor near-term demand through METI-backed fuel cell commercialization roadmaps with specified procurement timelines. The Ministry of Economy, Trade and Industry coordinates standardization with JIS alignment to UN-ECR-134 for dual-certified architectures. Kansai region manufacturing bases near Osaka are integrating embedded fiber optic monitoring systems for operational telemetry.
United States
North American manufacturing footprints are securing regional logistics and heavy-transport contracts under DOT-FCV certification pathways. The Department of Transportation and NHTSA govern 18-24 month homologation cycles that freeze product iteration speed for non-incumbent suppliers. California hydrogen hub deployments are piloting grid-scale buffering arrays for seasonal electricity shifting.
India
National Hydrogen Mission incentives are opening localization pathways for composite vessel assembly under PLI scheme alignment. The Bureau of Indian Standards and central electricity authority coordinate pressure equipment regulations with emerging hydrogen hub standards. Gujarat and Maharashtra industrial corridors are attracting filament winding capacity for domestic fuel-cell bus programs.
High-Pressure Hydrogen Tanks Market Competitive Landscape
Diversified industrial conglomerates and specialized composite fabricators split the market into distinct capability tiers. Tier-one positions concentrate around firms with aerospace qualification pathways and automated winding scale. Three archetypes dominate: integrated materials-to-systems suppliers, pure-play composite pressure vessel specialists, and aluminum-lined legacy incumbents. Competitive dynamics center on backward integration into carbon fiber precursor supply and geographic expansion through regional manufacturing footprints.
Among North American and European fabricators, Worthington Enterprises, Luxfer Group, and Hexagon Purus occupy differentiated positions within this structure. Worthington exemplifies the diversified industrial archetype with broad manufacturing reach. Luxfer represents legacy aluminum-lined expertise sustained through premium qualification pathways. Hexagon Purus anchors the composite specialist tier with European fuel-cell deployment exposure. Each occupies a distinct competitive vector without direct portfolio overlap.
| Leading Market Players |
|---|
| Worthington Enterprises |
| Luxfer Group |
| Hexagon Purus |
| Quantum Fuel Systems LLC |
| Faber Industrie S.p.A. |
| Everest Kanto Cylinder Ltd. |
| Beining Tianhai Industry Co. Ltd. |
| NPROXX |
| Composite Advanced Technologies, LLC |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese carbon fiber precursor manufacturing is compressing Type IV tank pricing while forcing European and North American fabricators into defensive margin postures. This utilization dynamic rewards buyers with volume leverage and punishes suppliers lacking automated filament winding scale.
Pricing Analysis
UN-ECR-134 and DOT-FCV certification tiers dictate the pricing structure across Type III, Type IV, and legacy metal architectures. Three-tier pricing separates aerospace-qualified aluminum-lined systems from automotive-grade Type IV composites and industrial metal tanks. Cost compression in Type IV manufacturing is intensifying because automated winding lines are slashing labor content per vessel. Heavy-duty trucking fleet operators exhibit the highest price sensitivity, while aerospace integrators tolerate premium positioning for extensive test documentation.
Supply Chain Analysis
Extended payment terms from Japanese automotive OEMs and supply-chain finance facilities from European hydrogen hub developers are reshaping working capital requirements for filament winding specialists. PAN-based carbon fiber supply clusters in China, Japan, and South Korea anchor upstream concentration. Raw material dependencies center on acrylonitrile precursors, epoxy resin systems, and high-density polyethylene liners. Single-source vulnerability in PAN precursor supply exposes fabricators to export control friction. Distribution runs through long-term offtake contracts with embedded volume commitments rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high-pressure hydrogen tanks market is recovering from certification bottleneck cyclicality as UN-ECR-134 and GB/T 35544 harmonization accelerates product iteration timelines. This regulatory convergence cycle is releasing pent-up procurement demand from automotive OEMs and energy sector developers.
For Market Incumbents: Build certification moats by accelerating dual-UN/DOT qualification pathways before harmonization windows close. Secure captive carbon fiber precursor supply through backward integration or long-term offtake agreements with Chinese and Japanese suppliers. Expand filament winding capacity in the Yangtze River Delta and Kansai region manufacturing clusters to anchor regional logistics contracts. Threat exposure concentrates in liquid hydrogen cryogenic systems displacing compressed gas architectures in maritime applications. For New Entrants and Emerging Players: Pursue grid-scale hydrogen buffering installations for renewable curtailment storage as the most penetrable demand segment outside mobility applications. Target Indian National Hydrogen Mission incentives under PLI scheme alignment for domestic assembly localization. European fuel-cell bus deployments offer lower certification barriers than automotive OEM supply chains. A go-to-market angle centered on embedded fiber optic monitoring systems differentiates against incumbent warranty offerings. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among composite pressure vessel specialists with long-term fleet service contracts and predictive maintenance telemetry subscriptions. Five-to-ten year viability favors firms with aerospace qualification pathways sustaining premium pricing and automated winding scale achieving cost-down trajectories. Acquisition target archetypes include regional filament winding specialists with UN-ECR-134 certification progress and established hydrogen hub supplier relationships. The signal to watch is CSRD-aligned embedded carbon documentation capabilities as a compliance differentiator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor | Captive PAN supply insulates against Japanese and Chinese export control friction. |
| Automated Filament Winding Scale-Up | Robotics integration slashes Type IV tank labor content and cycle times. |
| Dual Certification Pathway Investment | UN-ECR-134 and DOT-FCV alignment reduces duplicate homologation costs. |
| Embedded Sensor Telemetry Development | Fiber optic monitoring systems digitize warranty risk allocation with fleet operators. |
| Grid-Scale Buffering Array Deployment | German utility pilots for seasonal electricity shifting open energy sector demand. |
Research Methodology
Cross-validation between primary interviews with tank fabricator engineering directors and secondary validation through UN-ECR-134 homologation databases anchors the qualitative findings. Stakeholder roles engaged include filament winding plant managers, automotive OEM fuel cell procurement leads, hydrogen hub project developers, aerospace qualification specialists, and refueling infrastructure EPC contractors. Secondary sources encompass DOT-FCV certification filings, MIIT production capacity disclosures, METI commercialization roadmaps, and EU Green Deal implementation tracking. Bottom-up tank production estimates and top-down hydrogen demand projections provide triangulation.
Calibration against historical certification cycle durations and capacity utilization rates in Chinese carbon fiber manufacturing informs the projection framework. Segmentation dimensions modeled span tank architecture type, liner technology, end-user industry, installation mode, and regional regulatory cluster. CAGRs derive from pressure vessel procurement volume trajectories tied to fuel cell vehicle deployment timelines and hydrogen hub construction schedules. Industry-specific inputs include filament winding automation adoption curves and carbon fiber precursor price elasticity assumptions.
Sensitivities concentrate around METI roadmap revision, EU Green Deal target adjustments, and carbon fiber export control escalation. Forecasts reflect documented assumptions on homologation harmonization progress and automated winding cost-down trajectories. Macroeconomic contraction, regulatory fragmentation, or breakthrough liquid hydrogen storage economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
Liquid Hydrogen Tank Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
Solar Hydrogen Panel Market