
 Qatar Oil and Gas Upstream Market | 2026-2036
Qatar Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Oil and Gas Upstream Market Analytics
Multi-source contracting for offshore engineering and drilling services is realigning procurement patterns across Qatar's upstream sector. Qatar Petroleum anchors the state's hydrocarbon strategy through direct equity stakes in all major concession blocks. Shell leverages deepwater technical expertise across the North Field complex. Total S.A. competes for subsea infrastructure contracts tied to liquefaction train expansions.
Qatar oil and gas upstream operations encompass exploration, development, and production of crude oil, natural gas, condensates, and associated gas from onshore and offshore reservoirs, typically employing directional drilling and subsea completion systems at depths exceeding 1,500 meters to sustain reservoir pressure and maximize recovery rates. The primary purpose centers on feedstock supply to liquefaction facilities for export to Asian and European gas markets. Production from natural gas and condensates dominates revenue contribution given Qatar's position as the world's largest LNG exporter. Seismic survey and drilling technology segments attract disproportionate capital allocation as operators map the North Field's southern extension. Engineering services within the service type category command premium margins due to specialist scarcity in ultra-deepwater project design.
Qatar's Ministry of Environment and Climate Change enforces marine protection standards that shape offshore drilling schedules and environmental impact assessment requirements. The General Authority of Customs and the Qatar Financial Centre Regulatory Authority govern equipment import flows and foreign contractor licensing frameworks. Stakeholders must monitor how domestic content requirements and local workforce quotas evolve as project complexity intensifies.
Market Dynamics
The North Field expansion timeline is compressing contractor mobilization schedules as QatarEnergy accelerates liquefaction train commissioning to meet offtake obligations with European and Asian buyers.
Growth Catalysts
- North Field East and South development:Ultra-deepwater production infrastructure deployment is pulling specialized drilling and subsea engineering capacity into Qatari waters. Reservoir characterization programs are expanding seismic survey scope across the southern extension.
- Domestic content requirements:The Ministry of Environment and Climate Change mandates local workforce quotas and supplier participation thresholds that redirect procurement toward Qatari-registered service firms.
- Directional drilling advancement:Extended-reach horizontal wells are accessing multiple reservoir zones from single surface locations, reducing offshore platform density while sustaining production rates.
Market Restraints
- Specialized vessel scarcity:Ultra-deepwater pipelay and heavy-lift vessel availability concentrates with a limited fleet of contractors, creating bottleneck risk for simultaneous North Field East and South construction phases.
- Steel alloy input volatility:Corrosion-resistant alloys for subsea manifolds and flowlines face price instability tied to nickel and molybdenum commodity markets, compressing fabrication margin forecasts.
- Environmental assessment timelines:Marine protection standards enforced by the Ministry of Environment and Climate Change extend permitting durations for seismic operations in sensitive habitat zones.
Strategic Opportunities
- Carbon capture integration:Associated gas processing facilities offer anchor demand for point-source capture systems, aligning with QatarEnergy's low-carbon LNG positioning for European offtakers.
- Digital twin deployment:Subsea asset performance monitoring is converging with predictive maintenance platforms, creating service contracts spanning engineering and data analytics functions.
- Ras Laffan industrial zone expansion:Downstream clustering around existing liquefaction infrastructure supports integrated development models linking upstream production with petrochemical feedstock supply.
Industry Challenges
- Subsea systems engineering capacity:Specialist design firms capable of ultra-deepwater manifold and tie-in configurations face stretched resource allocation across multiple concurrent megaprojects.
- Legacy platform integration:Brownfield modifications to existing North Field infrastructure must accommodate higher-pressure, higher-temperature reservoir conditions without disrupting continuous production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Oil and Gas Upstream Market |
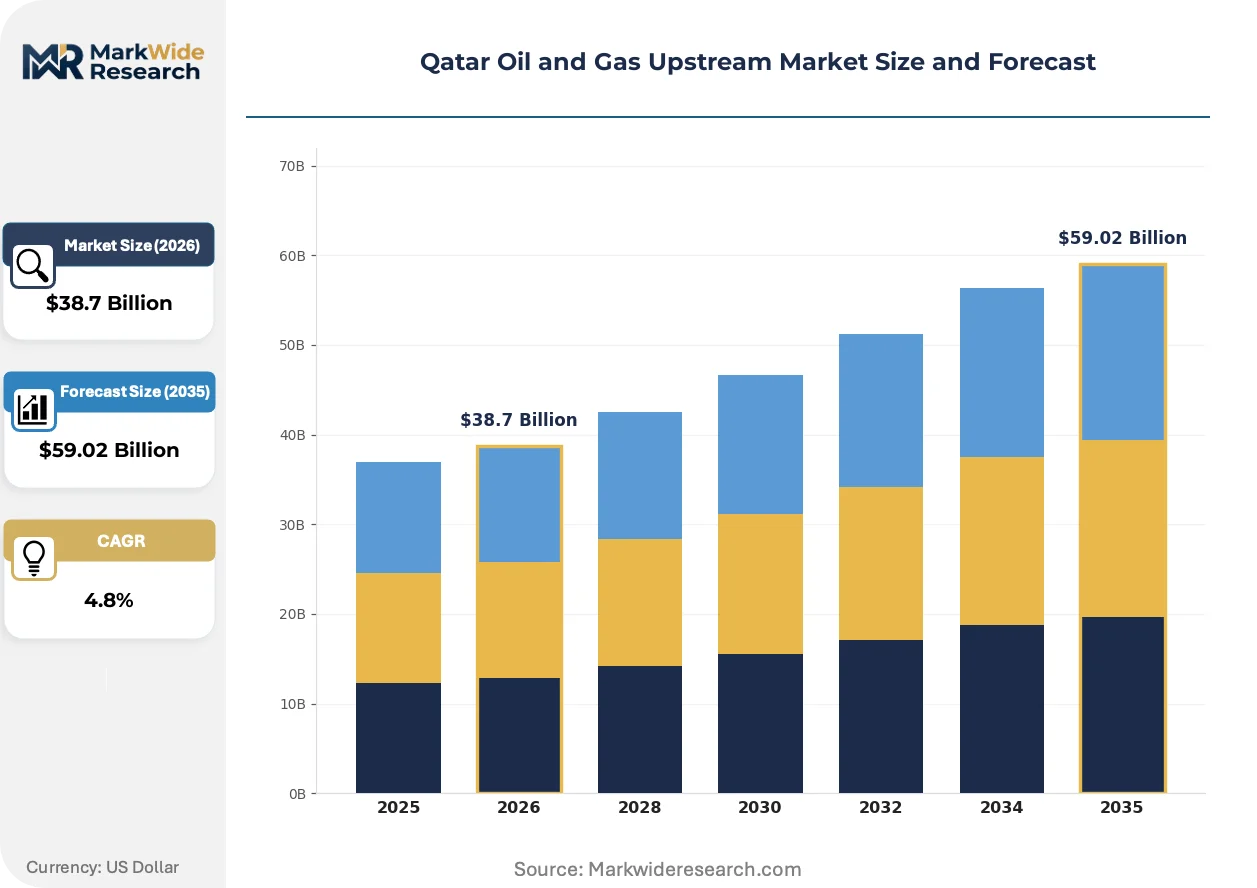
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Seismic Survey, Drilling, Completion, Production Service Type: Engineering Services, Maintenance, Asset Management, Supply Chain Management Product Type: Oil, Natural Gas, Condensates, Associated Gas End User: Exploration Companies, National Oil Companies, Independent Producers, Service Providers |
| Companies Covered | ConocoPhillips Company, Shell, Qatar Petroleum, Chevron Corporation, BP, Qatargas Operating Company Limited, Total S.A., Occidental Petroleum Corporation, Exxon Mobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Oil and Gas Upstream Market Evolving Landscape
Automation and remote operations are reconfiguring offshore staffing models while digital infrastructure investments reshape how reservoir data flows into development decisions.
Managed pressure drilling is converging with real-time downhole telemetry to maintain precise annular pressure control across the North Field's fractured carbonate formations. QatarEnergy and its drilling contractors are deploying these systems on exploration and appraisal wells to reduce non-productive time. The technology is converging with automated well control protocols that compress response times to kick detection, enabling narrower operational windows without escalating safety risk.
Qatar's Ministry of Environment and Climate Change has tightened marine discharge standards for drilling fluids and produced water, extending treatment system requirements for offshore platforms. Operators must now install enhanced solids control and wastewater processing packages before receiving drilling permits. Subsea infrastructure contractors are responding by specifying closed-loop systems in platform engineering packages to preempt regulatory delay.
Long-term service agreements are displacing discrete project contracting as QatarEnergy seeks to lock in engineering and construction capacity across the North Field expansion timeline. Integrated project delivery models now bundle front-end engineering with fabrication and installation scope under single-source arrangements. This concentration is most visible in subsea production system procurement, where QatarEnergy has moved toward alliance structures with preferred contractors.
Qatar Oil and Gas Upstream Market Segmentation
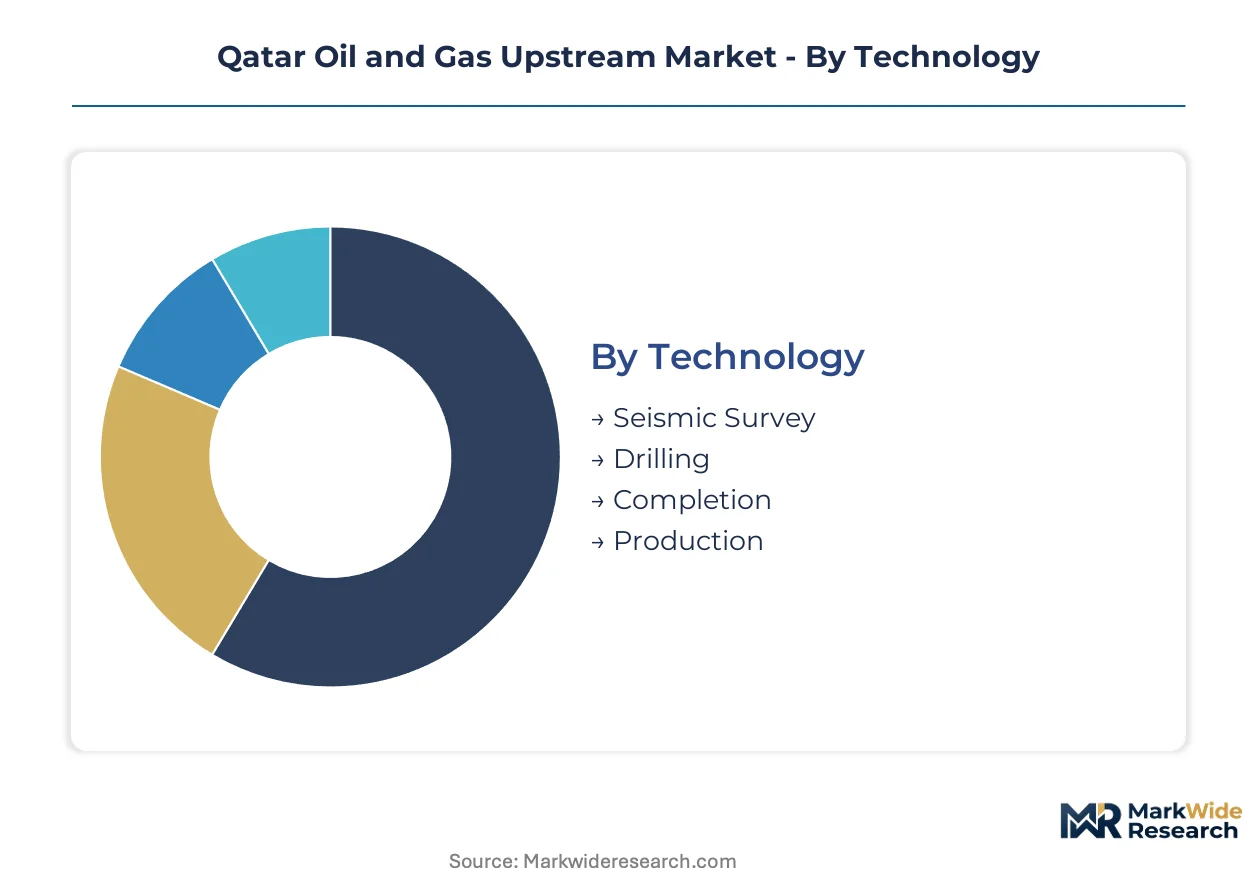
Upstream segmentation in Qatar reflects capital allocation priorities across the North Field expansion timeline. Technology and service categories map directly to contractor procurement patterns, while product and end-user dimensions track revenue concentration toward LNG feedstock supply.
Technology:
Upgrade cycles for offshore equipment are compressing as QatarEnergy accelerates North Field East and South development schedules.
- Seismic Survey:High-resolution 3D and 4D seismic acquisition maps the North Field's southern extension where reservoir complexity demands advanced imaging. QatarEnergy has expanded survey scope across ultra-deepwater blocks to reduce appraisal well counts.
- Drilling:Managed pressure drilling systems with real-time telemetry maintain annular pressure control across fractured carbonate formations. Extended-reach horizontal wells access multiple reservoir zones from single surface locations, cutting platform density.
- Completion:Subsea completion hardware withstands high-pressure, high-temperature conditions at depths exceeding 1,500 meters.
- Production:Artificial lift and subsea boosting systems sustain flow rates from mature North Field wells.
Seismic Survey sits at the top of the volume ranking, with Drilling climbing the fastest.
Service Type:
Cost tiers separate specialist engineering from commoditized maintenance functions across Qatar's contractor base.
- Engineering Services:Front-end design for ultra-deepwater manifolds and tie-in configurations commands premium margins due to specialist scarcity. QatarEnergy has shifted toward alliance structures bundling engineering with fabrication scope.
- Maintenance:Brownfield modifications to existing North Field infrastructure accommodate higher-pressure reservoir conditions without production disruption.
- Asset Management:Digital twin deployment for subsea performance monitoring converges predictive maintenance with data analytics.
- Supply Chain Management:Procurement coordination navigates domestic content requirements and local workforce quotas mandated by the Ministry of Environment and Climate Change.
Engineering Services captures the highest margin tier, while Asset Management expands most quickly through digitalization mandates.
Product Type:
Application focus distinguishes LNG feedstock supply from liquid hydrocarbon export streams.
- Natural Gas:Dry gas feedstock dominates QatarEnergy's liquefaction train commitments to European and Asian offtakers. North Field expansion targets capacity additions aligned with long-term purchase agreements.
- Condensates:Light liquid fractions from gas processing yield premium pricing in Asian refining markets. Production volumes track closely with LNG train throughput.
- Oil:Limited onshore and offshore crude production contributes minor revenue share against gas-dominated output.
- Associated Gas:Gas caps and dissolved gas from oil reservoirs supplement primary natural gas supply for domestic power generation.
Natural Gas leads absolute volume, with Condensates gaining share fastest on Asian demand.
End User:
Customer concentration shapes contracting structures from integrated project delivery to discrete service procurement.
- National Oil Companies:QatarEnergy anchors all major concession blocks through direct equity stakes, centralizing procurement decisions across the North Field complex. Long-term service agreements now displace discrete project contracting.
- Exploration Companies:International partners participate through production-sharing arrangements on specific offshore blocks.
- Independent Producers:Smaller operators focus on marginal field development and enhanced recovery from mature reservoirs.
- Service Providers:Drilling contractors and subsea specialists execute front-end engineering through installation scope under QatarEnergy-directed alliance structures.
National Oil Companies concentrate procurement authority, with Service Providers experiencing the steepest contract volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ras Laffan Industrial City anchors Qatar's upstream sector through its liquefaction and petrochemical clustering. The North Field complex drives capital allocation toward ultra-deepwater development zones. Ministry of Environment and Climate Change regulations shape offshore permitting timelines across all operational areas.
North Field East
QatarEnergy directs liquefaction train construction and subsea infrastructure deployment across this northern extension. The Ministry of Environment and Climate Change mandates marine protection buffers that extend environmental assessment durations. Ras Laffan serves as the primary logistics hub for module fabrication and heavy-lift vessel mobilization.
North Field South
Seismic survey programs map reservoir complexity across the southern extension where appraisal drilling intensifies. Domestic content requirements redirect procurement toward Qatari-registered engineering firms. The Industrial Area of Doha supports fabrication yards supplying subsea manifolds and flowline components.
Al Shaheen Field
Heavy oil production from this offshore block requires enhanced recovery systems and artificial lift infrastructure. The General Authority of Customs governs specialized equipment import flows for drilling contractors. Port of Ras Laffan handles crude export logistics alongside LNG cargo operations.
Al Khaleej Field
Associated gas processing facilities supply feedstock to domestic power generation and industrial consumers. Qatar Financial Centre Regulatory Authority frameworks license foreign contractors executing brownfield modifications. Mesaieed Industrial City clusters downstream processing capacity linking to upstream production streams.
Dukhan Field
Onshore crude production from mature reservoirs depends on waterflood programs and well workover campaigns. Ministry of Environment and Climate Change standards govern produced water treatment and disposal systems. Dukhan township anchors workforce accommodation for onshore operational crews.
Qatar Oil and Gas Upstream Market Competitive Landscape
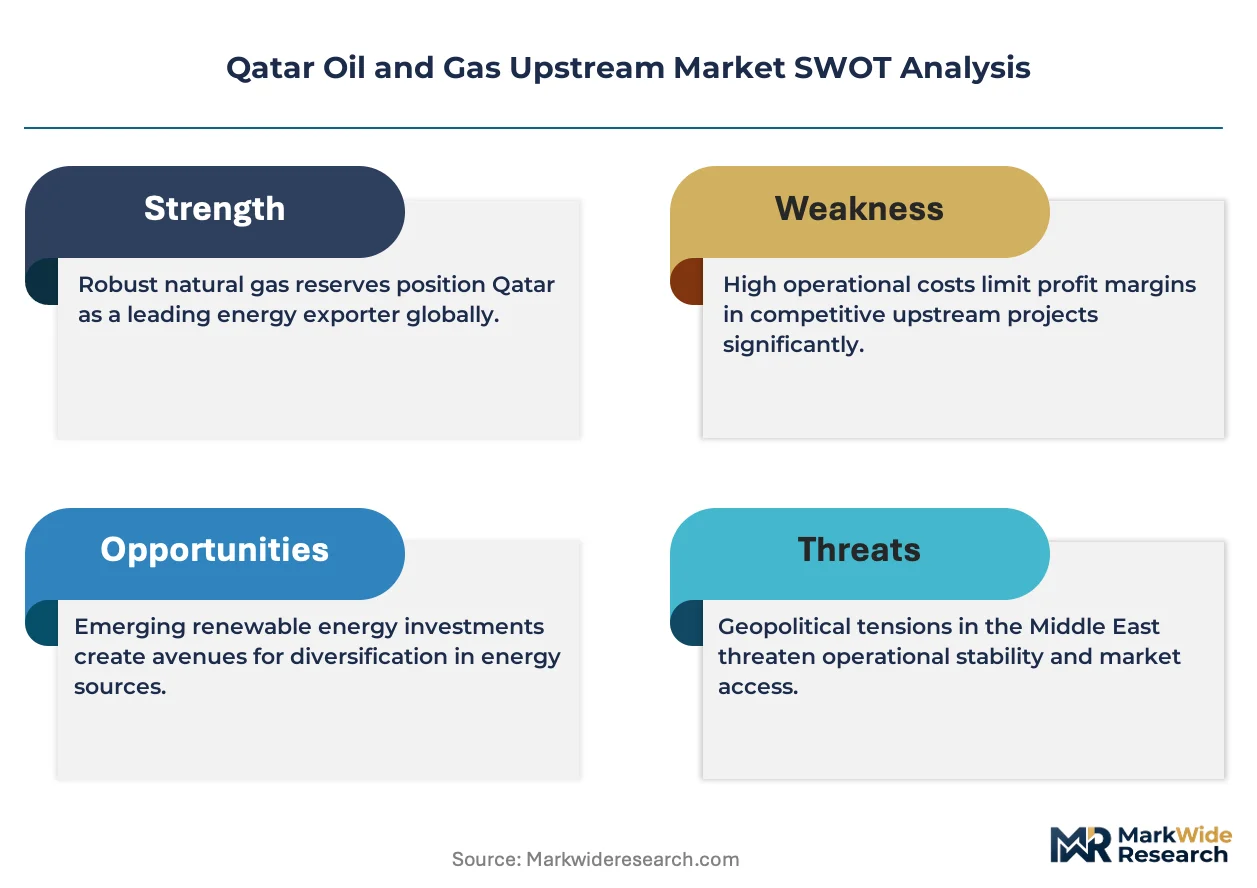
Global majors compete with regional champions across concession equity and service contracting dimensions. Qatar Petroleum holds direct stakes in all major blocks, creating a concentrated national champion structure. Three archetypes dominate: integrated supermajors leveraging deepwater expertise, national oil companies controlling equity and procurement decisions, and specialized subsea contractors executing engineering and installation scope. Competitive moves center on long-term alliance structures replacing discrete project awards, and integrated project delivery models bundling front-end engineering with fabrication.
Within the supermajor tier, Shell and Total S.A. exemplify technical positioning through subsea system deployment and liquefaction infrastructure partnerships. Qatar Petroleum anchors the national champion archetype through direct operational control across the North Field complex. ConocoPhillips Company occupies a position among international partners participating through production-sharing arrangements on specific offshore blocks.
| Leading Market Players |
|---|
| ConocoPhillips Company |
| Shell |
| Qatar Petroleum |
| Chevron Corporation |
| BP |
| Qatargas Operating Company Limited |
| Total S.A. |
| Occidental Petroleum Corporation |
| Exxon Mobil Corporation |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers anchor Qatar's upstream sector through QatarEnergy's direct equity control across all major concession blocks, compressing procurement timelines while enforcing rigid cost discipline through long-term service agreements that displace spot-market contracting.
Pricing Analysis
Input-cost pass-through from corrosion-resistant alloys and specialized vessel day-rates directly shapes subsea fabrication and drilling service quotes. Contract-based long-term offtake structures dominate, with price differentiation driven by certification tier and volume scale commitments to liquefaction train operators. Pricing pressure stems from nickel and molybdenum commodity volatility squeezing fabrication margins. National oil companies exhibit lowest price sensitivity given captive feedstock demand, while independent service providers face acute margin compression on commoditized maintenance scopes.
Supply Chain Analysis
Domestic content requirements mandated by Qatar's Ministry of Environment and Climate Change are redirecting procurement toward Qatari-registered engineering firms and local fabrication yards. Geographic supply concentration centers on South Korea, Singapore, and the United Arab Emirates for subsea manifolds and heavy-lift vessels. Raw material dependencies draw from specialty steel mills, high-pressure valve manufacturers, and subsea umbilical producers. Single-source vulnerability concentrates in ultra-deepwater pipelay vessel availability. Distribution runs through Ras Laffan Industrial City as the primary logistics hub for module integration and offshore mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's upstream market represents a late-cycle quality story as European offtakers shift purchase criteria toward low-carbon LNG specifications, rewarding operators with integrated carbon capture positioning.
For Market Incumbents: Cement alliance structures with preferred subsea contractors to lock in engineering capacity across concurrent North Field East and South development phases. Deepen backward integration into specialty steel procurement to defend margin position against nickel alloy price volatility. Prioritize certification investment in carbon capture readiness to meet evolving European offtake specifications.
For New Entrants and Emerging Players: Marginal field operators and enhanced recovery specialists represent an underserved buyer archetype with unmet demand for artificial lift and brownfield modification services. Target Dukhan Field waterflood program expansions and Al Shaheen heavy oil recovery optimization as the most penetrable segments. Pursue direct contracting relationships with QatarEnergy's technical services division rather than tier-two subcontractor positioning.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialist subsea engineering firms with proven ultra-deepwater manifold design capabilities and established QatarEnergy alliance relationships. Long-term viability hinges on sustained North Field expansion capital deployment through the projection horizon. Monitor liquefaction train commissioning schedules as the critical inflection signal for service contract volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Agreement | Locks in engineering capacity with QatarEnergy across North Field expansion phases. |
| Backward Integration into Specialty Steel | Captures margin from corrosion-resistant alloy supply chains serving subsea fabrication. |
| Carbon Capture Integration | Aligns associated gas processing with European low-carbon LNG procurement criteria. |
| Digital Twin Deployment | Converges predictive maintenance with data analytics for subsea asset performance monitoring. |
| Local Content Compliance Investment | Meets Ministry of Environment and Climate Change workforce quotas and supplier thresholds. |
Research Methodology
Direct dialogue with upstream project managers, subsea engineering directors, drilling contractors, and procurement leads at QatarEnergy and international partners grounded the qualitative foundation. Secondary validation drew from Qatar Financial Centre regulatory filings, Ministry of Environment and Climate Change permit databases, customs import records, and liquefaction project development trackers. Bottom-up and top-down triangulation reconciled contractor capacity assessments with QatarEnergy's announced expansion timelines.
Bottom-up modeling aggregated individual project scopes across North Field East and South development phases, while top-down analysis cross-checked against aggregate LNG capacity addition targets. Segmentation dimensions spanned technology category, service type tier, product stream, and end-user archetype across the analysis window. CAGRs derived from project-level capital expenditure phasing and contractor backlog disclosures. Forecast inputs incorporated seismic survey scope expansion rates and subsea installation vessel availability constraints.
Underlying measurement precision varies by segment; seismic survey and drilling technology categories carry tighter precision than maintenance services due to disclosed contract award values. Forecasts reflect assumptions around regulatory permitting timelines and offtake agreement execution. Supply chain disruption or commodity price spikes could materially revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Floating Production Storage and Offloading Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
China Oil and Gas Downstream Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market