
 Hydrogen Fuel Cell Vehicle Market | 2026-2036
Hydrogen Fuel Cell Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Fuel Cell Vehicle Market Intelligence
Platinum is repositioning away from dominant catalyst status as iridium and cobalt alloy formulations achieve comparable proton exchange efficiency at lower loadings. Toyota Motor Corporation leverages its multi-decade stack manufacturing depth to sustain cost curves below competitors. Hyundai Motor Group anchors its strategy in integrated hydrogen ecosystem investments spanning production, storage, and retail infrastructure. Ballard Power Systems specializes in heavy-duty module architectures that dominate North American bus and truck retrofit segments.
A hydrogen fuel cell vehicle converts stored hydrogen gas into electrical energy through an electrochemical reaction, typically operating at 60-80°C in proton exchange membrane configurations with power outputs ranging from 50 kW for passenger cars to 250+ kW for long-haul trucks. Passenger cars currently occupy the largest installed base though trucks represent the fastest-expanding category as logistics operators seek zero-emission alternatives to diesel powertrains. Proton exchange membrane technology leads commercial deployment while solid oxide systems compete in stationary-range extender applications where higher operating temperatures improve system efficiency. Fuel cell stack manufacturing captures the dominant share of component value, yet hydrogen storage systems in 700-bar Type IV carbon-fiber tanks are deepening margin pools as safety certification requirements intensify.
The US EPA and NHTSA coordinate tailpipe emission standards that effectively mandate zero-emission powertrains for medium and heavy-duty vehicles in key freight corridors, while Japan's METI directs subsidy allocation through its Green Innovation Fund to accelerate domestic fuel cell stack production capacity. The EU's F-Gas Regulation and forthcoming CO2 standards for heavy-duty vehicles are reshaping product certification requirements and market access conditions for non-compliant powertrain technologies. Stakeholders must monitor hydrogen production source certification schemes as renewable-origin thresholds become decisive in qualifying for consumer incentives and fleet procurement tenders.
Market Dynamics
Platinum loadings in membrane electrode assemblies are collapsing as iridium-cobalt catalyst layers achieve comparable proton exchange efficiency, fundamentally restructuring stack cost economics and supplier power across the value chain.
Growth Catalysts
- California Freight Corridor Mandates:The US EPA and NHTSA coordinate tailpipe emission standards that effectively mandate zero-emission powertrains for medium and heavy-duty vehicles operating between Los Angeles and Long Beach port complexes.
- Japan's Green Innovation Fund:METI directs subsidy allocation toward accelerating domestic fuel cell stack production capacity, with metropolitan transit authorities in Tokyo and Osaka scaling procurement tenders.
- 700-bar Type IV Tank Certification:Safety certification requirements for carbon-fiber hydrogen storage systems are intensifying, deepening margin pools for qualified manufacturers serving German and South Korean municipal bus fleets.
Market Restraints
- Iridium Supply Concentration:Primary iridium mining concentrates in South African platinum group metal operations, creating geopolitical exposure for catalyst layer manufacturers dependent on alloy formulations.
- Hydrogen Production Certification Complexity:Renewable-origin thresholds for consumer incentives and fleet procurement tenders vary across California, Japan, and Germany, fragmenting qualification pathways.
- Battery Electric Substitution:Lithium-ion powertrains with expanding range capabilities capture overlapping use cases in urban delivery and regional haul segments where charging infrastructure matures faster.
Strategic Opportunities
- Solid Oxide Range Extenders:Higher operating temperature systems improve efficiency in stationary auxiliary power applications for long-haul trucks, converging with sleeper cab electrification trends.
- German Hydrogen Roadmap Procurement:Municipal bus fleets under national hydrogen roadmaps are scaling procurement with multi-year tender structures favoring integrated ecosystem providers.
- Retrofit Module Channels:Heavy-duty bus and truck retrofit segments in North America present white space for modular fuel cell architectures that bypass OEM-locked powertrain integration.
Industry Challenges
- Membrane Electrode Assembly Talent Scarcity:Specialized electrochemical engineering expertise for thin-film catalyst deposition remains concentrated among a limited pool of experienced practitioners.
- Stack Durability Certification Timelines:Automotive-grade lifetime validation protocols require extended operational testing, compressing product launch windows against regulatory deadline acceleration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Fuel Cell Vehicle Market |
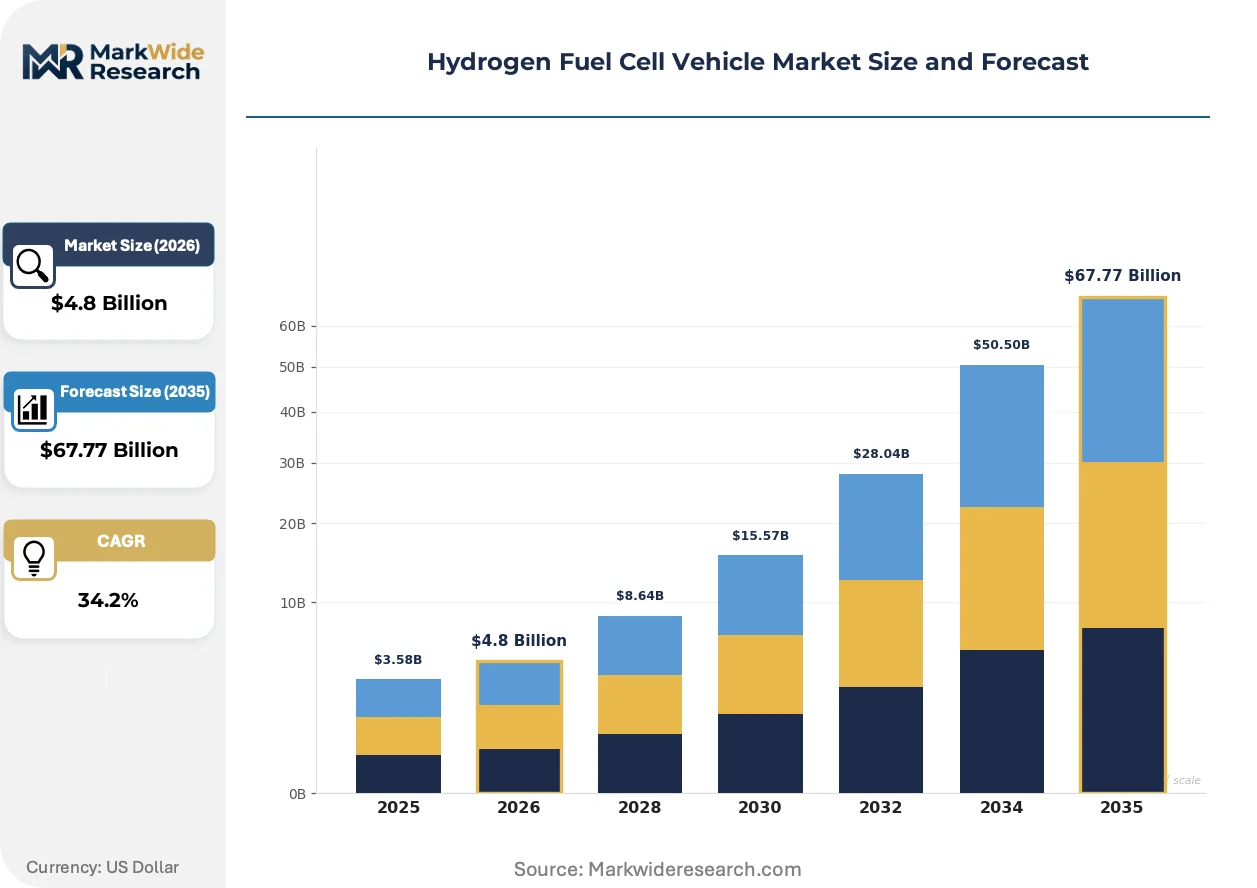
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $67.77 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Buses, Trucks, Forklifts Technology: Proton Exchange Membrane, Solid Oxide, Alkaline, Direct Methanol Component: Fuel Cell Stack, Hydrogen Storage, Power Control Unit, Electric Motor End User: Private Owners, Public Transport, Logistics Companies, Government Fleet |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Group, Honda Motor Co., Ltd., Daimler AG, General Motors, BMW AG, Nikola Corporation, Ballard Power Systems, SAIC Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Fuel Cell Vehicle Market Strategic Shifts & Innovations
Electrochemical system architectures are converging with digital control layers and advanced manufacturing methods, compressing development cycles while expanding addressable vehicle categories beyond early passenger car deployments.
Automated catalyst layer deposition is automating precision coating of iridium-cobalt formulations onto proton exchange membranes with sub-micron uniformity. Tier-one stack manufacturers in Japan and Germany are adopting these systems to reduce platinum group metal waste and accelerate production ramp rates. The technology is automating quality control integration that previously required manual inspection, compressing defect detection cycles from hours to minutes.
The EU's F-Gas Regulation is tightening fluorinated gas containment requirements for cooling systems in fuel cell stacks, forcing redesigns of thermal management architectures. Manufacturers must now certify leak-free operation across wider temperature ranges to maintain market access. Heavy-duty truck platforms face the steepest compliance burden as their larger thermal loads demand higher refrigerant charges.
Fleet operators are consolidating procurement authority into centralized sustainability offices that negotiate multi-year hydrogen supply agreements alongside vehicle contracts. This bypasses traditional decentralized purchasing where individual depots selected powertrains independently. The pattern is most visible in California's freight corridor networks where logistics operators seek volume-locked hydrogen pricing to hedge against retail station volatility.
Hydrogen Fuel Cell Vehicle Market Segmentation
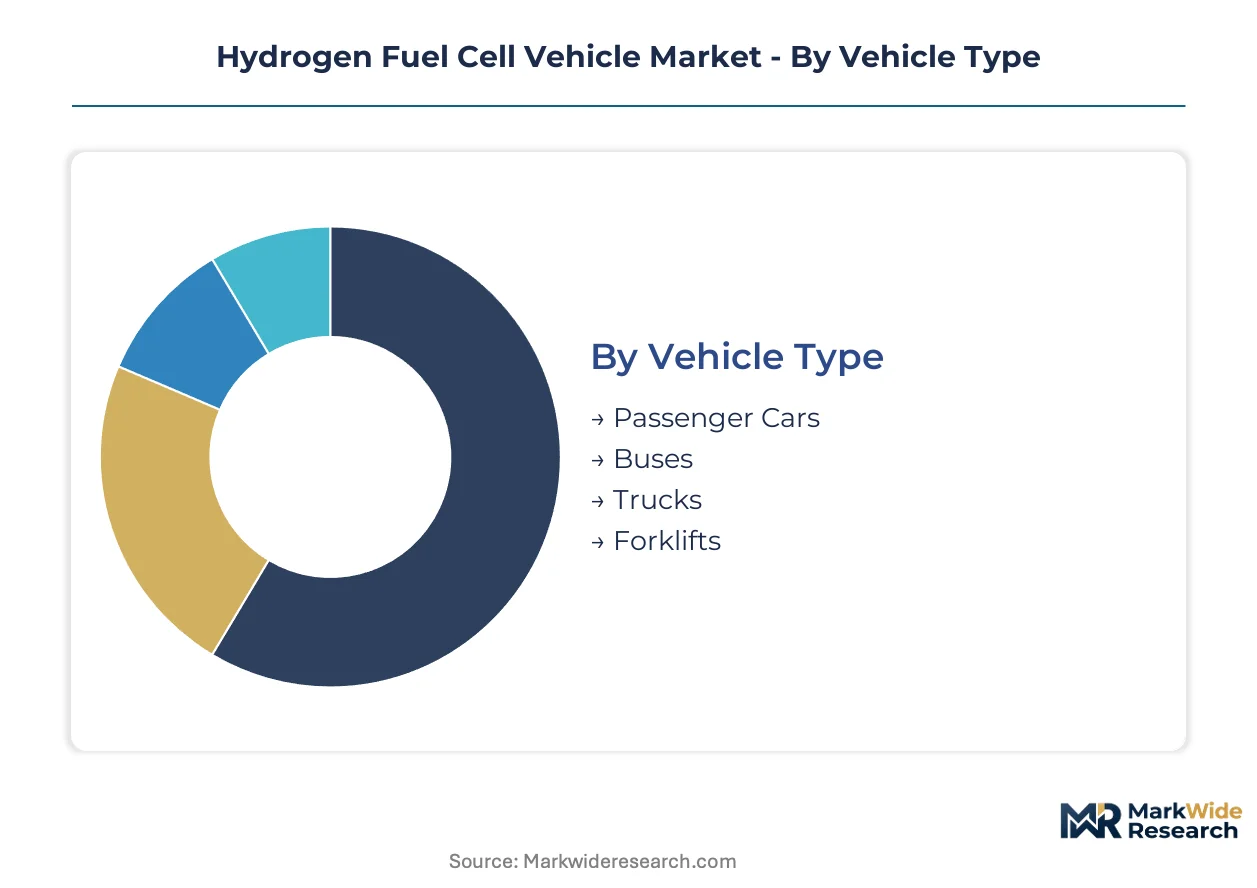
Segmentation in hydrogen fuel cell vehicles reveals divergent cost structures and infrastructure dependencies across mobility applications. Each category isolates distinct buyer priorities, from range anxiety thresholds in private ownership to total cost of ownership calculations in freight logistics.
Vehicle Type:
Buyer priorities diverge sharply between range-dependent long-haul operators and fixed-route municipal fleets with captive refueling infrastructure.
- Passenger Cars:These vehicles deploy 50-100 kW fuel cell stacks with 700-bar Type IV hydrogen storage, targeting early adopters in California and Japan where retail station networks achieve critical density. Private buyers prioritize refueling speed over battery charging intervals, though purchase premiums remain substantial against comparable battery electric alternatives.
- Trucks:Long-haul configurations demand 250+ kW stack outputs with dual or triple hydrogen tanks extending range beyond 800 kilometers. Logistics operators in California's freight corridors are consolidating procurement authority to secure volume-locked hydrogen pricing, bypassing retail station volatility that undermines route planning certainty.
- Buses:Municipal transit authorities in Germany and South Korea scale procurement under national hydrogen roadmaps, favoring integrated ecosystem providers with multi-year service contracts.
- Forklifts:Warehouse operators in cold-storage environments value rapid refueling and consistent power output where lithium-ion performance degrades.
Passenger cars lead volumes today; trucks are gaining share fastest.
Technology:
Operating temperature and proton conductivity requirements separate commercial deployment from experimental applications.
- Proton Exchange Membrane:Operating at 60-80°C with platinum-iridium-cobalt catalyst layers, PEM systems dominate automotive applications through rapid cold-start capability and power density. Stack manufacturers in Japan and Germany automate catalyst deposition to reduce platinum group metal waste while accelerating production ramp rates.
- Solid Oxide:Higher operating temperatures above 600°C improve system efficiency for stationary auxiliary power in long-haul truck sleeper cabs, converging with electrification trends in overnight cab amenities.
- Alkaline:Lower cost catalysts using nickel and silver suit stationary applications where system weight matters less than capital expenditure minimization.
- Direct Methanol:Liquid fuel storage eliminates hydrogen infrastructure dependencies for niche portable power applications with modest energy density requirements.
Proton exchange membrane leads volumes today; solid oxide is expanding most quickly in range-extender configurations.
Component:
Value capture concentrates where safety certification requirements intensify manufacturing complexity and supplier qualification timelines.
- Fuel Cell Stack:Membrane electrode assemblies with declining platinum loadings capture dominant component value as iridium-cobalt formulations mature. METI's Green Innovation Fund accelerates domestic Japanese production capacity to reduce import dependency.
- Hydrogen Storage:700-bar Type IV carbon-fiber tanks deepen margin pools as safety certification requirements intensify for German and South Korean municipal bus fleets.
- Power Control Unit:DC-DC converters and inverters manage voltage transformation between stack output and electric motor demand.
- Electric Motor:Traction motors sized to vehicle power requirements integrate with fuel cell systems through standardized automotive electrical architectures.
Fuel cell stacks lead volumes today; hydrogen storage is climbing the fastest as certification barriers concentrate qualified supply.
End User:
Procurement centralization patterns separate fleet operators negotiating hydrogen supply agreements from fragmented individual purchasing decisions.
- Logistics Companies:Centralized sustainability offices negotiate multi-year hydrogen supply agreements alongside vehicle contracts, seeking volume-locked pricing to hedge retail station volatility. California freight corridor operators pioneered this procurement consolidation.
- Public Transport:Municipal transit authorities in Tokyo, Osaka, and German metropolitan regions scale tender structures favoring integrated ecosystem providers with maintenance and fueling commitments.
- Private Owners:Individual purchasers concentrate in California and Japan where retail hydrogen networks achieve usable density despite limited model availability.
- Government Fleet:Federal and state procurement mandates in emission-regulated corridors drive standardization around certified vehicle platforms.
Public transport leads volumes today; logistics companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's freight corridor networks anchor hydrogen fuel cell vehicle deployment through coordinated port mandates and zero-emission corridor designations. National hydrogen roadmaps in Germany and Japan are accelerating municipal procurement timelines. South Korea's metropolitan transit authorities are scaling tender structures that favor integrated ecosystem providers.
United States
The Los Angeles-Long Beach port complex drives heavy-duty truck demand through EPA-NHTSA coordinated tailpipe standards that mandate zero-emission powertrains. California's Air Resources Board administers HVIP incentives that offset vehicle purchase premiums for fleet operators. Freight logistics operators in the San Pedro Bay corridor are consolidating procurement authority into centralized sustainability offices.
Germany
Municipal bus fleets in Berlin and Hamburg are scaling procurement under the National Hydrogen Strategy's 2030 deployment targets. The Federal Motor Transport Authority (KBA) certifies 700-bar Type IV tank systems for commercial vehicle integration. Industrial clusters in North Rhine-Westphalia are developing integrated hydrogen production and refueling infrastructure for heavy-duty applications.
Japan
Tokyo and Osaka metropolitan transit authorities are expanding fuel cell bus tenders through METI's Green Innovation Fund subsidy allocation. The Ministry of Economy, Trade and Industry directs domestic stack production capacity expansion to reduce import dependency. Automotive manufacturing corridors in Aichi Prefecture are automating catalyst layer deposition systems for membrane electrode assembly production.
South Korea
Seoul's municipal transit corporation is procuring fuel cell buses under the Hydrogen Economy Roadmap's 2025 deployment targets. The Ministry of Trade, Industry and Energy coordinates subsidy allocation with domestic stack manufacturer qualification requirements. Ulsan's industrial complex is integrating hydrogen production, storage, and vehicle manufacturing within a single regional ecosystem.
China
Foshan and Zhengzhou are piloting fuel cell bus fleets through the Ministry of Industry and Information Technology's new energy vehicle subsidy program. The National Development and Reform Commission directs hydrogen infrastructure investment into designated demonstration zones. Yangtze River Delta manufacturing clusters are developing domestic proton exchange membrane stack production capacity.
Hydrogen Fuel Cell Vehicle Market Key Industry Players
Global majors compete with regional champions across integrated ecosystem capabilities and manufacturing scale. The market structures around three tiers: automotive OEMs with multi-decade stack manufacturing depth, specialized powertrain module suppliers, and state-linked industrial conglomerates with captive hydrogen infrastructure. Strategic moves concentrate on backward integration into catalyst material supply and geographic expansion through joint venture manufacturing.
Within the automotive OEM tier, Toyota Motor Corporation and Hyundai Motor Group exemplify divergent strategic postures. Toyota leverages manufacturing depth accumulated through sequential Mirai platform generations. Hyundai anchors positioning through integrated investments spanning production, storage, and retail infrastructure. Ballard Power Systems occupies a specialist position in heavy-duty module architectures for retrofit applications.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Group |
| Honda Motor Co., Ltd. |
| Daimler AG |
| General Motors |
| BMW AG |
| Nikola Corporation |
| Ballard Power Systems |
| SAIC Motor Corporation |
| Others |
Cost & Logistics Intelligence
Automotive-grade certification tiers bifurcate procurement economics between qualified 700-bar Type IV tank manufacturers and uncertified challengers, concentrating pricing power with German and South Korean suppliers while pressuring margins for membrane electrode assembly producers facing iridium-cobalt catalyst standardization.
Pricing Analysis
Input-cost pass-through from platinum group metal volatility governs stack pricing, with iridium-cobalt formulations displacing pure platinum loadings and compressing material cost premiums. Price differentiation hinges on automotive-grade durability certification and captive hydrogen infrastructure bundling. Cost compression in passenger car segments intensifies as battery electric alternatives narrow total cost of ownership gaps. Logistics operators in California freight corridors demonstrate lowest price sensitivity due to regulatory compliance mandates, while municipal bus authorities in Germany negotiate hardest on multi-year service contracts.
Supply Chain Analysis
Reverse-logistics flows for membrane electrode assemblies remain underdeveloped, creating stranded asset risk for early-generation stacks while South Korean and Japanese manufacturers pilot refurbishment programs for transit bus powertrains. Primary iridium mining concentrates in South African platinum group metal operations, with carbon-fiber tank production anchored in Germany, Japan, and South Korea. Single-source vulnerability in iridium feedstock exposes catalyst layer manufacturers to geopolitical disruption. Distribution runs through OEM-locked channels for passenger cars and modular retrofit suppliers for heavy-duty segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as freight corridor zero-emission mandates harden regulatory baselines, ensuring durable demand expansion for compliant powertrain technologies.
For Market Incumbents: Lock in catalyst material supply through long-term offtake agreements with South African platinum group metal operators, insulating against iridium concentration risk. Secure 700-bar Type IV tank certification ahead of EU F-Gas Regulation tightening to defend automotive-grade positioning against emerging Chinese competitors. For New Entrants and Emerging Players: Solid oxide range-extender architectures offer technology-first wedge into long-haul truck sleeper cab electrification, where higher operating temperatures improve auxiliary power efficiency. Target North American heavy-duty retrofit segments with modular fuel cell architectures that bypass OEM-locked integration, partnering with fleet maintenance networks for aftermarket installation capacity. For Investors and Strategic Acquirers: Consolidation pressure builds where membrane electrode assembly talent scarcity concentrates among Japanese and German specialists with thin-film catalyst deposition expertise. Five-to-ten-year viability favors integrated ecosystem providers with captive hydrogen infrastructure rather than pure-play stack manufacturers. Monitor renewable hydrogen production certification scheme harmonization across California, Japan, and Germany as inflection signal for incentive-qualified demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Materials | Long-term iridium supply agreements with South African mining operations reduce feedstock volatility exposure. |
| 700-bar Type IV Tank Certification Investment | EU F-Gas Regulation compliance secures market access for German and South Korean bus fleet suppliers. |
| Solid Oxide Range-Extender Development | Higher operating temperature systems capture long-haul truck sleeper cab auxiliary power applications. |
| Hydrogen Supply Agreement Consolidation | California logistics operators lock volume-locked pricing to hedge retail station volatility in freight corridors. |
| Modular Retrofit Channel Partnership | North American heavy-duty bus and truck segments bypass OEM-locked powertrain integration barriers. |
Research Approach
Direct dialogue with fuel cell stack manufacturing executives, municipal transit procurement directors, logistics fleet sustainability officers, and hydrogen infrastructure developers grounded qualitative findings, cross-validated against EPA and NHTSA regulatory filings, METI subsidy allocation disclosures, EU F-Gas Regulation implementation guidance, and vehicle production database trajectories. Bottom-up stack shipment estimates and top-down hydrogen consumption projections were triangulated to anchor volume figures.
Segment-level outputs across vehicle type, technology architecture, component category, and end-user procurement pattern were generated over the projection horizon, with CAGRs derived from regulatory mandate timelines and infrastructure deployment trajectories. Modeled inputs incorporated platinum group metal price elasticity, 700-bar tank certification queue lengths, and renewable hydrogen origin threshold harmonization progress.
The model holds under sustained regulatory enforcement of zero-emission corridor designations; deviation in battery electric range expansion or hydrogen production cost curves would shift technology substitution timing. Practitioners should monitor iridium spot price volatility and cross-border hydrogen certification mutual recognition agreements for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Bipolar Plate Coatings Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
Hydrogen Recirculation Blower for Fuel Cell Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Fuel Cell for Data Center Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market