
 Blow Molding Tools Market | 2026-2036
Blow Molding Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Blow Molding Tools Market Intelligence
Electrification of vehicle powertrains is narrowing the design envelope for blow molded fuel tanks and fluid reservoirs, forcing toolmakers to engineer for thinner wall sections and multi-layer barrier structures. Kaysun Corporation leverages its Wisconsin-based toolroom capacity to serve Tier 1 automotive contracts requiring rapid design iteration. Creative Blow Mold Tooling specializes in complex manifold geometries for medical and consumer packaging applications. ADM Precision Tools anchors European demand through its UK operations focused on high-cavitation PET preform tooling.
Blow molding tools are precision-machined mold assemblies—typically fabricated from hardened tool steel or aluminum alloys with cooling channel networks—that shape molten thermoplastic into hollow containers, automotive ducts, or industrial vessels under controlled pressure and temperature cycles. Their primary purpose centers on delivering dimensional repeatability across millions of production cycles while minimizing flash and cycle time. Extrusion blow molding dominates tooling volumes for industrial and automotive bulk containers where part size justifies lower cavitation counts. Injection blow molding commands premium tooling economics in pharmaceutical packaging due to stringent FDA validation requirements and cleanroom compatibility. Stretch blow molding tooling for PET beverage bottles represents a mature, high-volume segment where Chinese fabricators compete aggressively on lead time.
EPA fuel permeation standards under 40 CFR Part 86 and the EU F-Gas Regulation constrain material selection and layer structures in automotive and HVAC blow molded components, directly shaping tool design specifications for multi-layer coextrusion. FDA 21 CFR Part 177 compliance for food-contact and pharmaceutical applications mandates traceable steel grades and validated cleaning protocols in tool fabrication facilities. Tool buyers must monitor how evolving PFAS restrictions in the EU and US states like Maine and Minnesota propagate through polymer supply chains, potentially forcing material transitions that obsolete existing mold cavity geometries.
Market Dynamics
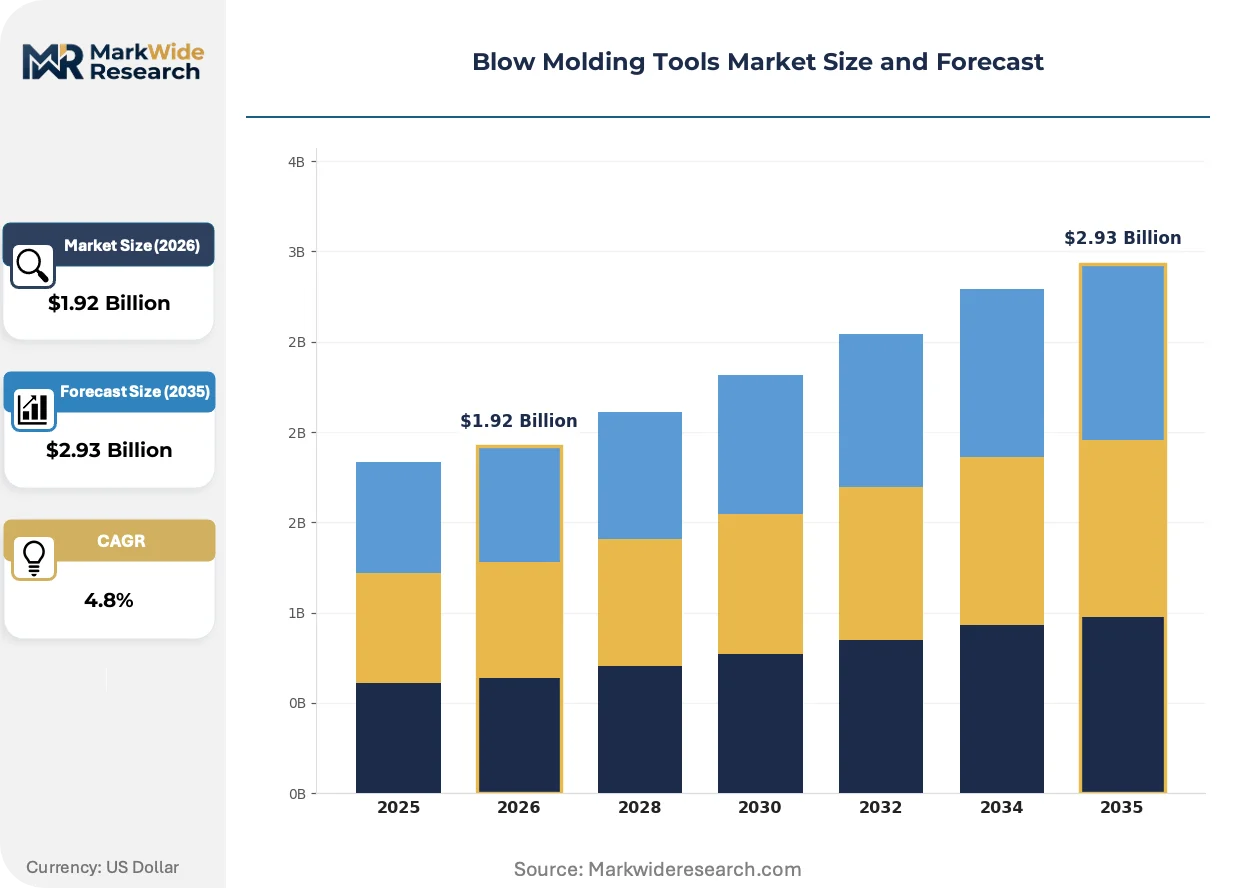
Automotive electrification is compressing demand for traditional fuel system tooling while simultaneously expanding requirements for battery cooling manifolds and thermal management ducts. Toolmakers face simultaneous pressure from thinner-wall specifications and multi-layer barrier mandates.
Growth Catalysts
- EPA Fuel Permeation Standards:Tier 1 automotive suppliers in Michigan and South Carolina are procuring coextrusion-capable tooling to meet 40 CFR Part 86 hydrocarbon emission limits for fuel tanks and vapor recovery systems.
- Medical Packaging Validation:FDA 21 CFR Part 177 compliance requirements for pharmaceutical blow molded containers are extending tool procurement cycles and locking in premium fabrication contracts with validated steel traceability.
- China Eastern Manufacturing Corridor:Mold fabrication clusters in Jiangsu and Zhejiang provinces are capturing export orders from European automotive OEMs seeking 30-40% lead time compression versus domestic European toolrooms.
Market Restraints
- Hardened Tool Steel Volatility:Alloy price swings for H13 and S7 grades are compressing fabrication margins and forcing fixed-price contract renegotiations mid-build.
- Chinese Fabricator Concentration:Stretch blow molding tooling for PET beverage applications is consolidating among Shenzhen and Dongguan-based suppliers, eroding pricing power for European and North American competitors.
- Multi-Layer Coextrusion Complexity:Barrier layer adhesion failures in automotive fuel tanks are extending tool debug cycles and delaying production qualification timelines.
Strategic Opportunities
- India Automotive Tier 2 Expansion:BIS certification requirements and PLI scheme incentives for component localization are opening captive tooling investments for fuel tank and HVAC duct manufacturers near Chennai and Pune.
- Battery Thermal Management:Convergence of blow molding with aluminum die-casting is enabling hollow cooling channel geometries for EV battery packs that machined channels cannot achieve.
- EU F-Gas Refrigerant Phase-Down:HVAC blow molded component mandates are accelerating demand for barrier-layer tooling compatible with low-GWP refrigerants in Germany and Poland.
Industry Challenges
- Multi-Axis CNC Programming Shortage:Complex cooling channel geometries for conformal cooling require specialized CAM expertise that toolrooms in Ohio and Baden-Württemberg struggle to staff.
- FDA Validation Documentation Burden:Pharmaceutical tooling contracts require 12-18 month qualification protocols that strain working capital and extend receivables cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blow Molding Tools Market |
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extrusion Blow Molding, Injection Blow Molding, Stretch Blow Molding, Single Stage Blow Molding Technology: Automated Systems, Manual Systems, Hybrid Systems, Pneumatic Systems End User: Consumer Products, Automotive, Pharmaceutical, Industrial Material: Polyethylene, Polypropylene, PVC, PET |
| Companies Covered | Abhijeet Dies and Tools Pvt. Ltd., ADM Precision Tools, Creative Blow Mold Tooling, Gemini Group, Kaysun Corporation, The Rodon Group, Custom-Pak, Inc., Agri-Industrial Plastics, APEX Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blow Molding Tools Market Strategic Shifts & Innovations
Tooling technology is bifurcating between high-cavitation commodity platforms and precision medical applications requiring validated traceability. Regulatory pressure on material barriers and cooling efficiency is accelerating design tool adoption.
Conformal cooling channel geometries generated through metal additive manufacturing are replacing straight-drilled circuits in high-performance automotive molds. Tier 1 suppliers in Stuttgart and Detroit are specifying these designs for fuel tank manifolds requiring ±0.1mm dimensional stability. The technology is migrating from prototype validation to production tooling for runs exceeding 500,000 cycles.
REACH SVHC restrictions and pending PFAS limitations under EU ECHA review are forcing material substitutions in fluoropolymer barrier layers. Automotive fuel system engineers are redesigning multi-layer structures to maintain permeation performance without prohibited chemistries. German KBA type-approval processes are extending 4-6 months as suppliers resubmit barrier layer specifications.
Consolidated procurement desks at major packaging OEMs are unbundling tool fabrication from maintenance contracts and demanding standalone performance guarantees. Distributor networks in the US Midwest are losing share to direct mill relationships. This pattern is most pronounced among dairy and edible oil processors in Wisconsin and Iowa seeking ISO 22000-aligned tool traceability.
Blow Molding Tools Market Segmentation
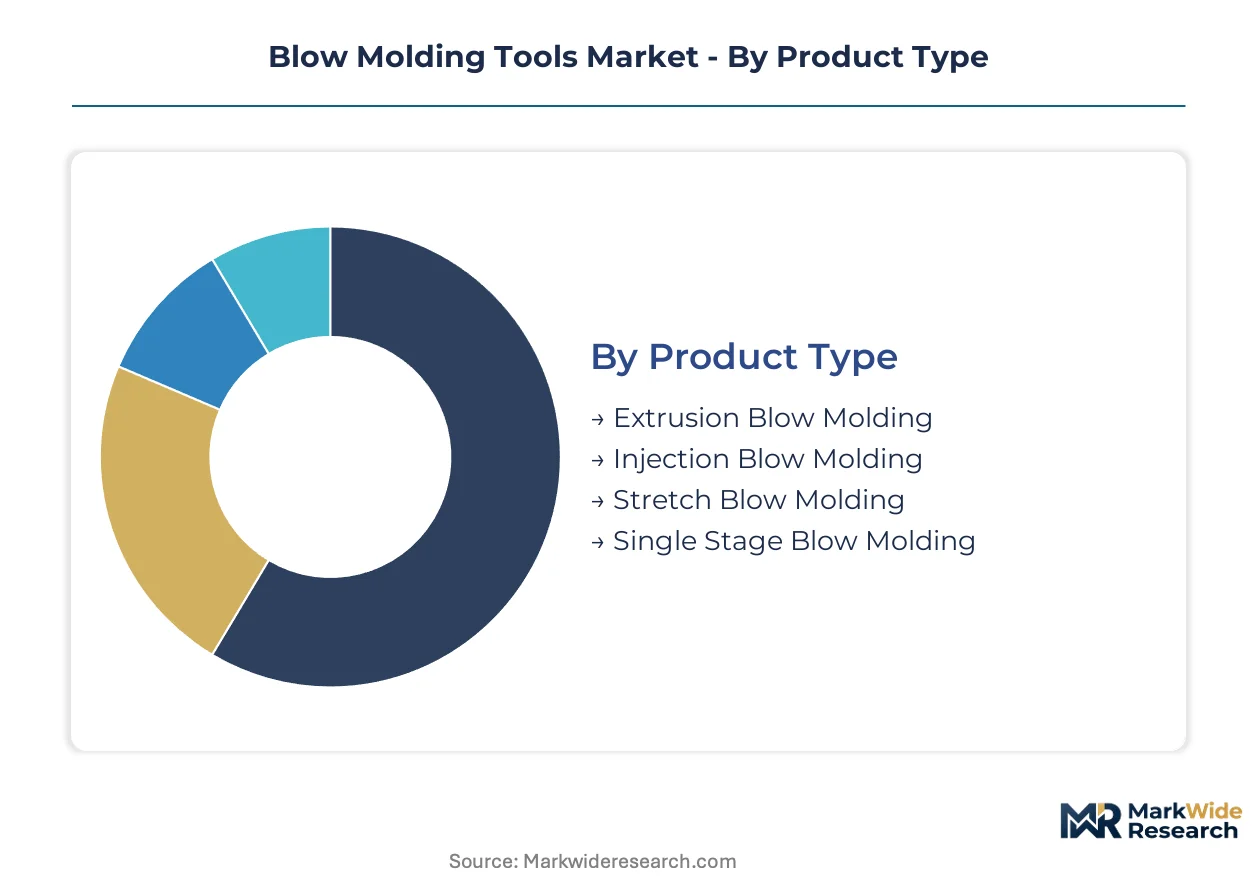
Blow molding tools serve radically different performance requirements across fuel systems, medical packaging, and beverage containers. Segmentation reveals where tooling complexity commands premium pricing versus where standardization drives cost competition.
Product Type:
Tooling configurations span from massive industrial vessels to precision pharmaceutical vials, with cycle economics and cavity counts diverging sharply across the spectrum.
- Extrusion Blow Molding:Mold assemblies for parison-based forming dominate automotive fuel tanks and industrial bulk containers. Hardened tool steel construction withstands million-cycle demands for HDPE fuel tanks meeting EPA permeation standards.
- Stretch Blow Molding:PET beverage bottle tooling achieves highest cavitation counts. Chinese fabricators in Jiangsu province compress lead times aggressively for export orders from European dairy processors.
- Injection Blow Molding:Precision mold sets for pharmaceutical preforms require FDA-validated steel traceability. Cleanroom-compatible tooling commands extended procurement cycles.
- Single Stage Blow Molding:Integrated injection-stretch systems suit low-volume specialty packaging. Niche medical applications favor this configuration for rapid material changeovers.
Established volume favors extrusion blow molding for automotive; emerging adoption favors stretch blow molding for lightweight beverage packaging.
Technology:
Automation intensity separates high-mix pharmaceutical production from commodity packaging lines running identical SKUs for years.
- Automated Systems:Servo-driven clamping and parison programming enable sub-second cycle times. Tier 1 automotive suppliers in Michigan specify these for fuel tank manifolds requiring ±0.1mm repeatability.
- Hybrid Systems:Semi-automated configurations balance flexibility with capital efficiency. Mid-volume consumer goods manufacturers in Ohio favor these for seasonal packaging transitions.
- Manual Systems:Operator-dependent tooling persists in prototype shops and ultra-low-volume medical device development. Limited to sub-10,000 annual cycle requirements.
- Pneumatic Systems:Compressed-air actuation dominates legacy installations in emerging manufacturing economies. Maintenance intensity limits adoption in regulated pharmaceutical environments.
Capital deployment favors automated systems for automotive scale; operational flexibility favors hybrid systems for packaging variability.
End User:
Regulatory burden and part complexity create four distinct procurement profiles with diverging validation requirements.
- Automotive:Multi-layer coextrusion tooling for fuel systems faces EPA 40 CFR Part 86 and EU F-Gas compliance mandates. German KBA type-approval processes extend qualification timelines.
- Pharmaceutical:FDA 21 CFR Part 177 compliance demands traceable steel grades and documented cleaning protocols. Validation documentation burdens strain toolmaker working capital.
- Consumer Products:High-cavitation PET tooling for beverage and personal care applications competes on lead time and unit cost. Chinese fabricators capture share through 30-40% faster delivery.
- Industrial:Large-tonnage extrusion molds for chemical containers and IBC totes prioritize durability over precision. H13 steel construction withstands abrasive polymer compounds.
Specification intensity favors pharmaceutical and automotive; volume scale favors consumer products.
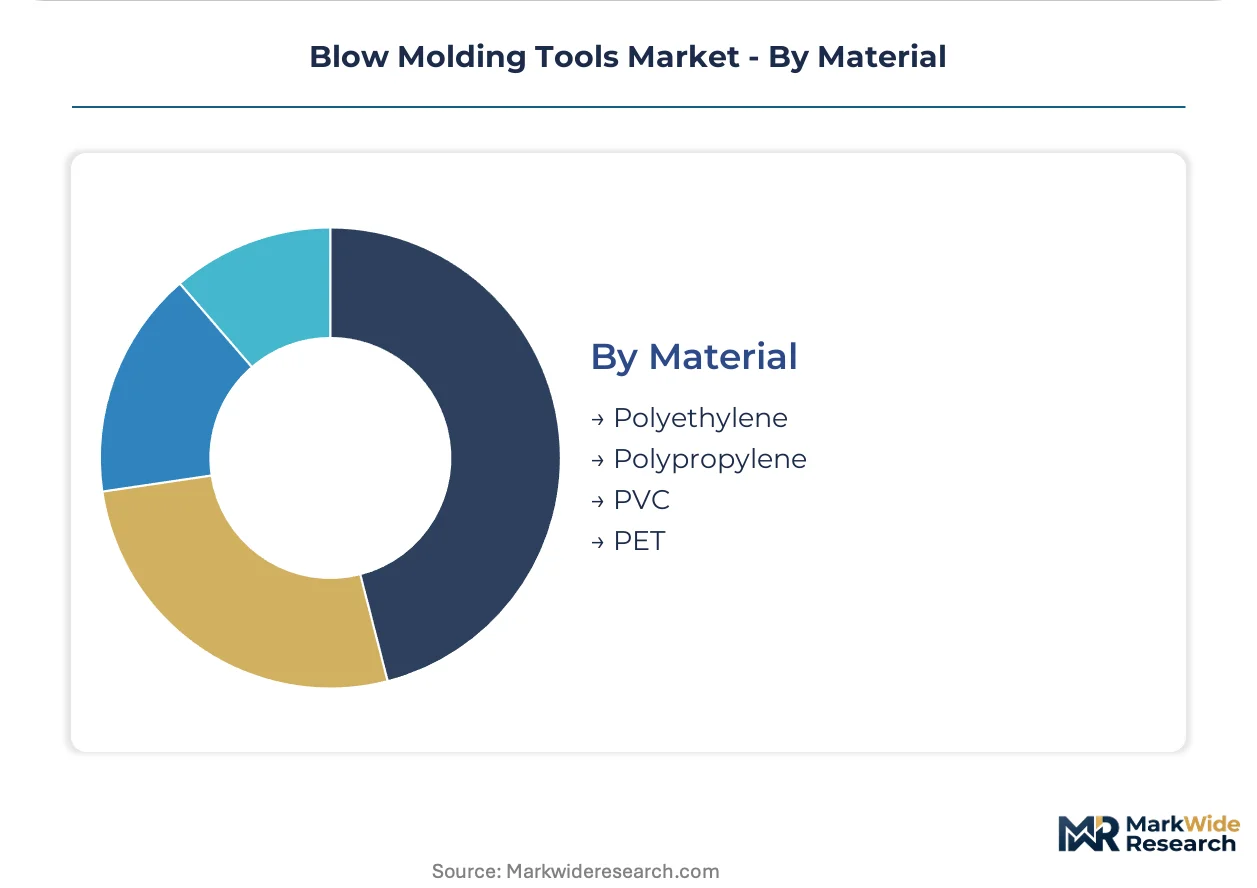
Material:
Polymer processing characteristics dictate cooling channel design, surface finish requirements, and wear-resistant coating selections.
- Polyethylene:HDPE and LDPE variants dominate fuel tank and industrial container tooling. Multi-layer barrier structures for automotive applications require precise layer thickness control.
- PET:Stretch blow molding for beverage bottles demands highly polished cavity surfaces and optimized crystallization control. High-cavitation tooling from Zhejiang fabricators serves global bottlers.
- Polypropylene:Random and impact copolymer grades suit automotive ducts and HVAC components. EU F-Gas refrigerant phase-down is forcing barrier layer redesigns.
- PVC:Rigid and plasticized formulations require corrosion-resistant mold materials and specialized venting. Medical tubing applications face tightening plasticizer restrictions.
Processing maturity favors polyethylene and PET; regulatory transition pressure favors polypropylene barrier development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and packaging converters concentrate procurement authority in manufacturing corridors where tool fabrication clusters intersect with end-user assembly plants. Tool buyers in Germany, the United States, China, India, and Mexico command disproportionate influence over specification standards and supplier qualification protocols.
United States
EPA 40 CFR Part 86 fuel permeation standards drive coextrusion tooling demand for HDPE fuel tanks and vapor recovery systems. Tier 1 automotive suppliers in Michigan and South Carolina operate captive procurement desks specifying rapid design iteration cycles. Wisconsin-based toolrooms serve dairy and edible oil processors demanding ISO 22000-aligned traceability.
Germany
KBA type-approval processes for multi-layer automotive fuel systems extend qualification timelines by 4-6 months. EU F-Gas Regulation refrigerant phase-down mandates barrier-layer tooling for HVAC components in Stuttgart and Wolfsburg manufacturing zones. Baden-Württemberg toolrooms face CAM programming shortages for conformal cooling channel geometries.
China
Jiangsu and Zhejiang mold fabrication clusters compress lead times 30-40% versus European competitors for stretch blow molding export orders. Domestic packaging OEMs and automotive suppliers in the eastern manufacturing corridor drive high-cavitation PET tooling volumes. Shenzhen and Dongguan suppliers consolidate PET beverage tooling through aggressive pricing.
India
BIS certification requirements and PLI scheme incentives for component localization open captive tooling investments near Chennai and Pune. Automotive Tier 2 expansion for fuel tanks and HVAC ducts attracts mold fabrication joint ventures. Maharashtra-based converters demand shorter qualification cycles for seasonal packaging transitions.
Mexico
Nuevo León automotive assembly plants procure blow molded ducts and reservoirs from cross-border tool suppliers. Nearshoring trends accelerate mold qualification protocols for US-bound automotive components. Querétaro packaging converters specify hybrid automation systems balancing flexibility with capital efficiency.
Blow Molding Tools Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tiers where no single fabricator commands pricing authority. The vendor base separates into automotive-focused coextrusion specialists, pharmaceutical validation experts, and high-cavitation commodity producers. Three archetypes dominate: integrated mold-machine suppliers, independent precision toolrooms, and volume-driven Asian fabricators. M&A activity concentrates among European toolrooms seeking CAM programming capabilities, while Chinese suppliers expand through direct mill relationships bypassing distributor networks.
Among North American fabricators, Kaysun Corporation occupies a position within the automotive coextrusion tier, while Creative Blow Mold Tooling exemplifies the precision medical-specialist archetype. ADM Precision Tools anchors European demand through UK-based operations. These three represent distinct competitive vectors: rapid design iteration for Tier 1 automotive contracts, complex manifold geometries for regulated medical applications, and high-cavitation PET preform tooling serving pharmaceutical validation requirements.
| Leading Market Players |
|---|
| Abhijeet Dies and Tools Pvt. Ltd. |
| ADM Precision Tools |
| Creative Blow Mold Tooling |
| Gemini Group |
| Kaysun Corporation |
| The Rodon Group |
| Custom-Pak, Inc. |
| Agri-Industrial Plastics |
| APEX Plastics |
| Others |
Cost & Logistics Intelligence
Hardened tool steel sourcing from Austrian and Swedish specialty mills concentrates upstream margin capture for H13 and S7 grades, while downstream pricing power fragments across automotive Tier 1 procurement desks, pharmaceutical validation specialists, and high-cavitation commodity fabricators competing on lead time compression.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate H13 and S7 tool steel procurement, though automotive Tier 1 suppliers increasingly demand fixed-price tooling agreements that transfer alloy volatility risk to fabricators. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical tooling from automotive coextrusion systems and commodity PET beverage molds. Pricing pressure stems from Chinese fabricator concentration in Jiangsu and Zhejiang, where 30-40% lead time compression erodes European and North American margin structures. Consumer products packaging converters exhibit highest price sensitivity due to unbundled procurement desks, while pharmaceutical OEMs prioritize validated traceability over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from automotive Tier 1 suppliers strain working capital for mid-sized European toolrooms, compressing cash conversion cycles to 90-120 days. Tool steel supply concentrates in Austria, Sweden, and Japan, while mold fabrication clusters operate in Germany, China, and the United States. Raw material dependencies span nickel-alloyed tool steels, copper-based cooling channel inserts, and aluminum alloy substrates. Single-source vulnerability in conformal cooling channel additive manufacturing equipment creates qualification bottlenecks. Distribution runs through direct mill relationships for large automotive contracts and regional distributor networks for mid-volume packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification-driven thermal management tooling demand and REACH SVHC material restrictions create a dual-velocity market where automotive coextrusion complexity accelerates while commodity PET tooling commoditizes.
For Market Incumbents: Entrench automotive coextrusion capabilities through backward integration into conformal cooling channel additive manufacturing, locking in Tier 1 contracts with Stuttgart and Detroit OEMs facing EPA 40 CFR Part 86 compliance deadlines. Defend against Chinese lead time compression by embedding rapid design iteration services that commodity fabricators cannot replicate without CAM programming depth. For New Entrants and Emerging Players: Build out battery thermal management tooling capacity targeting EV platform standardization cycles, where hollow cooling channel geometries merge blow molding with aluminum die-casting capabilities. Focus initial penetration on India automotive Tier 2 expansion near Chennai and Pune, leveraging BIS certification requirements and PLI scheme incentives that favor localized mold fabrication joint ventures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive tooling platforms in Ohio and Baden-Württemberg holding legacy fuel system expertise that requires thermal management retooling. Five-to-ten year viability hinges on successful capability migration from permeation barrier systems to battery cooling manifold geometries. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for HVAC barrier-layer tooling demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Conformal Cooling Channel Integration | Additive manufacturing adoption by Stuttgart Tier 1 suppliers enables ±0.1mm dimensional stability for fuel tank manifolds. |
| Multi-Layer Coextrusion Capability Buildout | EPA 40 CFR Part 86 compliance mandates extend procurement cycles for hydrocarbon barrier tooling in Michigan. |
| India Manufacturing Joint Venture | BIS certification and PLI scheme incentives attract captive tooling investments near Chennai automotive clusters. |
| Battery Thermal Management Diversification | EV platform convergence creates hollow cooling channel demand that machined aluminum channels cannot satisfy. |
| Pharmaceutical Validation Documentation Investment | FDA 21 CFR Part 177 compliance burdens lock in premium fabrication contracts with traceable steel requirements. |
Research Approach
Desk research of SEC 10-K filings, EU ECHA substance restriction databases, and automotive production registration data preceded structured interviews with Tier 1 supplier procurement directors, toolroom operations managers, and pharmaceutical packaging validation specialists. Primary fieldwork across Germany, the United States, and China captured specification evolution for multi-layer barrier tooling and conformal cooling adoption timelines. Secondary validation drew from customs trade statistics, FDA 510(k) device filings, and KBA type-approval documentation. Bottom-up segment sizing triangulated against top-down market value estimates from fabrication capacity and average selling price analysis.
Assumptions held fixed include regulatory enforcement intensity for EPA fuel permeation standards and EU F-Gas refrigerant phase-down schedules, while variables tested spanned alloy price volatility scenarios and Chinese export lead time compression rates. Segmentation modeling incorporated product type, automation technology tier, end-user regulatory burden, and polymer material processed. CAGRs derived from installed base replacement cycles and greenfield capacity additions across automotive and packaging verticals. Forecast inputs included EV battery thermal management adoption curves and REACH SVHC restriction propagation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported fabrication clusters or rapid conformal cooling technology diffusion would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Flow Wrap Packaging Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Packaging Racks Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Powder Filling Equipment Market
Packaging Equipment
Packing Belt Market