
 Thermal Transfer Roll Market | 2026-2036
Thermal Transfer Roll Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Transfer Roll Market Outlook
Distributor consolidation across industrial labeling channels is rewriting how thermal transfer rolls reach end users. DNP Corporation leverages captive resin-coating capacity to control material quality from substrate to finished ribbon. ARMOR Group anchors European supply through its regional manufacturing footprint, while Zebra Technologies Corporation competes by bundling printer hardware with certified media programs.
A thermal transfer roll is a cylindrical ribbon substrate coated with pigmented wax, resin, or wax-resin formulations that melt under precise heat from a thermal printhead to transfer images onto receiving materials. Wax-resin coatings withstand abrasion and moderate chemical exposure, serving barcode labels in logistics and pharmaceutical packaging. High-performance resin rolls command margin pools in pharmaceutical and electronics labeling where solvent resistance and print longevity are mandatory. Specialty grades represent the fastest-expanding category as cold-chain logistics and sterilization-indicator labels proliferate. Standard wax rolls occupy high-volume, price-sensitive segments in retail and basic shipping applications.
FDA DSCSA serialization requirements and EU MDR traceability mandates shape product specifications by demanding print permanence and chemical resistance that only resin-dominant formulations satisfy. REACH chemical restrictions and RoHS substance limits constrain coating chemistries, pushing manufacturers toward halogen-free and bisphenol-A-free alternatives. ISO 9001 and IEC quality frameworks govern production consistency for rolls deployed in regulated pharmaceutical environments. Stakeholders must monitor evolving chemical compliance thresholds and printer OEM certification programs as gatekeepers to commercial access.
Market Dynamics
Pharmaceutical serialization mandates under FDA DSCSA and EU MDR are compressing specification windows for thermal transfer ribbons, forcing resin-grade formulations into logistics networks that previously accepted wax-resin blends.
Growth Catalysts
- EU MDR traceability mandates:European medical device regulations now require permanent barcode legibility through sterilization cycles, pulling resin-dominant ribbons into surgical instrument labeling.
- Cold-chain logistics expansion:Temperature excursion indicators and cryogenic storage labels in biologics distribution are consuming specialty-grade thermal transfer media at accelerating rates.
- Japan's pharmaceutical track-and-trace system:METI-aligned serialization requirements for prescription drugs mandate chemical-resistant printing, standardizing resin ribbon deployment across domestic packaging lines.
Market Restraints
- Petrochemical feedstock volatility:Polyester film substrates and resin binders expose manufacturers to crude oil derivative price swings that compress margin predictability.
- Coating chemistry concentration:Halogen-free resin formulations depend on a narrow supplier base in Germany and Japan, creating single-source vulnerability for REACH-compliant grades.
- Direct thermal substitution:Short-life shipping labels in e-commerce fulfillment increasingly migrate to direct thermal media, eliminating ribbon consumption entirely.
Strategic Opportunities
- Sterilization-indicator labels:Steam and gamma-radiation exposure markers for surgical trays represent an emerging application with specification premiums and limited incumbent supply.
- India's pharmaceutical export growth:CDSCO serialization alignment with FDA DSCSA is creating demand for barcode-grade ribbons in contract packaging operations serving US markets.
- Halogen-free regulatory tailwinds:RoHS substance restrictions and brand-owner sustainability mandates are opening substitution windows for bisphenol-A-free and chlorine-free coating platforms.
Industry Challenges
- Printer OEM certification timelines:Zebra and SATO qualification protocols for new ribbon formulations extend 18-24 months, delaying commercialization of advanced resin chemistries.
- Coating uniformity at thin gauges:Sub-4-micron resin layers for high-speed pharmaceutical lines demand capital-intensive precision coating assets with limited installed base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Transfer Roll Market |
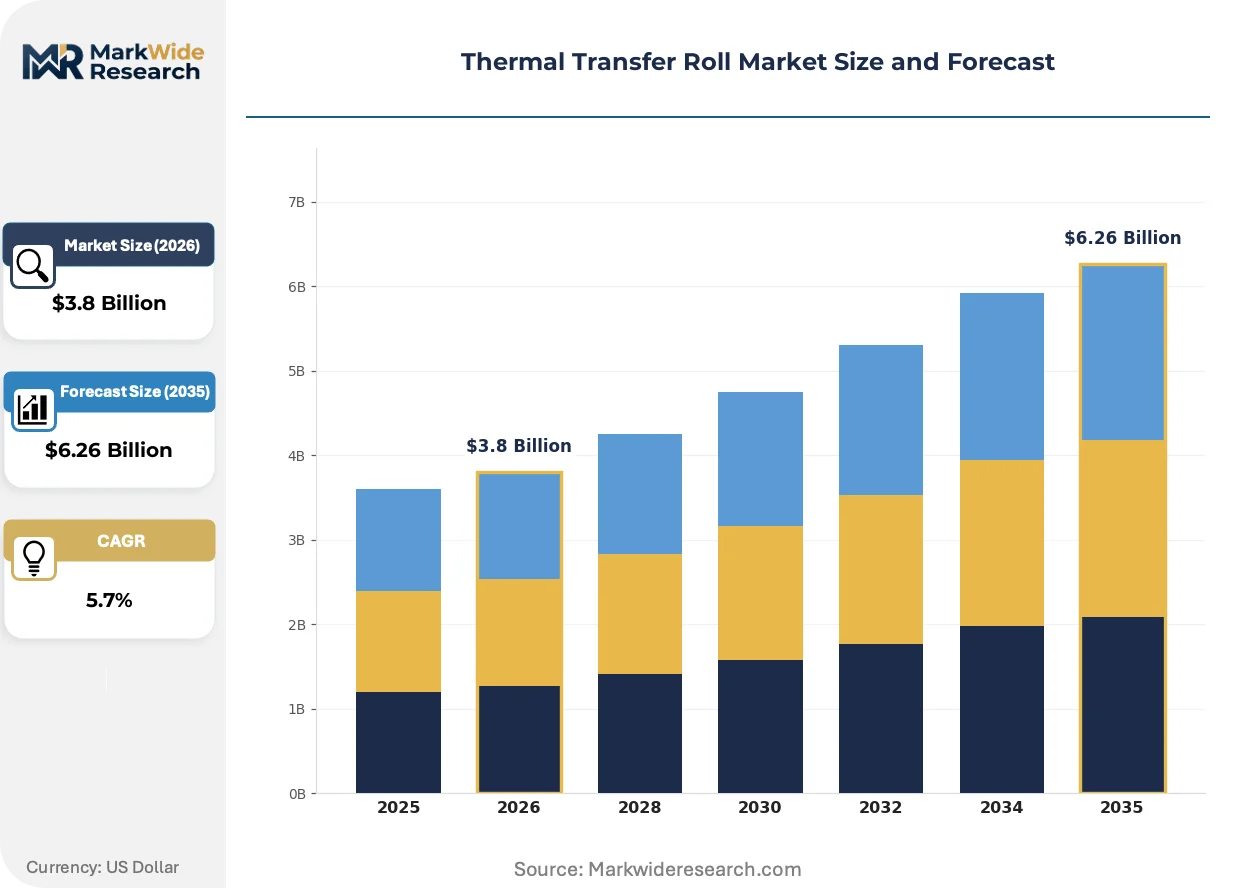
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, High Performance, Specialty, Low-Cost Material: Wax, Resin, Wax-Resin, Thermal Application: Labeling, Packaging, Barcode Printing, Asset Tracking End User: Manufacturing, Retail, Logistics, Pharmaceuticals |
| Companies Covered | DNP Corporation, ARMOR Group, ITW Thermal Films, Zebra Technologies Corporation, SATO Holdings Corporation, Ricoh Company, Ltd., Honeywell International Inc., Toshiba Tec Corporation, Brady Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Transfer Roll Market Strategic Shifts
Near-edge printhead architectures and halogen-free resin chemistries are reconfiguring competitive requirements across pharmaceutical and electronics labeling, compressing the viable technology set for new market entrants.
Water-based resin dispersion coatings are rendering obsolete solvent-borne thermal transfer ribbons in European pharmaceutical packaging. Bayer and Sanofi manufacturing sites in Germany have completed line conversions to aqueous-compatible media. The shift eliminates volatile organic compound emissions from coating operations while maintaining solvent resistance for end-use barcode permanence.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of premium resin ribbons previously dependent on fluorinated additives for chemical resistance. Coating manufacturers in the Netherlands and Belgium are accelerating alternative polymer development. Electronics labeling for circuit board tracking now requires PFAS-free certification, with OEMs auditing supply chains for compliance documentation.
Consolidated procurement by pharmaceutical contract packagers is compressing supplier counts and unbundling hardware-media bundled contracts. Large CMOs in the United States now negotiate ribbon supply separately from printer maintenance agreements, opening direct sourcing channels previously controlled by OEM-certified programs. This disintermediation is most visible in New Jersey and North Carolina packaging clusters serving FDA-regulated drug distribution.
Thermal Transfer Roll Market Segmentation
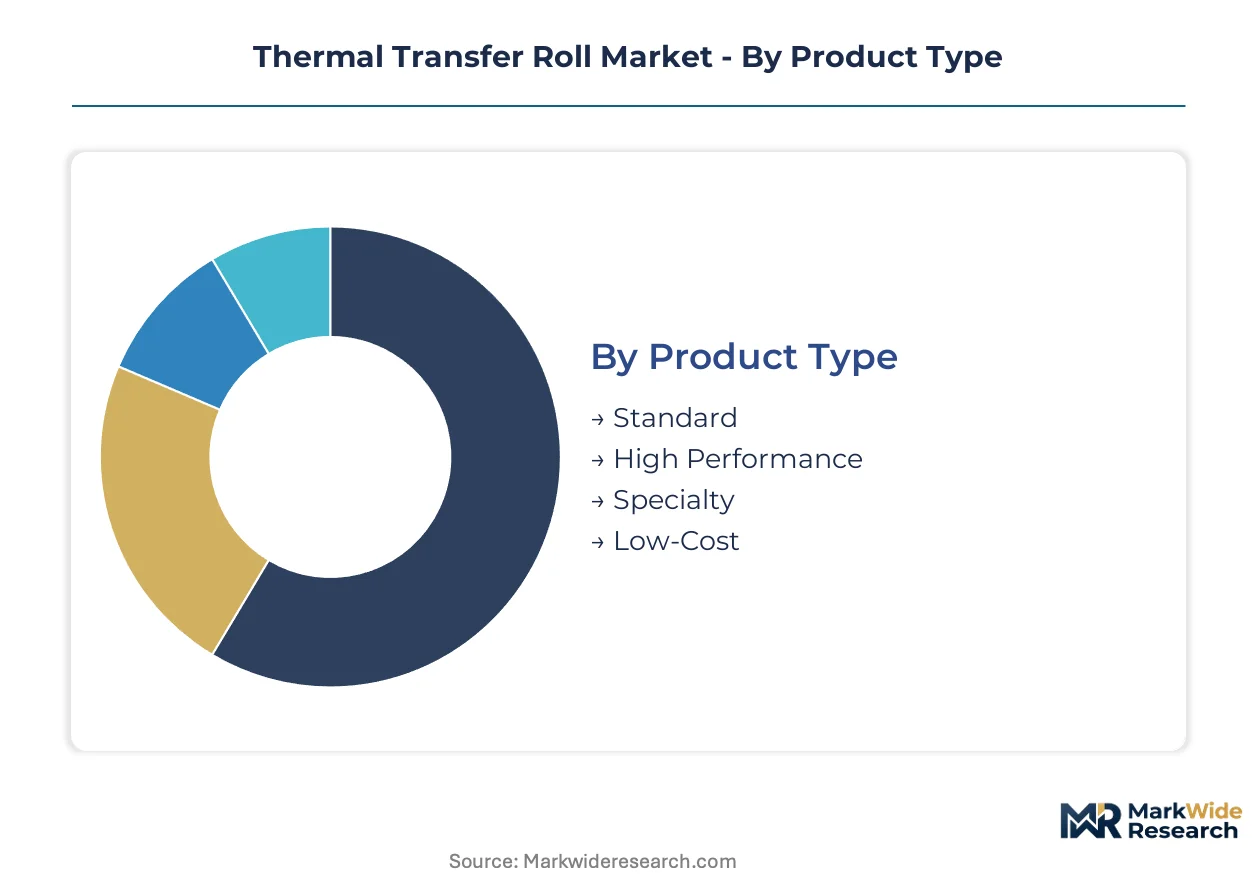
Thermal transfer roll specifications diverge sharply across use cases, with pharmaceutical serialization and cold-chain logistics driving premium formulation requirements. After-sales service intensity varies by segment, as resin-grade installations demand printhead calibration support and compliance documentation that wax-roll deployments rarely require.
Product Type:
After-sales service intensity escalates from economy grades through specialty formulations, with high-performance and specialty rolls requiring OEM-certified technician visits for qualification protocols.
- High Performance:Resin-dominant coatings deliver solvent resistance and print permanence for FDA DSCSA and EU MDR compliance. Pharmaceutical serialization in Germany and Japan consumes these grades where sterilization cycles and chemical exposure threaten standard formulations. Technical support contracts bundle printhead maintenance with media supply agreements.
- Specialty:Cryogenic-grade and sterilization-indicator formulations serve biologics cold chains and surgical tray tracking. Temperature excursion labels for mRNA vaccine distribution and gamma-radiation markers represent the steepest expansion trajectory as healthcare supply chains deepen track-and-trace requirements.
- Standard:Wax-resin blends balance abrasion resistance with cost for logistics barcode labels in retail distribution.
- Low-Cost:Basic wax formulations occupy high-volume shipping applications with minimal technical support overhead.
High Performance holds the largest share; momentum sits with Specialty.
Material:
Cost tier separation runs from commodity wax through precision resin systems, with coating chemistry directly determining end-market access and margin structure.
- Resin:Premium polyester-backed formulations with thermoplastic binders withstand aggressive solvents and extended UV exposure. Electronics labeling in Japan and pharmaceutical packaging in the United States standardize these grades for permanent asset identification. REACH-compliant halogen-free variants command specification premiums.
- Wax-Resin:Hybrid coatings marry smudge resistance with moderate durability for warehouse barcode labels in logistics networks.
- Wax:Paraffin-based formulations serve short-life retail price marking with minimal chemical resistance requirements.
- Thermal:Direct thermal substrates eliminate ribbon consumption entirely in e-commerce shipping label applications.
Resin dominates revenue concentration; Wax-Resin expands most quickly in mid-tier logistics.
Application:
Application focus determines specification stringency, with regulated industries imposing certification barriers that commodity segments bypass.
- Barcode Printing:Pharmaceutical serialization under FDA DSCSA and EU MDR mandates chemical-resistant resin formulations with print permanence through distribution cycles. Track-and-trace compliance in the United States, Germany, and Japan standardizes high-performance grades across packaging lines.
- Labeling:Product identification spans food packaging durability requirements to industrial safety warnings.
- Packaging:Secondary and tertiary packaging labels balance cost with handling resistance in fulfillment operations.
- Asset Tracking:Fixed asset and IT equipment labeling demands long-term legibility with moderate environmental exposure.
Barcode Printing commands the specification premium; Labeling captures the broadest volume base.
End User:
Customer type dictates procurement sophistication, with pharmaceutical and logistics sectors driving divergent specification and service models.
- Pharmaceuticals:Serialization mandates under FDA DSCSA and EU MDR require resin-grade ribbons with documented batch traceability and printhead compatibility certification. Contract packagers in New Jersey and North Carolina negotiate direct ribbon supply separate from printer maintenance agreements.
- Logistics:E-commerce fulfillment and third-party distribution centers consume high-volume wax-resin blends with minimal qualification overhead.
- Manufacturing:Work-in-process and finished goods labeling spans automotive component tracking to electronics assembly verification.
- Retail:Price marking and shelf-edge labeling prioritize cost minimization over durability in short-rotation applications.
Pharmaceuticals generates the highest margin pool; Logistics delivers the largest unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's resin coating supply chain, while Japan's Chubu Centrair International Airport anchors pharmaceutical cold-chain distribution across East Asia.
United States
FDA DSCSA serialization deadlines and contract packaging consolidation in New Jersey and North Carolina drive resin-grade ribbon procurement. The FDA enforces track-and-trace compliance through 2024-2025 phased implementation. Philadelphia's pharmaceutical corridor hosts CDMOs now sourcing ribbons separately from printer maintenance contracts.
Germany
EU MDR medical device traceability mandates and Bayer's aqueous coating conversion pull halogen-free resin formulations. ECHA REACH Annex XVII restrictions on PFAS substances force coating chemistry reformulation. The Rhine-Main packaging cluster around Frankfurt serves as the testing ground for water-based resin dispersion adoption.
Japan
METI-aligned pharmaceutical serialization and electronics labeling durability requirements standardize resin ribbon deployment. The PMDA enforces prescription drug track-and-trace through domestic packaging line certification. The Chubu region surrounding Nagoya concentrates precision coating assets serving semiconductor and pharmaceutical end users.
India
CDSCO serialization alignment with FDA DSCSA and pharmaceutical export growth create demand for barcode-grade ribbons in contract packaging. The DGFT monitors API and finished dosage traceability for US-bound shipments. Ahmedabad's pharmaceutical formulation cluster drives ribbon specification upgrades among CMOs serving American markets.
China
NMPA drug traceability expansion and domestic biologics cold-chain investment accelerate specialty-grade media consumption. SAMR oversees medical product serialization compliance across provincial manufacturing bases. The Yangtze River Delta pharmaceutical corridor around Shanghai deploys resin formulations for temperature excursion labeling in mRNA vaccine distribution.
Thermal Transfer Roll Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream controlling formulation chemistry and substrate quality. The market structures around three tiers: printer OEMs bundling certified media programs, captive resin coaters with backward integration into polyester film production, and independent ribbon converters serving price-sensitive logistics segments. Two competitive moves dominate: capacity expansion in halogen-free coating platforms and geographic footprint consolidation to serve pharmaceutical contract packagers directly.
Among Japanese coating specialists, DNP Corporation and Ricoh Company, Ltd. occupy positions emphasizing material quality control from substrate to finished ribbon. European manufacturing presence clusters around ARMOR Group's regional footprint strategy. Zebra Technologies Corporation exemplifies the platform integrator archetype, bundling hardware deployment with certified media supply agreements that govern end-user procurement.
| Leading Market Players |
|---|
| DNP Corporation |
| ARMOR Group |
| ITW Thermal Films |
| Zebra Technologies Corporation |
| SATO Holdings Corporation |
| Ricoh Company, Ltd. |
| Honeywell International Inc. |
| Toshiba Tec Corporation |
| Brady Corporation |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's chemical handling infrastructure shapes cost dynamics across European resin coating supply, concentrating upstream pricing power among German and Dutch halogen-free formulation specialists while downstream buyers in pharmaceutical contract packaging face tiered procurement based on certification grade and volume scale.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade resin ribbons from logistics wax-resin blends, with FDA DSCSA and EU MDR certification status driving the steepest price premiums. Price differentiation rests on REACH compliance grade and printer OEM qualification status, with Zebra and SATO certified media commanding substantial markups over unqualified alternatives. Cost compression in standard wax rolls intensifies as direct thermal substitution eliminates ribbon consumption in e-commerce fulfillment. Logistics operators show highest price sensitivity, while pharmaceutical CMOs prioritize compliance documentation over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts polyester film substrate flows that feed coating operations in Japan and Germany. Geographic supply concentration centers on Japan, Germany, and the Netherlands for halogen-free resin formulations, with petrochemical derivatives and precision coating equipment as critical inputs. Single-source vulnerability persists for REACH-compliant resin binders sourced from narrow supplier bases. Distribution runs through printer OEM certified-media programs and direct sourcing channels opened by pharmaceutical contract packager consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates durable competitive positions. FDA DSCSA and EU MDR certification timelines lock in incumbent relationships through 18-24 month qualification protocols that new entrants cannot bypass.
For Market Incumbents: Insulate market position by deepening captive resin-coating capacity to control substrate quality from polyester film through finished ribbon. Add halogen-free formulation capacity in Germany or Japan to capture REACH-driven substitution demand. Direct thermal substitution in e-commerce logistics threatens wax-roll volume; counter by bundling technical support contracts with resin-grade pharmaceutical installations.
For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical export corridor where CDSCO serialization alignment with FDA DSCSA creates ribbon demand among CMOs serving American markets. Target sterilization-indicator labels for surgical trays as a specification-premium segment with limited incumbent supply. Pursue aqueous coating technology partnerships with European pharmaceutical manufacturers completing solvent-borne line conversions.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized thermal transfer divisions lacking pharmaceutical certification focus. Long-term viability favors coating specialists with backward integration into resin chemistry and substrate production. Monitor PFAS regulatory enforcement as the inflection signal for premium reformulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Coating Platform Expansion | REACH Annex XVII compliance opens substitution windows for bisphenol-A-free and chlorine-free alternatives in German pharmaceutical packaging. |
| Printer OEM Certification Investment | Zebra and SATO qualification protocols govern commercial access to pharmaceutical contract packagers in New Jersey and North Carolina. |
| Aqueous Coating Line Conversion | Bayer and Sanofi manufacturing sites in Germany have eliminated VOC emissions while maintaining barcode permanence standards. |
| Direct Sourcing Channel Development | Large CMOs now negotiate ribbon supply separately from printer maintenance agreements, bypassing traditional OEM bundling. |
| Sterilization-Indicator Label Capacity Addition | Steam and gamma-radiation exposure markers for surgical trays carry specification premiums with limited incumbent supply. |
Study Parameters
Initial hypotheses were tested against primary input from coating plant managers, pharmaceutical packaging procurement leads, printer OEM technical certification directors, and logistics channel partners and refined through secondary validation. Trade data from customs authorities, ECHA REACH substance restriction filings, SEC 10-K disclosures from listed coating specialists, and FDA DSCSA implementation guidance documents anchored quantitative sizing. Bottom-up volume modeling across resin, wax-resin, and wax formulation tiers triangulated against top-down pharmaceutical serialization mandate impact assessments.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product performance tier, coating chemistry type, end-use application, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to pharmaceutical track-and-trace compliance timelines and cold-chain logistics expansion trajectories. Forecast inputs incorporated printer OEM certification pipeline data and PFAS regulatory enforcement probability assessments.
Sensitivities concentrate around petrochemical feedstock volatility, REACH chemical restriction expansion, and direct thermal substitution rates in e-commerce fulfillment. Forecasts reflect assumptions on regulatory implementation pacing and coating technology conversion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Single Dose Detergent Packaging Market
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Vacuum Packaging Market
Packaging Materials
Carded Packaging Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Nigeria Packaging Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Food Grade Sealant Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Cavitated Films Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Europe Single-Use Packaging Market