
 MDPE Bottles Market | 2026-2036
MDPE Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
MDPE Bottles Market Foresight
Asset-light leasing models for blow-molding equipment is reconfiguring competitive entry barriers, allowing mid-sized converters to scale without heavy capese commitments. Amcor plc leverages its integrated resin sourcing networks to sustain margin stability across volatile polymer cycles. Berry Global Group anchors North American supply through distributed manufacturing footprints. ALPLA Group competes via specialized lightweighting technologies that reduce per-unit resin consumption.
Medium-density polyethylene bottles are thermoplastic containers manufactured through extrusion blow-molding of ethylene-hexene copolymers with densities ranging from 0.926 to 0.940 g/cm³, valued for their balance of stiffness, stress-crack resistance, and moisture barrier properties in liquid packaging applications. Storage bottles occupy the largest volume share within product type segmentation due to universal adoption across household and industrial chemical segments. Squeeze bottles represent the fastest-expanding category, driven by personal care brands seeking differentiated dispensing formats. The 500ml size tier captures disproportionate margin contribution in beverage end-use applications where premium positioning commands higher unit economics.
FDA food-contact regulations and EU REACH compliance frameworks govern resin additive approvals and migration limits, directly constraining formulation choices for converters serving regulated end-uses. EPA guidelines on post-consumer recycled content integration are pressuring virgin resin dependency in US-sourced production. BIS certification requirements in India add another compliance layer for exporters targeting pharmaceutical packaging segments. Stakeholders must monitor evolving extended producer responsibility mandates across multiple jurisdictions to anticipate recyclability-driven material specification shifts.
Market Dynamics
Asset-light leasing models for blow-molding equipment are collapsing capital barriers for mid-sized converters, enabling rapid capacity scaling without balance-sheet strain. This structural shift is redistributing competitive leverage toward agile regional players and away from legacy asset-heavy incumbents.
Growth Catalysts
- FDA food-contact standards:Tightening migration limits for resin additives are filtering out substandard converters and consolidating procurement among certified suppliers serving beverage bottlers.
- India's manufacturing clusters:Cost-efficient blow-molding capacity scaling in Gujarat and Maharashtra is drawing multinational packaging procurement away from higher-cost origins.
- Lightweighting technologies:Advanced parison control systems are reducing per-unit resin consumption by 8-12% without compromising drop-impact performance.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker economics tie MDPE resin pricing to volatile energy markets, compressing converter margins during upstream spikes.
- Chinese resin oversupply:State-subsidized polyethylene capacity additions are dumping low-cost virgin material into Southeast Asian markets.
- Substitution by PET:Carbonated beverage brands are reverting to polyethylene terephthalate for high-pressure applications where MDPE's stress-crack resistance offers insufficient advantage.
Strategic Opportunities
- Post-consumer recycled mandates:EPA guidelines on recycled content integration are creating first-mover advantages for converters with advanced decontamination capabilities.
- Pharmaceutical packaging in India:BIS certification requirements for drug-contact applications are raising entry barriers and rewarding compliant domestic producers.
- E-commerce liquid fulfillment:Leak-resistant squeeze formats are capturing share in direct-to-consumer personal care channels previously dominated by rigid containers.
Industry Challenges
- Multi-jurisdiction compliance timelines:Simultaneous REACH, FDA, and BIS certification requirements are extending product qualification cycles by 6-9 months.
- Retrofitting legacy extrusion lines:Integrating Industry 4.0 process controls with 1990s-vintage blow-molding equipment demands specialized automation engineering scarce in regional labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MDPE Bottles Market |
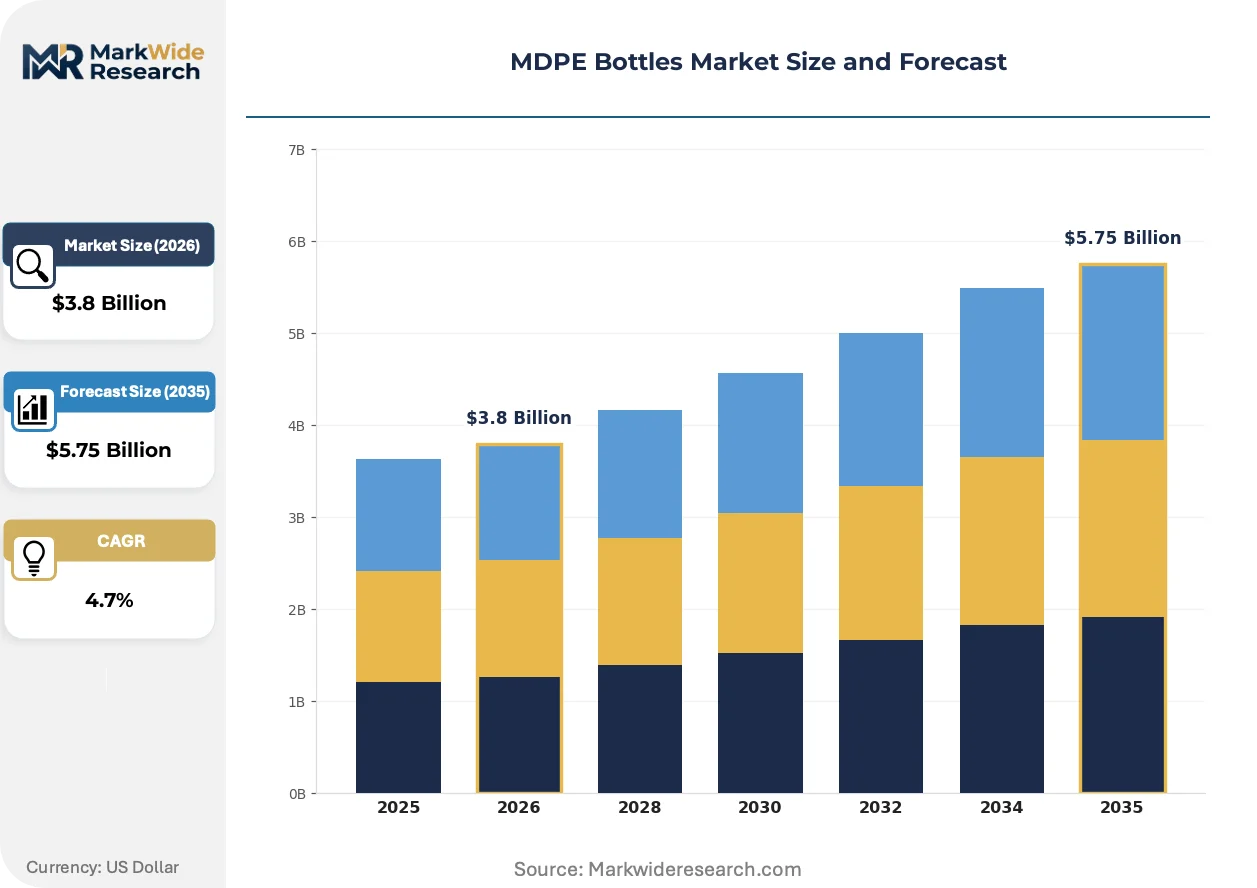
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispensing Bottles, Storage Bottles, Squeeze Bottles, Spray Bottles End User: Pharmaceuticals, Beverages, Personal Care, Chemical Industry Size: 50ml, 100ml, 250ml, 500ml Closure Type: Screw Caps, Flip Top, Trigger Sprays, Tamper Evident |
| Companies Covered | Amcor plc, Berry Global Group, Trimurti Plast Containers, Shenzhen Qihai Technology, The Plastic Bottles Company, ALPLA Group, Graham Packaging Company, Silgan Holdings Inc., Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MDPE Bottles Market Shifts & Advancements
Convergence between material science and process automation is compressing development cycles and enabling specification-grade customization at mass-production economics. Three distinct vectors are restructuring competitive advantage.
Coextrusion barrier technology is hybridizing MDPE with ethylene vinyl alcohol laminates to extend oxygen-sensitive product shelf life. Nutraceutical brands in Germany and Switzerland are specifying these structures for omega-3 oil packaging, forcing converters to reconfigure parison programming for multi-layer distribution. The technology is hybridizing commodity resin economics with performance polymer functionality.
REACH SVHC candidate list expansions are accelerating substitution of conventional antioxidants and UV stabilizers in resin formulations. ECHA's 2024-2025 updates have designated several hindered phenolic compounds, compelling reformulation investments across European-serving production. Pharmaceutical packaging converters in the Netherlands and Belgium are responding fastest, locking in additive approvals ahead of sunset dates.
Direct converter relationships with resin producers are displacing distributor intermediaries for volume-stable beverage accounts. Tier-one bottlers in Brazil and Mexico are negotiating annual fixed-volume contracts with Saudi and Qatari petrochemical suppliers, capturing basis-point margin improvements unavailable through spot-market purchasing. This pattern is most visible in 500ml and 1-liter beverage formats where specification standardization enables long-term commitments.
MDPE Bottles Market Segmentation
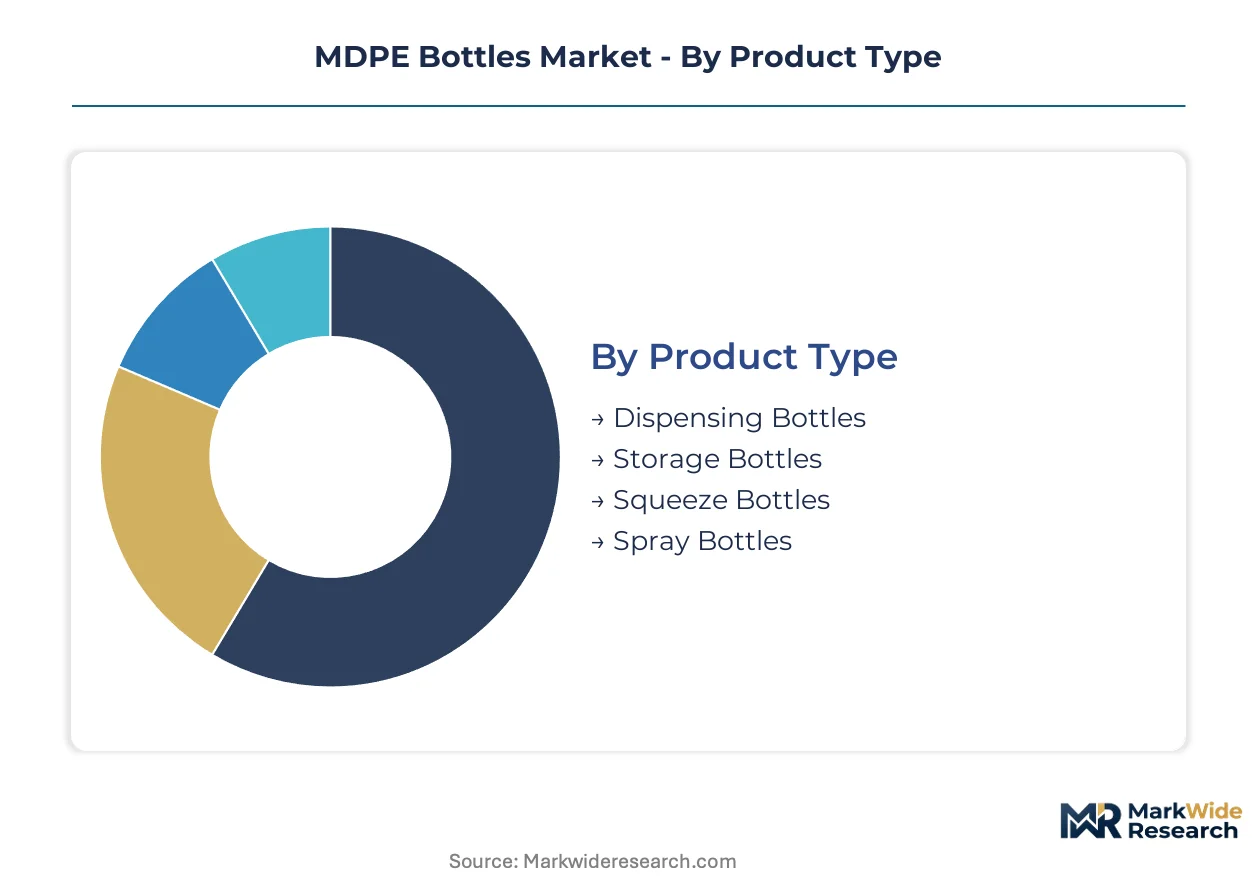
MDPE bottle specifications diverge sharply across end-use requirements, with pharmaceutical and beverage applications demanding incompatible performance profiles. Converters configure extrusion parameters, barrier architecture, and closure systems to match precise functional mandates rather than pursuing commodity standardization.
Product Type:
Use-case spectrum spans controlled dispensing to bulk containment, with each format optimized for distinct liquid rheology and user interaction patterns.
- Storage Bottles:Cylindrical containers with reinforced shoulder geometry maximize cubic efficiency in palletized distribution. Household chemical manufacturers in Gujarat and Maharashtra specify these for bleach and detergent concentrates where stack-load resistance outweighs dispensing precision.
- Squeeze Bottles:Controlled-deformation sidewalls enable metered dispensing without secondary pumps. Personal care brands targeting e-commerce direct fulfillment in Germany and Switzerland are specifying leak-resistant variants for shampoo and conditioner subscriptions.
- Dispensing Bottles:Narrow-neck designs with calibrated orifice control suit laboratory reagent packaging.
- Spray Bottles:Pressure-tolerant cylindrical bodies accommodate trigger-actuated atomization for surface cleaners.
The dominant share belongs to Storage Bottles, while Squeeze Bottles are closing the gap fastest.
End User:
Customer procurement patterns split between specification-driven regulated sectors and cost-optimized consumer categories.
- Beverages:FDA food-contact compliance and EU REACH additive restrictions constrain resin formulation choices. Bottlers in Brazil and Mexico negotiate annual fixed-volume contracts with Saudi and Qatari resin suppliers to lock in margin stability.
- Pharmaceuticals:BIS certification requirements in India and migration limit testing under EMA guidelines in Europe extend qualification cycles. Dutch and Belgian converters are securing additive approvals ahead of ECHA sunset dates.
- Personal Care:Brand differentiation through tactile surface finishes and ergonomic grip geometry drives format innovation.
- Chemical Industry:Stress-crack resistance specifications prioritize resin molecular weight distribution over aesthetic properties.
Beverages command the largest procurement volumes, though Pharmaceuticals is climbing fastest as certification barriers filter out marginal competitors.
Size:
Volume tiers correlate with distribution economics and consumption occasion granularity.
- 500ml:The standard beverage single-serve format where premium positioning enables superior unit economics. Brazilian and Mexican bottlers standardize on this tier to maximize line efficiency across brand portfolios.
- 250ml:Travel-size personal care and pharmaceutical sampling formats where TSA compliance and portability drive specification.
- 100ml:Clinical trial packaging and airline amenity applications.
- 50ml:High-value concentrate and diagnostic reagent containment.
The 500ml tier anchors production volume, while 250ml is gaining share fastest through e-commerce sample proliferation.
Closure Type:
Sealing mechanisms determine shelf-life integrity, child-safety compliance, and user experience differentiation.
- Screw Caps:Universal threading compatibility and tamper-evident band integration suit regulated pharmaceutical applications. Swiss nutraceutical brands specify these for omega-3 oil packaging where oxygen ingress control is critical.
- Tamper Evident:Break-ring or shrink-band designs provide visible integrity assurance for over-the-counter drug distribution.
- Flip Top:Single-handed actuation suits personal care and food condiment dispensing.
- Trigger Sprays:Integrated pump mechanisms for household and industrial surface treatment chemicals.
Screw Caps retain the largest installed base, yet Tamper Evident formats are expanding most quickly as pharmaceutical serialization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in MDPE bottles track resin availability and blow-molding capacity density, with export-oriented manufacturing clusters in Asia drawing procurement away from legacy Atlantic basin suppliers. Import dependency ratios diverge sharply between polymer-producing and converting-only economies.
United States
Beverage bottlers along the Gulf Coast leverage proximity to ethylene crackers in Texas and Louisiana for feedstock cost advantages. EPA guidelines on post-consumer recycled content integration are pressuring converters serving regulated end-uses. Chicago-area converters are retrofitting extrusion lines with Industry 4.0 controls to meet pharmaceutical serialization mandates.
Germany
Nutraceutical brands in Bavaria specify coextrusion barrier structures for oxygen-sensitive omega-3 oil packaging. ECHA's 2024-2025 SVHC candidate list expansions are compelling reformulation investments across resin additive portfolios. The Ruhr Valley industrial corridor hosts specialized converters securing additive approvals ahead of sunset dates.
India
Cost-efficient blow-molding capacity scaling in Gujarat and Maharashtra is capturing multinational packaging procurement from higher-cost origins. BIS certification requirements for pharmaceutical packaging segments are raising entry barriers and rewarding compliant domestic producers. The Delhi-NCR cluster is expanding squeeze bottle output for e-commerce personal care fulfillment.
Brazil
Tier-one bottlers negotiate annual fixed-volume resin contracts with Saudi and Qatari petrochemical suppliers to lock in margin stability. ANVISA pharmaceutical regulations constrain migration limits for drug-contact applications. São Paulo-state converters standardize on 500ml formats to maximize line efficiency across beverage brand portfolios.
China
State-subsidized polyethylene capacity additions are dumping low-cost virgin material into Southeast Asian export markets. GB standards on food-contact materials govern resin purity specifications for domestic beverage applications. The Yangtze River Delta concentrates blow-molding equipment manufacturing and aftermarket servicing capabilities.
MDPE Bottles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The MDPE bottles sector exhibits tiered consolidation with multinational converters holding beverage and pharmaceutical accounts while regional fabricators serve cost-sensitive chemical and household segments. Three archetypes dominate: integrated resin-to-package conglomerates with captive polymer sourcing, specialized lightweighting technology developers, and agile regional converters leveraging asset-light equipment leasing. Dominant competitive moves include backward integration into resin distribution relationships and geographic expansion through distributed manufacturing footprints.
Among integrated packaging conglomerates, Amcor plc and Berry Global Group occupy positions exemplifying scale-driven supply security. ALPLA Group represents the specialized technology tier with concentrated expertise in parison control systems. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group |
| Trimurti Plast Containers |
| Shenzhen Qihai Technology |
| The Plastic Bottles Company |
| ALPLA Group |
| Graham Packaging Company |
| Silgan Holdings Inc. |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
Gujarat and Maharashtra manufacturing clusters concentrate blow-molding capacity expansion, feeding downstream pricing power to converters serving multinational beverage and pharmaceutical accounts. Naphtha-cracker economics tie MDPE resin costs to volatile energy markets, while asset-light equipment leasing redistributes margin capture toward agile regional players.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across beverage and pharmaceutical segments. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified pharmaceutical grades from FDA food-contact tiers and uncertified chemical packaging. Cost compression in standard-grade tiers is intensifying because Chinese state-subsidized resin oversupply dumps low-cost virgin material into Southeast Asian markets. Household chemical manufacturers show highest price sensitivity due to specification commoditization, while Swiss nutraceutical brands accept premium positioning for oxygen-barrier coextrusion structures.
Supply Chain Analysis
Specialized converters in India, Germany, and Brazil hold differentiated capacity for regulated end-uses. Raw material feeds draw from Saudi and Qatari ethylene crackers, Texas-Louisiana Gulf Coast petrochemical complexes, and state-subsidized Chinese polyethylene additions. Single-source vulnerability concentrates in naphtha-derived ethylene feedstock exposed to energy market volatility. Distribution runs through direct converter relationships with resin producers displacing distributor intermediaries for volume-stable beverage accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among tier-one beverage bottlers is shifting bargaining power upstream, fragmenting converter margins unless countered by specification differentiation or captive resin sourcing.
For Market Incumbents: Harden additive approval pipelines ahead of ECHA sunset dates to lock pharmaceutical accounts before REACH SVHC expansions filter out marginal competitors. Deepen backward integration into Saudi and Qatari resin distribution relationships to capture basis-point margin improvements unavailable through spot-market purchasing. Defend squeeze bottle positioning against PET substitution in carbonated applications by emphasizing stress-crack resistance for sensitive liquid formats. For New Entrants and Emerging Players: Southeast Asian pharmaceutical packaging underpenetration offers white-space entry where BIS certification requirements raise barriers for unqualified exporters. Target e-commerce personal care fulfillment channels in Germany and Switzerland with leak-resistant squeeze formats previously dominated by rigid containers. Lead with asset-light blow-molding equipment leasing to scale without balance-sheet strain against legacy asset-heavy incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized lightweighting technology developers with concentrated parison control expertise over commodity converters. Five-to-ten-year viability hinges on recyclability-driven material specification shifts and decontamination capabilities for post-consumer recycled mandates. Monitor EPA guideline evolution on recycled content integration as inflection indicator for first-mover advantage capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Amcor plc sustains margin stability across volatile polymer cycles through integrated networks. |
| Lightweighting Technology Investment | ALPLA Group reduces per-unit resin consumption by 8-12% via advanced parison control systems. |
| REACH Compliance Certification | Dutch and Belgian converters secure additive approvals ahead of ECHA sunset dates for pharmaceutical lock-in. |
| Asset-Light Equipment Leasing | Mid-sized converters in Gujarat and Maharashtra scale rapidly without heavy capital commitments. |
| Direct Resin Producer Relationships | Brazilian and Mexican bottlers negotiate fixed-volume contracts with Saudi and Qatari suppliers. |
Research Methodology
Operator-level perspectives from blow-molding plant managers, beverage procurement leads, pharmaceutical regulatory affairs directors, and resin distribution channel partners anchored the qualitative base. Secondary validation drew from FDA food-contact filings, ECHA REACH registrations, BIS certification databases, and customs trade flow records. Bottom-up capacity surveys across Gujarat, Maharashtra, and Ruhr Valley clusters triangulated with top-down demand modeling from beverage bottler and personal care brand procurement disclosures.
Scenario-bracketing framed volume and value outputs across the analysis window, modeling segmentation by product type, end-use industry, closure system, and regional regulatory cluster. CAGRs derived from iterative convergence between resin price elasticity estimates and blow-molding capacity expansion trajectories. Forecast inputs incorporated ethylene feedstock volatility indices and lightweighting technology diffusion curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-subsidized resin producers or rapid EPA recycled mandate acceleration would shift outcomes. Quarterly review of ECHA SVHC candidate list updates and naphtha-cracker margin spreads is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
Clear Plastic Boxes Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
Europe Blow Molded Plastic Market