
 Packaging Racks Market | 2026-2036
Packaging Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Racks Market Outlook
Third-party logistics providers is collapsing historical reliance on in-house warehousing among food and beverage manufacturers, redirecting capital toward outsourced rack infrastructure. Daifuku Co., Ltd. leverages its automated material handling heritage to dominate integrated rack-robotics installations across Asia-Pacific distribution hubs. Bluff Manufacturing anchors its position through heavy-duty steel rack specialization for automotive and industrial manufacturing floors. Mecalux S.A. competes on modular adjustable rack architectures that accommodate SKU proliferation in European pharmaceutical cold storage.
Packaging racks are engineered load-bearing frameworks, typically fabricated from welded tubular steel or extruded aluminum profiles with powder-coated or galvanized finishes, designed to stabilize palletized goods, individual cartons, or intermediate bulk containers during storage, transport, and order fulfillment operations. Static racks retain dominance in high-density warehouse storage for homogeneous pallet loads with predictable turnover cycles, while mobile racking systems capture the fastest expansion in refrigerated pharmaceutical and fresh food distribution where floor-space premiums justify motorized carriage infrastructure. Aluminum and plastic material segments are displacing conventional steel in electronics and textile end uses where corrosion resistance and lightweight handling reduce freight cost exposure.
OSHA workplace safety standards and EU machinery directives (CE marking) mandate load-rating documentation and anti-tip engineering for industrial rack installations, elevating compliance costs for entry-tier suppliers while favoring certified manufacturers. EPA industrial emissions frameworks and REACH substance restrictions on surface coatings are reshaping material specification decisions across steel and aluminum supply chains. Stakeholders must monitor evolving carbon-border adjustment mechanisms and building-code harmonization between warehouse automation and structural engineering disciplines to anticipate specification shifts before procurement cycles lock in multi-year rack deployments.
Market Dynamics
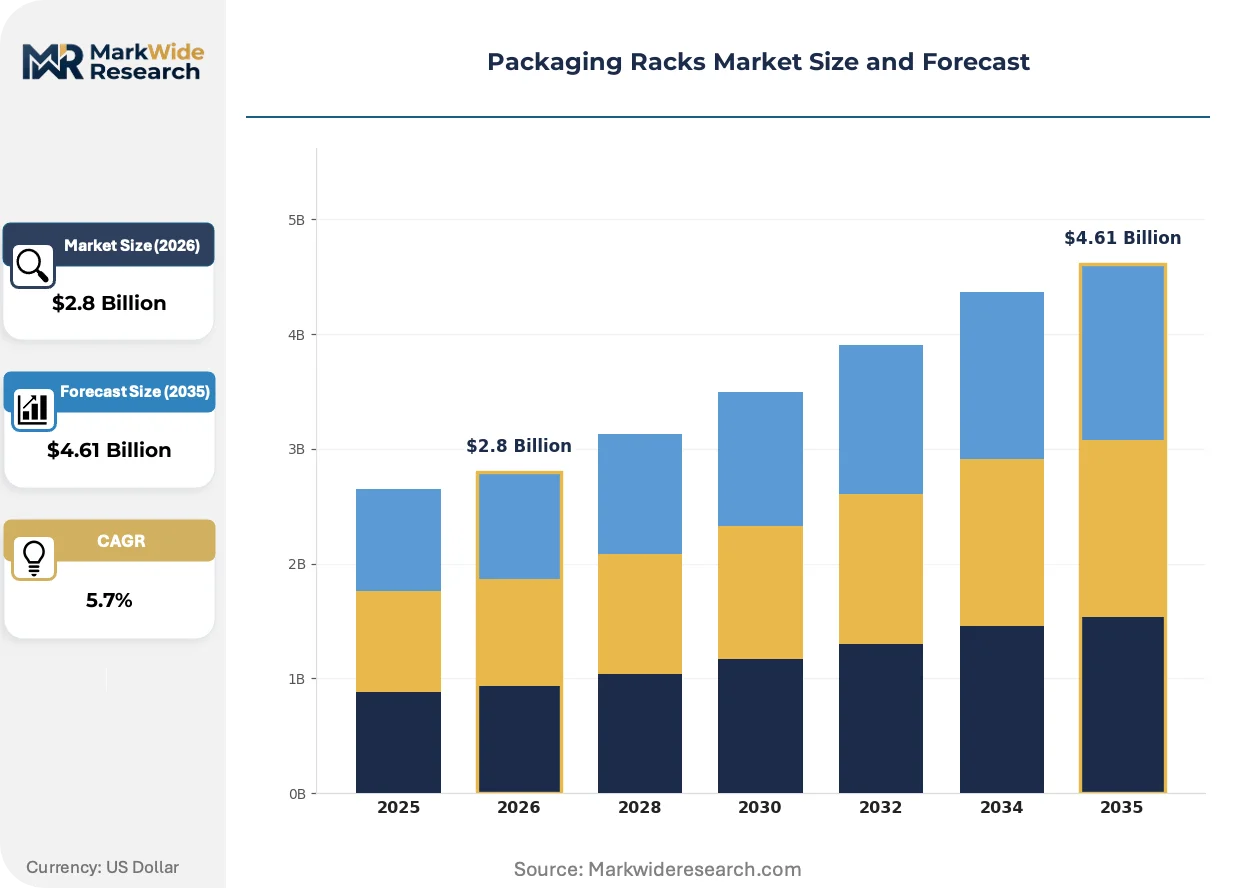
Automated warehouse buildouts and cold-chain infrastructure upgrades are compressing procurement cycles for packaging rack systems as e-commerce fulfillment centers prioritize throughput density over capital expenditure minimization.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Steel and aluminum rack producers face evolving sustainability mandates that accelerate material specification shifts toward lower-carbon fabrication processes.
- Pharmaceutical cold storage expansion:Mobile racking systems capture demand in refrigerated pharmaceutical distribution where floor-space premiums justify motorized carriage infrastructure.
- Last-mile throughput optimization:E-commerce fulfillment centers are expanding procurement of mobile and adjustable rack systems to optimize fulfillment velocity.
Market Restraints
- Steel price volatility:Raw material input cost fluctuations compress margin predictability for welded tubular steel rack fabricators.
- REACH substance restrictions:Surface coating compliance requirements elevate formulation costs and limit supplier flexibility across European markets.
- Fixed-bay rack substitution:Static shelving systems face displacement from dynamic storage technologies in homogeneous pallet load applications.
Strategic Opportunities
- India cold-chain infrastructure:Underpenetrated pharmaceutical and fresh food distribution networks present white space for corrosion-resistant aluminum rack deployments.
- OSHA load-rating documentation mandates:Workplace safety standard enforcement creates certified manufacturer preference windows.
- Robotics-rack convergence:Integrated automated material handling installations enable specification capture in Asia-Pacific distribution hubs.
Industry Challenges
- Anti-tip engineering certification:CE marking compliance timelines extend procurement cycles for entry-tier suppliers seeking European market access.
- Legacy WMS integration:Mobile racking system deployment encounters friction with incumbent warehouse management software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Racks Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Racks, Mobile Racks, Adjustable Racks, Heavy-Duty Racks Material: Steel, Aluminum, Plastic, Wood Application: Warehouse Storage, Retail Displays, Shipping Logistics, Manufacturing End User: Food & Beverage, Pharmaceuticals, Electronics, Textiles |
| Companies Covered | PS Ideal Solutions, Bluff Manufacturing, Creative Plastics, Schematic System, Bradford Company, Lamar Packaging Systems, Mecalux S.A., Daifuku Co., Ltd., Kardex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Racks Market Strategic Shifts
Material substitution and regulatory compliance automation are compressing traditional specification hierarchies while reshaping competitive positioning across fabrication technologies.
Extruded aluminum rack profiles are displacing conventional steel in electronics and textile end uses where corrosion resistance and lightweight handling reduce freight cost exposure. Electronics manufacturers with high-SKU variability are adopting aluminum systems at accelerated pace. This displacement is compressing steel rack share in freight-sensitive applications.
REACH substance restrictions on surface coatings are reshaping material specification decisions across steel and aluminum supply chains. Industrial emissions frameworks mandate documentation burdens that favor integrated coating-fabrication operations. Pharmaceutical cold storage rack suppliers in Germany and France are consolidating coating compliance in-house.
Third-party logistics providers are collapsing historical reliance on in-house warehousing among food and beverage manufacturers. Capital redirection toward outsourced rack infrastructure is fragmenting buyer concentration. This pattern is most visible in United States distribution networks where beverage manufacturers divest captive warehouse assets.
Packaging Racks Market Segmentation
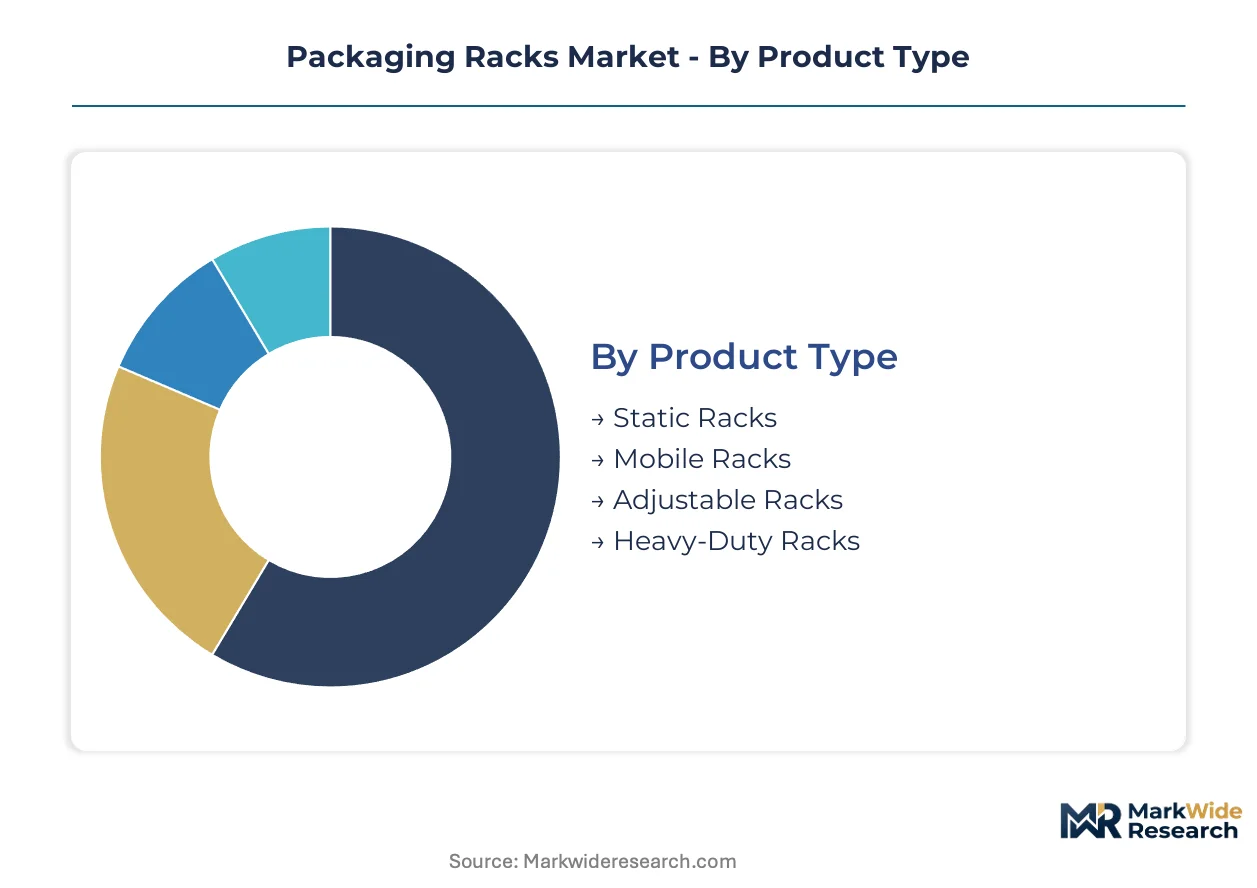
Packaging rack procurement channels diverge sharply across end-use verticals, with e-commerce fulfillment centers favoring mobile configurations while automotive manufacturing floors anchor demand for heavy-duty steel systems. Specification decisions cascade through material selection, load-rating requirements, and integration complexity with warehouse automation infrastructure.
Product Type:
Channel flow separates static rack volumes through distributor networks serving traditional warehousing, while mobile and adjustable systems move direct through systems integrators targeting automated fulfillment environments.
- Static Racks:Welded tubular steel frameworks with fixed bay configurations dominate high-density warehouse storage for homogeneous pallet loads with predictable turnover cycles. Demand concentrates in Germany and the United States where legacy distribution centers prioritize capital expenditure minimization over throughput velocity.
- Mobile Racks:Motorized carriage infrastructure on rail-mounted bases captures specification in refrigerated pharmaceutical and fresh food distribution where floor-space premiums justify higher capital investment. China and India cold-chain buildouts are accelerating procurement of these systems for last-mile consolidation hubs.
- Adjustable Racks:Modular beam-and-upright architectures accommodate SKU proliferation in European pharmaceutical storage.
- Heavy-Duty Racks:Reinforced steel fabrication with enhanced load ratings serves automotive and industrial manufacturing floors in the United States and Germany.
By volume, Static Racks leads. By growth pace, Mobile Racks is ahead.
Material:
Cost tier stratification places steel at economy positioning, aluminum at premium freight-sensitive applications, and plastic at specialized corrosion-resistant niches.
- Steel:Welded tubular profiles with powder-coated or galvanized finishes retain dominance in high-load warehouse and manufacturing applications. EPA industrial emissions guidelines and EU Green Deal carbon-border adjustments are forcing specification shifts toward lower-carbon fabrication processes among producers in Germany and the United States.
- Aluminum:Extruded profiles with anodized or powder-coated surfaces displace steel in electronics and textile end uses where corrosion resistance and lightweight handling reduce freight cost exposure. Electronics manufacturers with high-SKU variability are adopting aluminum systems at accelerated pace.
- Plastic:Injection-molded or rotationally molded polymer construction serves cleanroom pharmaceutical and food-grade applications requiring washdown compatibility.
- Wood:Engineered timber and plywood decking provides economical containment for bulk agricultural and textile shipments with lower structural demands.
Steel commands the volume base. Aluminum is climbing the fastest on material substitution trends.
Application:
Customer type segmentation separates capital-intensive automated warehouse deployments from operational-expense-driven retail and logistics configurations.
- Warehouse Storage:High-density pallet racking systems with selective, drive-in, or push-back configurations optimize cubic utilization in distribution centers. Demand concentrates in China, Germany, and the United States as these countries anchor automated warehouse buildouts.
- Shipping Logistics:Collapsible and nestable rack designs facilitate empty return logistics in third-party freight networks. E-commerce fulfillment centers are expanding procurement of mobile and adjustable rack systems to optimize last-mile throughput.
- Retail Displays:Aesthetic rack systems with branded finishes serve consumer-facing floor and fixture applications.
- Manufacturing:Heavy-duty work-in-process staging racks integrate with production line flow in automotive and industrial assembly environments.
Warehouse Storage holds the installed base. Shipping Logistics is expanding most quickly on e-commerce fulfillment velocity pressures.
End User:
Maturity differentiation separates established warehousing verticals from emerging cold-chain and high-SKU electronics applications with distinct compliance and specification requirements.
- Food & Beverage:Corrosion-resistant coatings and washdown-compatible designs serve refrigerated and frozen storage requirements. Third-party logistics providers are collapsing historical reliance on in-house warehousing among food and beverage manufacturers, redirecting capital toward outsourced rack infrastructure.
- Pharmaceuticals:Mobile racking systems with temperature monitoring integration capture demand in refrigerated pharmaceutical distribution where floor-space premiums justify motorized carriage infrastructure. REACH substance restrictions on surface coatings are reshaping material specification decisions across European supply chains.
- Electronics:Lightweight aluminum systems with electrostatic discharge protection serve high-value component storage.
- Textiles:Long-span shelving with garment-on-hanger compatibility addresses fashion and apparel distribution requirements.
Food & Beverage anchors volume procurement. Pharmaceuticals is gaining share fastest on cold-chain infrastructure upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity for packaging rack systems clusters in Germany, China, and the United States, where automated warehouse buildouts and cold-chain infrastructure upgrades concentrate procurement volumes. These three markets anchor specification trends that radiate into adjacent regions through export flows and technology licensing.
United States
E-commerce fulfillment velocity pressures drive procurement of mobile and adjustable rack systems across distribution hubs. OSHA workplace safety standards mandate load-rating documentation and anti-tip engineering, elevating compliance costs for entry-tier suppliers. The Southeast corridor from Atlanta to Charlotte anchors heavy-duty steel rack demand serving automotive manufacturing floors.
Germany
EU Green Deal carbon-border adjustments force steel and aluminum rack producers toward lower-carbon fabrication processes. REACH substance restrictions on surface coatings reshape material specification decisions across supply chains. The Ruhr industrial belt concentrates pharmaceutical cold storage rack production with integrated coating-fabrication operations.
China
Automated warehouse buildouts and last-mile consolidation hubs accelerate mobile racking system procurement. Dual carbon goals under MEE frameworks pressure steel producers toward emissions-intensive process upgrades. Yangtze River Delta distribution centers anchor demand for corrosion-resistant aluminum systems in electronics storage.
India
Underpenetrated pharmaceutical and fresh food distribution networks present expansion opportunities for corrosion-resistant aluminum rack deployments. BIS standards govern structural safety certification for industrial rack installations. Maharashtra and Gujarat cold-chain buildouts concentrate procurement of motorized carriage infrastructure for space-constrained urban hubs.
Japan
High-SKU electronics manufacturers adopt lightweight aluminum systems with electrostatic discharge protection at accelerated pace. METI industrial efficiency guidelines incentivize space-optimizing storage technologies. Kansai region automotive suppliers anchor demand for heavy-duty work-in-process staging racks integrated with production line flow.
Packaging Racks Market Competitive Environment
Concentration sits with integrated material handling specialists and regional fabrication heavyweights. The vendor base stratifies across three tiers: multinational automation conglomerates with rack-robotics convergence capabilities, mid-cap metal fabricators with vertical specialization in steel or aluminum, and regional job shops serving price-sensitive warehousing applications. Dominant competitive moves include strategic partnerships with warehouse management software providers and capacity expansion into underpenetrated cold-chain corridors.
Among Asia-Pacific integrated specialists, Daifuku Co., Ltd. occupies a position exemplifying automated material handling heritage, while Mecalux S.A. represents European modular architecture capabilities. Bluff Manufacturing anchors the heavy-duty steel fabrication tier serving automotive and industrial manufacturing floors. These three entities illustrate how competitive positioning fragments across geography and specialization rather than consolidating around unified product architectures.
| Leading Market Players |
|---|
| PS Ideal Solutions |
| Bluff Manufacturing |
| Creative Plastics |
| Schematic System |
| Bradford Company |
| Lamar Packaging Systems |
| Mecalux S.A. |
| Daifuku Co., Ltd. |
| Kardex Group |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day steel coil lead times from German and Chinese mills compress procurement flexibility for rack fabricators, concentrating pricing power with vertically integrated coating-fabrication operations while forcing spot-market buyers into premium freight absorption. This inventory pressure feeds directly into tiered quotation structures that separate certified manufacturers from uncertified job shops across European and North American distribution networks.
Pricing Analysis
EU Green Deal carbon-border adjustments dictate the pricing tier structure across steel and aluminum rack supply chains. Three-tier pricing separates CE-marked premium systems from standard OSHA-compliant configurations and economy-grade uncertified imports. Price differentiation hinges on certification grade and volume scale, with pharmaceutical cold-storage buyers absorbing premium coatings while beverage logistics operators drive standard-tier negotiations. Cost compression in economy steel fabrication is intensifying because of EPA emissions compliance burdens. Third-party logistics providers show highest price sensitivity; integrated automation specialists show lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate steel rack procurement, with fabricators holding 45-60 days of tubular inventory to hedge coil price volatility. Raw material supply concentrates in China, Germany, and the United States as primary steel and aluminum production hubs. Fabrication draws from welded tubular steel, extruded aluminum profiles, and powder-coat chemistries. Single-source vulnerability sits with specialized REACH-compliant coating formulations from German chemical suppliers. Distribution runs through distributor networks for static rack volumes and direct systems-integrator channels for mobile automation deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaging rack demand is inflecting on robotics-rack convergence, with automated material handling integration rewriting specification capture rules across Asia-Pacific distribution hubs. This technological disruption compresses traditional procurement cycles and elevates capital requirements for competitive participation.
For Market Incumbents: Secure coating-fabrication integration to defend margin position against REACH compliance cost escalation. Anchor automated rack-robotics specification capture through partnerships with warehouse management software providers. Capacity addition in India cold-chain corridors counters displacement risk from aluminum substitution in freight-sensitive electronics applications.
For New Entrants and Emerging Players: Anchor in underpenetrated Indian pharmaceutical cold-storage infrastructure where BIS certification gaps create qualified-supplier shortages. Target corrosion-resistant aluminum rack deployments for fresh food distribution networks in Maharashtra and Gujarat. Pursue direct engagement with third-party logistics providers divesting captive warehouse assets as primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated rack-robotics installations. Five-to-ten-year viability favors mid-cap metal fabricators with captive coating operations and established CE marking pathways. Acquisition target archetype: European modular rack specialists with pharmaceutical cold-storage certification and Ruhr industrial belt production footprint. Signal to watch: OSHA enforcement intensity on load-rating documentation mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Operations | REACH compliance consolidation captures margin from fragmented job shops across European pharmaceutical corridors. |
| Robotics-Rack Convergence Partnership | Daifuku and Mecalux installations demonstrate specification lock-in at Asia-Pacific automated fulfillment hubs. |
| India Cold-Chain Capacity Expansion | Maharashtra and Gujarat buildouts address space-constrained urban pharmaceutical distribution infrastructure gaps. |
| Aluminum Profile Extrusion Investment | Yangtze River Delta electronics manufacturers accelerate lightweight system adoption for high-SKU variability storage. |
| CE Marking Certification Acceleration | Ruhr industrial belt pharmaceutical rack producers shorten procurement cycles for European cold-storage deployments. |
Study Parameters
A spread of perspectives from warehouse automation engineers, third-party logistics procurement directors, pharmaceutical cold-storage facility managers, steel and aluminum mill sales executives, and coating formulation specialists converged on the working assumptions. Primary interviews combined with secondary validation from customs trade data, SEC manufacturing filings, EU ETS emissions disclosures, and BIS structural safety notifications. Bottom-up installation tracking and top-down materials flow analysis provided triangulation across volume estimates.
Segmentation dimensions modeled include product type, material composition, application vertical, and end-user industry across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment velocity indices and cold-chain infrastructure investment pipelines. Industry-specific forecast inputs encompass steel price volatility bands and REACH substance restriction implementation timelines.
Material uncertainties — carbon-border adjustment tariff schedules, OSHA enforcement intensity escalations, and dual carbon goal acceleration under MEE frameworks — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory implementation pacing and buyer substitution elasticity between steel and aluminum systems. Revision becomes warranted when carbon-border adjustment rates or EPA industrial emissions thresholds cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Bottle-Capping Equipment Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Packer Market
Packaging Equipment
Container Washing System Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Bag Re-Sealer Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Gas-Flushing Band Sealing Systems Market