
 Loading Spout Market | 2026-2036
Loading Spout Market Size, Share, and Industry Trends Forecast 2026-2036
Loading Spout Market Outlook
Direct-to-mill distribution is narrowing as original equipment manufacturers consolidate aftermarket service networks. Polimak leverages vertical integration across its Turkish production base to control component costs. Salina Vortex Corporation sustains dominance in North American grain handling through specialized valve-and-spout integration. WAMGROUP S.p.A. anchors European market presence with dense distributor coverage across Italian and German industrial corridors.
A loading spout is a telescopic or fixed conveying apparatus engineered to transfer dry bulk solids from storage silos or conveyors into trucks, railcars, or vessels while containing fugitive dust through integrated aspiration systems. Typical configurations employ carbon steel or stainless steel construction with wear-resistant polymer cones rated for abrasive aggregates, cement, or grain flows exceeding 500 tons per hour. Telescopic spouts lead product type demand due to their adaptability across varying vehicle heights and vessel hatch configurations. Dust control spouts represent the fastest-growing product category as EPA and MSHA enforcement intensifies around respirable crystalline silica and combustible dust hazards. Mining application demand concentrates margin pools where equipment must withstand continuous abrasive service and extreme temperature cycling.
OSHA enforces permissible exposure limits for respirable dust that directly mandate enclosed loading systems in mineral processing and grain handling facilities. MSHA ventilation regulations for underground and surface mining operations require dust suppression at material transfer points, creating specification pull-through for certified loading spout assemblies. EPA National Emission Standards for Hazardous Air Pollutants further constrain open loading practices at chemical manufacturing and cement terminals. Stakeholders must monitor regulatory harmonization between federal dust standards and emerging state-level silica rules to anticipate compliance-driven replacement cycles and specification upgrades.
Market Dynamics
Telescopic spout manufacturers face mounting specification pressure as EPA and MSHA dust enforcement tightens permissible emission thresholds at mineral transfer points. Equipment replacement cycles compress where older open-loading systems cannot retrofit to meet enclosed aspiration mandates.
Growth Catalysts
- MSHA ventilation standards:Underground and surface mining operations must suppress dust at material transfer points, pulling certified loading spout assemblies into specification at Appalachian coal terminals and Great Plains grain elevators.
- Abrasive wear technologies:Polymer cone liners rated for cement and aggregate flows exceeding 500 tons per hour extend service intervals in continuous-duty mining applications.
- Grain elevator modernization:Dust control spout demand concentrates in the United States where aging terminal infrastructure requires enclosed loading systems to meet OSHA respirable dust limits.
Market Restraints
- Stainless steel input volatility:Spout fabrication relies on austenitic grades vulnerable to nickel and chromium price swings, compressing margin predictability for carbon-steel-alternative producers.
- Component supply concentration:Wear-resistant polymer cone manufacturing clusters in German and Italian industrial corridors, exposing North American assemblers to transatlantic logistics friction.
- Fixed spout substitution:Simpler fixed-length configurations displace telescopic units in standardized-height railcar loading where vessel hatch variability is minimal.
Strategic Opportunities
- State-level silica rule harmonization:Emerging sub-federal standards beyond federal OSHA limits create compliance-driven replacement windows for certified enclosed loading systems.
- Chemical manufacturing terminals:EPA National Emission Standards for Hazardous Air Pollutants constrain open loading practices, opening specification pull-through for aspiration-integrated spouts.
- Sensor-integrated spouts:Convergence of load-cell weighing and dust-monitoring telemetry enables real-time emission compliance verification during vessel filling operations.
Industry Challenges
- Welding certification bottlenecks:Pressure vessel and structural steel welding qualifications for abrasive-service spout fabrication extend production lead times.
- Legacy aspiration retrofit complexity:Integrating modern dust collection manifolds with existing silo discharge chutes requires custom engineering that delays project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loading Spout Market |
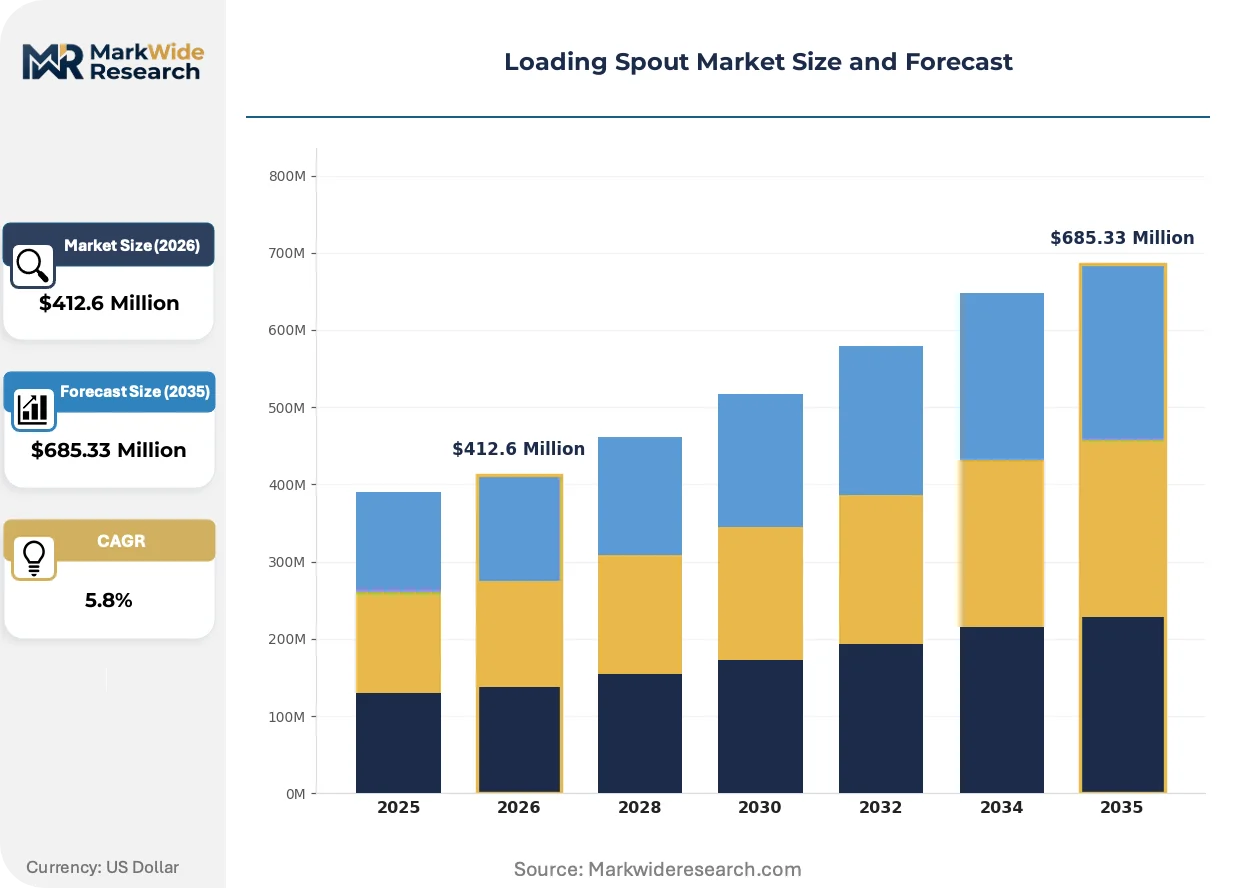
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telescopic Spouts, Fixed Spouts, Flexible Spouts, Dust Control Spouts Application: Agricultural, Food Processing, Chemical Manufacturing, Mining Material: Stainless Steel, Carbon Steel, Polypropylene, Aluminum End User: Agriculture, Food & Beverage, Pharmaceuticals, Construction |
| Companies Covered | Polimak, Salina Vortex Corporation, DCL, Inc., PEBCO, WAMGROUP S.p.A., Beumer Group, Midwest International, HENNLICH s.r.o., Erhard Muhr GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loading Spout Market Strategic Shifts
Loading spout engineering is pivoting toward intelligent material containment as regulatory enforcement hardens around respirable crystalline silica and combustible dust. Fabricators are embedding telemetry and adaptive sealing into core product architectures.
Carbon-fiber-reinforced polymer cone assemblies are hybridizing traditional steel telescopic spout construction. Mining operators in the Powder River Basin are specifying these hybrid configurations to reduce weight-induced boom stress while maintaining abrasion resistance. The technology is hybridizing competitive positioning between European steel specialists and advanced composites suppliers.
EPA National Emission Standards for Hazardous Air Pollutants are tightening enforcement at chemical manufacturing and cement terminals. The regulation mandates enclosed loading systems with verified aspiration capture efficiency, disqualifying legacy open-chute configurations. Chemical terminal operators in the Gulf Coast corridor are accelerating specification reviews to preempt compliance deadlines.
Terminal operators are unbundling after-sales service from original equipment procurement. Grain elevator cooperatives in the Great Plains are contracting third-party maintenance networks for spout inspection and cone replacement, bypassing manufacturer service agreements. This purchasing behavior is most visible in the United States where independent service technician pools have developed around agricultural bulk handling infrastructure.
Loading Spout Market Segmentation
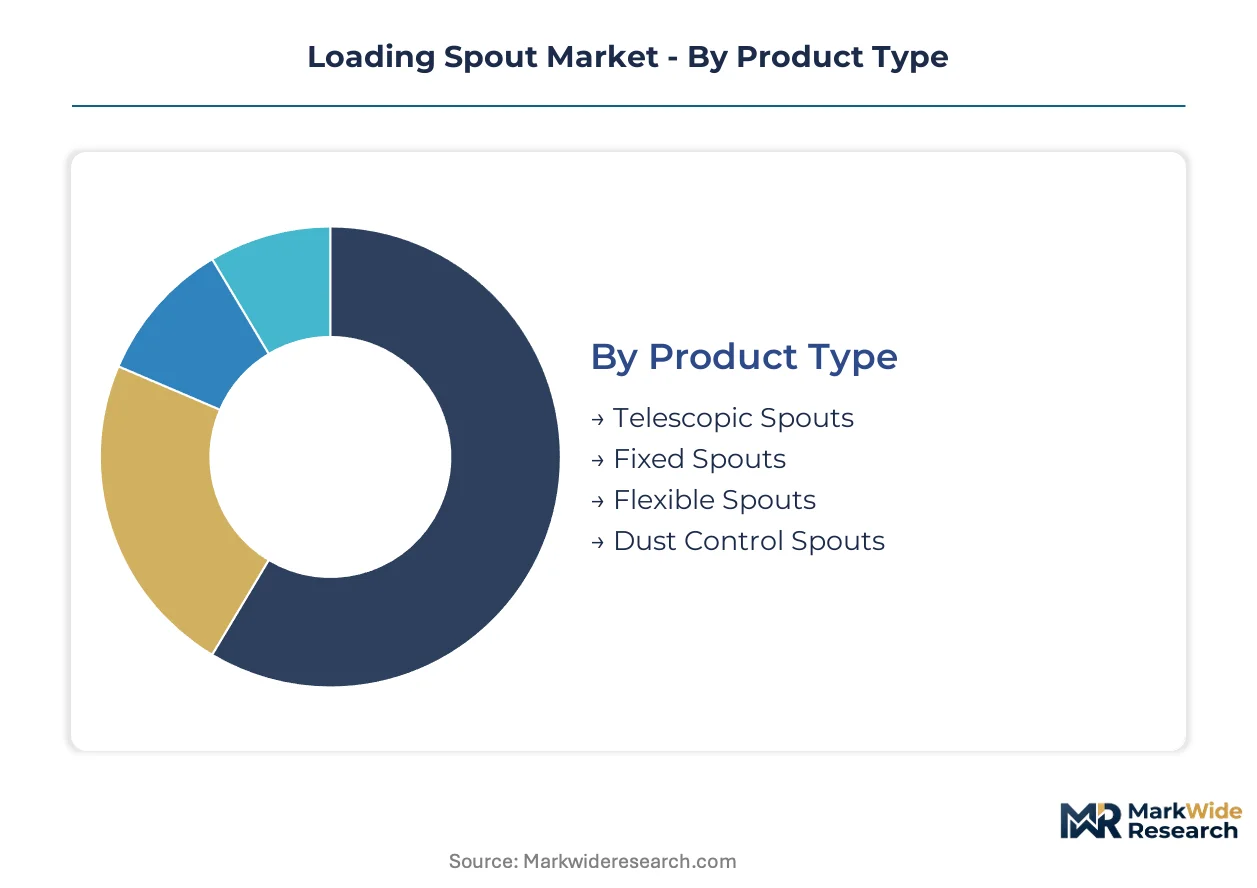
Loading spout procurement patterns diverge sharply across product architectures and end-use environments. Replacement cycles stretch to fifteen years in fixed installations but compress below five years where abrasive mining duty accelerates wear. Specification requirements splinter between grain elevators demanding gentle handling and chemical terminals requiring sealed containment.
Product Type:
Telescopic spouts command the shortest replacement cycles where continuous extension-retraction mechanisms wear under heavy aggregate flows. Fixed spouts endure longest where loading geometry remains constant.
- Telescopic Spouts:Multi-stage steel or aluminum sleeves with internal polymer guide bushings adapt to variable vehicle heights and vessel hatch positions. Mining operators in the Powder River Basin specify these for coal loading where railcar roof heights vary by car type and loading must proceed through sequential hatches without repositioning the source conveyor.
- Dust Control Spouts:Enclosed telescopic or fixed configurations integrate aspiration manifolds and flexible skirt seals to capture fugitive dust at the material discharge point. EPA enforcement at cement terminals and MSHA ventilation mandates at surface coal operations are concentrating specification pull-through for these systems in the United States.
- Fixed Spouts:Rigid steel chutes of predetermined length serve standardized-height railcar loading where vessel geometry is uniform.
- Flexible Spouts:Fabric-reinforced polymer sleeves with wire helix reinforcement accommodate misalignment between silo discharge and vehicle inlet.
Telescopic spouts dominate installed base. Dust control spouts are where expansion concentrates.
Application:
Cost tiers stratify sharply across these segments, with mining applications absorbing premium abrasion-resistant specifications and agricultural buyers optimizing for capital efficiency.
- Mining:Continuous abrasive service with quartz-bearing aggregates and extreme temperature cycling demands polymer cone liners rated for flows exceeding 500 tons per hour. Appalachian coal terminals and Great Plains frac sand operations sustain replacement demand where MSHA dust enforcement mandates equipment upgrades.
- Chemical Manufacturing:EPA National Emission Standards for Hazardous Air Pollutants constrain open loading of hazardous powders, pulling specification toward enclosed aspiration-integrated spouts. Gulf Coast petrochemical corridor terminals are accelerating procurement to preempt compliance deadlines.
- Agricultural:Grain elevators and fertilizer terminals prioritize gentle handling to prevent kernel damage and dust generation during high-volume seasonal operations.
- Food Processing:Sanitary stainless steel construction with quick-disassembly features supports allergen control and washdown protocols in flour milling and sugar handling.
Mining commands the highest per-unit pricing. Chemical manufacturing is climbing the fastest as regulatory deadlines approach.
Material:
Supply concentration for specialized alloys and engineered polymers creates procurement risk that shapes material selection tradeoffs.
- Carbon Steel:Austenitic grades with wear-resistant surface treatments dominate standard-duty applications where cost sensitivity prevails over corrosion resistance.
- Stainless Steel:304 and 316 grades serve food processing and chemical applications requiring corrosion resistance and sanitary cleanability.
- Polypropylene:Glass-filled and UHMW variants form cone liners and wear components where abrasion resistance must combine with material non-reactivity.
- Aluminum:Extruded and cast alloys reduce boom stress in telescopic configurations where weight limits constrain equipment sizing.
Carbon steel dominates installed base. Aluminum and polymer composites are gaining share fastest in weight-critical mining specifications.
End User:
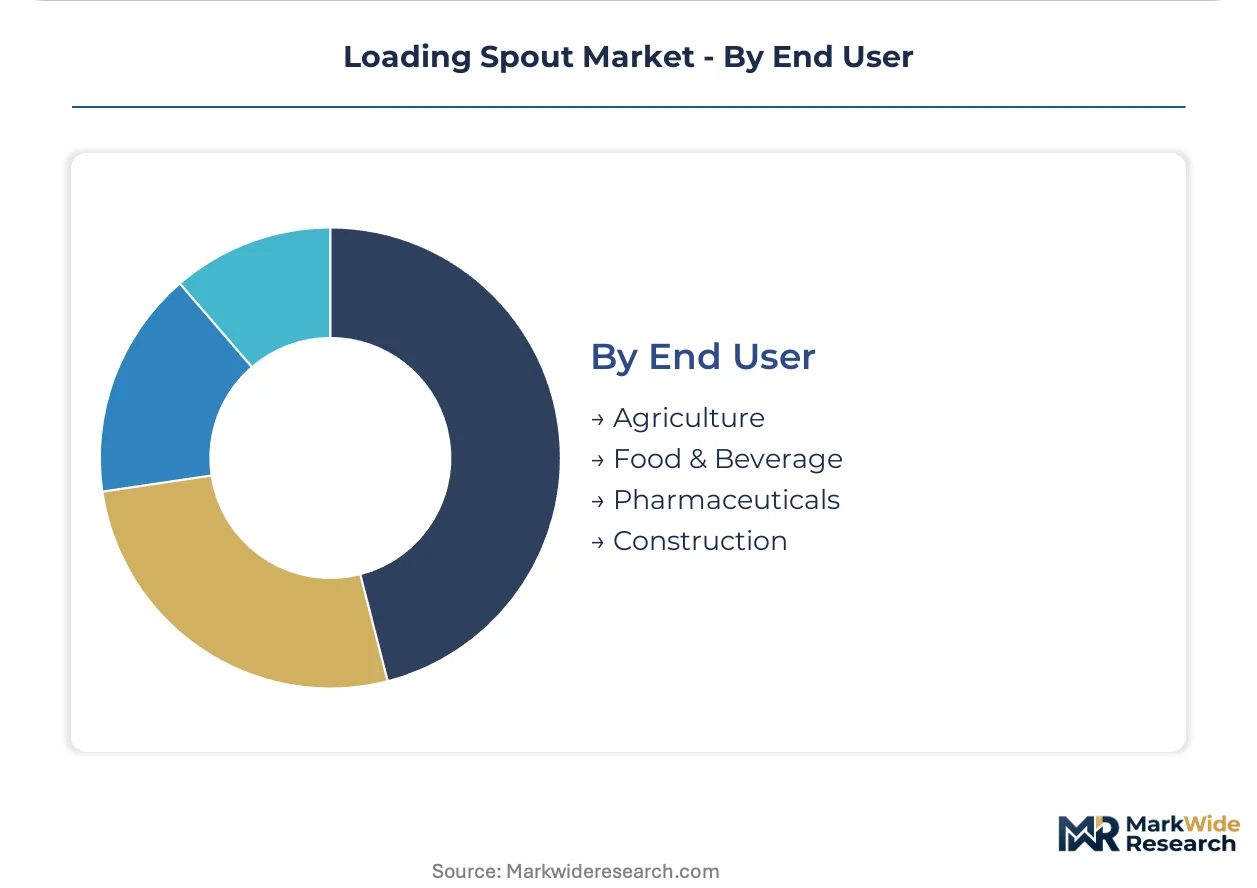
Customer procurement maturity varies dramatically, with agricultural cooperatives consolidating purchasing and pharmaceutical buyers demanding validation documentation.
- Agriculture:Grain elevator cooperatives in the Great Plains are unbundling after-sales service from original equipment procurement, contracting independent maintenance networks for spout inspection and cone replacement.
- Construction:Ready-mix concrete and asphalt aggregate terminals require rapid loading cycles where equipment downtime directly impacts batch plant throughput.
- Food & Beverage:Flour milling and sugar handling operations balance dust containment against sanitary design requirements.
- Pharmaceuticals:Active pharmaceutical ingredient and excipient handling demands validated containment systems with documented aspiration capture efficiency.
Agriculture dominates installed base. Pharmaceuticals is where specification premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Powder River Basin rail corridor underwrites North American bulk material handling capacity, moving coal and frac sand through unit trains that demand rapid, dust-contained loading cycles. Appalachian coal terminals and Great Plains grain elevators anchor replacement demand for enclosed aspiration systems.
United States
Appalachian coal terminals and Great Plains grain elevators sustain equipment replacement cycles where MSHA ventilation standards mandate dust suppression at material transfer points. OSHA enforces permissible exposure limits for respirable crystalline silica that directly specification-pull enclosed loading systems. The Powder River Basin coal loading complex in Wyoming deploys telescopic spouts rated for continuous abrasive service exceeding 500 tons per hour.
Germany
Ruhr industrial corridor cement terminals and Rhine River bulk handling facilities drive specification demand for EPA-equivalent emission containment systems. REACH chemical registration requirements constrain open loading of hazardous powders, pulling aspiration-integrated spouts into procurement cycles. The Port of Hamburg bulk terminal cluster is retrofitting fixed spout installations with telescopic dust control configurations to meet tightening EU air quality directives.
China
Yangtze River Delta coal terminals and northern grain handling corridors sustain domestic equipment demand as MEE air quality standards tighten particulate emission thresholds. GB standards for bulk material handling equipment mandate dust containment at transfer points, accelerating replacement of legacy open-chute systems. The Tianjin Port bulk handling zone is specifying carbon-fiber-reinforced polymer cone assemblies to reduce boom stress in high-volume coal loading operations.
Australia
Pilbara iron ore export terminals and Queensland coal loading facilities demand abrasion-resistant polymer cone liners rated for quartz-bearing aggregate flows. State-level mining safety regulators enforce dust exposure limits that specification-pull certified enclosed loading systems at Port Hedland and Hay Point bulk export terminals. The Hunter Valley coal rail corridor is upgrading telescopic spout fleets to meet tightening respirable dust monitoring requirements.
Brazil
Santos Port grain terminals and Minas Gerais iron ore rail loading facilities drive demand for dust-contained material transfer equipment. ANVISA industrial hygiene guidelines and state environmental agency enforcement constrain open loading practices at agricultural export terminals. The Paranaguá bulk grain terminal complex is procuring enclosed aspiration systems to preempt tightening federal particulate emission standards.
Loading Spout Market Competitive Environment
On the supply side, the industry is structured around three tiers: integrated European industrial conglomerates with captive component production, North American specialists focused on grain and mining applications, and regional fabricators serving price-sensitive emerging markets. Strategic archetypes include aspiration technology specialists, abrasion-resistant materials innovators, and vertical integrators controlling polymer cone manufacturing. Dominant competitive moves span geographic expansion through distributor network density and portfolio diversification into sensor-integrated smart spout systems.
Among European-based fabricators, WAMGROUP S.p.A. and Erhard Muhr GmbH occupy positions within the integrated industrial tier, exemplifying supply chain control through in-house production of core wear components. Polimak represents the regional specialist archetype, leveraging Turkish manufacturing proximity to serve Middle Eastern and Central Asian bulk handling markets. Salina Vortex Corporation anchors the North American specialist segment, with its corporate name indicating Kansas-based concentration in agricultural material handling applications.
| Leading Market Players |
|---|
| Polimak |
| Salina Vortex Corporation |
| DCL, Inc. |
| PEBCO |
| WAMGROUP S.p.A. |
| Beumer Group |
| Midwest International |
| HENNLICH s.r.o. |
| Erhard Muhr GmbH |
| Others |
Value Chain & Pricing Dynamics
Transatlantic container freight corridors linking German and Italian polymer cone manufacturing hubs to North American assembly plants transmit cost volatility directly into downstream price differentiation. Buyers face divergent landed costs depending on sourcing geography, while suppliers leverage captive component production to defend margin structures against input price swings.
Pricing Analysis
Volume-discount tiering structures separate mining operators procuring certified MSHA-compliant assemblies from agricultural cooperatives optimizing for capital efficiency. Pricing stratifies across premium abrasion-resistant specifications, standard carbon-steel configurations, and economy fixed-spout alternatives. Cost compression in mid-tier stainless steel variants is intensifying because nickel and chromium price volatility compresses margin predictability. Grain elevator cooperatives exhibit highest price sensitivity due to seasonal cash flow constraints, while chemical terminal operators absorb premium pricing to secure EPA-compliant aspiration integration.
Supply Chain Analysis
Export-control regimes limiting advanced composite technologies constrain carbon-fiber-reinforced polymer cone flows from European specialists to certain end-markets. Manufacturing concentrates in Germany, Italy, and Turkey, with raw material dependencies spanning austenitic stainless steel grades, glass-filled polypropylene compounds, and wear-resistant UHMW polymers. Single-source vulnerability clusters around German-engineered polymer liner production. Distribution runs through OEM-direct channels for large mining contracts and independent distributor networks serving agricultural replacement parts demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated grain elevator cooperatives unbundling after-sales service from equipment procurement, fragmenting traditional manufacturer-captive revenue streams.
For Market Incumbents: Insulate core margin pools by deepening backward integration into polymer cone manufacturing and securing welding certification capacity ahead of competitor expansion. Salina Vortex Corporation's valve-and-spout integration model demonstrates how captive component supply defends against emerging Turkish cost competitors. Priority investment belongs to sensor-integrated telemetry capabilities that lock in long-term service contracts. For New Entrants and Emerging Players: Establish a beachhead in chemical manufacturing terminals along the Gulf Coast corridor where EPA compliance deadlines concentrate near-term procurement urgency. Sensor-integrated smart spout systems represent the most penetrable white-space, as incumbents lag in converging load-cell weighing with dust-monitoring telemetry. Go-to-market positioning should emphasize real-time emission compliance verification during vessel filling operations. For Investors and Strategic Acquirers: Carve-out targets emerge from European industrial conglomerates seeking to divest non-core bulk handling divisions amid portfolio rationalization pressures. Long-term viability hinges on regulatory enforcement durability rather than commodity cycle exposure. The signal to watch is state-level silica rule harmonization beyond federal OSHA limits, which would accelerate replacement windows and validate premium pricing for certified enclosed systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Cone Manufacturing | Captive supply of wear-resistant liners defends margin structures against transatlantic logistics friction. |
| Sensor-Integrated Smart Spout Development | Convergence of load-cell weighing and dust-monitoring telemetry enables real-time MSHA compliance verification. |
| Independent Service Network Partnership | Third-party maintenance contracts with Great Plains grain cooperatives bypass traditional OEM service agreements. |
| Carbon-Fiber-Reinforced Hybrid Configuration Launch | Powder River Basin mining operators specify reduced boom stress alongside maintained abrasion resistance. |
| Gulf Coast Chemical Terminal Specification Push | EPA National Emission Standards enforcement accelerates procurement cycles at hazardous powder loading facilities. |
Study Parameters
A spread of perspectives from maintenance directors at Appalachian coal terminals, plant engineers at Great Plains grain elevators, OEM procurement teams specifying abrasion-resistant assemblies, and aftermarket service heads managing cone replacement cycles converged on the working assumptions. Primary fieldwork combined with secondary validation from MSHA enforcement records, EPA emission compliance databases, SEC filings of listed industrial conglomerates, and customs trade data tracking polymer component flows. Bottom-up equipment replacement modeling and top-down market sizing triangulated volume estimates across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling replacement cycles against installed base aging and regulatory compliance deadlines throughout the forecast period. Segmentation dimensions spanned product architecture, application severity, material specification tier, and end-user procurement maturity. CAGRs were derived from slope analysis of replacement demand curves and regulatory enforcement timelines. Industry-specific inputs included MSHA ventilation standard revision schedules and state-level silica rule emergence patterns.
Stress conditions across nickel and chromium price volatility bands, transatlantic logistics disruption scenarios, and regulatory enforcement intensity levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding equipment life cycles and compliance-driven replacement elasticity. Material shifts in federal-state regulatory harmonization or abrupt stainless alloy supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Laser Coding Equipment Market
Packaging Equipment
Powder Filling Equipment Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Automatic Liquid Filling Market
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Packaging Equipment Market
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Global Pack Conveyors Market