
 Packing Belt Market | 2026-2036
Packing Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Packing Belt Market Analytics
Preventive maintenance subscriptions and software-defined tension monitoring is pivoting how packing belt vendors monetize equipment. Signode Industrial Group leverages its service infrastructure to lock in long-term contracts with beverage bottlers. Teufelberger Holding AG anchors its position through R&D intensity in high-tenacity synthetic cores. Samuel Strapping Systems competes on geographic dominance across North American distribution hubs.
A packing belt is a continuous loop of reinforced material—typically polyurethane, nylon, or rubber composites ranging from 2 mm to 20 mm in thickness—engineered to transmit motion, convey unit loads, or apply strapping force within automated packaging and material handling systems. Its primary purpose is to synchronize product flow, maintain positional accuracy, and withstand repeated flexural stress under rated tensile loads. Flat belts and modular belts lead volume in food processing and parcel sorting, where washdown resistance and repairability command premium positioning. Timing belts represent the fastest-expanding material category as electronics and pharmaceutical cleanrooms demand precise indexing with minimal particulate shedding.
REACH in Europe restricts Substances of Very High Concern in rubber and polyurethane compounds, while FDA food-contact standards govern belt surfaces in U.S. dairy and meat processing. OSHA machine-guarding rules further shape belt enclosure and access-panel specifications in American manufacturing plants. Stakeholders must monitor how evolving per- and polyfluoroalkyl substance restrictions alter coating chemistries and supplier qualification timelines.
Market Dynamics
Preventive maintenance subscriptions and software-defined tension monitoring are compressing traditional equipment sales cycles into recurring revenue streams, forcing vendors to restructure service architectures around uptime guarantees rather than unit shipments.
Growth Catalysts
- E-commerce fulfillment automation:Parcel sorting hubs in Germany, the Netherlands, and Poland are installing polyurethane modular belts at scale to handle peak-season volume surges.
- REACH phthalate restrictions:ECHA mandates on Substances of Very High Concern are accelerating formulation shifts toward bio-based polyurethane alternatives in European food-contact applications.
- Automotive cluster density:Conveyor-intensive powertrain assembly plants in Stuttgart, Wolfsburg, and Munich generate concentrated demand for high-tenacity timing belts with cleanroom-grade particulate control.
Market Restraints
- Petrochemical input volatility:MDI and polyol feedstock prices fluctuate with crude oil benchmarks, squeezing margin predictability for polyurethane belt manufacturers.
- Asian supply concentration:Synthetic fiber cores and specialty rubber compounds depend heavily on Chinese and South Korean petrochemical complexes, creating single-source vulnerability.
- Steel cord substitution ceiling:Heavy-load mining and bulk material applications remain locked into steel-reinforced conveyor systems that resist lightweight polymer displacement.
Strategic Opportunities
- Indian food processing expansion:FSSAI modernization and cold-chain infrastructure investments in Maharashtra and Gujarat create openings for FDA-compliant thermoplastic belts in dairy and poultry handling.
- Pharmaceutical cleanroom indexing:Precision timing belts with antistatic coatings are capturing share in fill-finish lines as batch sizes shrink and serialization requirements tighten.
- Service unbundling:Predictive maintenance platforms using IoT vibration sensors enable vendors to sell subscription-based belt health monitoring separate from hardware.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for phthalate-free polyurethane with equivalent abrasion resistance resides in a thin talent pool concentrated in German and Swiss industrial chemistry programs.
- Legacy system integration friction:Retrofitting software-defined tension monitoring onto existing mechanical drive trains requires custom engineering that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packing Belt Market |
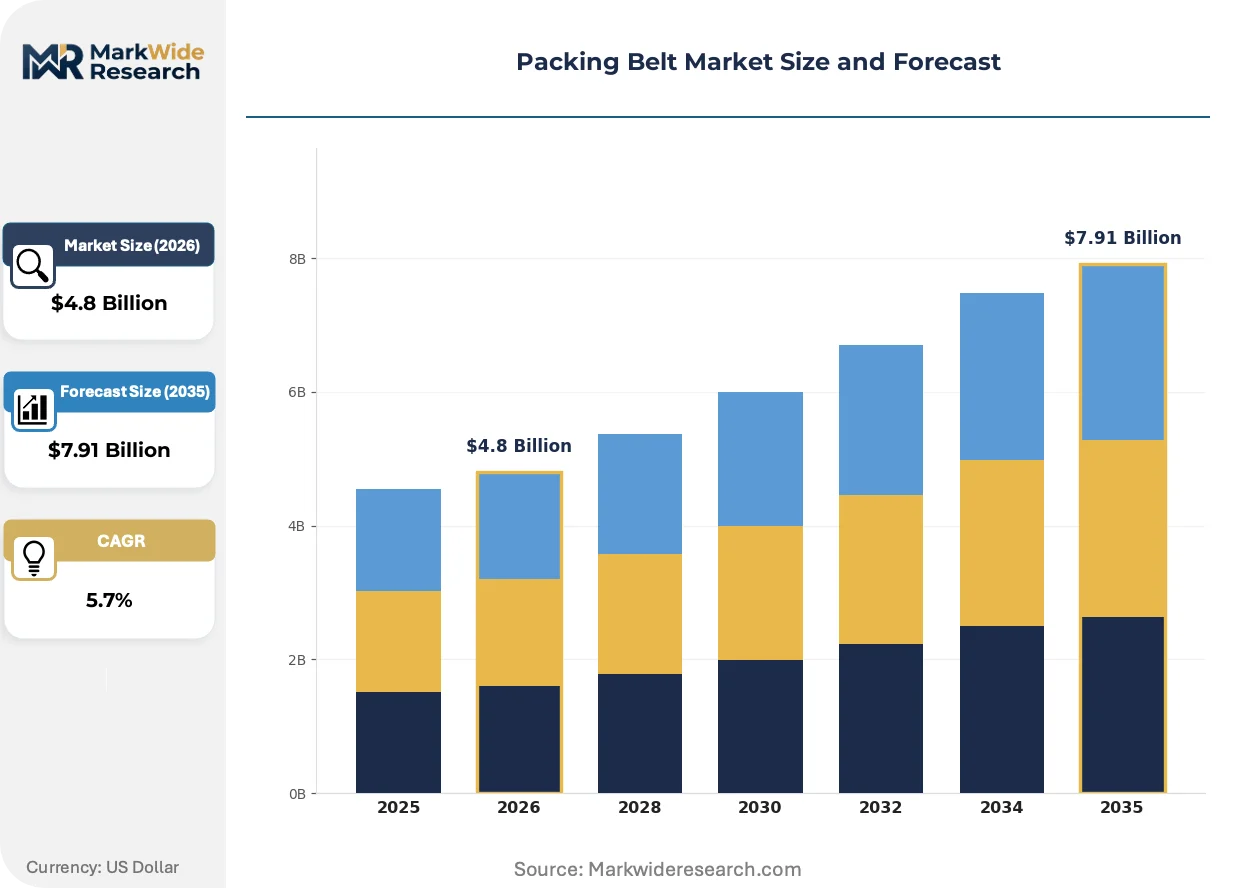
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Belts, Modular Belts, Timing Belts, V-Belts Material: Polyurethane, Nylon, Rubber, Steel End User: Food & Beverage, Electronics, Pharmaceuticals, Textiles Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Signode Industrial Group, Teufelberger Holding AG, Samuel Strapping Systems, FROMM Packaging Systems, Mosca GmbH, Linder GmbH, Forbo Movement Systems, Habasit, Ammeraal Beltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packing Belt Market Evolving Landscape
Material science breakthroughs and regulatory chemistry mandates are rewriting specification standards across food, pharmaceutical, and electronics handling environments.
Embedded fiber-optic strain sensing is decentralizing condition monitoring from centralized control rooms to individual belt segments. Pharmaceutical packagers in Basel and Singapore are piloting these systems to detect micro-fractures before cleanroom contamination events. The shift collapses maintenance response times from scheduled intervals to real-time alerts.
REACH Annex XIV expansion is forcing reformulation of plasticizers in polyurethane surface layers. Belt suppliers serving European dairy processors must now qualify alternatives to traditional phthalate esters without sacrificing flexural fatigue resistance. German automotive suppliers are absorbing the compliance cost premium to maintain CE-marked access.
Buying committees at North American distribution hubs are unbundling after-sales service from initial equipment procurement. Beverage bottlers in Wisconsin and Georgia now negotiate belt supply and predictive maintenance as separate contracts, compressing vendor lock-in periods and accelerating supplier rotation cycles.
Packing Belt Market Segmentation
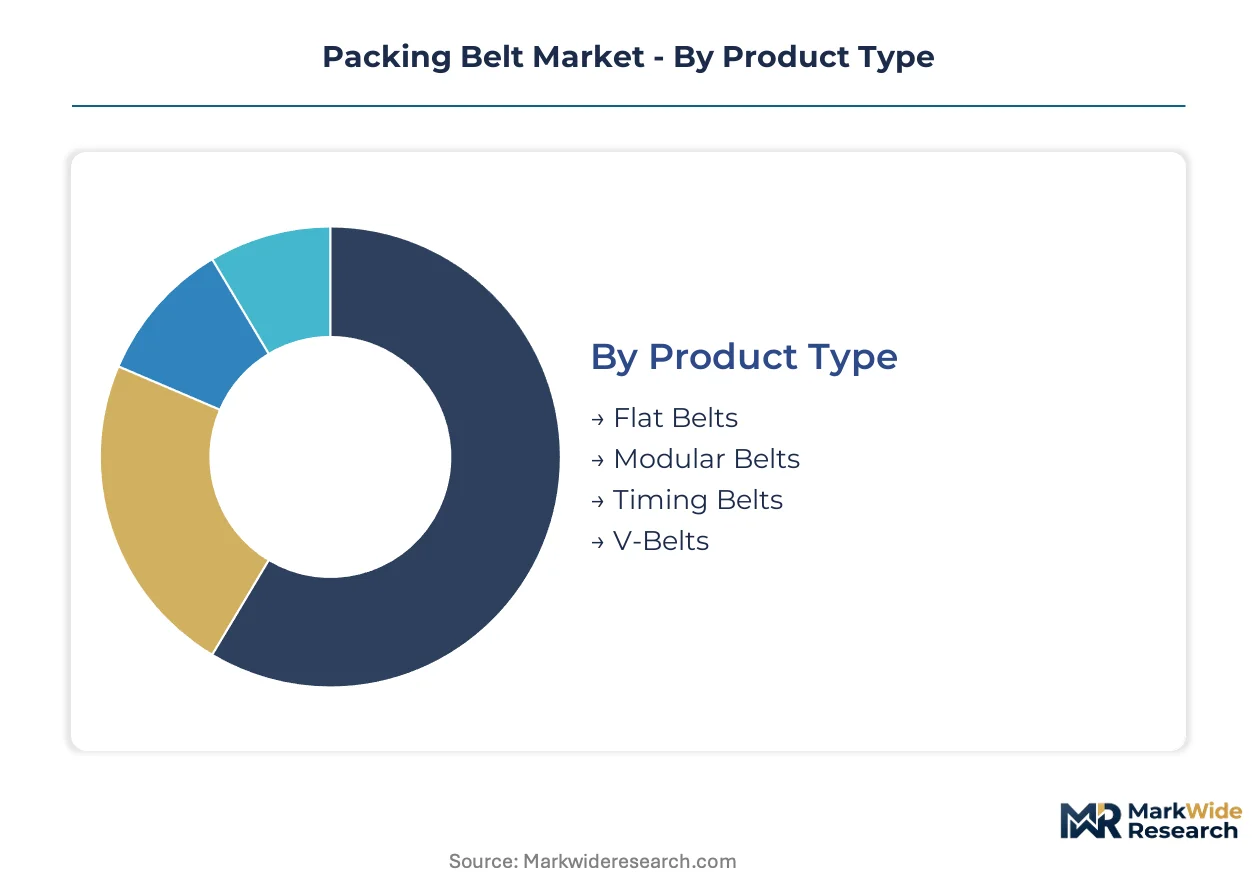
Packing belt procurement splits sharply between high-volume standardized configurations and specification-intensive custom orders. Material chemistry and belt architecture determine compliance pathways, while end-use hygiene standards dictate surface treatment investments.
Product Type:
Volume concentration sits with general-purpose conveying solutions, while premium positioning attaches to precision indexing applications requiring positional repeatability.
- Flat Belts:Continuous webs of rubber or polyurethane composites, typically 2–10 mm thick, engineered for bulk material transport and package accumulation. Demand concentrates in German automotive paint shops and Dutch parcel hubs where washdown compatibility and splice repairability reduce downtime costs.
- Timing Belts:Tooth-profiled reinforced elastomers with steel or glass-fiber tensile members, delivering synchronous motion transfer with sub-millimeter positioning accuracy. Electronics cleanrooms in Singapore and pharmaceutical fill-finish lines in Basel specify antistatic variants as batch sizes shrink and serialization tightens.
- Modular Belts:Interlocking plastic segments enabling localized repair and directional flexibility.
- V-Belts:Trapezoidal cross-section power transmission belts for high-torque industrial drives.
Mature deployment sits with Flat Belts. Newer deployment is concentrated in Timing Belts.
Material:
Cost tiering separates commodity elastomers from engineered polymers commanding formulation premiums.
- Polyurethane:Thermoplastic or thermoset elastomers offering abrasion resistance, flexural fatigue life, and tunable hardness grades. ECHA REACH Annex XIV phthalate restrictions are accelerating bio-based formulation shifts among European dairy processors seeking CE-marked food-contact compliance.
- Nylon:Polyamide cores providing high strength-to-weight ratios and moisture-resistant dimensional stability. Asian textile mills and South Korean electronics assembly lines specify glass-reinforced variants for lightweight tension members.
- Rubber:Natural and synthetic elastomer compounds including SBR, NBR, and EPDM grades.
- Steel:High-tensile cord or solid strip reinforcement for extreme load applications resisting polymer displacement.
Commodity procurement dominates Rubber formulations. Specification intensity clusters with Polyurethane.
End User:
Regulatory stringency varies dramatically across hygiene classifications, with food-contact and pharmaceutical applications imposing surface chemistry and particulate shedding requirements absent in industrial handling.
- Food & Beverage:Belt surfaces must satisfy FDA 21 CFR compliance in U.S. dairy and meat processing, while EU 10/2011 migration limits govern European operations. German breweries and Wisconsin bottlers prioritize modular polyurethane belts with quick-release rod designs enabling tool-free sanitation.
- Pharmaceuticals:Cleanroom-grade timing belts with antistatic and low-particulate coatings for sterile fill-finish and packaging lines. Swiss and Singaporean packagers pilot fiber-optic strain sensing to detect micro-fractures before contamination events.
- Electronics:Precision indexing with electrostatic discharge protection for semiconductor and component assembly.
- Textiles:High-speed conveying with lint-resistant surfaces for yarn and fabric handling.
Established specification regimes anchor Food & Beverage. Steepest expansion trajectory appears in Pharmaceuticals.
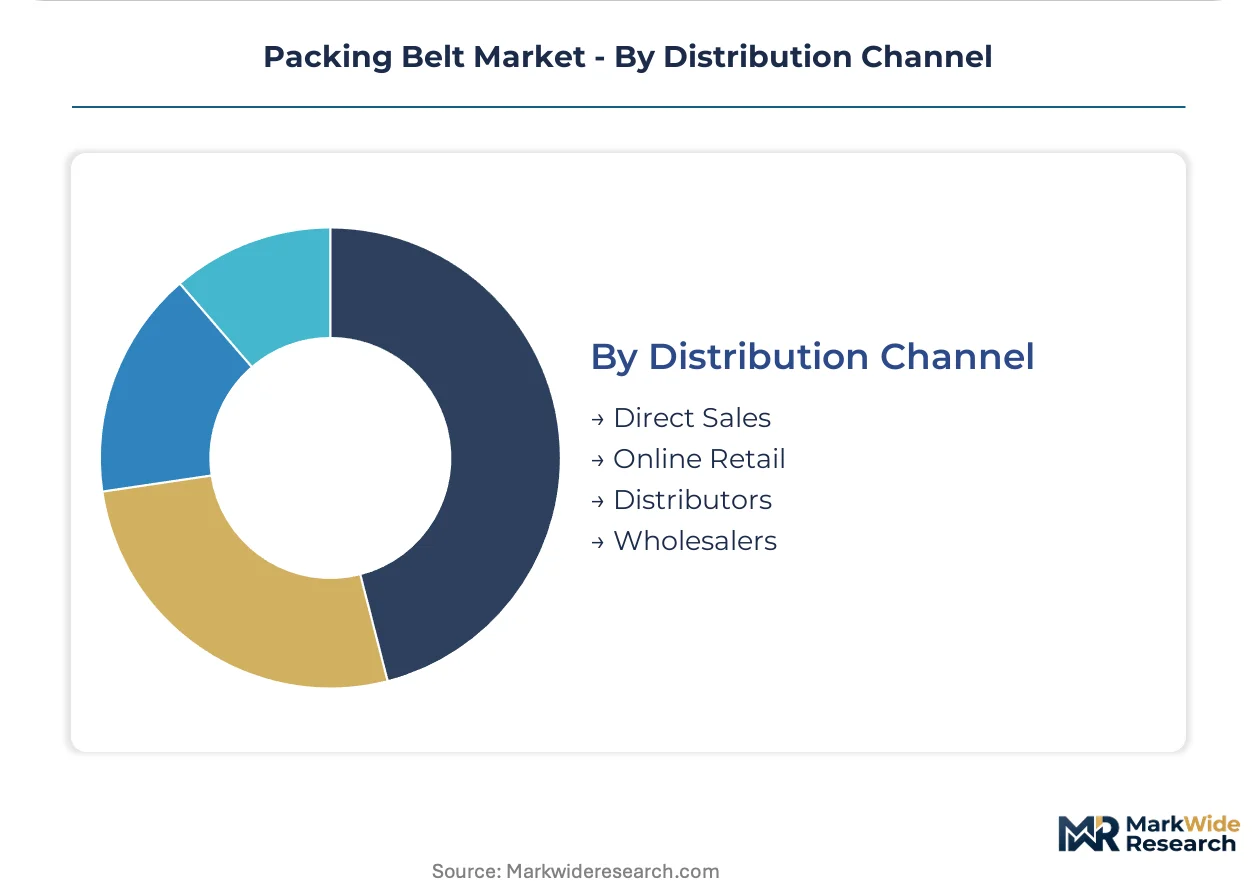
Distribution Channel:
Customer scale and technical support requirements determine route-to-market selection, with large OEMs bypassing intermediaries while mid-tier operators rely on distributor inventory buffers.
- Direct Sales:Manufacturer-to-OEM relationships for engineered-to-order specifications, preventive maintenance subscriptions, and uptime guarantee contracts. Signode Industrial Group leverages this channel to lock beverage bottlers into long-term service agreements.
- Distributors:Stocking intermediaries providing technical consultation, local inventory, and emergency replacement logistics for regional manufacturing clusters.
- Online Retail:Standardized dimension catalog sales for maintenance, repair, and operations procurement.
- Wholesalers:Volume aggregation for commodity-grade belt resupply in price-sensitive industrial segments.
Relationship intensity concentrates in Direct Sales. Transactional efficiency drives Online Retail adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors continental demand for precision timing belts serving automotive powertrain assembly, while Wolfsburg and Munich generate parallel pull for cleanroom-grade conveying systems in battery and electronics manufacturing.
Germany
Automotive clusters in Stuttgart, Wolfsburg, and Munich drive concentrated demand for high-tenacity timing belts with cleanroom-grade particulate control. ECHA REACH Annex XIV phthalate restrictions accelerate bio-based polyurethane formulation shifts among food-contact belt suppliers. Bavarian dairy processors and Baden-Württemberg automotive paint shops specify modular polyurethane belts with quick-release rod designs.
United States
FDA 21 CFR compliance requirements govern belt surfaces in Wisconsin dairy and Georgia meat processing operations. OSHA machine-guarding rules shape belt enclosure specifications across manufacturing plants. Beverage bottlers in Wisconsin and Georgia negotiate predictive maintenance contracts separately from hardware procurement.
China
Synthetic fiber cores and specialty rubber compounds concentrate production in coastal petrochemical complexes. MIIT industrial upgrading programs push domestic belt manufacturers toward higher-tenacity synthetic formulations. Yangtze River Delta electronics assemblers specify antistatic timing belts for semiconductor component handling.
India
FSSAI modernization and cold-chain infrastructure investments in Maharashtra and Gujarat create demand for FDA-compliant thermoplastic belts. CDSCO pharmaceutical regulations tighten cleanroom standards for fill-finish operations. Gujarat poultry processors and Maharashtra dairy cooperatives pilot modular belt installations with tool-free sanitation features.
Singapore
Pharmaceutical packagers pilot fiber-optic strain sensing systems to detect micro-fractures before cleanroom contamination events. Precision timing belts with antistatic coatings capture share in fill-finish lines as batch sizes shrink. Biotech manufacturing clusters specify belts meeting both FDA and EMA dual-jurisdiction requirements.
Packing Belt Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered supply positions. The vendor base separates into integrated compounders controlling polyurethane formulation, specialized fabricators focusing on end-use customization, and service-anchored distributors bundling predictive maintenance. Consolidation pressure concentrates among mid-scale European compounders facing feedstock volatility. Dominant competitive moves include preventive maintenance subscription unbundling and geographic expansion into Indian food processing corridors.
Among European-anchored compounders, Teufelberger Holding AG and Forbo Movement Systems represent integrated formulation-to-fabrication archetypes with captive polymer expertise. Signode Industrial Group exemplifies the service-anchored model leveraging preventive maintenance infrastructure to secure long-term beverage bottler contracts. These three occupy distinct competitive vectors—compound integration, geographic density, and service unbundling—rather than direct product overlap.
| Leading Market Players |
|---|
| Signode Industrial Group |
| Teufelberger Holding AG |
| Samuel Strapping Systems |
| FROMM Packaging Systems |
| Mosca GmbH |
| Linder GmbH |
| Forbo Movement Systems |
| Habasit |
| Ammeraal Beltech |
| Others |
Value Network & Pricing Analysis
Embedded fiber-optic strain sensing and predictive maintenance platforms are compressing capital equipment margins into recurring service revenue, simultaneously redistributing pricing power toward vendors with captive field service infrastructure and fragmenting procurement leverage among mid-tier buyers without bundled uptime guarantees.
Pricing Analysis
Uptime-based subscription contracts anchor value capture for leading vendors, with Signode Industrial Group and Teufelberger Holding AG bundling preventive maintenance into multi-year service agreements that command 15-30% lifetime value premiums over transactional belt sales. Price differentiation hinges on REACH-compliant formulation certification and IoT-enabled condition monitoring capability, with German automotive OEMs least price-sensitive due to cleanroom contamination cost exposure while Indian food processors exhibit acute sensitivity to per-meter procurement costs. Cost compression in standard polyurethane flat belts is intensifying as Chinese petrochemical feedstock volatility squeezes compounder margins, forcing mid-tier European suppliers toward unprofitable spot-market participation.
Supply Chain Analysis
Single-source vulnerability sits with MDI and specialty polyol feedstock production concentrated in Chinese and South Korean petrochemical complexes, where Yangtze River Delta and Ulsan manufacturing clusters control 60-70% of global polyurethane precursor output. Raw material dependencies extend to glass-fiber tensile members from German and Belgian roving producers, plus antistatic coating chemistries tethered to Swiss and Japanese specialty chemical houses. Tariff exposure on Chinese-sourced synthetic fiber cores creates margin volatility for European compounders lacking backward integration into polymer production. Distribution runs through direct OEM relationships for engineered specifications and regional distributor networks for maintenance-driven replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer chemist scarcity across German and Swiss industrial chemistry programs constrains phthalate-free formulation capacity, propping premium pricing for REACH-compliant suppliers while locking mid-tier competitors into commodity positioning.
For Market Incumbents: Anticipate accelerated service unbundling by locking beverage bottlers and automotive OEMs into decade-long predictive maintenance contracts before IoT platform commoditization erodes subscription pricing power. Prioritize captive polyurethane compounding capacity in Germany or Switzerland to defend margin position against Asian feedstock volatility and ECHA regulatory escalation. Vertical integration into bio-based polyol R&D represents the critical lever for sustaining CE-marked access as Annex XIV restrictions tighten. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian food processing belts exceeds 40% on a total-cost-of-ownership basis, creating white-space opportunity for FDA-compliant thermoplastic suppliers with localized assembly and FSSAI-authorized distribution partnerships. Target Maharashtra dairy cooperatives and Gujarat poultry processors with modular belt architectures featuring tool-free sanitation as the beachhead application, then expand into CDSCO-regulated pharmaceutical cleanrooms. A technical licensing arrangement with established European compounders offers the fastest route to formulation credibility without capital-intensive R&D buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial conglomerates seeking service-anchored revenue streams and REACH-compliant formulation assets. Long-term viability favors compounders with captive polymer science capabilities and installed base density across German automotive clusters. Watch for inflection in ECHA SVHC list expansion velocity as the signal for regulatory compliance premium sustainability versus commodity margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Subscription Unbundling | Signode Industrial Group leverages service infrastructure to convert transactional belt sales into recurring uptime guarantee contracts with Wisconsin beverage bottlers. |
| Bio-Based Polyurethane Formulation Shift | Teufelberger Holding AG anchors R&D investment in phthalate-free alternatives to maintain CE-marked access under REACH Annex XIV expansion. |
| Indian Food Processing Corridor Expansion | Forbo Movement Systems targets FSSAI modernization in Maharashtra and Gujarat with FDA-compliant modular belt installations featuring quick-release sanitation. |
| Fiber-Optic Strain Sensing Integration | Pharmaceutical packagers in Basel and Singapore pilot embedded monitoring to collapse maintenance response from scheduled intervals to real-time fracture detection. |
| Backward Integration into Polyol Production | European compounders absorb German and Swiss petrochemical assets to reduce MDI feedstock exposure from Chinese and South Korean supply concentration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with maintenance directors at German automotive plants, procurement leads at Wisconsin beverage bottlers, plant engineers at Maharashtra dairy cooperatives, and aftermarket service heads at European distribution hubs. ECHA REACH guidance documents, FDA 21 CFR food-contact standards, and FSSAI modernization circulars provided regulatory boundary conditions. Bottom-up belt shipment estimates by material chemistry and end-use hygiene classification triangulated against top-down petrochemical feedstock demand models.
Granularity-level modeling operated at product type by material by end-use by distribution channel, with timing belt precision indexing applications, polyurethane REACH-compliant formulations, pharmaceutical cleanroom specifications, and direct sales with service bundling each receiving discrete treatment. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating E-commerce fulfillment automation intensity, automotive cluster capacity utilization, and pharmaceutical serialization regulatory phase-in as industry-specific forecast inputs.
Underlying measurement precision varies by segment; timing belt pharmaceutical applications carry tighter precision than commodity flat belt industrial handling due to concentrated buyer visibility and regulatory documentation requirements. Forecasts reflect assumptions on ECHA SVHC list expansion trajectory, crude oil benchmark correlation with MDI pricing, and Indian cold-chain infrastructure investment velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Bag Re-Sealer Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Flow Wrap Packaging Market
Packaging Equipment
Automatic Liquid Filling Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Linear Net Weighing Machines Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
Airless Pumps Market
Packaging Equipment
Single Use Mixer Market
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Diaper Packaging Machines Market