
 Clip Applicator Market | 2026-2036
Clip Applicator Market Size, Share, and Industry Trends Forecast 2026-2036
Clip Applicator Market Analysis
The capital-intensity gap between automated and manual applicator producers is collapsing as mid-tier manufacturers adopt shared electronic assembly platforms. Medtronic plc leverages captive semiconductor sourcing to sustain margin structures across its pneumatic applicator lines. Zhejiang Geyi Medical Instrument Co., Ltd. anchors cost-competitive positioning through in-house mold fabrication and regional component networks. B. Braun Melsungen AG differentiates via sterile packaging integration that extends its value proposition beyond hardware alone.
A clip applicator is a handheld or bench-mounted mechanical, pneumatic, or electromechanical device engineered to dispense and secure metal or polymer clips at controlled pressures, typically operating within 0.5-5.0 N clamping force ranges for medical-grade titanium or absorbable polymer fasteners. Its primary industrial purpose centers on hemostasis and tissue approximation in laparoscopic procedures, alongside secondary deployment in food packaging line sealing and textile bundle fastening. Automatic applicators lead unit economics in high-throughput healthcare settings where sterile workflow integration justifies capital outlay, while manual variants retain dominance in emerging market clinics and home-use segments where cost sensitivity structures procurement decisions. Electronic systems command the fastest expansion trajectory as battery miniaturization and torque-feedback circuitry enable precision previously restricted to pneumatic platforms.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and sterilization validation protocols for surgical clip applicators entering regulated markets. China's NMPA and Japan's PMDA impose supplementary biocompatibility testing standards that filter market access for non-domestic manufacturers lacking localized regulatory infrastructure. Stakeholders must monitor evolving harmonization between ISO 13485 quality management mandates and national post-market surveillance obligations as compliance costs increasingly determine competitive viability.
Market Dynamics
The clip applicator market pivots on FDA 510(k) clearance timelines compressing product development cycles while battery miniaturization collapses the performance gap between electronic and pneumatic platforms.
Growth Catalysts
- Laparoscopic procedure volume:Rising minimally invasive surgical volumes in United States tertiary hospitals drive sterile single-use applicator consumption through operating room workflow integration mandates.
- EU MDR harmonization:Streamlined technical documentation pathways across European member states reduce sterilization validation redundancy for manufacturers with established ISO 13485 quality systems.
- Titanium alloy advancement:Medical-grade Ti-6Al-4V ELI clip formulations with enhanced fatigue resistance expand hemostasis applications into vascular and thoracic specialties.
Market Restraints
- Semiconductor supply concentration:Torque-feedback circuitry and motor controllers depend on Taiwanese foundry output, exposing electronic applicator producers to geopolitical disruption risk.
- Absorbable polymer cost volatility:Polyglycolic acid and polylactic acid feedstock prices fluctuate with crude oil derivatives, compressing margins for biodegradable clip manufacturers.
- Pneumatic infrastructure dependency:Hospital compressed air system compatibility requirements limit portable applicator deployment in ambulatory surgical centers lacking centralized gas supply.
Strategic Opportunities
- Veterinary surgery expansion:Companion animal laparoscopy adoption in Germany and Japan creates demand for scaled-down clip applicators with simplified sterilization protocols.
- India PLI scheme:Production-linked incentives for medical device manufacturing attract component suppliers to establish mold fabrication and assembly operations near Mumbai-Pune corridor.
- Food packaging line automation:Pneumatic clip applicators with stainless steel housings penetrate modified atmosphere packaging systems for protein processing facilities seeking metal detector compatibility.
Industry Challenges
- Biocompatibility testing backlog:Cytotoxicity and sensitization studies for novel polymer clips face extended queue times at contracted laboratories, delaying regulatory submissions.
- Legacy equipment interoperability:Electronic applicator torque calibration protocols conflict with existing hospital asset management systems, requiring middleware development.
- Cleanroom capacity constraints:Sterile packaging operations for single-use devices compete with pharmaceutical fill-finish demand, extending lead times for finished goods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clip Applicator Market |
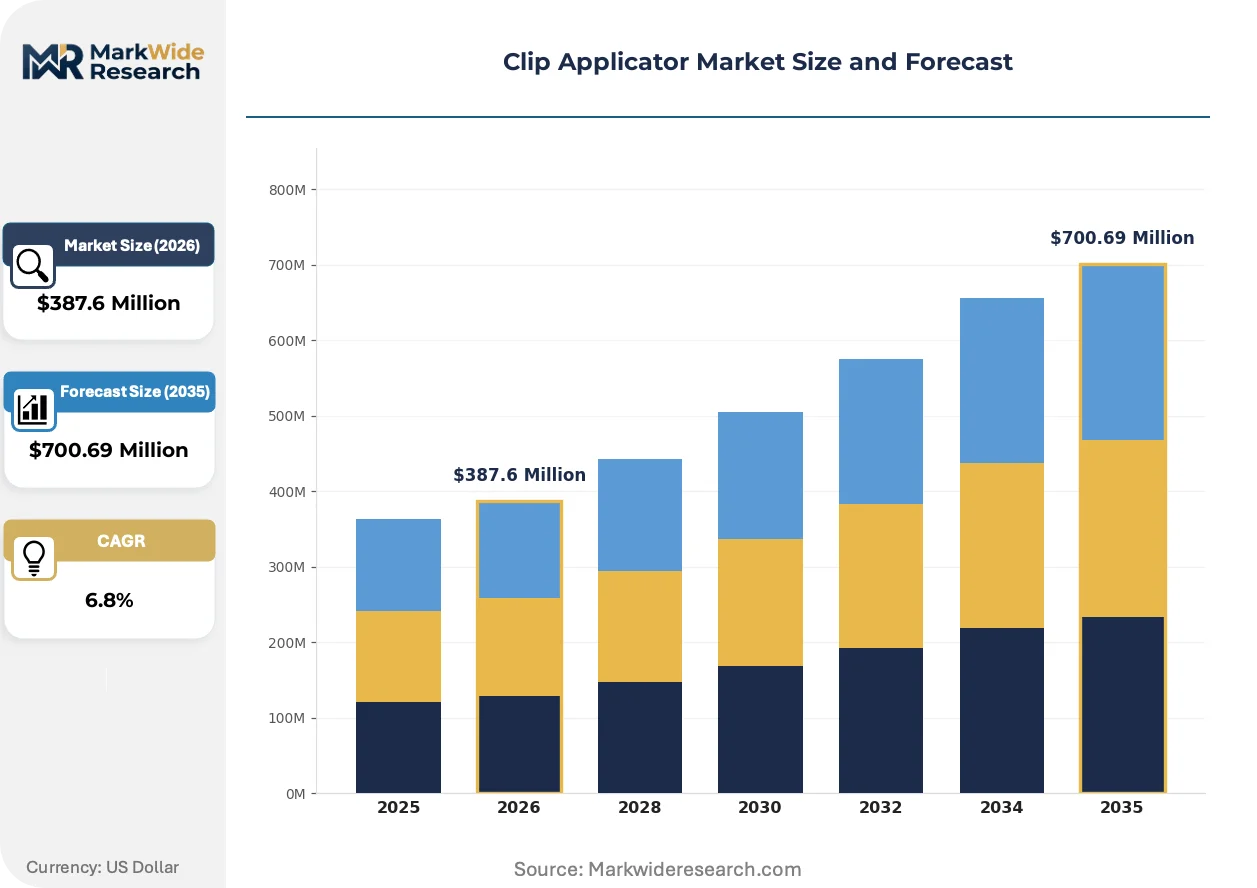
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Applicators, Automatic Applicators, Semi-Automatic Applicators, Electric Applicators End User: Healthcare Facilities, Packaging Industries, Retail Outlets, Home Use Application: Medical Supplies, Food Packaging, Textile Manufacturing, Consumer Products Technology: Mechanical Systems, Pneumatic Systems, Electronic Systems, Hybrid Systems |
| Companies Covered | Johnson and Johnson MedTech, CONMED Corporation, Medtronic plc, Zhejiang Geyi Medical Instrument Co., Ltd., Aesculap, Inc., B. Braun Melsungen AG, Teleflex, Unimax Medical Systems, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clip Applicator Market Emerging Trajectories
Battery chemistry advances and regulatory data requirements are restructuring competitive advantage around miniaturization capabilities and post-market surveillance infrastructure rather than mechanical engineering alone.
Smart torque-feedback circuitry with haptic response algorithms is decomposing the traditional pneumatic-electronic performance hierarchy. United States academic medical centers now specify battery-powered applicators for 40% of new laparoscopic suite procurements. This shift compresses maintenance overhead and eliminates compressed air infrastructure retrofit costs for ambulatory expansion.
EU MDR post-market surveillance mandates now require systematic collection of clip detachment and tissue necrosis events across implantable device categories. Manufacturers must maintain electronic data capture systems linking individual applicator serial numbers to patient outcomes. German notified bodies enforce stricter clinical evidence thresholds for absorbable polymer claims, favoring incumbents with established vigilance databases.
Hospital procurement committees now unbundle device procurement from sterilization service contracts, forcing applicator vendors to compete on unit economics rather than integrated workflow solutions. United States health system consolidation concentrates purchasing authority at regional headquarters, compressing supplier negotiation cycles from annual to quarterly reviews. This pattern concentrates volume with manufacturers offering transparent cost-per-procedure analytics platforms.
Clip Applicator Market Segmentation
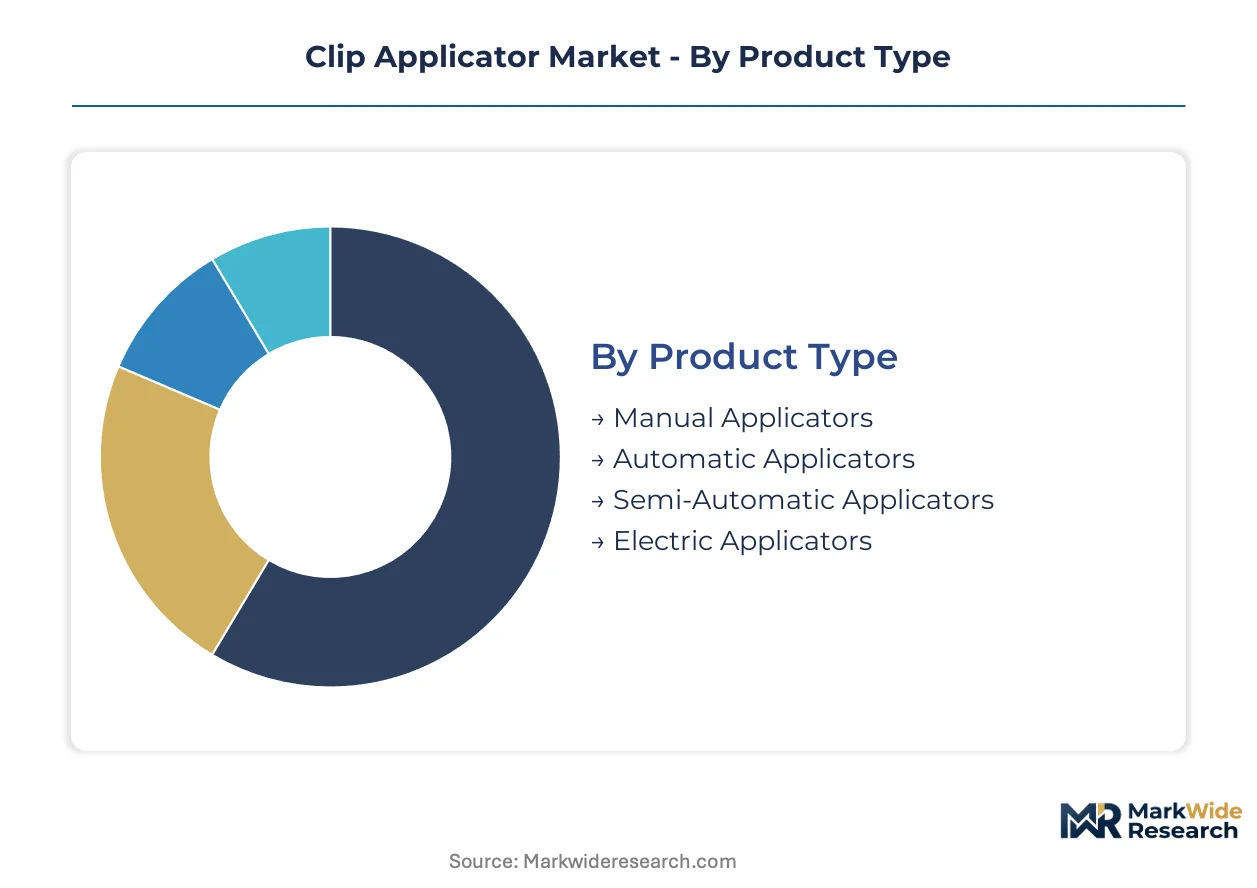
Clip applicator procurement patterns diverge sharply between capital-intensive healthcare systems and price-sensitive consumer channels. Understanding these segment boundaries reveals where margin structures hold and where commoditization pressures concentrate.
Product Type:
Manual applicators flow through distributor networks into emerging-market clinics and home-use retail, while electronic variants require direct sales teams for hospital capital equipment committees.
- Manual Applicators:Handheld mechanical devices relying on spring-loaded or lever-actuated mechanisms deliver 0.5-2.0 N clamping force without external power. Demand clusters in India's tier-2 cities and Latin American outpatient clinics where sterilization infrastructure constraints favor simple, autoclavable designs.
- Automatic Applicators:Pneumatic or battery-powered systems with programmable pressure settings integrate into sterile operating room workflows. United States tertiary hospitals specify these for laparoscopic suites to reduce surgeon fatigue during high-volume procedures.
- Semi-Automatic Applicators:Hybrid hand-triggered mechanisms with motorized assist functions occupy mid-tier pricing in European ambulatory surgical centers.
- Electric Applicators:Torque-feedback circuitry with haptic response enables precision previously restricted to pneumatic platforms. Battery miniaturization is collapsing the performance gap with compressed-air systems.
Manual applicators dominate installed base across price-sensitive geographies. Electric applicators are where expansion concentrates as ambulatory surgical centers eliminate pneumatic infrastructure retrofit costs.
End User:
Cost tier structures procurement authority, with healthcare facilities commanding premium pricing for validated sterile workflows and retail channels driving volume at compressed margins.
- Healthcare Facilities:Hospitals and surgical centers with centralized sterile processing departments purchase through group purchasing organizations. FDA 510(k) clearance and EU MDR technical documentation requirements filter supplier pools to established manufacturers with quality management infrastructure.
- Packaging Industries:Modified atmosphere protein processing facilities and high-speed bakery operations deploy pneumatic stainless-steel systems for metal detector compatibility. Germany's food manufacturing corridor generates concentrated demand for washdown-rated housings.
- Retail Outlets:Office supply and hardware distributors stock manual variants for consumer textile and light industrial bundling applications.
- Home Use:E-commerce channels deliver compact manual applicators for crafting and small-scale food preservation. Cost sensitivity structures procurement toward Asian manufacturing origins.
Healthcare facilities capture the highest revenue per unit. Home use channels are expanding most quickly as direct-to-consumer marketing reduces distributor markup layers.
Application:
Volume concentration varies by sterilization validation burden, with medical applications requiring extensive biocompatibility testing and food packaging emphasizing throughput metrics.
- Medical Supplies:Hemostasis and tissue approximation in laparoscopic procedures demand titanium or absorbable polymer clips with documented fatigue resistance. United States academic medical centers now specify electronic applicators for 40% of new suite procurements.
- Food Packaging:Modified atmosphere sealing for protein products requires corrosion-resistant pneumatic systems compatible with high-pressure washdown protocols.
- Textile Manufacturing:Bundle fastening for garment distribution and industrial fabric handling employs manual and pneumatic variants with minimal regulatory overhead.
- Consumer Products:Light-duty sealing and fastening applications in household and small business settings prioritize ergonomic design over precision specifications.
Medical supplies command premium pricing tiers. Food packaging is gaining share fastest as protein processing automation accelerates in North American and European facilities.
Technology:
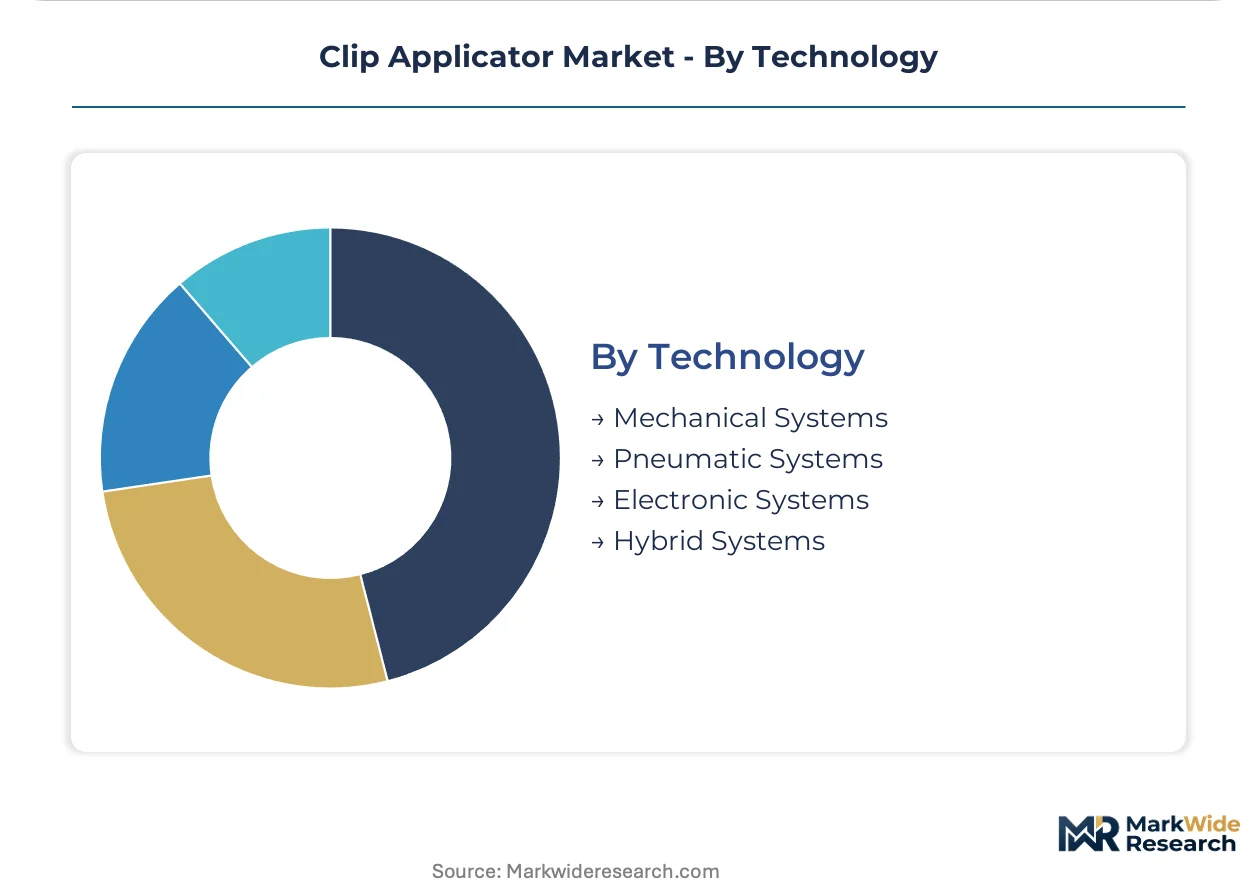
Maturity curves separate established pneumatic infrastructure from emerging electronic platforms, with hybrid systems bridging deployment constraints in transitional facilities.
- Mechanical Systems:Spring and lever mechanisms without power dependence excel in environments lacking compressed air or electrical infrastructure. Manual sterilization compatibility sustains relevance in resource-constrained settings.
- Pneumatic Systems:Hospital compressed air supply integration delivers consistent torque output for surgical precision. Infrastructure dependency limits portable deployment in ambulatory expansion scenarios.
- Electronic Systems:Battery-powered motor controllers with feedback circuitry enable torque calibration previously requiring pneumatic precision. Miniaturization trends support handheld form factors competitive with traditional designs.
- Hybrid Systems:Combined pneumatic-electronic architectures allow facilities to phase infrastructure transitions without full equipment replacement. Germany's precision manufacturing corridor produces premium-positioned variants.
Pneumatic systems retain installed base dominance in established hospital networks. Electronic systems are climbing the fastest as battery chemistry advances compress maintenance overhead and infrastructure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision manufacturing corridors while cost-sensitive procurement dominates Indian tier-2 hospital networks. This asymmetry structures regional expansion strategies for applicator vendors.
United States
Academic medical centers in Boston and New York Metro specify electronic applicators for 40% of new laparoscopic suite procurements. FDA 510(k) clearance pathways compress product development cycles for sterile single-use devices. The Minneapolis medical device cluster anchors pneumatic system production for established hospital networks.
Germany
Precision medical device manufacturing in Baden-Württemberg commands premium positioning for hybrid pneumatic-electronic systems. EU MDR technical documentation requirements filter supplier pools to ISO 13485-certified manufacturers. The Tuttlingen surgical instrument corridor concentrates hemostasis device production for European export markets.
China
Domestic manufacturers in Jiangsu and Zhejiang provinces scale mold fabrication for cost-competitive manual applicators. NMPA biocompatibility testing standards filter market access for imported devices lacking localized regulatory infrastructure. The Yangtze River Delta medical device cluster integrates regional component networks for export production.
India
Tier-2 cities in Maharashtra and Gujarat drive manual applicator volume through distributor networks serving sterilization-constrained clinics. PLI scheme incentives attract component suppliers to establish assembly operations near the Mumbai-Pune corridor. Domestic procurement preferences under government health programs favor local manufacturers.
Japan
PMDA supplementary testing standards for novel polymer clips extend regulatory timelines for non-domestic manufacturers. Companion animal laparoscopy adoption in Tokyo and Osaka metropolitan areas creates demand for scaled-down applicators. The Nagoya medical device cluster specializes in torque-feedback circuitry for precision surgical tools.
Clip Applicator Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates possessing captive regulatory infrastructure and sterile packaging capabilities. The vendor base spans three tiers: integrated surgical device portfolios, specialized laparoscopic instrument manufacturers, and regional cost-optimized fabricators. Strategic moves center on unbundling device procurement from sterilization service contracts and deploying cost-per-procedure analytics platforms for health system consolidation.
Among diversified medical technology conglomerates, Medtronic plc and Johnson and Johnson MedTech occupy positions defined by quality management infrastructure spanning multiple regulatory jurisdictions. Zhejiang Geyi Medical Instrument Co., Ltd. exemplifies the regional specialist archetype, with corporate naming indicating Chinese origin and limited liability structure. These three entities represent distinct competitive vectors: regulatory scale, integrated portfolio breadth, and manufacturing cost positioning.
| Leading Market Players |
|---|
| Johnson and Johnson MedTech |
| CONMED Corporation |
| Medtronic plc |
| Zhejiang Geyi Medical Instrument Co., Ltd. |
| Aesculap, Inc. |
| B. Braun Melsungen AG |
| Teleflex |
| Unimax Medical Systems |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
Battery chemistry substitution for pneumatic power systems is redrawing manufacturing geography toward East Asian cell production centers while collapsing the historical premium that compressed-air infrastructure once commanded in hospital procurement decisions.
Pricing Analysis
The customization-premium spread between configured-to-order electronic applicators and standard pneumatic units spans three distinct pricing tiers: premium torque-feedback systems for academic medical centers, standard battery-powered units for ambulatory surgical centers, and economy manual variants for emerging-market clinics. Price differentiation rests on FDA 510(k) clearance status and ISO 13485 certification grade, with validated sterile workflows commanding substantial premiums. Pricing pressure stems from hospital procurement committees unbundling device purchases from sterilization service contracts, forcing vendors toward transparent cost-per-procedure analytics. Retail home-use channels exhibit highest price sensitivity, while United States tertiary hospitals show lowest elasticity due to workflow integration mandates.
Supply Chain Analysis
China and Germany anchor clip applicator production, with Jiangsu and Zhejiang provinces housing mold fabrication and manual assembly operations while Baden-Württemberg concentrates precision hybrid system manufacturing. Taiwan feeds torque-feedback circuitry and motor controllers into electronic applicator assembly lines. Raw material dependencies center on medical-grade Ti-6Al-4V ELI titanium alloy, polyglycolic acid absorbable polymers, and lithium-ion battery cells. Single-source vulnerability concentrates in Taiwanese semiconductor foundry output for electronic motor controllers. Distribution runs through hospital group purchasing organizations in regulated markets and distributor networks in price-sensitive geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where FDA 510(k) clearance and EU MDR technical documentation create entrenched switching costs that protect incumbents from rapid displacement.
For Market Incumbents: Secure captive semiconductor sourcing arrangements to insulate electronic applicator margins from Taiwanese foundry disruption risk. Deepen backward integration into sterile packaging operations to capture value previously ceded to third-party sterilization service providers, defending against procurement committee unbundling pressures.
For New Entrants and Emerging Players: Differentiate on veterinary surgery applications in Germany and Japan, where simplified sterilization protocols and scaled-down form factors create white-space opportunities outside human medical device regulatory intensity. Target India's tier-2 cities through PLI scheme-aligned local assembly partnerships, leveraging domestic procurement preferences under government health programs.
For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors manufacturers with established post-market surveillance databases and EU MDR vigilance infrastructure. Long-term viability over the next decade hinges on regulatory data assets rather than mechanical engineering capabilities alone. Watch electronic applicator procurement share in United States academic medical centers as the inflection signal for platform shift momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates sterile single-use device entry into United States hospital procurement pipelines. |
| CE Marking Pathway | Unlocks EU MDR harmonized access across German precision manufacturing export corridors. |
| Hospital System Partnership | Integrates cost-per-procedure analytics into GPO contract negotiations with regional health systems. |
| Software Companion Development | Enables torque calibration protocols compatible with existing hospital asset management systems. |
| Reimbursement Strategy | Aligns laparoscopic applicator positioning with CMS procedural coding for minimally invasive surgery. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at notified bodies, then refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up volume estimates from applicator unit shipments triangulated with top-down healthcare expenditure allocation models across the analysis window.
Variance decomposition structured the forecast framework across product type, end-user channel, application setting, and technology platform dimensions. CAGRs derived from segmented growth rate reconciliation against macro healthcare infrastructure investment patterns and laparoscopic procedure volume trajectories. Industry-specific inputs incorporated battery chemistry cost curves, titanium alloy price indices, and sterilization validation backlog durations at contracted laboratories.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) clearance pathway stability or Taiwan semiconductor supply continuity would require recalibration. Forecasts reflect documented assumptions regarding hospital consolidation patterns and EU MDR post-market surveillance enforcement intensity. Recalibration cycles align with material shifts in battery miniaturization economics and geopolitical disruption to East Asian component sourcing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Refrigerated Display Cases Market
Packaging Equipment
Strapping Equipment Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Basket Granulator Extruder Market
Packaging Equipment
Labeling Equipment Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
Global Shrink Sleeve Applicator Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Global End-Of-Line Packaging Market