
 Hot Melt Equipment Market | 2026-2036
Hot Melt Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Melt Equipment Market Analysis
Aftermarket service revenue is reconfiguring profit pools across the hot melt equipment landscape. Nordson Corporation leverages its global spare parts logistics network to capture recurring revenue streams. Graco Inc. sustains competitive position through dedicated R&D facilities focused on precision dispensing architectures. ITW Dynatec anchors its presence in high-volume automotive assembly applications with modular platform designs.
Hot melt equipment encompasses industrial machinery engineered to heat thermoplastic adhesives to precise molten states, typically operating between 120°C and 200°C, then pump and dispense them through automated or manual applicators for bonding substrates. Melters and application equipment constitute the core revenue base, while electric heating technology gains traction against steam-based alternatives as manufacturers prioritize energy efficiency and temperature control accuracy. Food packaging and electronics end-user segments exhibit divergent equipment specifications, with the former demanding sanitary-grade stainless steel construction and the latter requiring micron-level dispensing precision.
EPA emissions standards in the United States restrict volatile organic compound releases from adhesive operations, compelling equipment upgrades with enclosed melt systems and fume capture. EU F-Gas Regulation and REACH chemical compliance frameworks in Europe mandate material compatibility documentation and restrict certain polymer chemistries used in equipment seals and hoses. Stakeholders must monitor evolving chemical safety classifications and energy efficiency benchmarks as procurement criteria tighten across both regulatory jurisdictions.
Market Dynamics
Equipment replacement cycles in Asia-Pacific food packaging lines are compressing from seven-year intervals to four-year cycles as manufacturers pursue throughput gains and regulatory compliance. This acceleration is redistributing capital flows toward modular electric heating platforms and away from legacy steam-based infrastructure.
Growth Catalysts
- EPA Emissions Standards:United States adhesive operations face volatile organic compound restrictions that mandate enclosed melt systems with fume capture capabilities. Food packaging converters in California and Texas are prioritizing compliant equipment purchases.
- China's Coastal Manufacturing Clusters:Export-oriented packaging operations in Guangdong and Zhejiang provinces operate at sufficient scale to justify automated hot melt line investments. These facilities drive demand for high-throughput dispensing architectures.
- Electric Heating Technology:Precision temperature control and energy efficiency advantages are pulling investment away from steam-based alternatives. Electronics assembly applications in South Korea and Japan specify electric melters for micron-level dispensing accuracy.
Market Restraints
- Specialized Polymer Feedstock Concentration:Thermoplastic adhesive resin supply concentrates among a limited set of petrochemical producers in Germany and the United States. Equipment purchasers face input cost volatility when ethylene-propylene copolymer prices fluctuate.
- EU F-Gas Regulation Compliance Costs:Material compatibility documentation requirements for seals and hoses impose non-trivial certification burdens. Smaller equipment fabricators in Italy and Spain struggle to absorb these fixed compliance investments.
- Water-Based Adhesive Substitution:Cold-seal technologies and aqueous systems compete for paperboard packaging applications where heat sensitivity matters. Certain confectionery and pharmaceutical blister formats are migrating to these alternatives.
Strategic Opportunities
- India's Packaging Infrastructure Buildout:The country's food processing sector expansion under PLI scheme incentives creates greenfield demand for sanitary-grade stainless steel equipment. Domestic converters in Maharashtra and Gujarat lack sufficient installed base.
- Modular Platform Architectures:Automotive assembly applications in Germany and Mexico favor reconfigurable dispensing systems that accommodate model changeovers. Equipment suppliers can capture share by reducing line retooling downtime.
- EU Green Deal Alignment:Energy efficiency benchmarking and carbon footprint disclosure requirements favor electric heating platforms with documented consumption metrics. Equipment vendors can differentiate through verified lifecycle assessments.
Industry Challenges
- Precision Dispensing Talent Scarcity:Electronics assembly applications require technicians capable of calibrating micron-level applicator heads. Technical training programs in Vietnam and Malaysia lag equipment deployment rates.
- Legacy Steam System Integration:Established packaging facilities in Brazil and Indonesia face capital allocation conflicts when retrofitting electric melters alongside functional steam infrastructure. Hybrid transition architectures extend payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Melt Equipment Market |
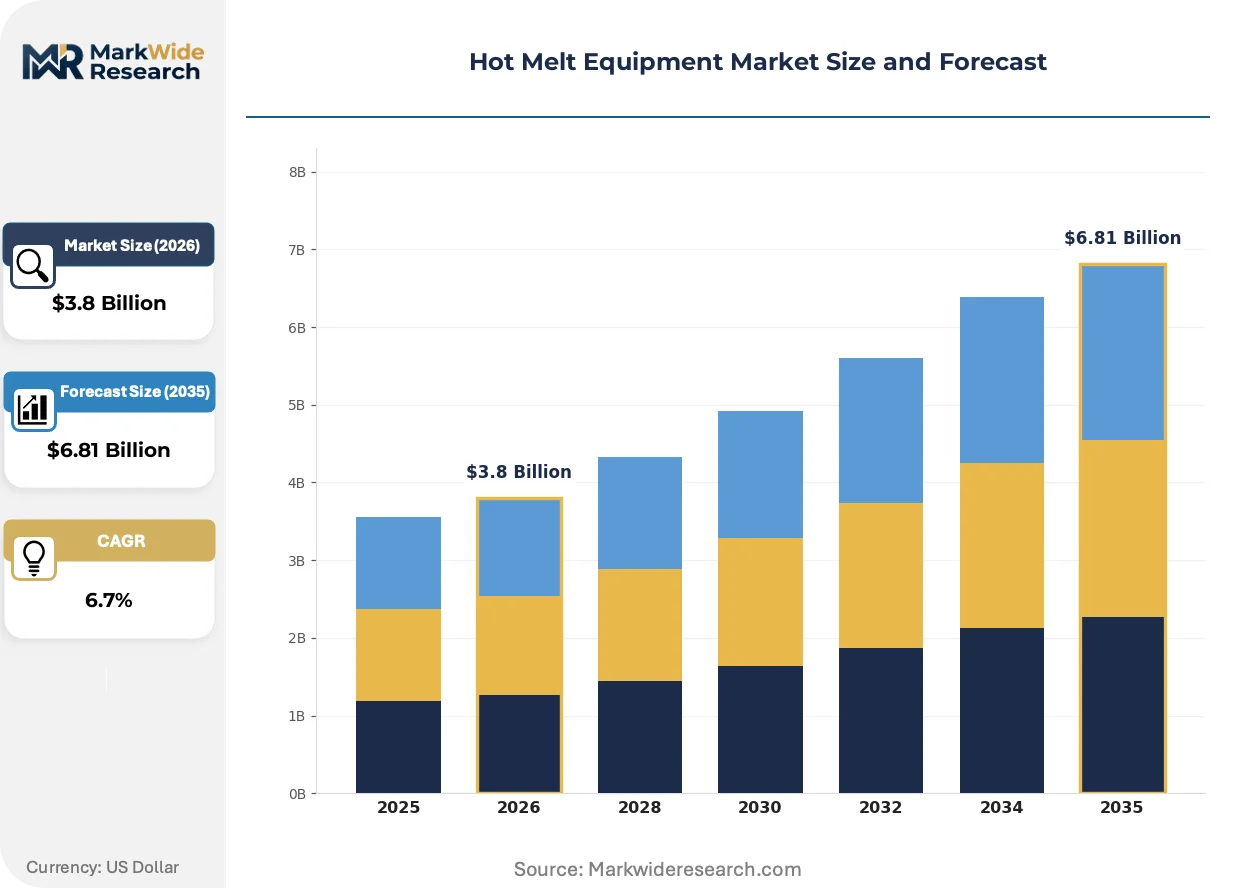
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glue Guns, Application Equipment, Melters, Accessories Technology: Hot Air, Infrared, Steam, Electric End User: Food Packaging, Automotive, Furniture, Electronics Material: Thermoplastics, Adhesives, Coatings, Sealants |
| Companies Covered | Nordson Corporation, Graco Inc., ITW Dynatec, 3M, Henkel AG & Co. KGaA, Robatech AG, Valco Cincinnati Inc., Glue Machinery Corporation, Banseok Precision Industry Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Melt Equipment Market Emerging Trajectories
Hot melt equipment architecture is pivoting toward closed-loop thermal management and predictive maintenance integration. These shifts compress operating costs while tightening bonding consistency across high-variability production environments.
Induction heating elements with embedded thermocouple arrays are rendering obsolete traditional resistance-wire configurations that suffer thermal lag and zone inconsistency. Electronics manufacturers in South Korea and Taiwan specify these systems for semiconductor packaging applications where bond-line uniformity determines yield. The technology is compressing energy consumption per kilogram of adhesive dispensed by eliminating heat-soak losses in idle periods.
REACH chemical compliance frameworks in Europe now mandate full material disclosure for all fluid-contact components including hoses, pumps, and seals. Equipment suppliers must maintain auditable supply chain documentation for fluoropolymer and silicone elastomer chemistries. Automotive assembly plants in Germany and Czech Republic are prioritizing vendors with pre-submitted technical dossiers to accelerate procurement timelines.
Service unbundling is separating equipment hardware from consumables and technical support contracts. Food packaging converters in China's coastal provinces increasingly procure melters through third-party distributors while sourcing adhesive formulations directly from polymer compounders. This channel fragmentation pressures original equipment manufacturers to defend margin through captive spare parts logistics rather than bundled system pricing.
Hot Melt Equipment Market Segmentation
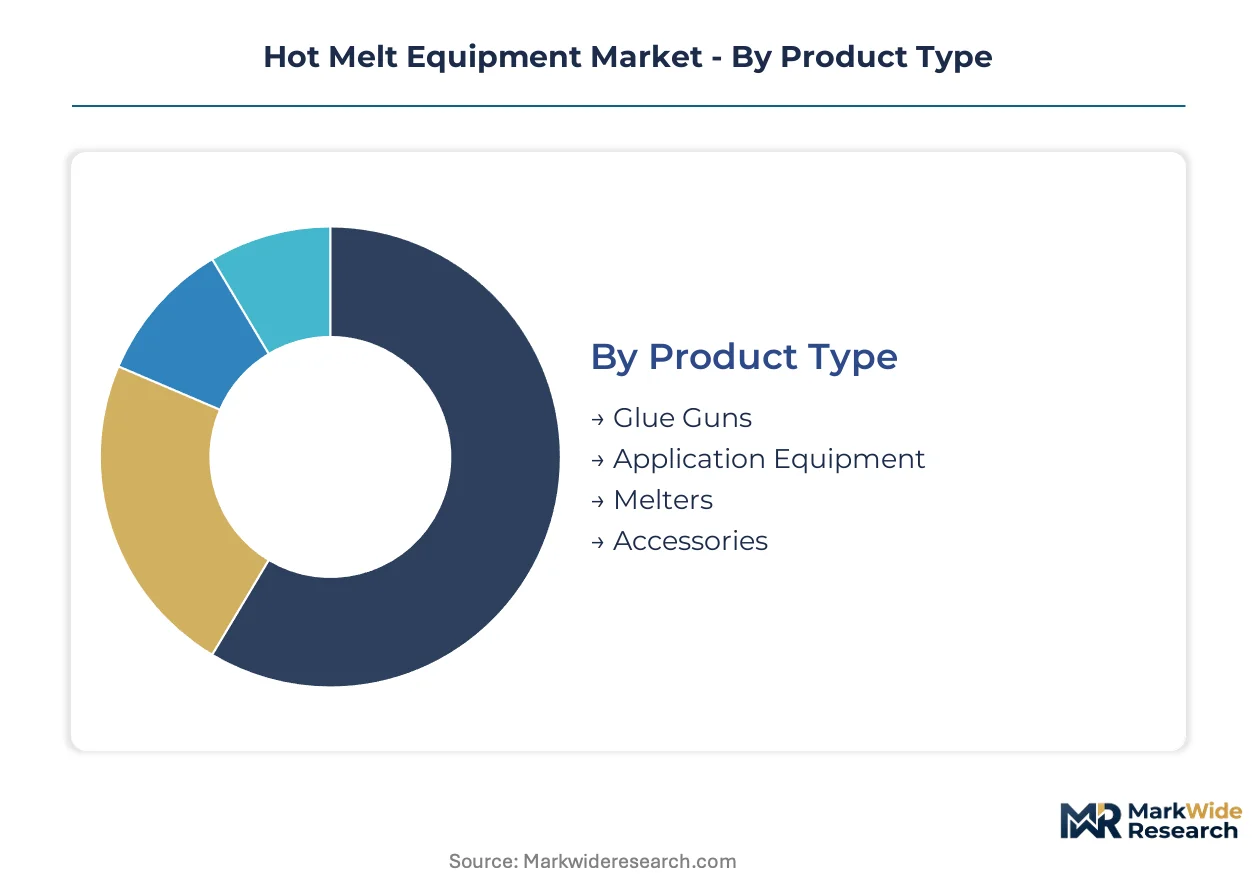
Equipment segmentation in hot melt systems reveals divergent replacement economics across product categories. Cycle time compression in food packaging accelerates turnover for application equipment while melters retain longer depreciation schedules. Technology choices further stratify capital recovery timelines between energy-intensive steam infrastructure and precision electric platforms.
Product Type:
Application equipment turns over fastest in high-throughput packaging environments, while melters anchor longer capital cycles. Glue guns and accessories occupy intermediate replacement intervals depending on duty intensity.
- Melters:These systems heat thermoplastic adhesives to precise molten states between 120°C and 200°C, incorporating pump mechanisms and thermal management architectures. Demand concentrates in China's coastal manufacturing provinces where export-oriented packaging clusters require continuous-duty tank systems with rapid recovery rates. EPA emissions standards mandate enclosed melt configurations with fume capture capabilities.
- Application Equipment:Automated and manual dispensers deliver molten adhesive to substrates through precision nozzles, spray heads, or extrusion dies. Electronics assembly operations in South Korea and Taiwan specify micron-level dispensing heads where bond-line uniformity determines semiconductor packaging yield. Modular platform designs reduce automotive line retooling downtime.
- Glue Guns:Handheld portable devices for manual dispensing operations in furniture assembly and light packaging applications.
- Accessories:Hoses, nozzles, pumps, and seals requiring periodic replacement due to thermal degradation and chemical exposure.
Melters dominate installed base across heavy manufacturing. Application equipment is where expansion concentrates as electronics precision requirements intensify.
Technology:
Cost tier stratification separates premium electric platforms from legacy steam infrastructure with divergent operating economics. Infrared and hot air systems occupy mid-tier positioning with application-specific advantages.
- Electric:Resistance and induction heating elements deliver precise temperature control with embedded thermocouple arrays eliminating thermal lag. Electronics manufacturers in Japan and South Korea specify these systems for energy efficiency and micron-level dispensing accuracy. EU Green Deal energy benchmarking favors documented consumption metrics.
- Steam:Conventional heat exchange systems utilizing facility boiler infrastructure face displacement pressure from efficiency regulations. Established packaging facilities in Brazil and Indonesia confront capital allocation conflicts when retrofitting alongside functional legacy infrastructure.
- Infrared:Radiant heating technology for rapid surface activation in specialized coating applications.
- Hot Air:Convective heating systems for pre-treatment and adhesive activation in furniture and textile bonding.
Electric platforms dominate new capital deployment. Steam retains defensive positions in boiler-integrated facilities.
End User:
Volume concentration varies sharply across end-use verticals with food packaging driving equipment throughput and automotive demanding reconfigurable architectures.
- Food Packaging:Sanitary-grade stainless steel construction with enclosed melt systems and fume capture for regulatory compliance. California and Texas converters prioritize EPA-compliant equipment purchases. India's PLI scheme incentives create greenfield demand in Maharashtra and Gujarat.
- Electronics:Micron-level dispensing precision for semiconductor packaging with induction heating and embedded thermocouple arrays. South Korean and Taiwanese manufacturers specify these systems where bond-line uniformity determines yield.
- Automotive:Modular platform architectures accommodating model changeovers with reduced retooling downtime in German and Mexican assembly plants.
- Furniture:Manual and semi-automated dispensing systems for panel bonding and edge banding operations.
Food packaging commands the largest equipment installed base. Electronics represents the steepest expansion trajectory as precision requirements intensify.
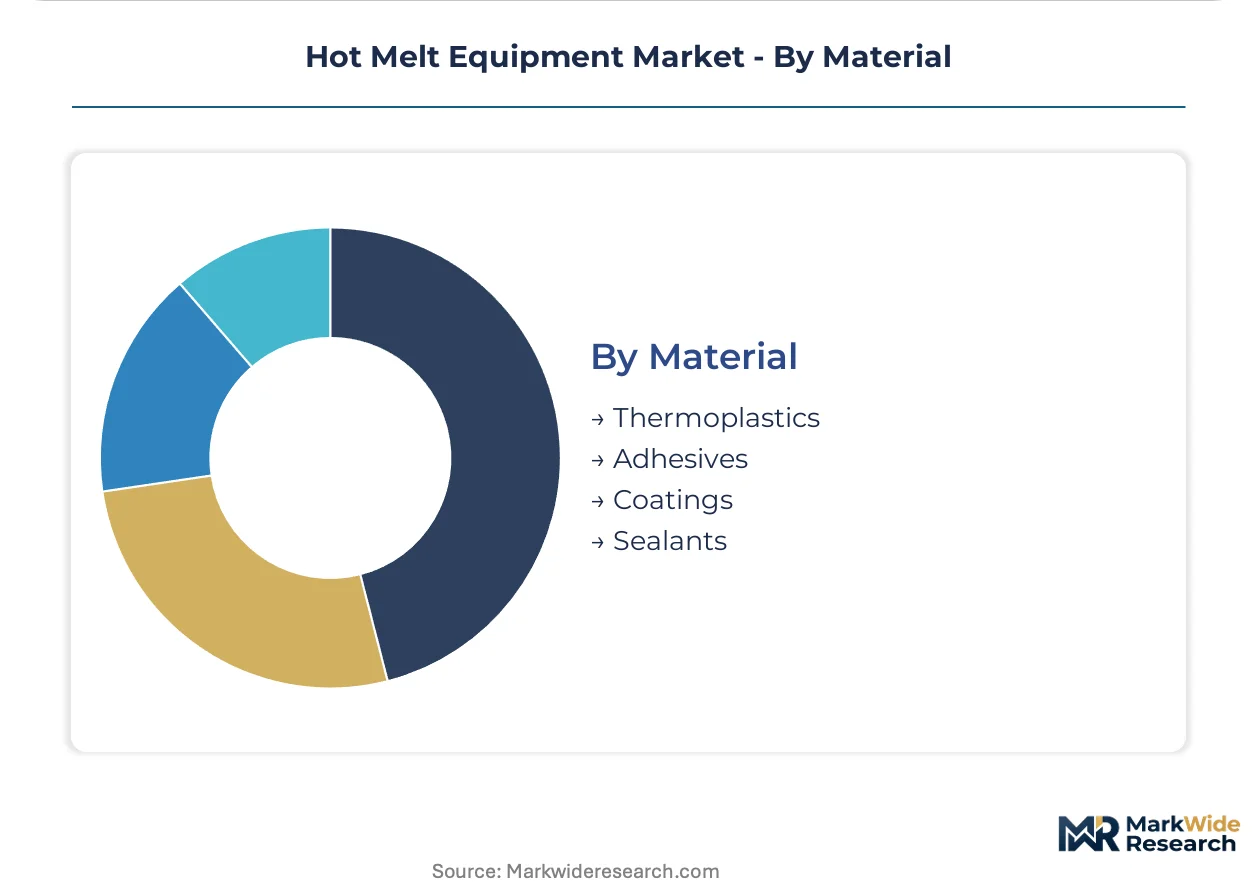
Material:
Supply concentration in polymer feedstocks creates input cost volatility that equipment specifications must accommodate through material compatibility engineering.
- Thermoplastics:Ethylene-propylene copolymers and polyolefin formulations requiring precise temperature control to maintain viscosity profiles. REACH compliance mandates full material disclosure for fluid-contact components in European automotive assembly procurement.
- Adhesives:Pressure-sensitive and structural hot melt chemistries with varying thermal stability ranges dictating equipment seal and hose specifications.
- Coatings:Protective and functional layer applications requiring specialized spray or roll-coat dispensing architectures.
- Sealants:Gap-filling and environmental barrier formulations with extended open time requirements affecting pump and nozzle design.
Thermoplastics dominate adhesive throughput volumes. Specialized sealants command premium equipment configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's coastal provinces exhibit the lowest price sensitivity due to scale economies, while converters in Brazil and Indonesia face capital constraints that compress replacement cycles. European procurement prioritizes compliance documentation over upfront cost. India's greenfield installations operate at intermediate elasticity where PLI incentives offset technology premiums.
United States
Food packaging converters in California and Texas drive equipment turnover as EPA emissions standards mandate enclosed melt systems with fume capture. The EPA restricts volatile organic compound releases from adhesive operations. Houston and Dallas-Fort Worth packaging clusters prioritize compliant capital purchases to maintain operational permits.
China
Export-oriented manufacturers in Guangdong and Zhejiang provinces justify automated hot melt line investments through throughput gains. MEE enforcement of dual carbon goals accelerates displacement of energy-intensive steam infrastructure. Shenzhen and Dongguan electronics assemblers specify induction heating systems for micron-level dispensing precision.
Germany
Automotive assembly plants in Bavaria and Baden-Württemberg favor modular platform architectures that reduce model changeover downtime. REACH compliance mandates full material disclosure for all fluid-contact components. Stuttgart and Munich industrial corridors prioritize vendors with pre-submitted technical dossiers to accelerate procurement.
India
Food processing sector expansion under PLI scheme incentives creates greenfield demand for sanitary-grade stainless steel equipment. FSSAI sanitary regulations align with international packaging standards. Domestic converters in Maharashtra and Gujarat lack sufficient installed base, opening territory for first-mover equipment suppliers.
South Korea
Electronics manufacturers specify electric melters with embedded thermocouple arrays for semiconductor packaging yield optimization. MFDS chemical safety classifications influence material compatibility requirements. Seoul and Suwon production corridors concentrate demand for precision dispensing architectures where bond-line uniformity determines output quality.
Hot Melt Equipment Market Vendor Landscape
Capability concentration sits with precision-tier specialists; scale advantage sits with diversified industrial conglomerates. The vendor base separates into three functional tiers: integrated adhesive-equipment systems providers, dedicated dispensing technology fabricators, and regional aftermarket service specialists. Consolidation pressure operates most intensely among mid-scale European equipment houses facing REACH documentation burdens. Dominant competitive moves include geographic expansion into India's packaging infrastructure buildout and portfolio diversification toward predictive maintenance service contracts.
Among diversified industrial technology groups, Nordson Corporation and Graco Inc. occupy positions where global spare parts logistics networks anchor recurring revenue streams. ITW Dynatec sits within the precision-tier specialist category, exemplifying modular platform designs targeted at high-volume automotive assembly applications. These three entities represent distinct competitive archetypes: the integrated systems provider with captive consumables, the precision fluid handling specialist with dedicated R&D facilities, and the application-focused fabricator with vertical market concentration.
| Leading Market Players |
|---|
| Nordson Corporation |
| Graco Inc. |
| ITW Dynatec |
| 3M |
| Henkel AG & Co. KGaA |
| Robatech AG |
| Valco Cincinnati Inc. |
| Glue Machinery Corporation |
| Banseok Precision Industry Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Guangdong province's dense concentration of export-oriented packaging clusters generates capacity leverage that compresses procurement costs for coastal Chinese converters while amplifying margin pressure on equipment fabricators serving price-sensitive inland markets.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational packaging converters and tier-one equipment suppliers, insulating volume purchasers from spot-price volatility in polymer feedstock markets. Three-tier pricing structure across premium induction-heating platforms, standard electric melters, and legacy steam systems differentiates on energy efficiency documentation and REACH pre-certification status. Cost compression in mid-tier electric equipment is intensifying because Italian and Spanish fabricators absorb fixed compliance investments for EU F-Gas material documentation. Food packaging converters in India's Maharashtra and Gujarat exhibit highest price sensitivity due to greenfield capital constraints, while South Korean electronics assemblers prioritize micron-level precision over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for equipment fabricators sourcing induction heating elements and precision pump assemblies. Manufacturing concentrates in Germany, China, and South Korea, with ethylene-propylene copolymer feedstock drawing from petrochemical complexes in the United States and Germany. Distribution runs through captive aftermarket service networks for spare parts logistics alongside third-party distributors unbundling adhesive formulations from hardware procurement. Single-source vulnerability in fluoropolymer seal chemistries threatens production continuity for European automotive assembly suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot melt equipment sits in early-cycle expansion as India's PLI-scheme packaging infrastructure buildout accelerates first-time equipment procurement faster than replacement demand in mature markets.
For Market Incumbents: Build captive spare parts logistics moats to defend recurring revenue streams against channel fragmentation. Consolidate position through backward integration into precision pump manufacturing to offset margin pressure from polymer feedstock volatility. Prioritize pre-submitted REACH technical dossiers to accelerate procurement timelines with German automotive assembly plants. For New Entrants and Emerging Players: Build out sanitary-grade stainless steel equipment offerings targeting Maharashtra and Gujarat food processing corridors where domestic installed base remains underdeveloped. Capture share through project-based pricing models that bundle installation with FSSAI compliance consulting. Focus initial penetration on mid-tier electric melter segments where incumbent lead times extend beyond converter capacity expansion schedules. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH documentation burdens and spare parts logistics scale advantages favor integrated systems providers over fragmented regional fabricators. Target mid-scale European equipment houses in Italy and Spain facing fixed compliance cost absorption challenges. Monitor EPA enforcement intensity in California and Texas as signal for North American equipment turnover inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Pump Manufacturing | Captures margin from polymer feedstock volatility affecting German automotive suppliers. |
| REACH Pre-Certification Investment | Accelerates procurement timelines with Bavaria and Baden-Württemberg assembly plants. |
| India Greenfield Distribution Partnership | Establishes first-mover position in Maharashtra and Gujarat PLI-scheme corridors. |
| Predictive Maintenance Service Contract Launch | Defends margin against unbundling pressure from Chinese coastal packaging converters. |
| Induction Heating Technology Licensing | Penetrates South Korean and Taiwanese electronics assembly precision segments. |
Methodological Framework
Desk research of customs trade data, SEC equipment manufacturer filings, and EPA enforcement records preceded structured interviews with plant engineers at packaging converters, procurement leads at automotive OEMs, aftermarket service heads, and technical R&D directors at adhesive compounders. Primary fieldwork across China's Guangdong and Zhejiang manufacturing clusters, Germany's Stuttgart industrial corridor, and India's Maharashtra food processing zones combined with secondary validation from MEE dual carbon policy documents and EU F-Gas Regulation compliance databases. Bottom-up equipment shipment analysis triangulated against top-down adhesive consumption metrics.
Assumptions held fixed include EPA emissions standard enforcement intensity and EU REACH material disclosure scope, while polymer feedstock price trajectories and PLI scheme incentive duration were varied across sensitivity bands. Segmentation modeling spanned product type, heating technology architecture, end-use vertical precision requirements, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression analysis and greenfield installation pacing across the projection horizon. Forecast inputs incorporated electronics assembly yield sensitivity to bond-line uniformity and automotive model changeover frequency.
Stress conditions across ethylene-propylene copolymer price volatility, MEE enforcement acceleration, and water-based adhesive substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory scope expansion or technology displacement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Packing Belt Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Packer Market
Packaging Equipment
PET Preform Machine Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Single Use Mixer Market
Packaging Equipment
Auger Filler Market