
 Shrink Wrap Equipment Market | 2026-2036
Shrink Wrap Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Wrap Equipment Market Analytics
Skilled automation technician availability is reorganizing how OEMs scale production capacity across North America and Western Europe. Texwrap Packaging Systems leverages vertical integration to control lead times on custom L-bar sealers for regional food distributors. Douglas Machine anchors its position through deep specialization in high-speed overwrappers for pharmaceutical contract packagers. MSK Verpackungs-Systeme dominates pallet-wrapping system exports from its German manufacturing base into Central European logistics hubs.
Shrink wrap equipment comprises heat-sealing machinery and shrink tunnels that apply controlled thermal energy to polymer films, typically polyethylene or polyolefin, causing molecular orientation relaxation that yields a tight product enclosure. These systems operate at temperatures between 150°C and 300°C depending on film gauge and throughput requirements, serving primary functions in product protection, unitization, and retail-ready presentation. L-bar sealers and automatic overwrappers occupy mature, high-volume positions where margin compression has pushed vendors toward aftermarket service contracts. Shrink tunnels and hybrid-technology systems represent faster-growing pockets as energy efficiency mandates reshape capital expenditure priorities. Electric-heated units are displacing legacy pneumatic and gas-fired alternatives in facilities subject to carbon accounting requirements.
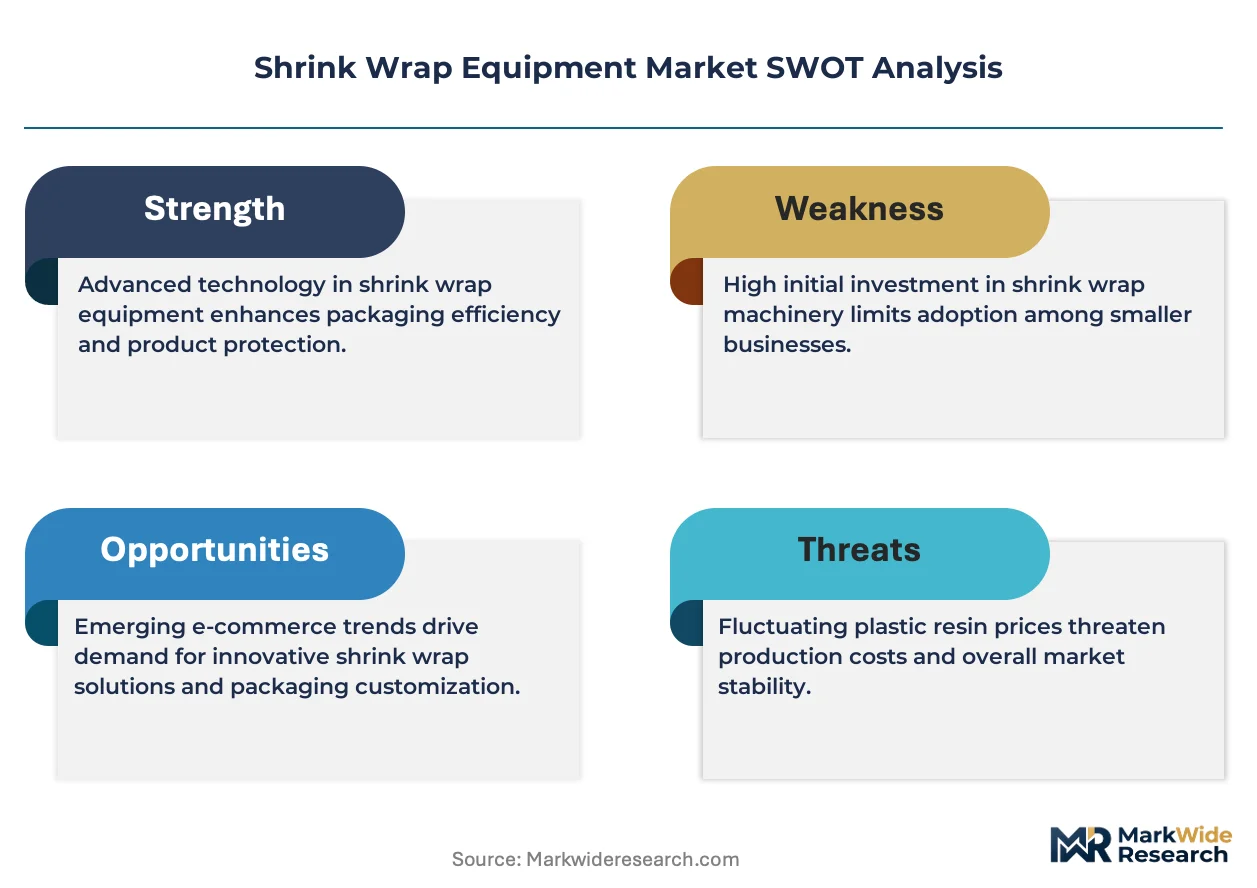
FDA food-contact material regulations and EU REACH compliance on film additives directly shape equipment specification requirements for cross-border machinery sales. OSHA thermal hazard standards and CE marking obligations under the EU Machinery Directive impose design and guarding protocols that lengthen engineering cycles but create compliance-based differentiation among vendors. Stakeholders must weigh total cost of ownership against retrofit compatibility as sustainability reporting obligations expand beyond Europe into North American and Asian procurement frameworks.
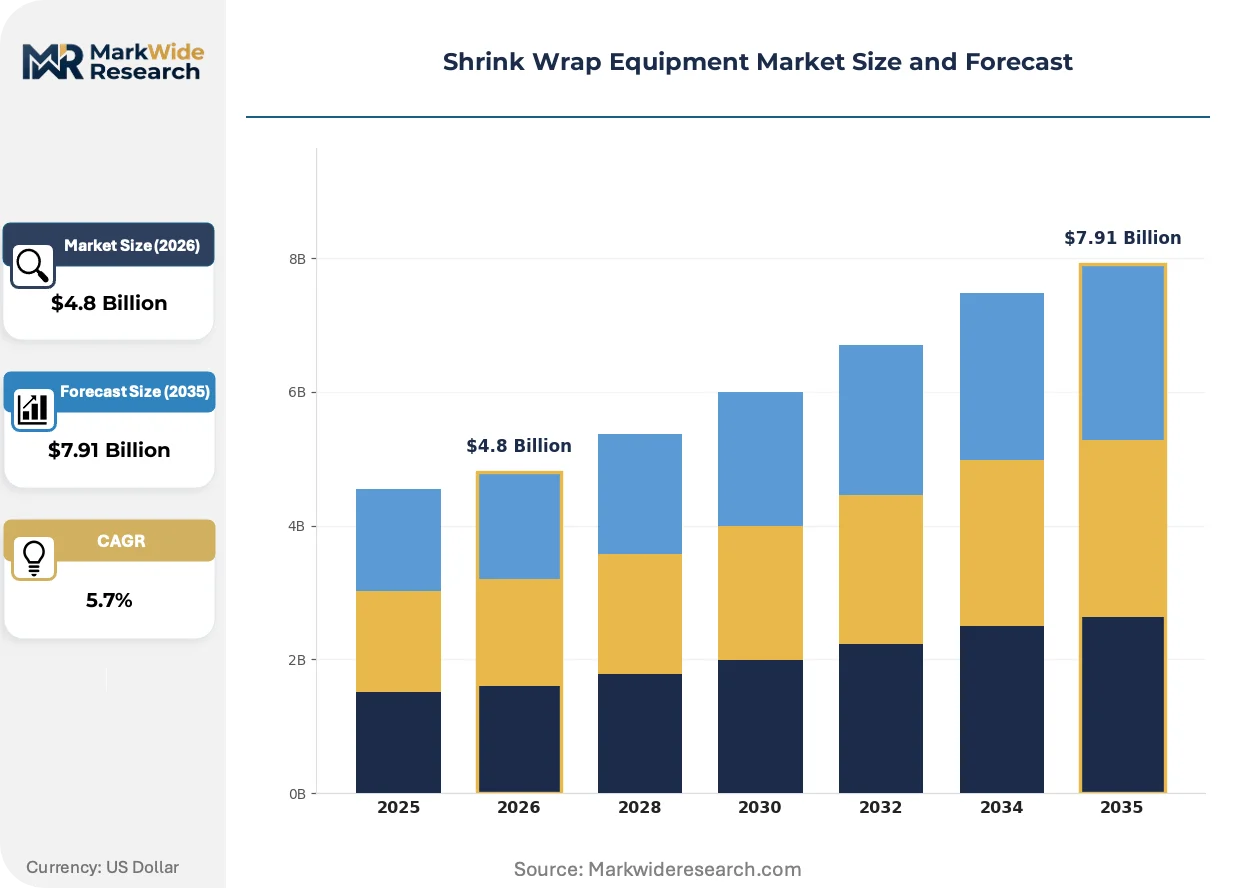
Market Dynamics
EU F-Gas Regulation mandates are forcing accelerated capital rotation from gas-heated to electric and steam-based shrink tunnel architectures across European processing facilities.
Growth Catalysts
- EU F-Gas Phase-Down:The regulation's stepped reduction in hydrofluorocarbon availability is compelling food processors to replace legacy gas-fired tunnels with electric-heated alternatives ahead of compliance deadlines.
- Film Material Innovation:Polyolefin films with lower sealing temperatures are expanding equipment compatibility across temperature-sensitive pharmaceutical and electronics packaging lines.
- German Engineering Clusters:Machinery manufacturing concentration around Stuttgart and Munich enables rapid prototyping and shortened delivery cycles for export-bound pallet-wrapping systems.
Market Restraints
- Copper and Aluminum Price Volatility:Heating element raw material cost swings compress margins on electric tunnel production and complicate long-term contract pricing.
- Control System Supplier Concentration:Dependence on German and Japanese PLC manufacturers creates vulnerability for mid-tier OEMs seeking to scale output.
- Film Thickness Limitations:Current polyethylene formulations above 150 gauge require extended dwell times that constrain line speed improvements in high-throughput environments.
Strategic Opportunities
- India Food Processing Expansion:Cold chain infrastructure investment under the PLI scheme is generating first-time demand for automated L-bar sealers among domestic snack and dairy processors.
- Pharmaceutical Serialization Integration:Convergence of shrink wrapping with track-and-trace systems creates bundled equipment sales potential for contract packaging service providers.
- US Inflation Reduction Act Clean Energy Credits:Facility energy efficiency upgrades qualify for tax incentives that reduce payback periods on electric tunnel investments.
Industry Challenges
- Automation Technician Scarcity:Programming and maintenance of servo-driven sealing systems requires skills that outpace vocational training output in Midwest US manufacturing corridors.
- CE Marking Documentation Burden:EU Machinery Directive compliance timelines extend product development cycles by four to six months for non-European OEMs seeking market entry.
- Legacy Pneumatic System Integration:Hybrid retrofits of existing packaging lines demand custom mechanical interfaces that fragment engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Wrap Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shrink Tunnels, L-Bar Sealers, Automatic Overwrappers, Manual Sealers Technology: Electric, Pneumatic, Steam, Hybrid End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Packaging Type: Bundling, Pallet Wrapping, Single Item, Multi-Pack |
| Companies Covered | Texwrap Packaging Systems LLC (Pro Mach Inc.), Standard-Knapp, Inc., Aetna Group S.P.A., PAC Machinery Group, Conflex Incorporated, U.S. Packaging & Wrapping LLC, Douglas Machine Inc., MSK Verpackungs-Systeme GmbH, Duravant LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Wrap Equipment Market Evolving Landscape
Active thermal management architectures and control system convergence are compressing equipment footprints while elevating energy accountability requirements across buyer specifications.
Infrared ceramic heating elements are miniaturizing tunnel chamber dimensions while maintaining heat distribution uniformity. Pharmaceutical contract packagers in Switzerland and Germany are adopting these compact units to reclaim floor space for serialization equipment. The technology is miniaturizing standard tunnel footprints by thirty to forty percent without throughput sacrifice.
REACH compliance on film additive substances is restricting phthalate-based plasticizer use in European food-contact applications. Machinery vendors must validate sealing temperature profiles for reformulated films that exhibit altered shrink response curves. High-speed overwrapper deployments in France and Italy face extended qualification periods as processors test alternative film chemistries.
Equipment-as-a-service contracting is displacing outright purchase models among North American regional food distributors. Monthly fee structures bundle maintenance, film supply, and throughput guarantees, transferring operational risk to OEMs. The model is most visible in California and Texas where distributor consolidation has concentrated buyer negotiating leverage.
Shrink Wrap Equipment Market Segmentation
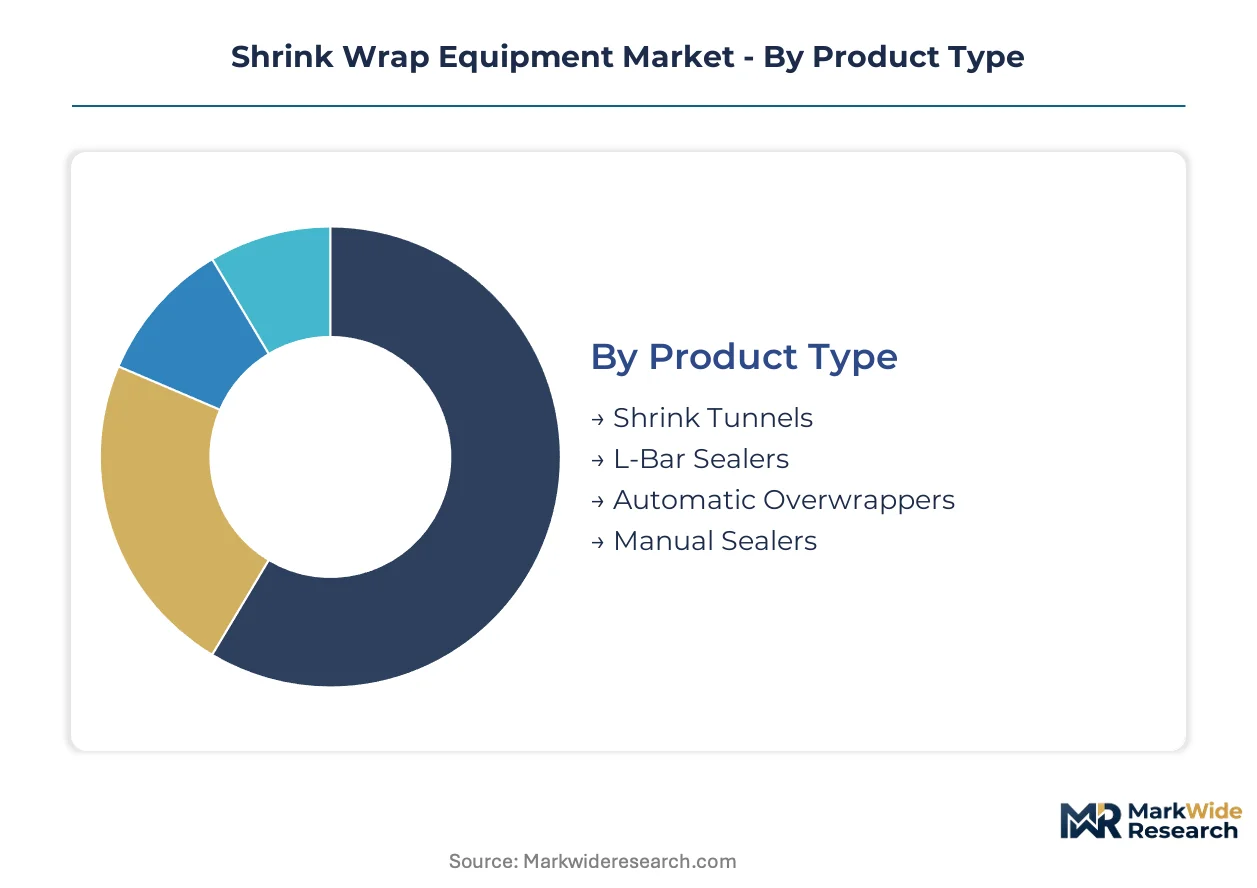
Shrink wrap equipment purchasing patterns diverge sharply between domestic processors seeking standardized throughput solutions and export-oriented machinery engineering clusters customizing for regional compliance regimes. Segment boundaries are blurring as energy efficiency mandates force technology convergence across product categories.
Product Type:
German and Italian OEMs dominate export markets for high-value automated systems, while domestic assembly of manual sealers concentrates in lower-cost manufacturing zones serving localized food processing.
- Shrink Tunnels:These chamber-based systems apply controlled thermal energy through convection, infrared, or steam methods to relax polymer film orientation. Demand is concentrating in German pharmaceutical corridors where FDA and EMA dual-compliance requirements favor validated electric-heated architectures over legacy gas-fired units.
- L-Bar Sealers:L-shaped sealing bars cut and seal film in a single motion, accommodating variable product dimensions through adjustable stroke lengths. California and Texas regional food distributors are driving equipment-as-a-service contracting for these systems as distributor consolidation transfers operational risk to OEMs.
- Automatic Overwrappers:High-speed rotary and inline systems integrate feeding, film application, and sealing for continuous production lines.
- Manual Sealers:Hand-operated impulse or constant-heat units serve low-volume operations and specialty packaging requirements.
Shrink tunnels hold the largest share; momentum sits with automatic overwrappers as pharmaceutical serialization integration creates bundled sales potential.
Technology:
Capital expenditure priorities are splitting between retrofit-compatible electric systems and greenfield steam-based installations favored by carbon accounting frameworks.
- Electric:Resistive and infrared ceramic heating elements deliver precise temperature control with measurable energy accountability. Swiss and German pharmaceutical contract packagers are reclaiming thirty to forty percent of tunnel floor space through compact infrared ceramic architectures.
- Pneumatic:Compressed-air-driven sealing mechanisms persist in legacy installations where pneumatic infrastructure is already amortized.
- Steam:Saturated steam heat transfer offers uniform temperature distribution for temperature-sensitive products.
- Hybrid:Configurations combine electric sealing with alternative heat sources for operational flexibility.
Electric systems command the dominant installed base; steam is climbing the fastest as EU F-Gas Regulation compliance deadlines accelerate capital rotation.
End User:
Regulatory stringency tiers separate pharmaceutical and food-contact applications from cosmetics and electronics where film additive restrictions are less prescriptive.
- Food & Beverage:Automated lines for snack, dairy, and beverage processors must validate sealing profiles for REACH-compliant films with altered shrink response curves.
- Pharmaceuticals:Track-and-trace serialization requirements in Switzerland and Germany are driving convergence between shrink wrapping and authentication systems.
- Cosmetics:Premium presentation demands favor high-clarity polyolefin films with lower sealing temperatures.
- Electronics:Static-dissipative films and controlled atmosphere packaging protect sensitive components.
Food and beverage represents the largest addressable volume; pharmaceuticals are expanding most quickly through serialization integration mandates.
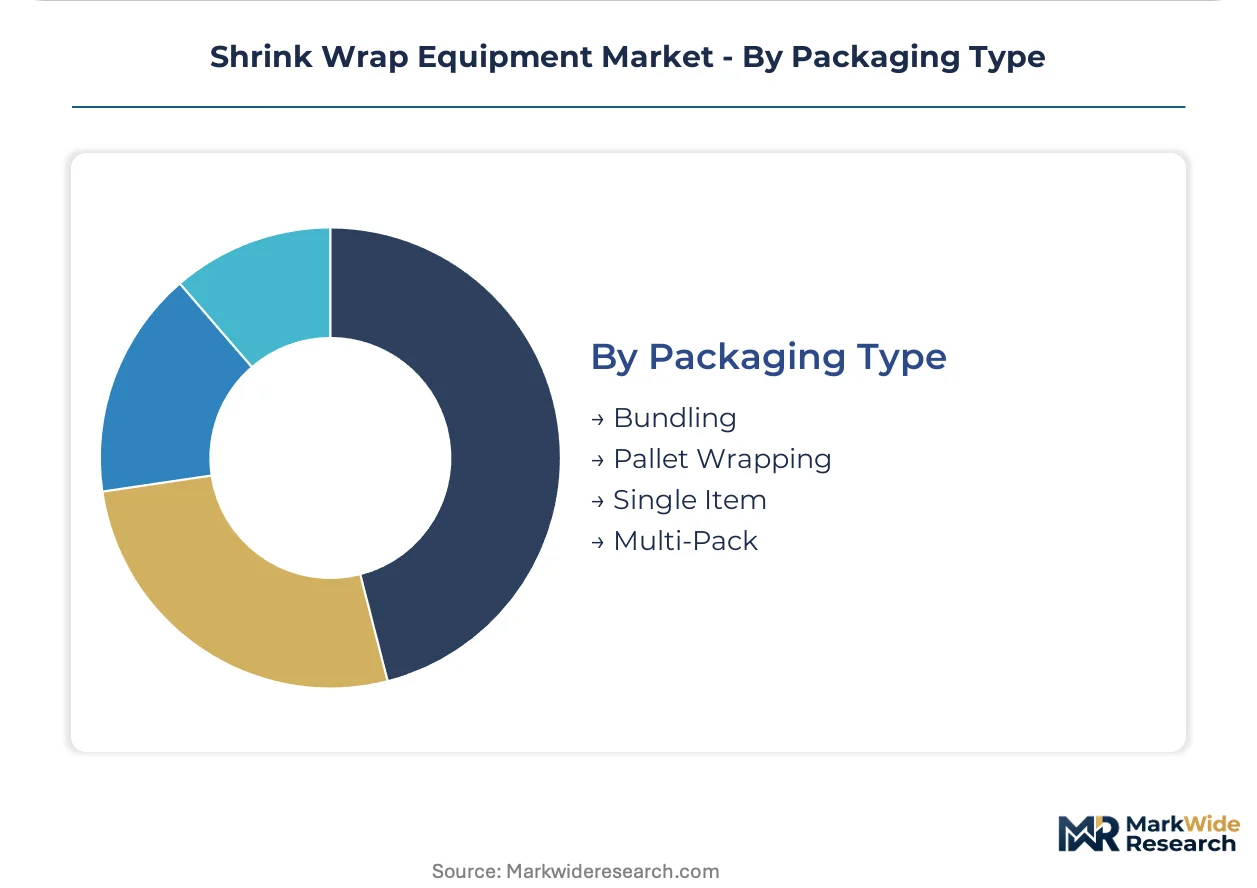
Packaging Type:
Unitization scale determines equipment specification, from single-item retail presentation through pallet-level logistics consolidation.
- Bundling:Multi-item collation systems group products for promotional or logistical efficiency.
- Pallet Wrapping:MSK Verpackungs-Systeme and comparable German engineering clusters dominate export of automated pallet-wrapping systems into Central European logistics hubs.
- Single Item:Individual product overwrapping serves retail-ready presentation requirements.
- Multi-Pack:Promotional and club-store formats require collation and wrapping in single operations.
Pallet wrapping holds the largest share; bundling is gaining share fastest as e-commerce fulfillment drives promotional pack demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European capital rotation priorities, while distinct national procurement frameworks reshape equipment specification requirements across manufacturing corridors in Germany, the United States, India, and Switzerland.
Germany
Stuttgart and Munich engineering clusters dominate export-oriented pallet-wrapping system production for Central European logistics hubs. The EU Machinery Directive imposes CE marking obligations that extend product development cycles for non-European OEMs seeking market entry. Baden-Württemberg machinery manufacturers are accelerating prototyping cycles for electric-heated shrink tunnel architectures ahead of F-Gas phase-down deadlines.
United States
California and Texas regional food distributors are driving equipment-as-a-service contracting models that transfer operational risk to OEMs. OSHA thermal hazard standards impose design and guarding protocols that lengthen engineering cycles but create compliance-based differentiation among vendors. Midwest manufacturing corridors face automation technician scarcity that constrains servo-driven sealing system deployment.
India
Cold chain infrastructure investment under the PLI scheme generates first-time demand for automated L-bar sealers among domestic snack and dairy processors. FSSAI food-contact material regulations shape equipment specification requirements for cross-border machinery sales. Maharashtra and Gujarat processing facilities are expanding automated packaging lines to meet throughput targets under central government production-linked incentive frameworks.
Switzerland
Pharmaceutical contract packagers in Basel and Zurich corridors are adopting compact infrared ceramic tunnel architectures to reclaim floor space for serialization equipment. Swissmedic track-and-trace requirements drive convergence between shrink wrapping and authentication systems. The country's precision manufacturing base validates sealing temperature profiles for REACH-compliant films with altered shrink response curves.
Shrink Wrap Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former controlling captive supply chains for heating elements and control systems while the latter concentrates on regional customization and aftermarket service density. The vendor base separates into three strategic archetypes: vertically integrated system builders, component-specialist sub-suppliers, and regional service-anchored distributors. Dominant competitive moves include backward integration into heating element manufacturing and geographic expansion through distributor acquisition in high-growth Asian markets.
Among Germany-based engineering specialists, MSK Verpackungs-Systeme GmbH exemplifies the export-focused pallet-wrapping archetype, while Douglas Machine Inc. and Texwrap Packaging Systems LLC represent North American positions in pharmaceutical and food distribution verticals respectively. These three anchors illustrate how regional regulatory specialization—CE marking proficiency, FDA validation capability, and OSHA compliance documentation—separates sustainable competitive positions from commodity equipment fabrication.
| Leading Market Players |
|---|
| Texwrap Packaging Systems LLC (Pro Mach Inc.) |
| Standard-Knapp, Inc. |
| Aetna Group S.P.A. |
| PAC Machinery Group |
| Conflex Incorporated |
| U.S. Packaging & Wrapping LLC |
| Douglas Machine Inc. |
| MSK Verpackungs-Systeme GmbH |
| Duravant LLC |
| Others |
Value Network & Pricing Analysis
Long-term equipment-as-a-service contracts lock in both heating element supply access and predictable pricing visibility for regional food distributors in California and Texas, insulating OEMs from copper and aluminum cost volatility while transferring operational risk downstream.
Pricing Analysis
German-engineered electric shrink tunnels command price premiums of thirty to forty percent above Asian-manufactured alternatives, reflecting CE marking compliance costs and validated thermal management architectures. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from regional food-grade equipment and manual sealer imports. Pricing pressure stems from raw material cost swings in heating element production, compressing margins on electric tunnel manufacturing. Regional food distributors exhibit highest price sensitivity, while pharmaceutical contract packagers prioritize compliance documentation over unit cost.
Supply Chain Analysis
Strategic stockpiling of PLC control systems and infrared ceramic heating elements characterizes German and Japanese OEM procurement, buffering against semiconductor supply constraints that disrupted pneumatic system retrofits. Manufacturing concentration centers on Germany, Italy, and China, with Stuttgart engineering clusters drawing from captive heating element production while Asian assembly feeds standardized manual sealer demand. Supply chain risk rests on single-source vulnerability for German and Japanese PLC manufacturers. Distribution runs through machinery engineering clusters serving export markets, anchored by regional service-anchored distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shrink wrap equipment market is accelerating through a regulatory inflection as EU F-Gas mandates force capital rotation from gas-heated to electric architectures, compressing replacement cycles and elevating energy accountability requirements.
For Market Incumbents: Compound service contract density to lock in aftermarket revenue streams as margin compression intensifies on equipment sales, while accelerating backward integration into infrared ceramic heating element manufacturing to secure supply against raw material volatility. CE marking proficiency and FDA validation capability separate sustainable positions from commodity fabrication. For New Entrants and Emerging Players: Lead with compact electric tunnel architectures targeting India's PLI-funded cold chain expansion, where first-time automated packaging demand among domestic snack processors outpaces established service infrastructure. Bundle equipment-as-a-service contracting with film supply agreements to transfer operational risk and capture recurring revenue. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive heating element production and established CE marking documentation workflows, positioned to capture European F-Gas compliance-driven replacement demand. The signal to watch is distributor consolidation in North American regional food networks, which concentrates buyer negotiating leverage and accelerates contracting model adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive supply of copper and aluminum components insulates margin from commodity volatility. |
| Equipment-as-a-Service Contracting | Monthly fee structures transfer operational risk to OEMs in California and Texas distributor markets. |
| CE Marking Documentation Investment | Four to six month compliance timelines create barrier against non-European OEM market entry. |
| Pharmaceutical Serialization Integration | Convergence with track-and-trace systems opens bundled sales potential in Swiss and German corridors. |
| Regional Distributor Acquisition | Geographic expansion through channel control captures PLI-driven demand in Maharashtra and Gujarat. |
Research Methodology
The analysis maps shrink tunnels, L-bar sealers, automatic overwrappers, and manual sealers, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and regional food distributor operations managers. Primary interviews triangulate with customs trade data, SEC machinery manufacturer filings, EU F-Gas Regulation compliance databases, and production-linked incentive scheme disclosures. Bottom-up equipment unit economics reconcile against top-down market sizing across the projection horizon.
Consistency checks validated volume and value outputs against heating element raw material consumption patterns and pharmaceutical serialization equipment deployment rates. Segmentation dimensions modeled include product type, heating technology architecture, end-use regulatory tier, and regional manufacturing cluster. CAGRs derive from replacement cycle compression under F-Gas mandates and cold chain infrastructure buildout rates, with electric tunnel adoption curves and film formulation qualification timelines as key forecast inputs.
Underlying assumptions cover EU F-Gas phase-down adherence, copper price stabilization, and vocational training output for automation technicians, with deviation risk concentrated in semiconductor supply constraints for PLC control systems. Revision becomes warranted when heating element raw material costs cross volatility thresholds that invalidate equipment-as-a-service contract economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Automatic Liquid Filling Market
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Plastic Waste Sorting Equipment Market
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Cannabis Packaging Equipment Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
Packing Belt Market
Packaging Equipment
Powder Filling Equipment Market
Packaging Equipment
Flow Wrap Packaging Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Packaging Equipment Market