
 Label Converting Equipment Market | 2026-2036
Label Converting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Label Converting Equipment Market Foresight
Aftermarket service revenue is reconfiguring profit pools across the label converting equipment landscape. Bobst Group SA leverages its global parts logistics network to capture recurring maintenance contracts. Mark Andy Inc. anchors its competitive stance through vertical integration into precision die supply. Nilpeter specializes in narrow-web flexographic configurations for premium beverage converters.
Label converting equipment encompasses machinery that transforms raw label stock into finished adhesive products through printing, die-cutting, laminating, and rewinding operations, typically handling web widths from 250 mm to 530 mm at speeds exceeding 200 meters per minute for high-volume packaging lines. Flexographic systems retain the largest installed base among product types, though digital configurations are gaining share in short-run pharmaceutical and personalized food packaging segments where UV-cured inkjet technology eliminates plate costs and reduces changeover intervals.
FDA serialization requirements for pharmaceutical packaging and EU F-Gas Regulation restrictions on solvent-based systems are redirecting capital toward compliant digital and water-based converting platforms. REACH chemical compliance and CE marking obligations further constrain equipment specification for European pharmaceutical converters. Stakeholders must weigh total cost of ownership against regulatory compliance horizons when committing to platform investments.
Market Dynamics
Pharmaceutical serialization mandates and EU F-Gas solvent restrictions are compressing equipment replacement cycles while redirecting capital toward digital and water-based converting platforms.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Track-and-trace requirements for pharmaceutical packaging are forcing converters in the United States to upgrade legacy flexographic lines with serialization-ready digital configurations.
- UV-cured inkjet adoption:Mid-size food packaging converters in India are eliminating plate costs and reducing changeover intervals through single-pass digital workflows for shorter run lengths.
- EU F-Gas Regulation phase-down:Restrictions on solvent-based systems are accelerating capital redeployment toward water-based and energy-curing converting platforms across German pharmaceutical packaging clusters.
Market Restraints
- Precision die supply concentration:Captive production of hardened tooling remains concentrated among a limited supplier base in Central Europe, constraining converter flexibility during demand surges.
- Skilled operator scarcity:Shortages of technicians trained in hybrid flexographic-digital workflow management are extending commissioning timelines for multi-process equipment installations.
- REACH chemical compliance friction:Registration, evaluation, and authorization obligations for UV-cured ink chemistries are lengthening equipment qualification periods for European pharmaceutical converters.
Strategic Opportunities
- Personalized food packaging micro-segments:Variable-data printing for regional cuisine labels and seasonal promotions represents unpenetrated volume for digital converting equipment in India.
- Aftermarket service unbundling:Independent parts logistics and remote diagnostics capabilities offer recurring revenue capture beyond original equipment sales for established service networks.
- CE marking harmonization:Simplified conformity assessment procedures for digital printing modules are reducing time-to-market for equipment upgrades across EU member states.
Industry Challenges
- Legacy system integration complexity:Retrofitting existing rewind and die-cutting stations with digital front-ends requires custom mechanical engineering that extends project timelines.
- Certification timeline compression:Pharmaceutical converters face compressed validation windows between FDA guidance updates and commercial deployment deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Label Converting Equipment Market |
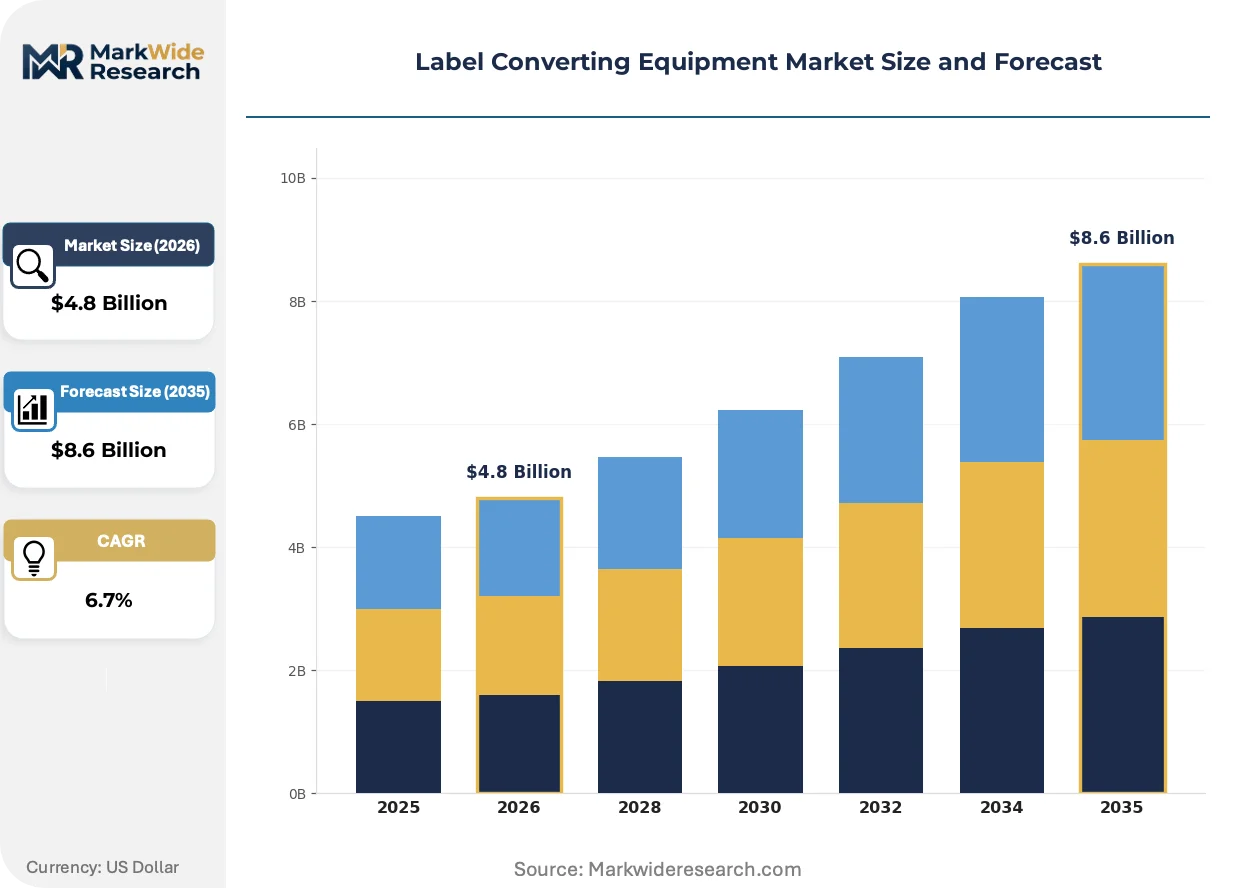
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexographic, Digital, Gravure, Hybrid Application: Beverages, Food Packaging, Pharmaceuticals, Industrial Labels End User: OEMs, Brand Owners, Converters, Retailers Technology: Water-Based, Solvent-Based, UV-Cured, Laser Cutting |
| Companies Covered | SMAG Graphique, A B Graphic International Ltd, Spartanics Ltd., Gallus Group, Mark Andy Inc., ASHE Converting Equipment, Bobst Group SA, Nilpeter, Daco Solutions Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Label Converting Equipment Market Shifts & Advancements
Digital front-end architectures and regulatory chemistry constraints are actively reconfiguring equipment specifications and buyer procurement criteria across pharmaceutical and food packaging verticals.
UV-cured inkjet printing heads with single-pass resolution capabilities are enabling variable-data serialization at production speeds matching legacy flexographic output. Pharmaceutical converters in Germany and the United States are adopting these configurations to eliminate plate inventory and reduce job changeover from hours to minutes. The technology is migrating from short-run proofing applications into primary production lines for high-volume drug packaging.
EU F-Gas Regulation restrictions on hydrofluorocarbon solvents are prohibiting new installations of conventional solvent-based laminating systems across member states. Equipment manufacturers are engineering water-based adhesive delivery modules and energy-curing drying tunnels to maintain line speeds without regulated chemistry. German pharmaceutical packaging clusters are most affected, with converters accelerating depreciation schedules to front-load compliant platform investments ahead of 2030 phase-down milestones.
Converter procurement patterns are fragmenting from centralized capital-committee decisions toward distributed technical-manager autonomy for digital module add-ons. Equipment vendors are responding with subscription-based consumable bundling and remote performance monitoring rather than traditional unit-sales models. This behavioral shift is most visible among mid-size Indian food packaging converters seeking operational flexibility without full-platform replacement commitments.
Label Converting Equipment Market Segmentation
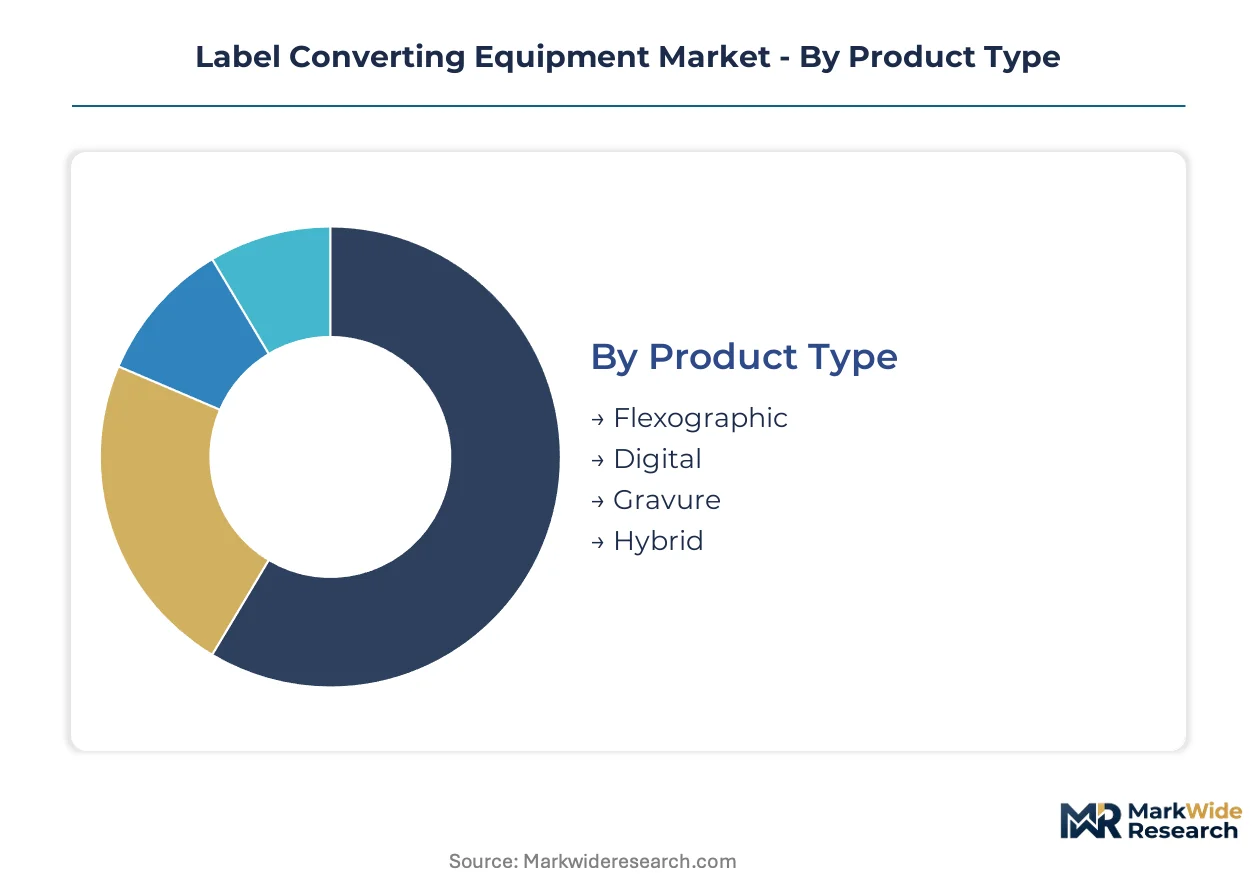
Equipment specification varies sharply across pharmaceutical serialization mandates, food packaging run-length economics, and beverage premiumization requirements. Converters prioritize platform modularity that accommodates regulatory chemistry shifts without full line replacement. Procurement criteria now weight total cost of ownership against compliance horizon flexibility rather than throughput metrics alone.
Product Type:
Converters deploy distinct printing architectures based on run-length economics, regulatory chemistry constraints, and substrate versatility requirements across pharmaceutical and food packaging verticals.
- Flexographic:Rotary letterpress systems utilizing photopolymer plates dominate high-volume beverage and industrial label production. German pharmaceutical converters retain these lines for established drug packaging formats where plate inventory amortizes across multi-year contracts.
- Digital:Single-pass UV-cured inkjet configurations eliminate plate costs and compress changeover intervals from hours to minutes. Mid-size Indian food packaging converters are adopting these systems for regional cuisine labels and seasonal promotional runs.
- Gravure:Cylinder-based intaglio printing delivers superior ink density for metallic decorative effects on premium beverage labels. European converters maintain limited installations for luxury spirits and cosmetic applications requiring scratch-resistant finishes.
- Hybrid:Integrated flexographic-digital architectures combine established web handling with variable-data capabilities. United States pharmaceutical converters favor these configurations for track-and-trace compliance without sacrificing throughput on primary packaging lines.
The dominant share belongs to Flexographic, while Digital is closing the gap fastest.
Application:
End-use demand concentrates where regulatory serialization intersects with operational flexibility requirements.
- Beverages:Premium spirits and craft beer segments drive demand for tactile varnishes and cold-foil stamping modules. European converters serving luxury wine markets specify equipment with inline embellishment stations.
- Food Packaging:Variable-data printing for allergen declarations and regional ingredient sourcing is displacing static formats. Indian mid-size converters seek shorter run capabilities for seasonal promotional campaigns.
- Pharmaceuticals:FDA Drug Supply Chain Security Act mandates are forcing serialization-ready equipment investments across United States converter bases. Track-and-trace compliance now dictates front-end architecture selection.
- Industrial Labels:Chemical resistance and outdoor durability specifications favor solvent-tolerant laminating systems. German industrial label converters balance performance requirements against EU F-Gas Regulation phase-down timelines.
Pharmaceuticals commands the largest equipment investment intensity, though Food Packaging is expanding most quickly.
End User:
Procurement authority patterns fragment based on capital scale and technical integration depth.
- OEMs:Original equipment manufacturers specify converting lines for captive label production integrated with primary packaging systems. Pharmaceutical OEMs in the United States prioritize serialization module compatibility with existing filling line architectures.
- Brand Owners:Consumer goods companies with in-house converting operations seek equipment with rapid format change capabilities. Beverage brand owners specify modular platforms accommodating seasonal promotional cycles.
- Converters:Independent label suppliers represent the largest equipment installed base across all geographies. Indian mid-size converters drive digital adoption through subscription-based consumable models rather than capital purchase.
- Retailers:Private-label retailers with captive converting capacity prioritize cost-efficient water-based systems for standard shelf-label applications.
Converters hold the dominant procurement volume, while Brand Owners are gaining direct converting capacity fastest.
Technology:
Chemistry compliance and curing energy economics are reconfiguring technology adoption trajectories.
- Water-Based:Acrylic adhesive and ink formulations satisfy EU F-Gas Regulation restrictions without solvent recovery infrastructure. German pharmaceutical packaging clusters are accelerating depreciation schedules to front-load compliant platform investments.
- Solvent-Based:Conventional adhesive systems face prohibition on new installations across EU member states. Existing installations remain operational but replacement parts availability is contracting.
- UV-Cured:Energy-curing inkjet and flexographic configurations eliminate volatile organic compound emissions while maintaining production speeds. REACH chemical compliance obligations for photoinitiator chemistries are lengthening equipment qualification periods.
- Laser Cutting:Non-contact die-cutting technology eliminates hardened tooling supply constraints for short-run applications. Precision edge quality limitations restrict adoption to premium beverage and cosmetic label segments.
UV-Cured retains the largest compliant installed base, while Water-Based is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical converters prioritize serialization-ready digital configurations, while Indian mid-size food packaging operators favor subscription-based consumable models for shorter run lengths. This consumption-mix differential separates regulatory compliance investments from operational flexibility procurement patterns.
United States
FDA Drug Supply Chain Security Act mandates are forcing track-and-trace equipment upgrades across pharmaceutical converter bases. Serialization-ready digital front-ends now dominate capital-committee decisions. Chicago-area packaging clusters are retrofitting legacy flexographic lines with UV-cured inkjet modules to eliminate plate inventory.
Germany
EU F-Gas Regulation restrictions on solvent-based systems are accelerating depreciation schedules for water-based converting platforms. REACH chemical compliance obligations for photoinitiator chemistries are lengthening equipment qualification periods. Stuttgart pharmaceutical packaging clusters are front-loading compliant investments ahead of 2030 phase-down milestones.
India
Mid-size food packaging converters are eliminating plate costs through single-pass digital workflows for regional cuisine labels and seasonal promotional runs. BIS certification requirements for imported printing modules are shaping procurement criteria. Ahmedabad-Gujarat industrial corridors are driving adoption of subscription-based consumable models rather than capital purchase.
China
Domestic beverage brand owners are specifying modular platforms accommodating rapid format change capabilities for seasonal promotional cycles. GB standards for UV-cured ink chemistries are influencing equipment specification. Yangtze River Delta manufacturing hubs are integrating laser cutting modules for premium cosmetic label applications.
Japan
Precision die supply constraints are driving investment in non-contact cutting technologies for short-run premium applications. METI energy-efficiency standards for drying tunnels are redirecting capital toward energy-curing configurations. Kansai industrial belt converters are maintaining gravure installations for luxury spirits requiring scratch-resistant metallic finishes.
Label Converting Equipment Market Competitive Landscape
Capability concentration sits with specialized narrow-web fabricators; scale advantage sits with diversified equipment conglomerates with global service networks. The vendor base organizes into three tiers: Swiss-German precision engineering specialists, North American hybrid-flexographic innovators, and Asian value-oriented fabricators. Consolidation pressure is intensifying through captive parts logistics expansion and remote diagnostics capability acquisition.
Within the precision engineering tier, Bobst Group SA and Nilpeter exemplify archetypes anchored in pharmaceutical and beverage packaging verticals respectively. Mark Andy Inc. occupies a position representing North American hybrid-configuration specialists serving serialization-mandated markets. These three entities illustrate competitive positioning stratification without exhausting the vendor landscape.
| Leading Market Players |
|---|
| SMAG Graphique |
| A B Graphic International Ltd |
| Spartanics Ltd. |
| Gallus Group |
| Mark Andy Inc. |
| ASHE Converting Equipment |
| Bobst Group SA |
| Nilpeter |
| Daco Solutions Ltd |
| Others |
Supply & Pricing Matrix
Central European hardened tooling suppliers command captive production of precision dies, anchoring margin pools in aftermarket service contracts and constraining converter flexibility during demand surges. This upstream concentration shapes pricing power downstream, where equipment vendors bundle maintenance logistics to capture recurring revenue beyond unit sales.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical converter procurement, locking in serialization-ready digital configurations across multi-year FDA compliance horizons. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-German precision engineering from North American hybrid-flexographic systems and Asian value-oriented fabricators. Cost compression in mid-size Indian food packaging tiers is intensifying because subscription-based consumable models displace capital purchase commitments. Brand owners with in-house converting capacity exhibit lowest price sensitivity; independent converters in emerging markets face acute margin pressure.
Supply Chain Analysis
Hardened steel feedstock for precision dies draws from Germany, Switzerland, and Japan, with photopolymer plate materials sourcing from specialized chemical manufacturers in the United States and Belgium. UV-cured inkjet printing heads, energy-curing drying modules, and water-based adhesive delivery systems constitute critical component dependencies. Single-source vulnerability concentrates in narrow-web flexographic die supply, where limited Central European fabricators control hardened tooling production. Distribution runs through direct OEM sales for large pharmaceutical converters and regional distributor networks serving mid-size food packaging operators in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified technicians trained in hybrid flexographic-digital workflow management are scarce, extending commissioning timelines and constraining equipment deployment velocity. This capability gap favors vendors with captive training infrastructure and remote diagnostics platforms.
For Market Incumbents: Entrench position by expanding captive parts logistics networks to capture aftermarket service revenue from installed flexographic bases threatened by digital displacement. Accelerate backward integration into precision die supply to mitigate Central European supplier concentration risk. Invest in remote performance monitoring capabilities to reduce customer reliance on scarce field technicians.
For New Entrants and Emerging Players: Pursue personalized food packaging micro-segments in India, where variable-data printing for regional cuisine labels remains underpenetrated by established vendors. Target subscription-based consumable models rather than capital sales to align with mid-size converter procurement preferences. Leverage BIS certification partnerships to accelerate market access for imported digital printing modules.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision engineering specialists in the Swiss-German corridor holding narrow-web pharmaceutical and beverage vertical positions. Five-to-ten year viability hinges on regulatory compliance horizon extension through serialization mandate expansion and EU F-Gas phase-down acceleration. Watch FDA guidance updates on track-and-trace implementation deadlines as inflection indicators for replacement cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Network Expansion | Captures recurring revenue from serialization-mandated pharmaceutical installed bases in Germany and the United States. |
| Backward Integration into Precision Die Supply | Mitigates Central European supplier concentration constraining converter flexibility during demand surges. |
| Remote Diagnostics Platform Deployment | Reduces customer dependence on scarce technicians trained in hybrid flexographic-digital workflows. |
| Subscription-Based Consumable Models | Aligns vendor economics with Indian mid-size converter preference for operational flexibility without capital commitment. |
| CE Marking Harmonization Investment | Accelerates time-to-market for digital printing module upgrades across EU member state pharmaceutical clusters. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with equipment procurement managers at pharmaceutical and food packaging converters, aftermarket service directors at OEMs, and technical training specialists; and secondary validation through SEC filings of listed equipment manufacturers, BIS certification registries for Indian imports, and EU F-Gas Regulation implementation tracking. Bottom-up triangulation across converter capital expenditure disclosures and top-down reconciliation against equipment manufacturer revenue segmentation ensured cross-verification.
Forecast inputs include regulatory compliance horizon modeling, run-length economics by vertical, and technology substitution curves for digital versus flexographic configurations. Segmentation dimensions encompass product type, application vertical, end-user procurement authority, and curing chemistry technology across the analysis window. CAGRs derive from equipment shipment tracking, installed base depreciation schedules, and mandate-driven replacement cycle compression. Industry-specific inputs incorporate FDA serialization timeline updates and EU F-Gas phase-down milestone acceleration.
Macroeconomic conditions sit as an overlay; deviation in capital availability for mid-size converters, energy cost trajectories affecting curing economics, or trade friction in precision die steel would shift the trajectory. Forecasts reflect assumptions around regulatory mandate adherence timelines and technology cost convergence. Material shifts in FDA guidance on track-and-trace implementation or EU F-Gas prohibition enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Tray Loader Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Global Dispensing Systems Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
Retail Press Dispenser Pump Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
PET Preform Machine Market
Packaging Equipment
Global Pack Conveyors Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Bottle-Capping Equipment Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Bagging Equipment Market