
 Flow Wrap Packaging Market | 2026-2036
Flow Wrap Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Wrap Packaging Market Foresight
Food-grade barrier specifications is reorganizing competitive dynamics across the flow wrap packaging value chain. Amcor PLC leverages its integrated film-to-package manufacturing footprint to sustain premium barrier grades for protein and dairy applications. Huhtamaki anchors European bakery demand through specialized heat-sealable paper-based flow wrap lines. Mondi PLC differentiates via kraft-polymer hybrid structures that occupy the fast-growing compostable packaging niche.
Flow wrap packaging is a form-fill-seal process where a single continuous web of flexible material—typically polyethylene, polypropylene, or laminated structures with thicknesses between 20 and 80 microns—is wrapped around a product and sealed longitudinally and transversely to form a tight, pillow-style enclosure. The process operates at speeds exceeding 300 packages per minute on rotary jaw systems, making it the dominant format for high-velocity food, pharmaceutical, and consumer goods lines. Horizontal flow wrap dominates confectionery and bakery applications where product stability and presentation clarity command priority, while vertical flow wrap configurations lead in pharmaceutical blister alternatives and hardware kit packaging where gravity-fed product insertion improves throughput. Laminates capture the highest margin pools due to their oxygen and moisture barrier performance, though polyethylene sustains the largest volume position across cost-sensitive snack and frozen bread categories.
FDA food contact substance notifications govern barrier additive approvals in the United States, while EFSA and REACH compliance in Europe restrict certain phthalate plasticizers and mandate recyclability disclosures under the EU Green Deal framework. These layered requirements are forcing converters to validate alternative sealant chemistries and document material provenance across multi-tier supply chains. Stakeholders must monitor how extended producer responsibility schemes and emerging state-level packaging taxes reshape total cost of ownership calculations for brand owners evaluating format transitions.
Market Dynamics
Europe's F-Gas Regulation is forcing converters to abandon hydrofluorocarbon-based sealing systems and validate lower-carbon alternatives across multi-tier supply chains. This single mandate is redrawing equipment procurement criteria and film specification standards simultaneously.
Growth Catalysts
- Extended Producer Responsibility schemes:Germany's packaging ordinance mandates recyclability disclosures, creating certified demand for mono-material flow wrap structures.
- Bakery chain expansion:Industrial bakeries in France and Italy are converting pastry lines to flow wrap for shelf-life extension without preservatives.
- Barrier film innovation:EVOH and nylon coextrusion advances enable protein packaging with 12-month oxygen protection, opening chilled meat applications.
Market Restraints
- Resin supply concentration:Polypropylene feedstock dependence on Rotterdam-Antwerp refining clusters creates price volatility exposure.
- Sealing technology transition costs:Ultrasonic and hot-air sealing systems require 40-60% higher capital outlay than conventional hot-jaw equipment.
- Compostable film performance gaps:PLA-based structures fail moisture barrier tests above 65% relative humidity, limiting snack applications.
Strategic Opportunities
- Pharmaceutical blister alternatives:Cold-seal flow wrap for unit-dose medications addresses DEA tamper-evidence requirements in the United States.
- India's organized retail growth:Modern trade expansion in Mumbai and Delhi NCR creates first-mover advantage for pre-made sandwich and wrap packaging.
- Digital printing convergence:HP Indigo and Xeikon systems enable lot-specific coding without plate changes, collapsing SKU proliferation costs.
Industry Challenges
- Multi-layer delamination certification:RecyClass and How2Recycle approvals require 18-24 month validation timelines for novel film structures.
- Retrofit integration complexity:Legacy horizontal form-fill-seal lines from the 2010-2015 vintage lack servo precision for ultrathin 20-micron films.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Wrap Packaging Market |
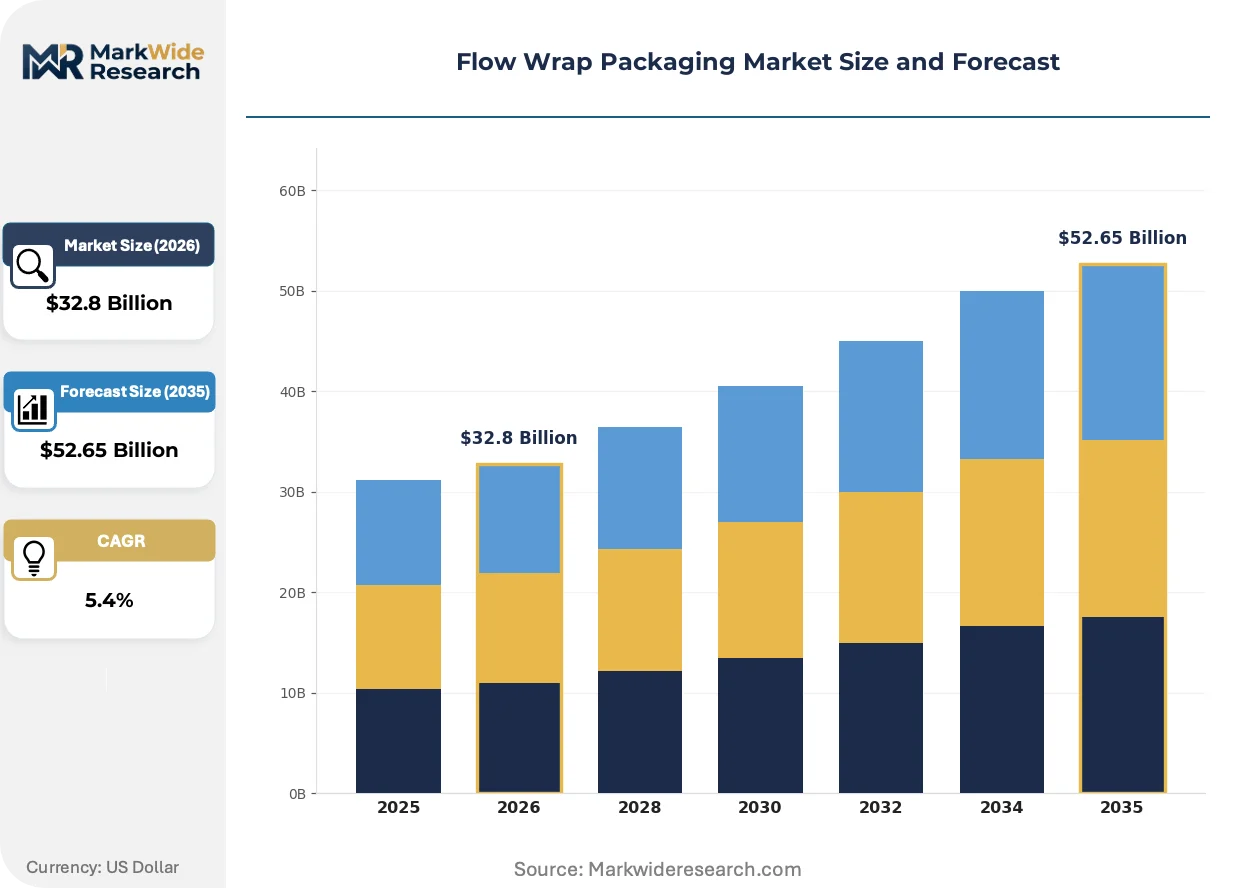
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Flow Wrap, Vertical Flow Wrap, Rotary Flow Wrap, Lap Seal Flow Wrap, Pillow Wrap Material: Polyethylene, Polypropylene, Cellophane, Polyester, Aluminum Foil, Laminates Application: Confectionery, Bakery, Pharmaceuticals, Electronics, Hardware, Personal Care End User: Food Producers, Drug Manufacturers, Electronics OEMs, Hardware Suppliers, Cosmetic Brands |
| Companies Covered | Amcor PLC, Huhtamaki, Constantia Flexibles Group, Sonoco Products Company, Winpak Ltd, Billerud AB, Mondi PLC, Sealed Air, ePac Holdings, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Wrap Packaging Market Shifts & Advancements
Active and intelligent packaging integration is redefining value capture in flow wrap applications. The convergence of sensor technology, sustainable materials, and regulatory disclosure requirements is creating new competitive differentiation vectors.
Mono-material polyethylene structures with enhanced EVOH barrier layers are fragmenting the traditional laminate market. Snack manufacturers in Spain and Poland are adopting these films at pilot scale for 2025 retail launches. The technology is fragmenting converter margins by collapsing the premium barrier tier into standard-grade pricing.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from bakery flow wrap. The regulation forces reformulation of heat-sealable papers used across Northern European sandwich chains. Protein and pastry segments are responding with silicon dioxide and clay-based barrier coatings that require new sealing temperature protocols.
Direct-store-delivery bakeries are consolidating purchasing through cooperative buying groups rather than individual plant negotiations. This channel compression is squeezing regional converter margins while favoring national suppliers with certified food-grade barrier specifications. The shift is most visible in Germany's Mittelstand bakery sector around Stuttgart and Nuremberg.
Flow Wrap Packaging Market Segmentation
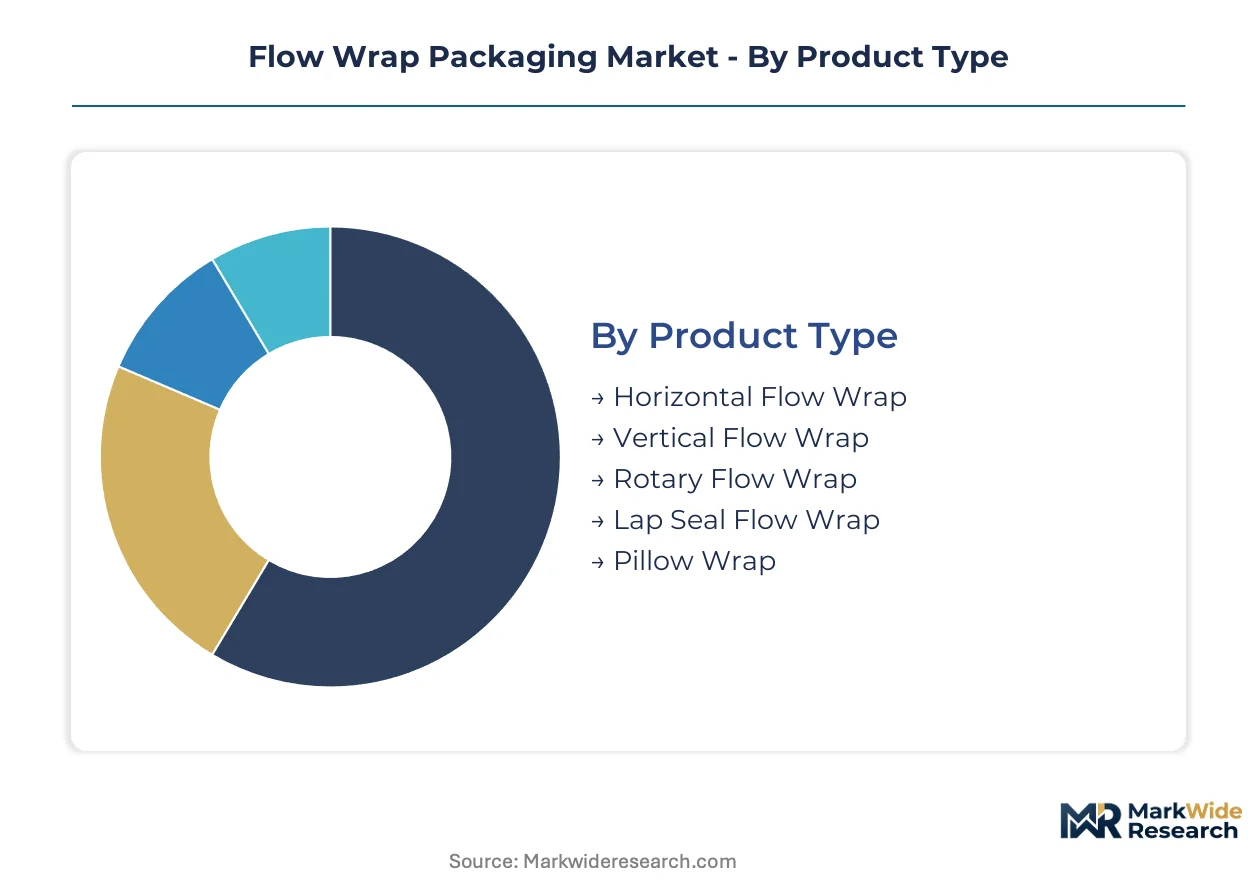
Flow wrap packaging segmentation reveals how equipment configuration, material chemistry, and end-use requirements intersect to determine procurement patterns across industrial buyers. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape vendor selection criteria.
Product Type:
Horizontal configurations dominate bakery and confectionery channels where product presentation and seal integrity command premium positioning, while vertical systems flow through pharmaceutical and hardware distribution networks requiring gravity-fed insertion protocols.
- Horizontal Flow Wrap:Rotary jaw systems operate at 300+ packages per minute using 20-80 micron films for confectionery and bakery applications. Germany's Mittelstand bakery sector around Stuttgart sources these systems for extended shelf-life bread lines under EU Green Deal recyclability mandates.
- Vertical Flow Wrap:Gravity-fed configurations excel in pharmaceutical blister alternatives and hardware kit packaging. Cold-seal variants address DEA tamper-evidence requirements for unit-dose medications in United States distribution channels.
- Rotary Flow Wrap:High-speed continuous motion systems serve frozen bread and snack categories where throughput maximization outweighs format flexibility.
- Lap Seal Flow Wrap:Overlapping longitudinal seals reduce material consumption by 8-12% versus fin seals, attracting cost-sensitive frozen food processors.
- Pillow Wrap:Basic three-side-seal configuration dominates hardware and bulk confectionery where barrier performance requirements remain minimal.
Horizontal Flow Wrap dominates installed base. Vertical Flow Wrap is where expansion concentrates.
Material:
Cost tier stratification separates commodity resins from engineered barrier structures, with mono-material grades gaining certified status under Germany's packaging ordinance while laminates retain protein and dairy applications.
- Polyethylene:Linear low-density grades sustain the largest volume position across snack and frozen bread categories. Mono-material PE structures with enhanced EVOH barrier layers are fragmenting traditional laminate markets in Spain and Poland pilot programs.
- Polypropylene:Biaxially oriented films deliver clarity and stiffness for confectionery presentation. Feedstock dependence on Rotterdam-Antwerp refining clusters creates price volatility exposure for converters.
- Cellophane:Regenerated cellulose films serve premium confectionery where biodegradability certifications support brand positioning.
- Polyester:Metallized PET structures provide intermediate barrier performance for dried fruit and nut applications.
- Aluminum Foil:Ultra-high barrier laminates preserve coffee and pharmaceutical stability where oxygen transmission rates below 0.01 cc/m2/day are mandatory.
- Laminates:Multi-layer coextrusions with EVOH and nylon enable 12-month oxygen protection for chilled meat applications, though RecyClass approval requires 18-24 month validation timelines.
Polyethylene commands volume leadership. Laminates capture margin concentration.
Application:
End-use performance requirements dictate sealing technology selection, with bakery and confectionery channels prioritizing heat-sealable paper aesthetics while pharmaceutical applications demand cold-seal tamper evidence.
- Confectionery:Horizontal flow wrap with metallized films and cold-seal adhesives preserves chocolate bloom resistance. France's industrial bakeries are converting pastry lines to flow wrap for shelf-life extension without preservatives.
- Bakery:Heat-sealable paper-based structures face REACH Annex XVII reformulation pressure as PFAS grease-resistant coatings phase out. Silicon dioxide and clay-based barrier coatings require new sealing temperature protocols.
- Pharmaceuticals:Unit-dose cold-seal flow wrap addresses DEA requirements in United States distribution. EMA compliance for barrier additive approvals governs European market entry.
- Electronics:Anti-static films with controlled moisture vapor transmission rates protect semiconductor components during Asian manufacturing hub distribution.
- Hardware:Heavy-gauge polyethylene pillow wraps with gusseted bottoms accommodate irregular tool geometries through hardware retail channels.
- Personal Care:High-clarity films with registered lot coding support cosmetic brand authentication requirements.
Bakery and Confectionery anchor current installed base. Pharmaceuticals is climbing the fastest.
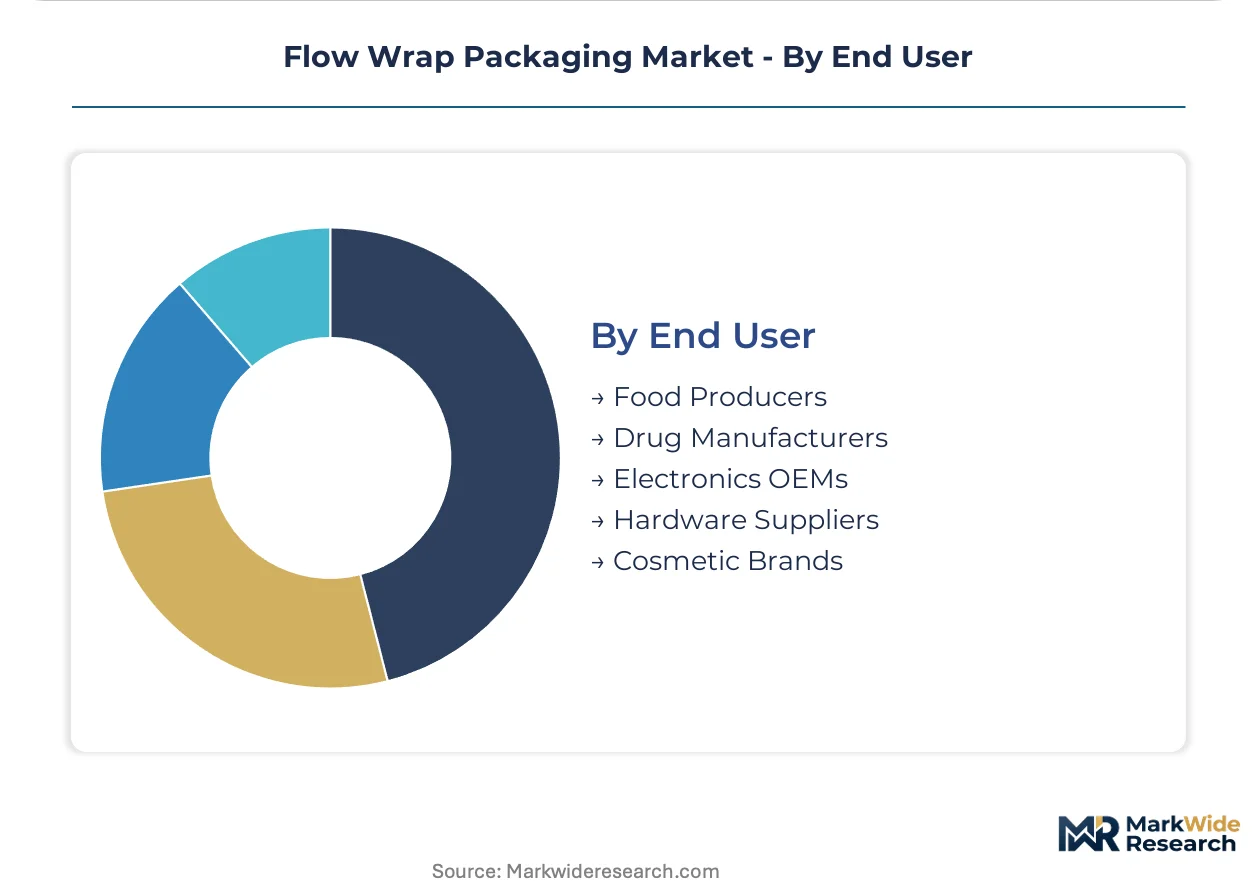
End User:
Procurement consolidation patterns separate fragmented regional food producers from centralized electronics OEMs, with cooperative buying groups emerging among direct-store-delivery bakeries.
- Food Producers:Industrial bakeries in France, Italy, and Germany's Munich-Stuttgart corridor drive demand for certified food-grade barrier specifications. Cooperative purchasing through buying groups squeezes regional converter margins.
- Drug Manufacturers:Large pharmaceutical OEMs validate cold-seal flow wrap for DEA-compliant unit-dose distribution. FDA food contact substance notifications govern barrier additive approvals in United States markets.
- Electronics OEMs:Semiconductor and component manufacturers specify anti-static films with precise moisture vapor transmission control for cleanroom-compatible packaging.
- Hardware Suppliers:Tool and fastener distributors prioritize puncture resistance and load stability over barrier performance in warehouse club distribution.
- Cosmetic Brands:Premium positioning demands high-clarity films with digital printing compatibility for lot-specific authentication codes.
Food Producers dominate segment volume. Drug Manufacturers is where specification tightening concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters supply barrier film technologies to France's industrial bakery sector, creating a cross-border value chain that channels specialized flow wrap equipment through the Munich-Stuttgart corridor toward Paris and Lyon manufacturing hubs.
Germany
Industrial bakeries in Bavaria and Baden-Württemberg drive demand for extended shelf-life bread packaging under the national packaging ordinance. ECHA's REACH Annex XVII restrictions on PFAS grease-resistant coatings force reformulation of heat-sealable paper structures. The Stuttgart-Nuremberg Mittelstand bakery belt concentrates cooperative purchasing groups that squeeze regional converter margins.
France
Paris-based industrial bakeries convert pastry lines to flow wrap systems for preservative-free shelf-life extension. The EU Green Deal recyclability mandates require certified mono-material structures for retail distribution. The Lyon-Rhône-Alpes food processing cluster anchors equipment procurement for high-velocity confectionery lines.
United States
Pharmaceutical OEMs validate cold-seal flow wrap for DEA-compliant unit-dose medication distribution. FDA food contact substance notifications govern barrier additive approvals for protein and dairy applications. The New Jersey-Pennsylvania pharmaceutical corridor concentrates demand for tamper-evident packaging technologies.
India
Mumbai and Delhi NCR modern trade expansion creates first-mover opportunities for pre-made sandwich and wrap packaging. FSSAI food-grade specifications mandate certified barrier films for organized retail channels. The Maharashtra-Gujarat industrial belt attracts flow wrap equipment investments from European technology licensors.
Spain
Snack manufacturers in Catalonia pilot mono-material polyethylene structures with enhanced EVOH barriers for 2025 retail launches. Spain's national packaging registry enforces extended producer responsibility disclosures for recyclability certification. The Barcelona packaging technology cluster supports converter migration from multi-layer laminates to certified mono-material grades.
Flow Wrap Packaging Market Competitive Landscape
Listed leaders compete with private specialists across film manufacturing and equipment fabrication, producing a tiered structure where scale-driven multinational converters hold premium barrier segments while regional specialists capture cost-sensitive bakery and snack categories. Three archetypes dominate: integrated film-to-package manufacturers with captive resin operations, specialized paper-based converters serving European sustainability mandates, and digital-native flexible packaging platforms disrupting short-run production economics. Capacity expansion and strategic technology licensing represent the dominant competitive moves, with players securing exclusive regional distribution rights for next-generation sealing systems.
Within the integrated converter tier, Amcor PLC and Mondi PLC exemplify multinational scale positions anchored across multiple continents, while Huhtamaki occupies a specialized niche in heat-sealable paper-based flow wrap technologies. These three entities represent distinct strategic postures: Australian-originated global film manufacturing, Anglo-Austrian kraft-polymer hybrid innovation, and Finnish paper-to-packaging specialization serving European bakery demand. Their collective presence illustrates how geographic origin and material expertise stratify competitive positioning in barrier film markets.
| Leading Market Players |
|---|
| Amcor PLC |
| Huhtamaki |
| Constantia Flexibles Group |
| Sonoco Products Company |
| Winpak Ltd |
| Billerud AB |
| Mondi PLC |
| Sealed Air |
| ePac Holdings, LLC |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German industrial bakeries and film converters lock in polypropylene supply access while fixing price visibility for 18-24 month equipment procurement cycles under EU Green Deal recyclability mandates.
Pricing Analysis
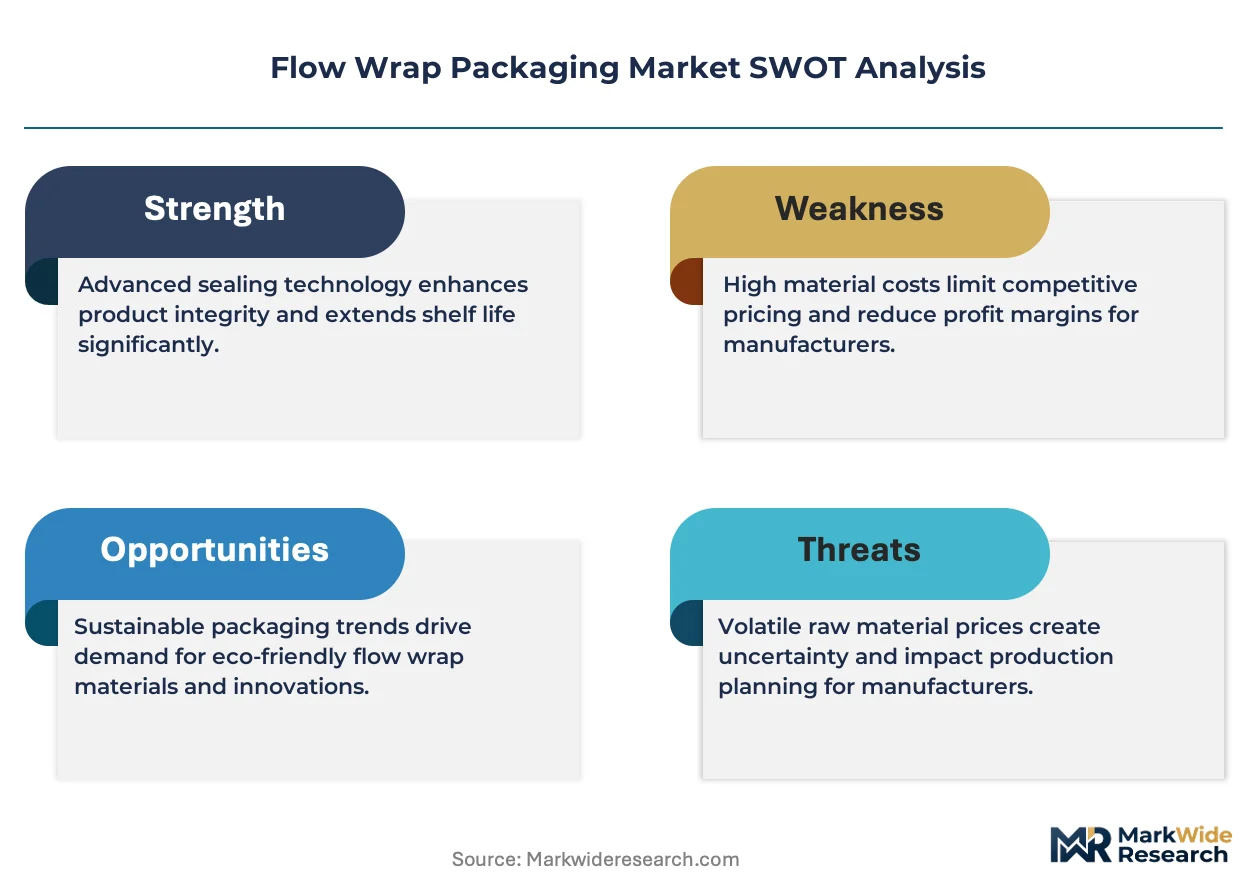
Next-generation ultrasonic sealing systems command 40-60% capital premiums over conventional hot-jaw equipment, collapsing the technology-generation pricing gap that previously separated premium from standard tiers. Three-tier pricing structure across certified mono-material, multi-layer laminates, and commodity polyethylene grades reflects RecyClass certification status and barrier performance tiers. Pricing pressure stems from cooperative buying groups in Germany's Mittelstand bakery belt squeezing regional converter margins. Frozen bread processors exhibit highest price sensitivity due to thin operating margins, while pharmaceutical OEMs accept premium positioning for DEA-compliant cold-seal configurations.
Supply Chain Analysis
Rotterdam-Antwerp refining clusters constitute a chokepoint for polypropylene feedstock, tethering European converter operations to Benelux petrochemical output. Raw material flows draw from Saudi Arabian ethylene sources, German propylene derivatives, and Belgian polymerization capacity. Single-source vulnerability concentrates in biaxially oriented polypropylene film production where three multinational converters control 70% of certified food-grade supply. Distribution runs through converter-to-brand direct contracts for high-volume bakery chains, supplemented by regional distributors serving fragmented hardware and personal care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flow wrap packaging incumbents face substitution pressure from rigid tray alternatives in premium protein applications, requiring defensive repositioning around barrier performance and sustainability certification.
For Market Incumbents: Compound barrier film innovation investments to defend against tray-to-flow-wrap format substitution in chilled meat applications. Prioritize backward integration into EVOH coextrusion capacity to secure oxygen barrier supply chains. Pursue RecyClass certification for mono-material structures ahead of Germany's packaging ordinance enforcement deadlines. For New Entrants and Emerging Players: RecyClass fast-track certification programs offer entry pathways into Spain's snack manufacturer pilot programs for 2025 retail launches. Target India's Mumbai-Delhi NCR modern trade expansion where FSSAI compliance creates first-mover barriers for established European players. Lead with digital printing-enabled short-run capabilities to capture SKU proliferation demand from direct-store-delivery bakeries. For Investors and Strategic Acquirers: Regional paper-to-film converters with captive heat-sealable coating capabilities present acquisition targets as REACH Annex XVII PFAS restrictions force incumbent reformulation cycles. Long-term viability hinges on material science differentiation rather than equipment fabrication scale. Monitor ECHA regulatory drafting timelines as inflection signals for barrier coating technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Certification Investment | RecyClass approval unlocks German bakery cooperative purchasing compliance under EU Green Deal mandates. |
| Ultrasonic Sealing Technology Licensing | F-Gas Regulation compliance positions converters for European equipment replacement cycles. |
| Digital Printing Platform Integration | HP Indigo systems collapse SKU proliferation costs for direct-store-delivery bakery consolidation. |
| Barrier Film Co-Development Partnerships | EVOH-nylon advances enable 12-month oxygen protection for chilled meat applications. |
| India Manufacturing Footprint Establishment | Maharashtra-Gujarat industrial belt proximity captures organized retail growth in Mumbai and Delhi NCR. |
Research Methodology
A spread of perspectives from film plant managers, bakery procurement leads at cooperative buying groups, sealing equipment engineers, and regulatory affairs specialists at ECHA converged on the working assumptions. Primary interview insights combined with secondary validation from EU packaging registry filings, German packaging ordinance compliance databases, and SEC disclosures from listed converters. Bottom-up demand modeling across bakery, confectionery, and pharmaceutical applications triangulated against top-down resin consumption data from petrochemical trade associations.
Segmentation dimensions modeled include equipment configuration, material chemistry tier, end-use application, and geographic regulatory cluster across the analysis window. CAGRs were derived from installed base growth rates, equipment replacement cycles, and format conversion trends in bakery and pharmaceutical channels. Forecast inputs incorporated F-Gas Regulation implementation timelines and extended producer responsibility scheme expansion patterns.
Decision-makers should treat outputs as directional under assumptions of steady EU regulatory enforcement and resin supply stability; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as REACH Annex XVII restriction scopes and India FSSAI enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Plastic Waste Sorting Equipment Market
Packaging Equipment
Hang Tag Applicators Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Filling Equipment Market
Packaging Equipment
Strapping Equipment Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Laser Coding Equipment Market