
 Burnisher Market | 2026-2036
Burnisher Market Size, Share, and Industry Trends Forecast 2026-2036
Burnisher Market Analysis
The EU Green Deal is recalibrating equipment procurement criteria across European commercial cleaning fleets. Tennant leverages its battery-electric platform to capture sustainability-driven retrofit demand. Nilfisk anchors its position through R&D intensity in autonomous floor-care systems. Clarke competes on manufacturing scale in propane-to-electric conversion programs.
A burnisher is a rotary floor machine employing high-speed pads to polish hard surfaces through friction-induced surface refinement. Units operate at 1500–2500 RPM with pad pressures calibrated to substrate hardness, producing specular gloss on concrete, terrazzo, and vinyl composite tile. Floor burnishers dominate installed base due to entrenched replacement cycles in retail and logistics facilities. Battery-operated power sources represent the fastest-expanding segment as lithium-ion pack costs compress total cost of ownership calculations. Commercial cleaning end users concentrate margin pools through multi-year service contracts bundling equipment and consumables.
EPA certifies propane burnishers under nonroad spark-ignition engine standards, while OSHA governs operator exposure to noise and vibration thresholds. The EU F-Gas Regulation indirectly shapes electric alternatives by restricting fluorinated greenhouse gases in related HVAC-linked building services. Stakeholders must monitor battery chemistry disclosure rules and right-to-repair legislation as these frameworks determine aftermarket revenue accessibility and product design liability.
Market Dynamics
The battery-electric transition is compressing replacement cycles for propane burnishers as facility managers recalculate total cost of ownership against tightening EPA emissions certification timelines.
Growth Catalysts
- Facility Management Outsourcing:Third-party cleaning contractors in the United States bundle equipment procurement into multi-year service agreements, accelerating refresh rates for aging propane fleets.
- EU Green Deal Procurement Criteria:European commercial cleaning fleets face mandatory sustainability scoring that favors battery-electric platforms over combustion alternatives in public tenders.
- Lithium-Ion Pack Cost Compression:Falling battery prices enable payback periods under three years for electric burnishers, shifting procurement calculations away from upfront capital constraints.
Market Restraints
- Propane Engine Certification Friction:EPA nonroad spark-ignition standards impose testing costs that disproportionately burden smaller equipment manufacturers lacking captive compliance teams.
- Critical Mineral Supply Concentration:Cobalt and lithium refining capacity clusters in China, exposing battery supply chains to geopolitical disruption and price volatility.
- Concrete Substrate Wear Limits:High-RPM burnishing degrades unsealed concrete faster than anticipated, constraining application scope in warehouse and logistics facilities.
Strategic Opportunities
- Autonomous Floor-Care Convergence:Integration of LiDAR navigation with rotary burnishing heads creates unmanned overnight polishing capacity in retail and healthcare settings.
- Right-to-Repair Legislative Tailwinds:Proposed state-level repair access mandates in the United States would unlock aftermarket battery and pad replacement revenue streams previously captured by OEMs.
- India Commercial Real Estate Expansion:Shopping mall and airport construction in Mumbai and Bangalore generates first-time equipment demand from facility management startups lacking legacy propane infrastructure.
Industry Challenges
- Technician Electrification Skill Gap:Field service teams trained on small-engine diagnostics lack certification for high-voltage battery system troubleshooting and thermal runaway containment.
- OSHA Noise Threshold Compliance:High-speed pad operation generates decibel levels approaching permissible exposure limits, requiring engineering controls that add cost and weight.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burnisher Market |
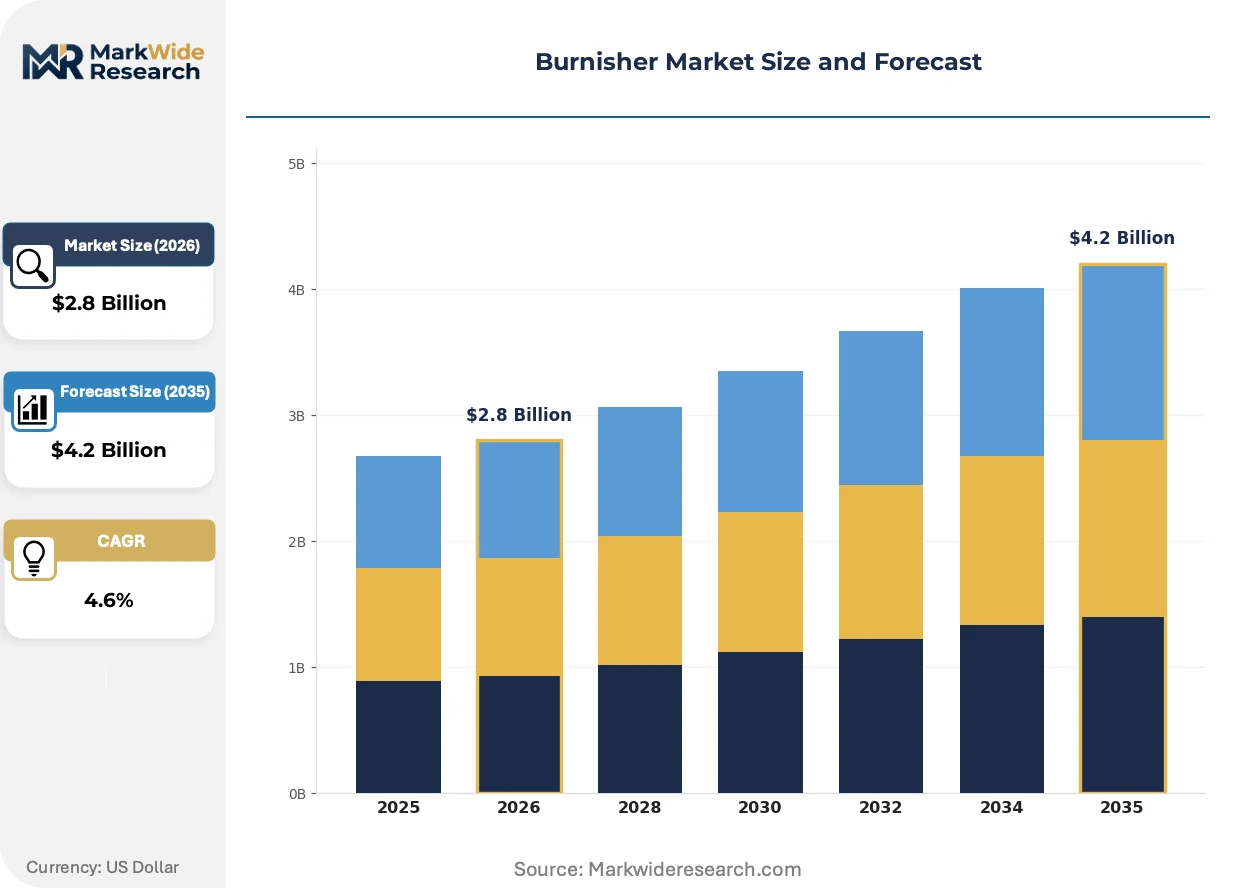
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Burnishers, Handheld Burnishers, Ride-on Burnishers, Auto Scrubbers Power Source: Electric, Propane, Battery-operated, Hybrid End User: Commercial Cleaning, Industrial Facilities, Healthcare Institutions, Educational Facilities Application: Hard Floors, Carpet Cleaning, Polishing, Maintenance |
| Companies Covered | Tennant, Nilfisk, Metabo, Hilti, DeWALT, Milwaukee, Clarke, Nobles, FLEX GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burnisher Market Emerging Trajectories
Battery-electric powertrains are overtaking combustion architectures across commercial cleaning fleets, while regulatory pressure and procurement model evolution reshape competitive positioning.
Lithium-ion battery systems are overtaking lead-acid and propane alternatives as the dominant power source for high-speed floor burnishers. Large retail chains and third-party facility managers are adopting these platforms at accelerating rates to eliminate fuel storage liability and reduce ventilation requirements. This transition is overtaking traditional distribution channels that bundled propane tank refills with equipment sales, compressing aftermarket revenue for legacy service networks.
EPA nonroad spark-ignition engine standards are tightening certification timelines for propane-powered equipment, forcing manufacturers to invest in emissions testing infrastructure or abandon combustion product lines. The industrial consequence is a narrowing supplier base as smaller OEMs exit rather than absorb compliance costs. Commercial cleaning contractors in California and the Northeast are responding by accelerating electric fleet conversions ahead of anticipated state-level zero-emission mandates.
Equipment-as-a-service contracting is displacing capital purchase models among multi-site retail operators seeking to offload maintenance and obsolescence risk. Third-party lessors are capturing margin pools previously held by distributors by bundling machines, consumables, and predictive maintenance into per-square-foot pricing. This shift is most visible in United States grocery and big-box retail chains where CFOs prioritize operational expenditure treatment over balance-sheet asset ownership.
Burnisher Market Segmentation
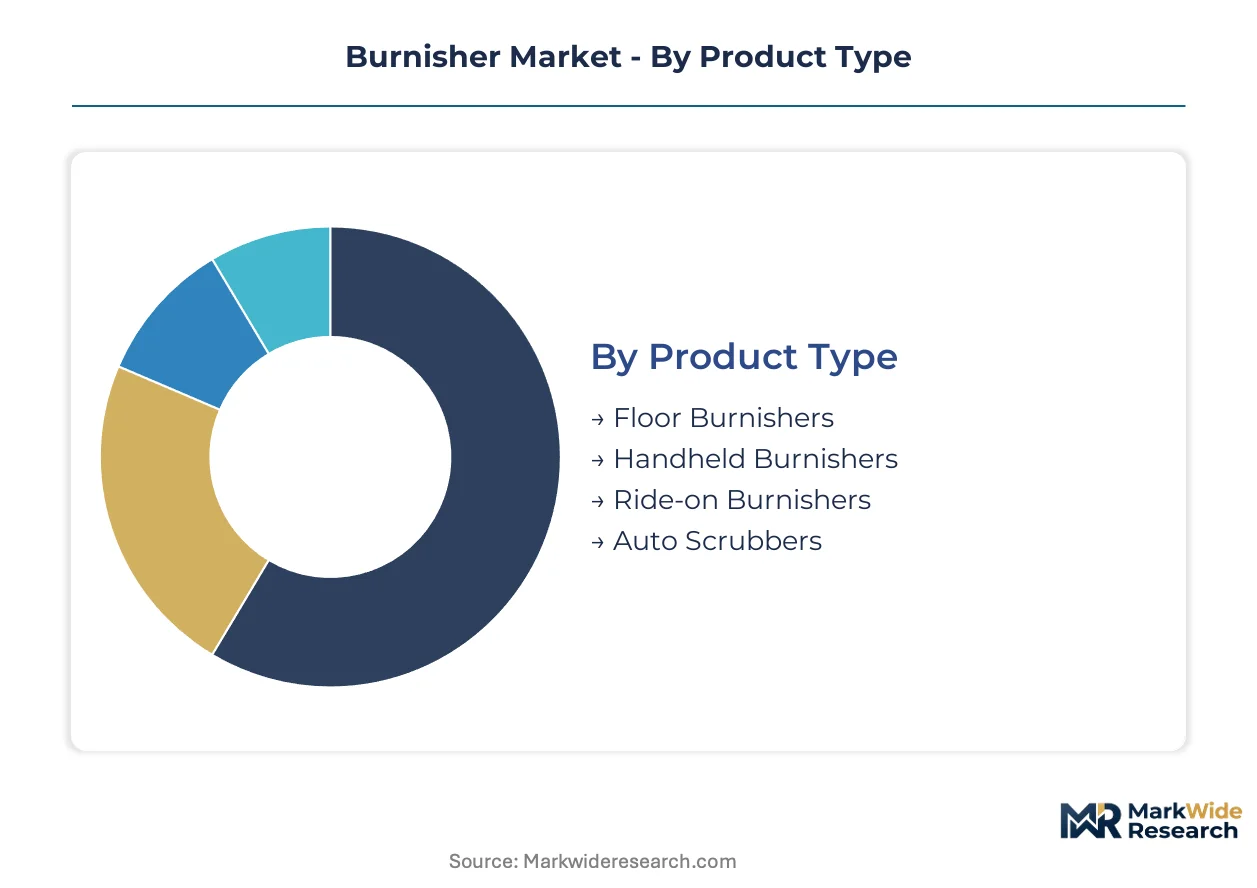
Equipment replacement cycles in commercial cleaning diverge sharply across power technologies and facility types. Procurement managers segment burnisher portfolios to align capital deployment with substrate requirements, ventilation constraints, and labor availability.
Product Type:
Upgrade trajectories favor machines that compress labor hours per square meter while extending pad life through programmable pressure modulation.
- Floor Burnishers:Rotary machines dominate installed bases in retail and logistics facilities with 1500–2500 RPM pad speeds calibrated to concrete hardness. Third-party facility managers in the United States bundle these into multi-year service contracts that accelerate refresh cycles for aging propane fleets.
- Ride-on Burnishers:Operator-positioned units reduce labor exposure in airport terminals and distribution centers exceeding 50,000 square meters. Demand concentrates where OSHA noise thresholds and worker compensation premiums make walk-behind alternatives uneconomical.
- Handheld Burnishers:Compact units serve edge polishing and confined-space maintenance in healthcare corridors and elevator lobbies.
- Auto Scrubbers:Combined scrub-burnish systems capture integrated procurement budgets from facilities seeking single-vendor accountability.
Floor burnishers sit at the top of the volume ranking, with ride-on burnishers climbing the fastest.
Power Source:
Cost tier stratification separates upfront capital requirements from lifetime fuel and maintenance exposures.
- Battery-operated:Lithium-ion packs eliminate propane storage liability and ventilation infrastructure in underground parking and enclosed retail. Falling cell prices compress total cost of ownership payback periods under three years for electric burnishers, shifting procurement calculations away from capital constraints.
- Propane:Combustion architectures retain footholds in facilities lacking electrical infrastructure upgrades or operating in extreme cold where battery performance degrades. EPA nonroad spark-ignition standards impose testing costs that disproportionately burden smaller equipment manufacturers lacking captive compliance teams.
- Electric:Corded units persist in fixed-route applications with reliable outlet density, particularly in educational facilities with predictable cleaning schedules.
- Hybrid:Dual-power configurations serve transitional fleets hedging against grid reliability and battery supply disruption.
Battery-operated systems sit at the top of the volume ranking, with hybrid configurations expanding most quickly among risk-averse procurement committees.
End User:
Application maturity determines margin capture through consumables bundling versus equipment-only transactions.
- Commercial Cleaning:Third-party contractors consolidate margin pools through multi-year service agreements bundling machines, pads, and predictive maintenance into per-square-foot pricing. This shift is most visible in United States grocery and big-box retail chains where CFOs prioritize operational expenditure treatment.
- Healthcare Institutions:Infection control protocols demand specular gloss standards on vinyl composite tile that only high-RPM burnishers achieve. Facilities face mandatory sustainability scoring under EU Green Deal procurement criteria that favors battery-electric platforms.
- Industrial Facilities:Warehouse operators balance throughput against concrete substrate wear limits that high-RPM burnishing accelerates.
- Educational Facilities:School districts defer replacement cycles due to capital budget fragmentation across municipal funding cycles.
Commercial cleaning sits at the top of the volume ranking, with healthcare institutions gaining share fastest through infection-control specification tightening.
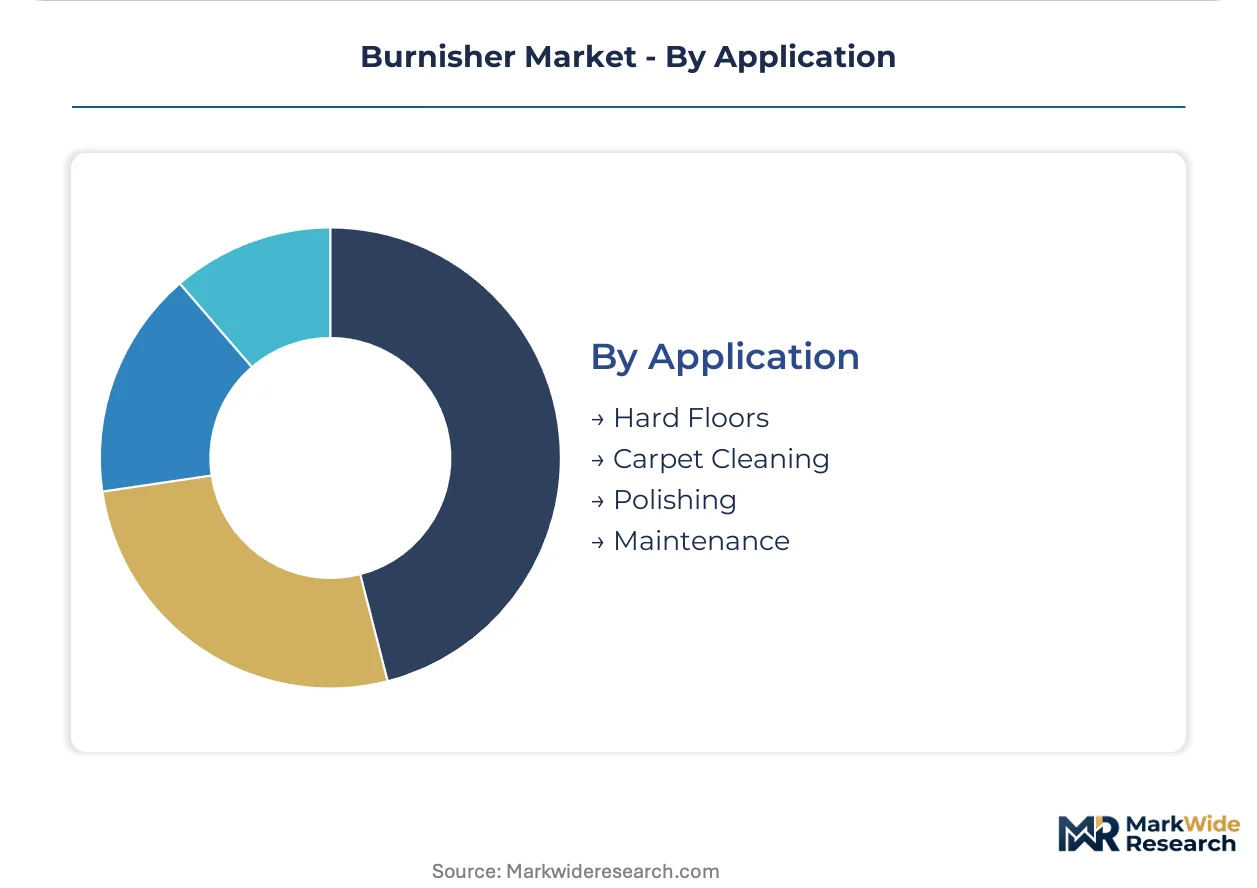
Application:
Geography of demand clusters where hard surface construction outpaces carpet installation in commercial real estate expansion corridors.
- Hard Floors:Concrete, terrazzo, and vinyl composite tile dominate new construction in Indian shopping malls and airport terminals. Battery-electric platforms eliminate fuel storage liability in these densely occupied structures.
- Polishing:Specular gloss maintenance drives replacement frequency in retail environments where brand presentation correlates with foot traffic conversion.
- Maintenance:Preventive programs extend asset life but compress equipment sales velocity compared to reactive replacement.
- Carpet Cleaning:Extraction equipment competes for overlapping capital budgets, though burnishers retain adjacency in hard-floor transition zones.
Hard floor applications sit at the top of the volume ranking, with polishing climbing the fastest among premium retail specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management talent pools concentrate in metropolitan corridors where commercial real estate density sustains specialized equipment procurement teams. These workforce clusters drive divergent adoption timelines across national markets.
United States
Third-party cleaning contractors in Dallas-Fort Worth and Atlanta bundle burnisher procurement into multi-year service agreements. EPA nonroad spark-ignition standards tighten certification timelines for propane-powered equipment. California and New York facility managers accelerate electric fleet conversions ahead of anticipated state-level zero-emission mandates.
Germany
Industrial facility managers in the Ruhr region and Bavaria prioritize ride-on burnishers for warehouse applications exceeding 50,000 square meters. EU Green Deal procurement criteria impose mandatory sustainability scoring on public tenders. Stuttgart-based equipment lessors capture margin pools through bundled machines and predictive maintenance contracts.
China
Shopping mall construction in Shanghai and Shenzhen generates first-time equipment demand from facility management startups. The country's national environmental regulator tightens emissions standards for commercial cleaning equipment in tier-one cities. Pearl River Delta manufacturing clusters produce lithium-ion battery packs that compress electric burnisher total cost of ownership.
India
Airport terminal expansion in Mumbai and Bangalore drives demand for operator-positioned ride-on units. The Bureau of Indian Standards develops certification frameworks for battery-operated commercial cleaning equipment. Delhi-NCR facility management contractors lack legacy propane infrastructure, enabling direct adoption of electric platforms.
Japan
Healthcare institutions in Tokyo and Osaka specify high-RPM burnishers for infection-control gloss standards on vinyl composite tile. METI promotes battery-electric transitions through commercial building energy efficiency programs. Kansai region logistics facilities balance concrete substrate wear limits against throughput requirements.
Burnisher Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the burnisher market structure. The supplier base concentrates around established floor-care equipment specialists with captive distribution networks and integrated battery supply chains. Three archetypes dominate: diversified industrial conglomerates with cleaning equipment divisions, pure-play floor-care specialists, and power tool manufacturers extending into surface maintenance. Competitive moves center on lithium-ion platform standardization and equipment-as-a-service contracting models that displace capital purchase relationships.
Among North American-based specialists, Tennant and Clarke occupy positions within the integrated floor-care archetype, bundling machines with consumables and service contracts. Nilfisk anchors the European specialist tier with R&D intensity in autonomous navigation systems. FLEX GmbH represents German engineering-focused fabrication, sitting within the precision equipment segment where pad pressure modulation and noise reduction engineering differentiate positioning.
| Leading Market Players |
|---|
| Tennant |
| Nilfisk |
| Metabo |
| Hilti |
| DeWALT |
| Milwaukee |
| Clarke |
| Nobles |
| FLEX GmbH |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up cleaning equipment specialists have consolidated regional service networks across the United States, compressing procurement leverage for independent distributors while standardizing lease-rate pricing across multi-site retail contracts. This ownership concentration tightens margin capture on battery pack replacements and predictive maintenance bundles, linking financing structures directly to aftermarket revenue streams.
Pricing Analysis
The bundled-versus-unbundled service split separates capital purchase models from equipment-as-a-service contracting, with the latter commanding premium rates through obsolescence risk transfer. Price differentiation hinges on certification tier under EPA nonroad spark-ignition standards and battery chemistry disclosure grade. Cost compression in lithium-ion cell production is intensifying price competition at the standard tier. Third-party facility managers exhibit highest price sensitivity due to per-square-foot contract economics, while healthcare institutions prioritize infection-control specification compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for battery pack refurbishment and pad remanufacturing are consolidating around third-party lessors seeking to capture circular economy revenue. Manufacturing concentration clusters in China for lithium-ion cells, the United States for precision motor assemblies, and Germany for pressure modulation components. Supply chains draw from cobalt refining capacity, rare earth magnet production, and high-grade aluminum castings. Single-source vulnerability in Chinese cathode material processing exposes margins to geopolitical disruption. Distribution runs through captive OEM service networks and independent janitorial supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where facility management contractors in India bypass legacy propane infrastructure costs that burden retrofit-dependent operators in the United States.
For Market Incumbents: Lock in battery supply agreements with Pearl River Delta manufacturers before regional environmental regulators tighten commercial equipment emissions standards. Secure technician certification programs for high-voltage troubleshooting to close the skill gap threatening service contract renewal rates. Vertical integration into lithium-ion pack assembly hedges against cobalt price volatility. For New Entrants and Emerging Players: Third-party equipment lessors represent the most penetrable channel partner type for autonomous burnisher modules targeting overnight retail polishing contracts. White-space concentrates in Indian airport terminal expansions and European healthcare sustainability retrofit programs. A direct-to-facility-manager sales model bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play floor-care specialists lacking autonomous navigation capabilities relative to diversified industrial conglomerates. Long-term viability favors asset-light designers with captive battery supply chains over capital-heavy manufacturers dependent on combustion product lines. Monitor EPA certification timeline announcements and state-level zero-emission mandate progressions as inflection indicators for electric fleet conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Pearl River Delta cell sourcing compresses electric burnisher total cost of ownership payback periods. |
| Autonomous Navigation Integration | LiDAR-guided overnight polishing unlocks unmanned capacity in OSHA noise-constrained retail environments. |
| Equipment-as-a-Service Launch | Per-square-foot bundling captures CFO preference for operational expenditure treatment in grocery chains. |
| Technician Certification Program | High-voltage battery training closes electrification skill gaps threatening field service contract renewals. |
| Right-to-Repair Compliance | State-level repair access mandates unlock aftermarket battery replacement revenue previously captured by OEMs. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market's facility management contractors and equipment procurement clusters. The approach combines structured interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads alongside secondary validation through SEC 10-K filings, customs trade records, and EPA certification databases. Bottom-up demand modeling triangulates against top-down industry association aggregates.
Granularity-level framing applies product type, power source technology, end-user vertical, and application substrate across the modeling period. CAGRs derive from replacement cycle analysis, regulatory phase-in schedules, and battery cost trajectory assumptions. Industry-specific inputs include EPA nonroad spark-ignition certification timelines and EU Green Deal procurement scoring weights.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium supply chain disruption and right-to-repair legislative adoption. Projections reflect documented assumptions regarding battery chemistry cost curves and facility management outsourcing penetration. Practitioners should monitor EPA certification deadline announcements and cobalt refining capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Rotary Band Heat Sealer Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Linear Net Weighing Machines Market
Packaging Equipment
Packaging Equipment Market
Packaging Equipment
Container Washing System Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Blow Molding Tools Market
Packaging Equipment
Global Pack Conveyors Market
Packaging Equipment
Loose Fill Packaging Systems Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
France Foam Pumps Market