
 Bespoke Dispenser Market | 2026-2036
Bespoke Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Bespoke Dispenser Market Outlook
Modular refill architectures is realigning procurement patterns across hospitality and retail sectors, allowing buyers to unbundle hardware from consumable contracts. Tetra Pak leverages its aseptic packaging heritage to extend dispensing system integration into food-service environments. Aptar Group anchors its position through precision dosing technology leadership in fragrance and personal care applications. Smurfit Kappa competes by embedding sustainable fiber-based housings that respond to corporate sustainability mandates.
A bespoke dispenser denotes a customized dispensing apparatus engineered to deliver measured quantities of liquid, gel, aerosol, or solid products, typically incorporating materials such as borosilicate glass, anodized aluminum, or engineered polymers with tolerances of 0.1 milliliters for dosage accuracy; its primary commercial purpose centers on brand differentiation through controlled consumer interaction with consumable products. Smart dispenser and digital dispenser segments command premium positioning due to IoT-enabled usage analytics and remote monitoring capabilities that reduce service intervals. The hospitality end-user segment concentrates margin pools in luxury properties seeking signature scent programming and touchless hygiene protocols.
The US EPA regulates volatile organic compound emissions from aromatic dispensing systems, while the EU REACH framework governs chemical safety in refill formulations and material substrates. China's SAMR enforces GB standards for electronic components in smart dispenser units, creating compliance thresholds for market entry. Stakeholders must calibrate R&D roadmaps against diverging regional material restrictions and connectivity standards before committing capital to platform designs.
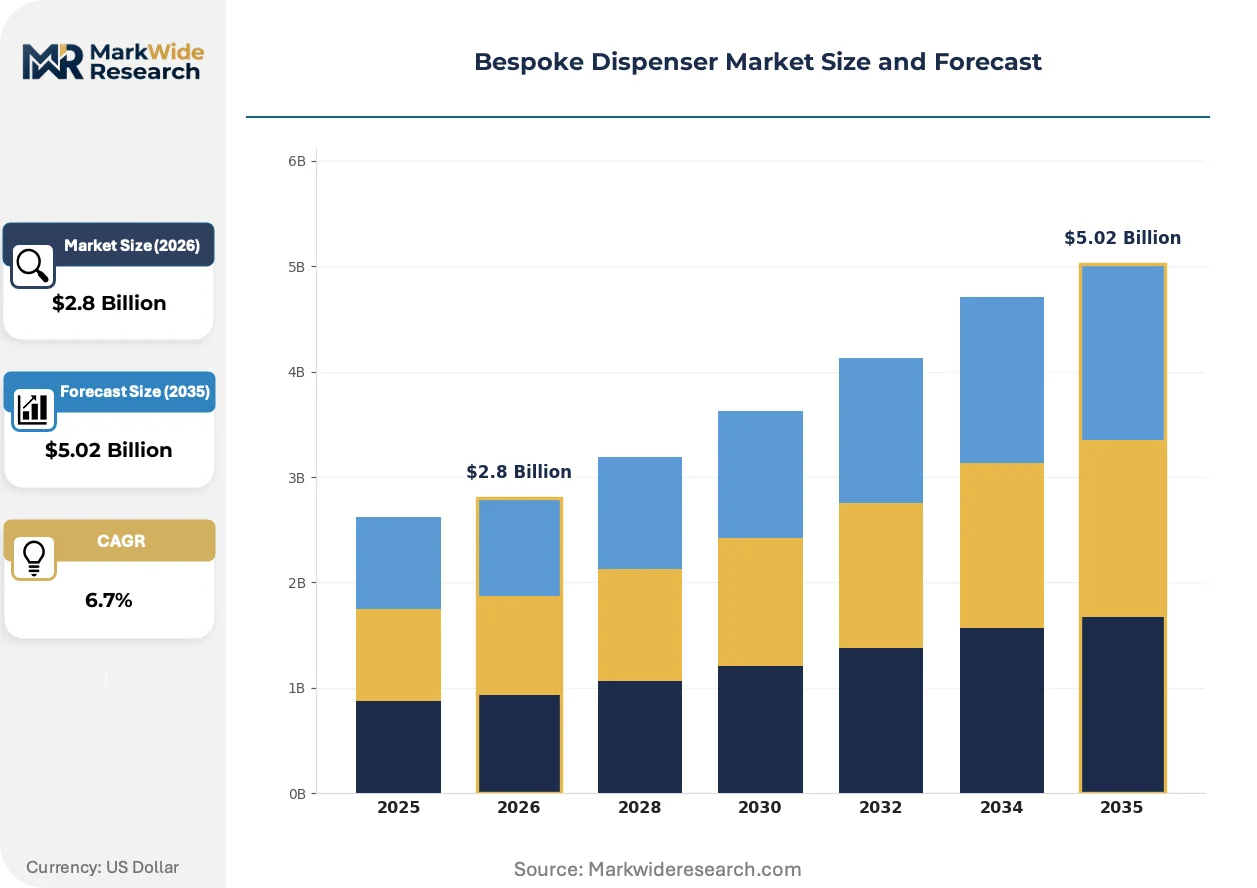
Market Dynamics
Modular refill architectures are fragmenting traditional hardware-consumable bundles across hospitality and retail procurement, forcing manufacturers to unbundle pricing and service contracts while repositioning around recurring revenue streams.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:The regulation mandates circular refill mechanisms, compelling manufacturers to redesign pump systems for material recovery and driving R&D investment in closed-loop architectures.
- Smart dispenser IoT integration:Remote monitoring capabilities reduce service intervals by enabling predictive maintenance, creating pull from luxury hotel chains seeking operational efficiency gains.
- Southeast Asia luxury hospitality expansion:Signature scent programming and touchless hygiene protocols concentrate demand in Bangkok, Singapore, and Jakarta properties competing on experiential differentiation.
Market Restraints
- Engineered polymer input volatility:Specialized polymer feedstock costs fluctuate with petrochemical markets, squeezing margin on precision-molded pump housings and dosing chambers.
- Precision dosing IP concentration:Patent thickets around 0.1-milliliter tolerance mechanisms concentrate in three German and Swiss component suppliers, limiting second-source options.
- REACH chemical compliance friction:The EU framework imposes substance restriction testing timelines that delay new fragrance formulation launches by 8-14 months.
Strategic Opportunities
- China tier-one city premium retail:Shanghai, Beijing, and Shenzhen branded touchpoint investments outpace national averages, creating white space for customizable dispensing at flagship cosmetics counters.
- Food-service aseptic integration:Aseptic packaging heritage from beverage cartons transfers to condiment and sauce dispensing, opening institutional catering and QSR channels.
- Fiber-based housing sustainability mandates:Corporate ESG procurement policies favor molded fiber over virgin plastic, rewarding suppliers with captive pulp molding capabilities.
Industry Challenges
- Multi-standard electronics certification:China's SAMR GB standards for smart dispenser connectivity diverge from FCC and CE frameworks, forcing parallel testing tracks that extend product development cycles.
- Legacy property infrastructure retrofit complexity:Historic hotel properties lack the power and data infrastructure for IoT-enabled units, requiring battery-powered workarounds that compromise functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bespoke Dispenser Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic, Smart Dispenser, Mechanical, Digital Dispenser Material: Glass, Plastic, Metal, Wood End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Tetra Pak, Aptar Group, Smurfit Kappa, DS Smith, Liqui-Box, Simplehuman, Bobrick Washroom Equipment, Kohler Co., Sloan Valve Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bespoke Dispenser Market Strategic Shifts
Digital connectivity and material circularity are converging to redefine how dispensing hardware generates value, shifting competitive advantage from unit economics to data-enabled service relationships and sustainability credentials.
Precision micro-pump technology is consolidating control over dosing accuracy in fragrance and personal care applications. Luxury hospitality buyers specify tolerances of 0.1 milliliters to preserve expensive concentrate formulations. This technical specification is consolidating supplier power around firms with captive precision molding capabilities and metrology expertise.
REACH substance restrictions are reshaping material selection across the EU market. The ECHA framework now governs chemical safety in refill substrates and pump elastomers, forcing reformulation of legacy fragrance carriers. Personal care applications face the steepest compliance burden, with manufacturers accelerating biobased polymer qualification programs.
After-sales service unbundling is fragmenting traditional vendor relationships in the hospitality vertical. Property operators now separate hardware procurement from consumable supply and technical maintenance, awarding contracts to specialized service firms. This pattern is most visible in Dubai and Saudi Arabia, where facility management outsourcing concentrates buying power with third-party operators rather than brand owners.
Bespoke Dispenser Market Segmentation
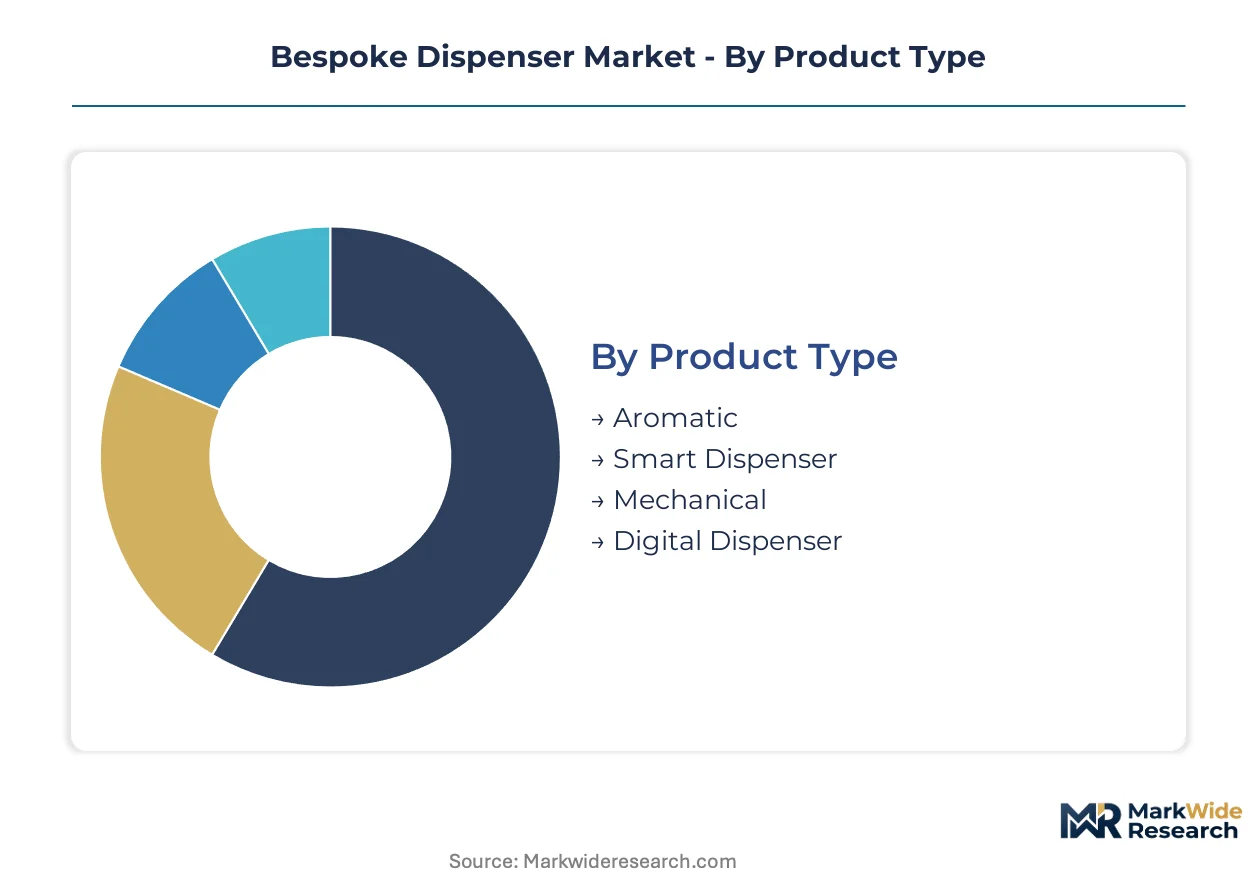
Segmentation in the bespoke dispenser market determines compliance pathways, procurement complexity, and margin architecture. Each dimension carries distinct certification burdens and end-use concentration patterns that reshape competitive positioning.
Product Type:
Certification requirements diverge sharply across this category. Smart and digital dispensers trigger China's SAMR GB standards for electronic components and FCC connectivity mandates in the United States. Aromatic systems face EPA volatile organic compound emission limits. Mechanical units encounter lighter regulatory loads, primarily REACH material safety compliance in Europe.
- Aromatic:Engineered to deliver measured fragrance releases with volatile compound control. Demand concentrates in Southeast Asian luxury hotels where signature scent programming differentiates guest experience. EPA emission thresholds and EU REACH chemical restrictions impose parallel testing tracks that extend development timelines.
- Smart Dispenser:IoT-enabled units with remote monitoring and predictive maintenance capabilities. Procurement concentrates with luxury hospitality chains in Bangkok, Singapore, and Jakarta seeking operational efficiency gains through reduced service intervals. Multi-standard electronics certification across SAMR, FCC, and CE frameworks fragments supplier compliance costs.
- Mechanical:Precision-molded pump systems without electronic components. REACH material compliance governs European market entry.
- Digital Dispenser:Touch-interface units with usage analytics and programmable dosing. China's tier-one city premium retail sector drives specification for branded consumer touchpoints.
Leading the category by volume: Mechanical. Growing fastest: Smart Dispenser.
Material:
Cost tier architecture separates premium specifications from mass-market alternatives. Borosilicate glass and anodized aluminum command three-to-five-fold hardware premiums over engineered polymers. Procurement patterns in hospitality favor metal and glass for visible installations, while industrial applications prioritize plastic durability.
- Glass:Borosilicate formulations deliver chemical inertness and optical clarity for premium fragrance presentation. Luxury hotel properties in Dubai and Saudi Arabia specify glass housings for lobby and spa installations where aesthetic differentiation justifies replacement cost exposure.
- Plastic:Engineered polymers with precision-molded tolerances dominate volume production. REACH substance restrictions and ECHA framework compliance reshape material selection across EU supply chains.
- Metal:Anodized aluminum housings resist corrosion in high-humidity hospitality environments. Corporate ESG procurement policies increasingly favor recycled content verification.
- Wood:Molded fiber and composite variants respond to sustainability mandates in European and North American corporate procurement.
Highest margin capture: Glass. Steepest expansion trajectory: Molded fiber alternatives to virgin plastic.
End User:
Application context determines specification intensity and service relationship structure. Hospitality buyers unbundle hardware, consumable, and maintenance contracts, fragmenting traditional vendor relationships. Residential procurement remains bundled through retail channels with lower technical support expectations.
- Residential:Consumer-grade units with simplified installation and minimal technical support requirements. China's tier-one city apartment developments increasingly specify smart dispensers as standard amenities.
- Commercial:Office and institutional applications prioritizing durability and standardized maintenance protocols. REACH compliance burden concentrates in corporate procurement policies with ESG screening.
- Industrial:Heavy-duty formulations for manufacturing and logistics environments. Metal housings dominate specification for impact resistance.
- Hospitality:Signature scent programming and touchless hygiene protocols drive premium specification. After-sales service unbundling concentrates buying power with third-party facility management operators in Dubai and Saudi Arabia.
Largest absolute spend: Hospitality. Fastest specification upgrade cycle: Residential smart dispenser integration.
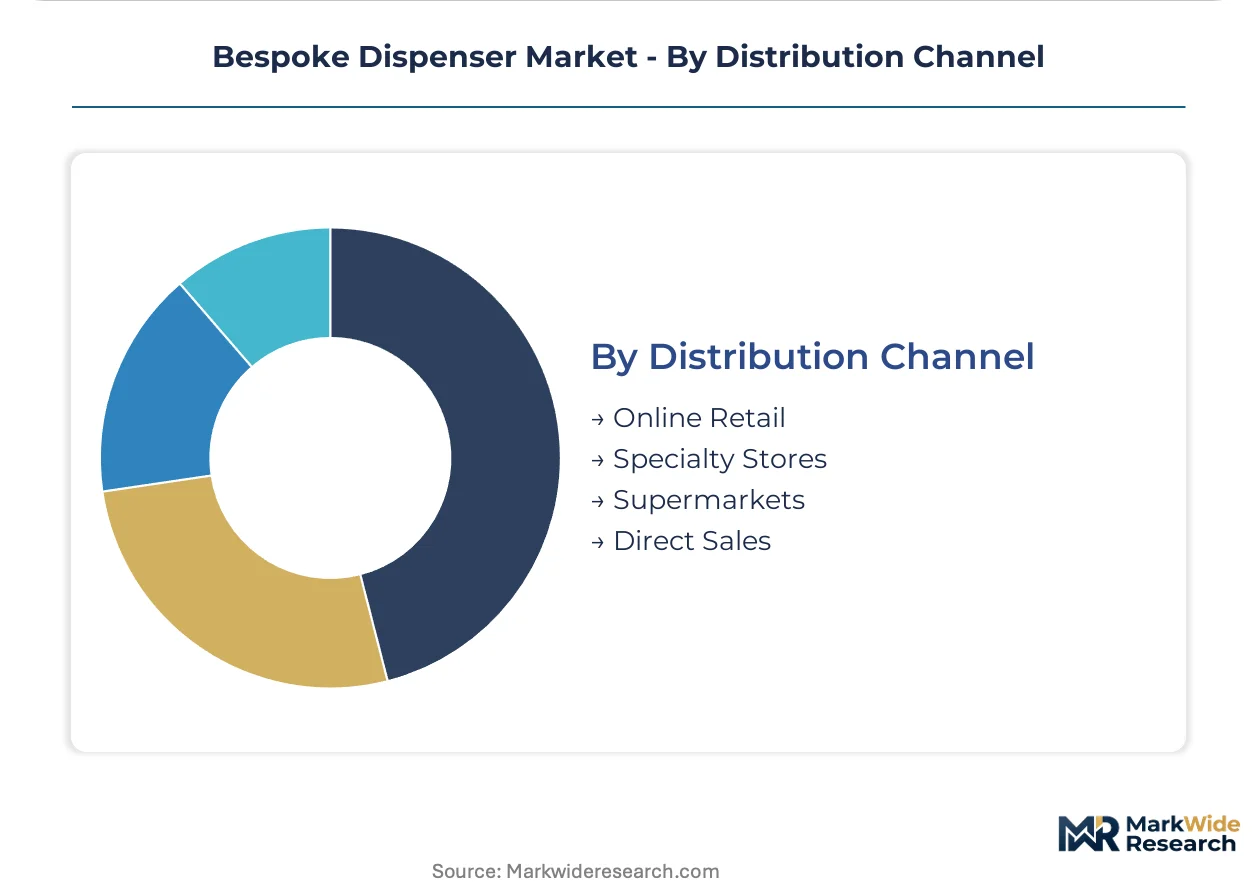
Distribution Channel:
Customer type and purchase scale determine channel economics. Direct sales capture enterprise hospitality contracts with multi-property rollouts. Online retail serves fragmented residential demand with lower service attachment rates.
- Online Retail:E-commerce platforms serving residential and small commercial buyers with standardized SKU fulfillment. China's Alibaba and JD.com ecosystems concentrate domestic volume.
- Specialty Stores:Premium retail counters with demonstration capabilities and consultative selling. Shanghai, Beijing, and Shenzhen flagship cosmetics locations drive branded touchpoint investments.
- Supermarkets:Mass-market channels for replacement units and consumable refills. Limited technical support attachment.
- Direct Sales:Enterprise account management for hospitality and industrial procurement with customized specification and service bundling. Saudi Arabian and UAE facility management outsourcing concentrates contract value with specialized operators.
Dominant by transaction volume: Online Retail. Expanding most quickly: Direct Sales with unbundled service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and Switzerland around precision-molded pump components, while consumption concentrates in China's tier-one cities and Southeast Asian hospitality corridors. This geographic split creates supply chain complexity for brands seeking proximity to both production expertise and end-use demand.
China
Shanghai, Beijing, and Shenzhen drive specification for smart and digital dispensers at flagship cosmetics counters and luxury retail installations. SAMR enforces GB standards for electronic components and connectivity protocols, creating compliance thresholds that filter out non-compliant imports. Yangtze River Delta manufacturing hubs supply precision-molded polymer housings to domestic and export markets.
Germany
Precision dosing IP concentrates around Stuttgart and Munich component suppliers holding patent positions on 0.1-milliliter tolerance mechanisms. KBA and federal environmental regulators enforce REACH substance restrictions on pump elastomers and fragrance carriers. Bavaria-based fabricators supply dosing chambers to European luxury hospitality chains and North American institutional buyers.
United States
EPA volatile organic compound emission limits govern aromatic dispensing system deployment in commercial and hospitality environments. FCC connectivity mandates apply to smart dispenser IoT integrations in hotel properties. California and New York Metro procurement offices embed ESG screening into corporate facility management contracts, favoring suppliers with recycled content verification.
Singapore
Luxury hotel chains in Marina Bay and Orchard Road districts specify signature scent programming and touchless hygiene protocols for guest experience differentiation. The city-state's Building and Construction Authority enforces green building standards that reward circular refill mechanisms in commercial fit-outs. Singapore serves as regional procurement hub for Southeast Asian hospitality rollouts.
United Arab Emirates
Dubai and Abu Dhabi facility management outsourcing concentrates buying power with third-party operators rather than brand owners, fragmenting traditional vendor relationships. MOHAP governs hygiene product safety in hospitality and healthcare applications. Jumeirah and Downtown Dubai luxury properties specify glass and metal housings for lobby installations where aesthetic differentiation commands premium positioning.
Bespoke Dispenser Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hardware, consumables, and integrated service contracts. Three German and Swiss component suppliers control precision dosing IP, limiting second-source options for 0.1-milliliter tolerance mechanisms. Market structure fragments across four strategic archetypes: packaging heritage conglomerates, precision component specialists, sustainable materials innovators, and facility equipment incumbents. Dominant competitive moves include unbundling hardware from consumable contracts and embedding IoT-enabled service relationships.
Among packaging heritage conglomerates, Tetra Pak leverages aseptic beverage expertise into food-service dispensing integration, while Smurfit Kappa anchors sustainable fiber-based housing capabilities. Aptar Group exemplifies precision dosing technology leadership in fragrance and personal care applications. These three occupy positions across divergent value chain segments—aseptic systems, sustainable materials, and precision mechanisms—reflecting the market's structural fragmentation between production expertise and end-use specification.
| Leading Market Players |
|---|
| Tetra Pak |
| Aptar Group |
| Smurfit Kappa |
| DS Smith |
| Liqui-Box |
| Simplehuman |
| Bobrick Washroom Equipment |
| Kohler Co. |
| Sloan Valve Company |
| Others |
Value Chain & Pricing Dynamics
Polypropylene and polycarbonate resin indices cascade through three distinct pricing tiers, with petrochemical volatility compressing margins on precision-molded pump housings while borosilicate glass and anodized aluminum command hardware premiums three-to-five-fold above engineered polymers.
Pricing Analysis
Margin tightening in mechanical dispenser tiers reflects engineered polymer feedstock volatility and REACH compliance testing costs. Three-tier pricing structure across premium glass-metal, standard polymer, and economy plastic levels stratifies by certification grade and after-sales service bundling. Cost-down pressure accelerates as hospitality buyers unbundle hardware from consumable contracts. Commercial office segments exhibit highest price sensitivity; luxury hotel chains demonstrate lowest sensitivity due to experiential differentiation budgets.
Supply Chain Analysis
China's SAMR domestic-content requirements for smart dispenser electronics reshape sourcing toward Yangtze River Delta manufacturing hubs. Supply concentration clusters in Germany and Switzerland for precision dosing components, China for polymer housings and electronics, and Italy for glass fabrication. Borosilicate glass, anodized aluminum, and precision-molded polymers constitute critical input dependencies. Single-source vulnerability concentrates around three German-Swiss patent holders controlling 0.1-milliliter tolerance mechanisms. Distribution runs through direct sales for enterprise hospitality contracts and Alibaba-JD.com ecosystems for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity constraints on precision dosing IP limit second-source options, propping supplier pricing power across the analysis window.
For Market Incumbents: Hedge against polymer feedstock volatility through backward integration into recycled content streams and captive pulp molding capabilities. Secure multi-standard electronics certification parallel tracks early to preempt SAMR-FCC-CE divergence delays. Precision dosing patent thickets remain the priority defensive moat.
For New Entrants and Emerging Players: EU Ecodesign for Sustainable Products Regulation in Europe opens a window for fiber-based housing specialists with circular refill architectures. Food-service aseptic integration presents the most penetrable white space, leveraging transferable packaging heritage. Target facility management outsourcing channels in Dubai and Saudi Arabia with unbundled service contracts as the primary go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors sustainable materials innovators with molded fiber capabilities and captive pulp supply. Long-term viability hinges on ESG procurement policy embedding across corporate facility management. Watch for REACH substance restriction expansion signals as inflection indicators for biobased polymer qualification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Refill Architecture Development | Enables unbundled hardware-consumable contracts for recurring revenue capture in hospitality procurement. |
| Multi-Standard Electronics Certification | SAMR GB standards, FCC, and CE parallel tracks filter non-compliant imports from China tier-one city markets. |
| Sustainable Fiber Housing Scale-Up | Molded fiber capabilities respond to EU Ecodesign mandates and corporate ESG procurement screening. |
| Precision Dosing IP Acquisition | Captive 0.1-milliliter tolerance mechanisms consolidate supplier power in fragrance and personal care applications. |
| Food-Service Aseptic Integration | Tetra Pak heritage transfers to institutional catering and QSR channels for condiment dispensing expansion. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this bespoke dispenser market assessment. Primary interviews with hospitality procurement directors, facility management operators, precision component engineers, and fragrance formulation specialists combined with ECHA substance restriction databases, EPA emission filings, and SAMR GB standard documentation. Bottom-up volume modeling and top-down value triangulation validated segment outputs.
Granularity-level modeling proceeded at product type, material tier, end-user vertical, and distribution channel dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers. Smart dispenser IoT adoption curves and REACH compliance timeline impacts served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for IoT-enabled dispensing; alternative pathways for battery-powered workarounds in legacy hotel infrastructure would alter the outlook. Forecasts reflect assumptions on polymer feedstock stability and electronics certification harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Filling Equipment Market
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Packaging Equipment Market
Packaging Equipment
Global Pack Conveyors Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Retail Press Dispenser Pump Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Clip Applicator Market