
 Powder Filling Equipment Market | 2026-2036
Powder Filling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Filling Equipment Market Analytics
The gap between pharmaceutical-grade precision and commodity food-processing throughput is recalibrating investment priorities across the powder filling landscape. GEA Group leverages its hygienic design expertise to dominate aseptic pharmaceutical lines. Krones AG anchors its position in high-speed beverage powder packaging through integrated container handling systems.
Powder filling equipment encompasses machinery engineered to dispense dry particulate substances into containers with controlled weight or volume accuracy, typically achieving tolerances within one to three percent depending on auger geometry and load-cell configuration. These systems serve industries where product consistency, contamination prevention, and throughput speed determine operational viability. Auger fillers lead the product type category due to their versatility across particle sizes and flow characteristics, while electromechanical technology captures expanding share as servo-driven systems replace pneumatic actuation for repeatable dosing control. The nutraceutical end user segment represents the fastest-growing demand pool, driven by protein powder and supplement SKU proliferation requiring frequent changeover capability.
FDA validation protocols and EU MDR conformity requirements shape equipment specification for pharmaceutical buyers, forcing manufacturers to document IQ/OQ/PQ qualification trails and material traceability. The EPA and OSHA frameworks influence chemical sector procurement through dust containment and worker exposure limits that dictate enclosed filling system architecture. Stakeholders must weigh capital intensity against modular upgrade paths as regulatory stringency and SKU fragmentation simultaneously escalate.
Market Dynamics
Pharmaceutical manufacturers in Germany and Switzerland are forcing equipment suppliers to reengineer dosing systems around EU MDR validation protocols, while nutraceutical packagers in India and Southeast Asia pull capacity toward semi-automatic auger fillers. This dual demand vector splits R&D budgets between precision engineering and cost-optimized modularity.
Growth Catalysts
- EU MDR Conformity Mandates:The Medical Device Regulation tightens documentation requirements for IQ/OQ/PQ qualification trails, compelling pharmaceutical buyers to upgrade legacy pneumatic systems to servo-driven electromechanical platforms with full material traceability.
- Protein Powder SKU Proliferation:Nutraceutical contract packagers face batch sizes below 500 units, driving demand for auger fillers with tool-less changeover capability and recipe-driven HMI interfaces.
- India:Domestic nutraceutical manufacturing scales under the PLI scheme, concentrating semi-automatic filler procurement in Pune and Hyderabad industrial corridors.
Market Restraints
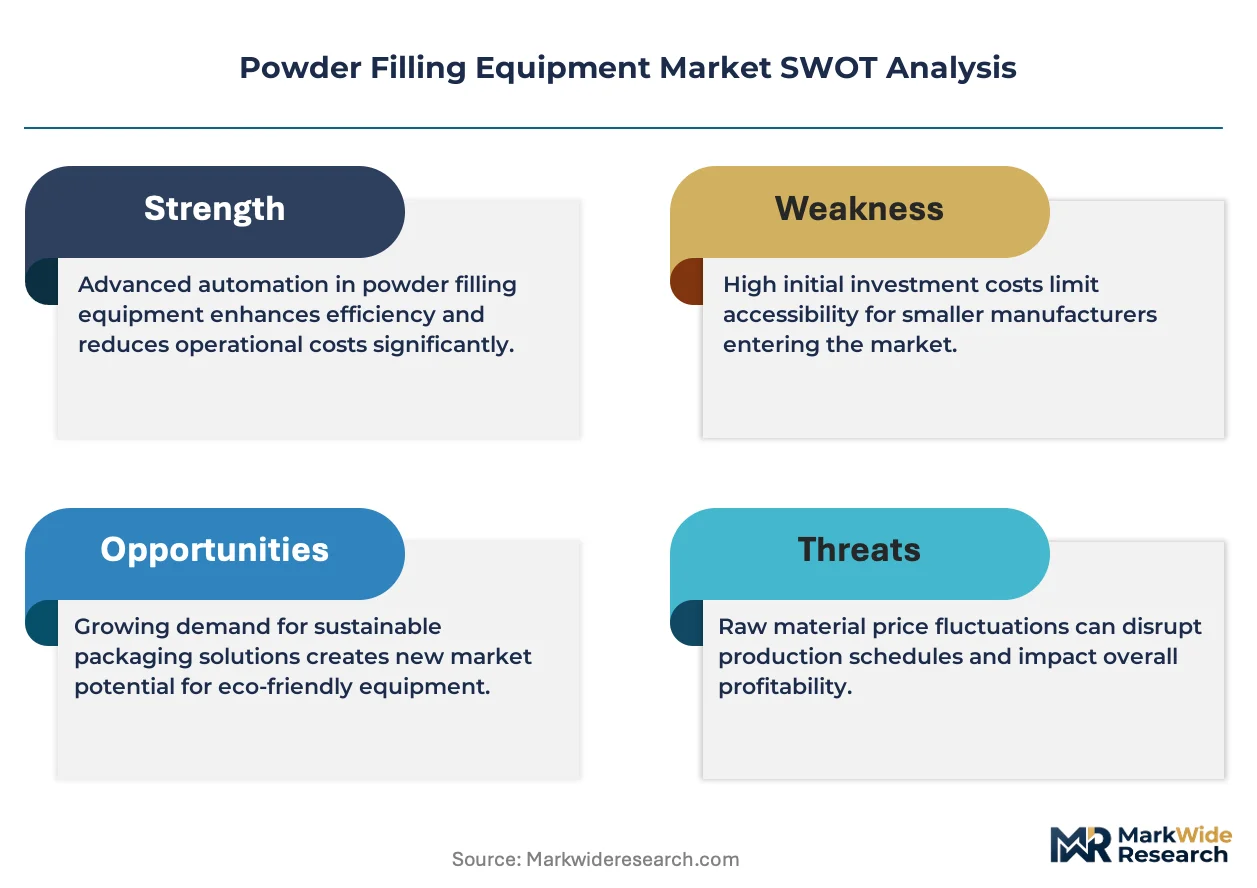
- Stainless Steel Price Volatility:Grade 316L sheet metal constitutes 35-45% of equipment COGS, exposing European fabricators to nickel supply disruptions from Indonesian concentrate.
- Validation Timeline Compression:FDA 21 CFR Part 11 compliance documentation extends pharmaceutical equipment sales cycles by 8-14 months, freezing working capital.
- Modular Pouch Systems:Pre-made stand-up pouches with integrated spouts displace rigid container filling in sports nutrition, eroding auger filler attach rates.
Strategic Opportunities
- Vietnam:Contract manufacturing for Japanese and South Korean supplement brands lacks domestic precision filling capacity, creating import substitution potential for European mid-tier suppliers.
- Continuous Manufacturing Integration:Direct compression tableting lines demand real-time powder feed systems, converging gravimetric filling with PAT process analytical technology.
- EPA Dust Containment Incentives:Chemical sector buyers qualify for accelerated depreciation on enclosed filling systems meeting NESHAP standards, redirecting capex from open-frame designs.
Industry Challenges
- Servo Motion Programming Talent:Electromechanical system commissioning requires expertise in Beckhoff or Siemens drive architecture, a skill set concentrated in southern Germany and northern Italy.
- Legacy Pneumatic Retrofit Complexity:Brownfield pharmaceutical plants face production downtime exceeding six weeks when migrating to servo-driven dosing, risking batch release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Filling Equipment Market |
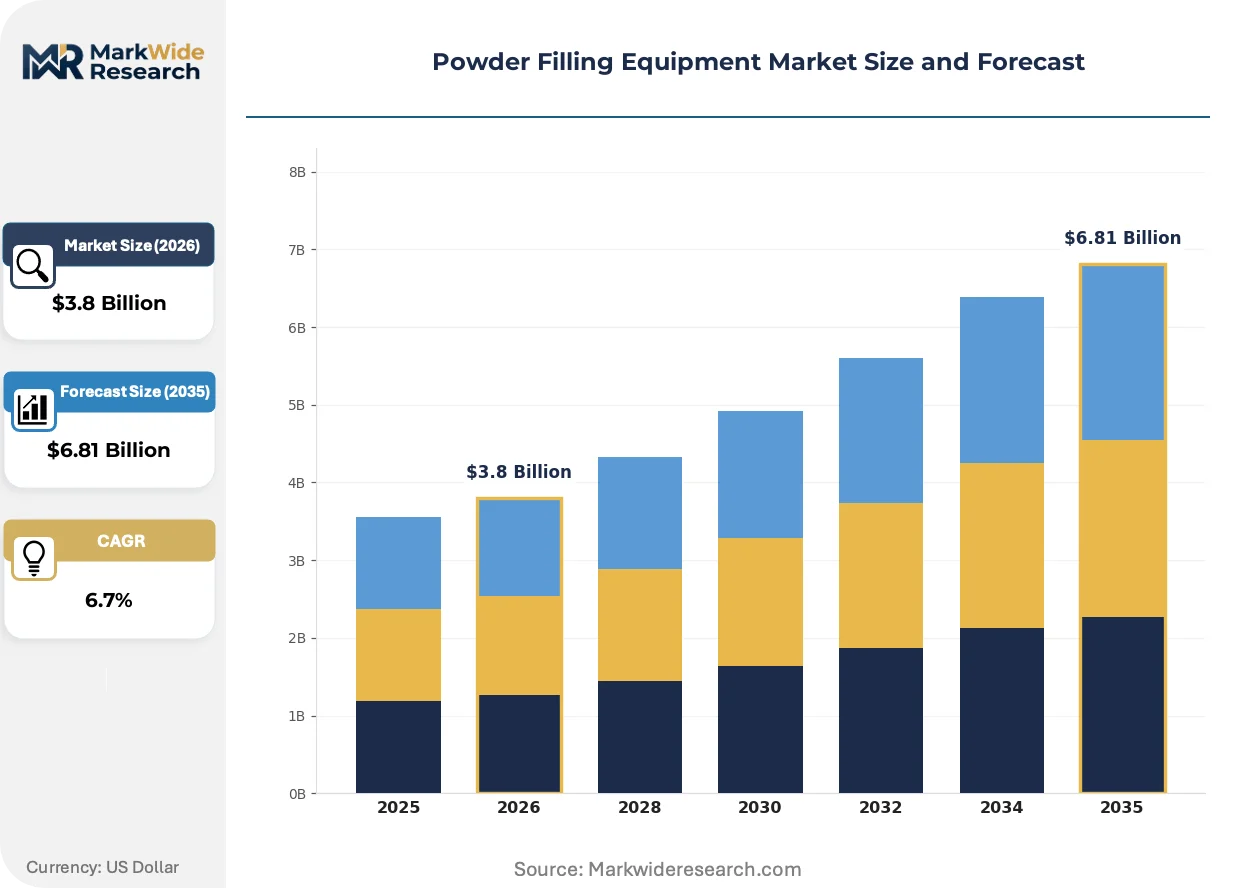
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Fillers, Auger Fillers, Cup Fillers, Tablet Fillers End User: Pharmaceuticals, Food & Beverage, Chemicals, Nutraceuticals Technology: Electromechanical, Pneumatic, Manual, Semi-Automatic Packaging Type: Bags, Bottles, Pouches, Containers |
| Companies Covered | Tetra Pak, Coesia Group, Krones AG, ProMach, Serac Group, Syntegon Technology, GEA Group, Barry-Wehmiller, IMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Filling Equipment Market Evolving Landscape
Machine learning is penetrating powder flow characterization, compressing recipe development from weeks to days. Equipment suppliers now embed spectroscopic sensors directly into auger housings, enabling real-time bulk density compensation without line stoppage.
Servo-driven multi-axis dosing systems are automating changeover sequences that previously required manual auger removal and hopper cleaning. Pharmaceutical packagers in Basel and Munich adopt these platforms to compress batch turnaround below 90 minutes. The technology is automating labor-intensive validation documentation by logging every torque and position parameter directly into batch records.
EU MDR Article 10.4 now mandates post-market surveillance data collection for all Class IIa and above medical device manufacturing equipment. Powder filler suppliers must embed unique device identification and event reporting capabilities into control architectures. German pharmaceutical OEMs are responding by pre-qualifying suppliers against EUDAMED database requirements, filtering out smaller automation houses lacking regulatory affairs bandwidth.
After-sales service unbundling is accelerating as contract packagers reject bundled maintenance contracts. Buyers in India's nutraceutical corridor now procure spare parts through independent distributors and self-perform auger refurbishment. This pattern is most visible in Ahmedabad and Mumbai, where third-party validation engineers compete directly with OEM field service teams on FDA inspection preparation.
Powder Filling Equipment Market Segmentation
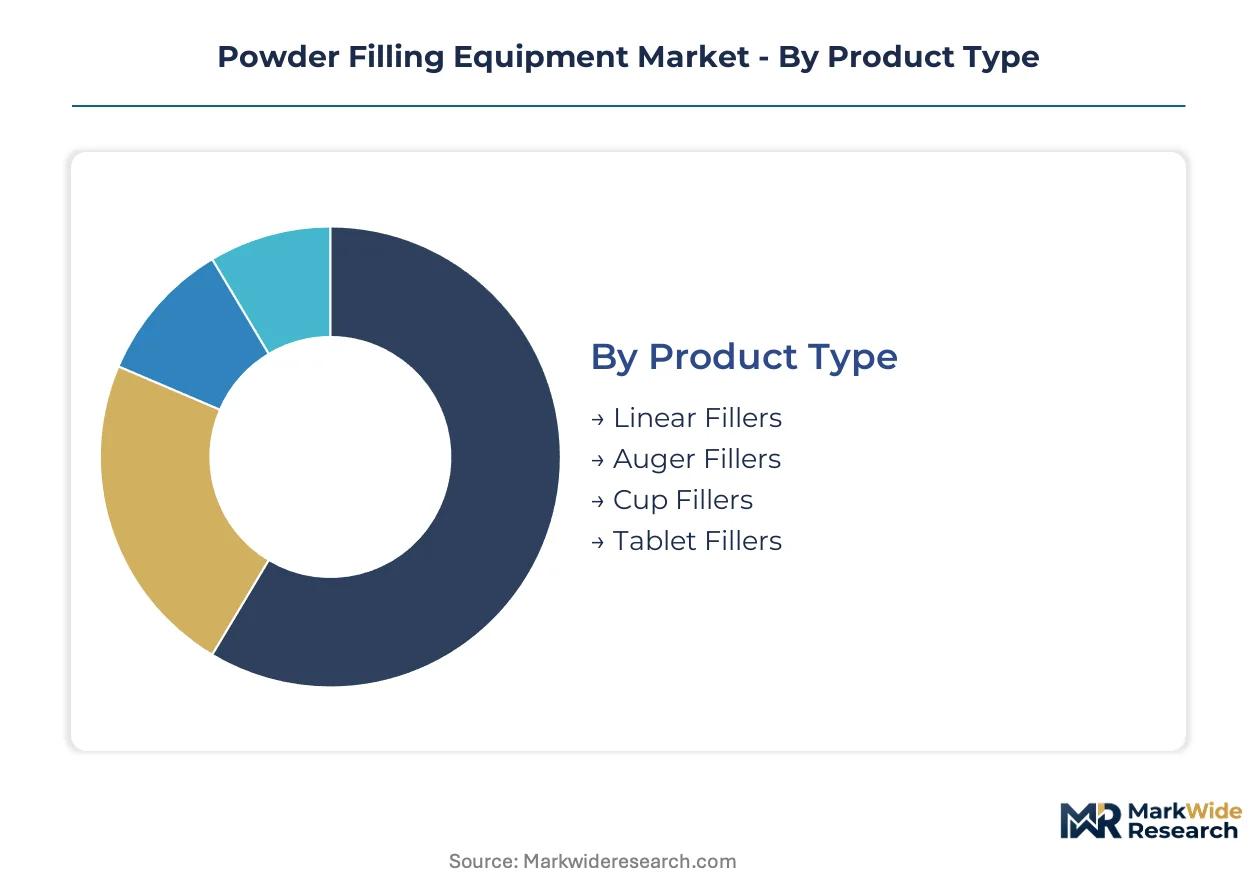
Powder filling equipment procurement splits across precision requirements, throughput demands, and regulatory exposure. Equipment specification varies sharply between aseptic pharmaceutical lines and commodity food processing, with capital allocation patterns reflecting these divergent operational priorities.
Product Type:
Auger fillers command the highest upfront capital outlay due to servo-driven multi-axis architectures and integrated load-cell feedback systems required for pharmaceutical-grade dosing accuracy.
- Auger Fillers:Helical screw mechanisms dispense powders across particle sizes from fine APIs to coarse protein blends. Swiss and German pharmaceutical manufacturers specify these systems for EU MDR-validated lines requiring documented torque traces and material certificates for every batch.
- Linear Fillers:Indexing conveyor platforms synchronize multiple filling heads for high-speed beverage powder operations. Krones AG integrates these with container handling systems at European dairy powder facilities where throughput exceeds 300 units per minute.
- Cup Fillers:Volumetric disc systems suit free-flowing granular products in food processing. Indian spice packagers in Gujarat deploy these for turmeric and chili powder operations where cost sensitivity limits servo investment.
- Tablet Fillers:Specialized gravity-fed systems handle pre-compressed dosages for effervescent and chewable formats. Nutraceutical contract manufacturers in Hyderabad specify these for vitamin tablet-in-bottle applications.
Auger fillers absorb the bulk of installed capacity; linear fillers are expanding most quickly in high-throughput beverage applications.
End User:
Regulatory burden intensity determines equipment specification tiers, with validation documentation requirements creating sharp procurement boundaries between segments.
- Pharmaceuticals:FDA 21 CFR Part 11 and EU MDR compliance mandate IQ/OQ/PQ qualification trails, material traceability, and unique device identification embedded in control systems. Basel and Munich manufacturing clusters drive specification for servo-driven platforms with full batch record automation.
- Nutraceuticals:Protein powder SKU proliferation below 500-unit batch sizes demands tool-less changeover and recipe-driven HMI interfaces. India's PLI scheme concentrates semi-automatic auger filler procurement in Pune and Hyderabad corridors.
- Food & Beverage:Dairy and instant coffee packagers prioritize throughput over precision, specifying pneumatic systems where one to three percent dosing tolerance satisfies commercial requirements.
- Chemicals:EPA NESHAP dust containment standards and OSHA exposure limits dictate enclosed filling architectures. Buyers qualify for accelerated depreciation on systems meeting environmental compliance thresholds.
Pharmaceuticals anchor premium equipment revenue; nutraceuticals are gaining share fastest as contract packaging fragments batch sizes.
Technology:
Actuation mechanism selection reflects the trade-off between dosing repeatability and capital deployment speed, with electromechanical platforms requiring extended commissioning timelines.
- Electromechanical:Servo-driven systems with Beckhoff or Siemens architecture deliver repeatable dosing control for pharmaceutical validation. Talent scarcity in southern Germany and northern Italy constrains deployment velocity.
- Pneumatic:Compressed air actuation dominates legacy food and chemical installations. Brownfield pharmaceutical plants face six-week production downtime when migrating to servo platforms.
- Semi-Automatic:Operator-assisted auger systems balance precision with capital efficiency. Southeast Asian nutraceutical packagers favor these for mid-scale protein powder operations.
- Manual:Hand-cranked fillers persist in artisanal spice and specialty chemical niches where batch volumes fall below automated equipment minimums.
Electromechanical platforms capture expanding specification share; semi-automatic systems maintain volume concentration in emerging manufacturing corridors.
Packaging Type:
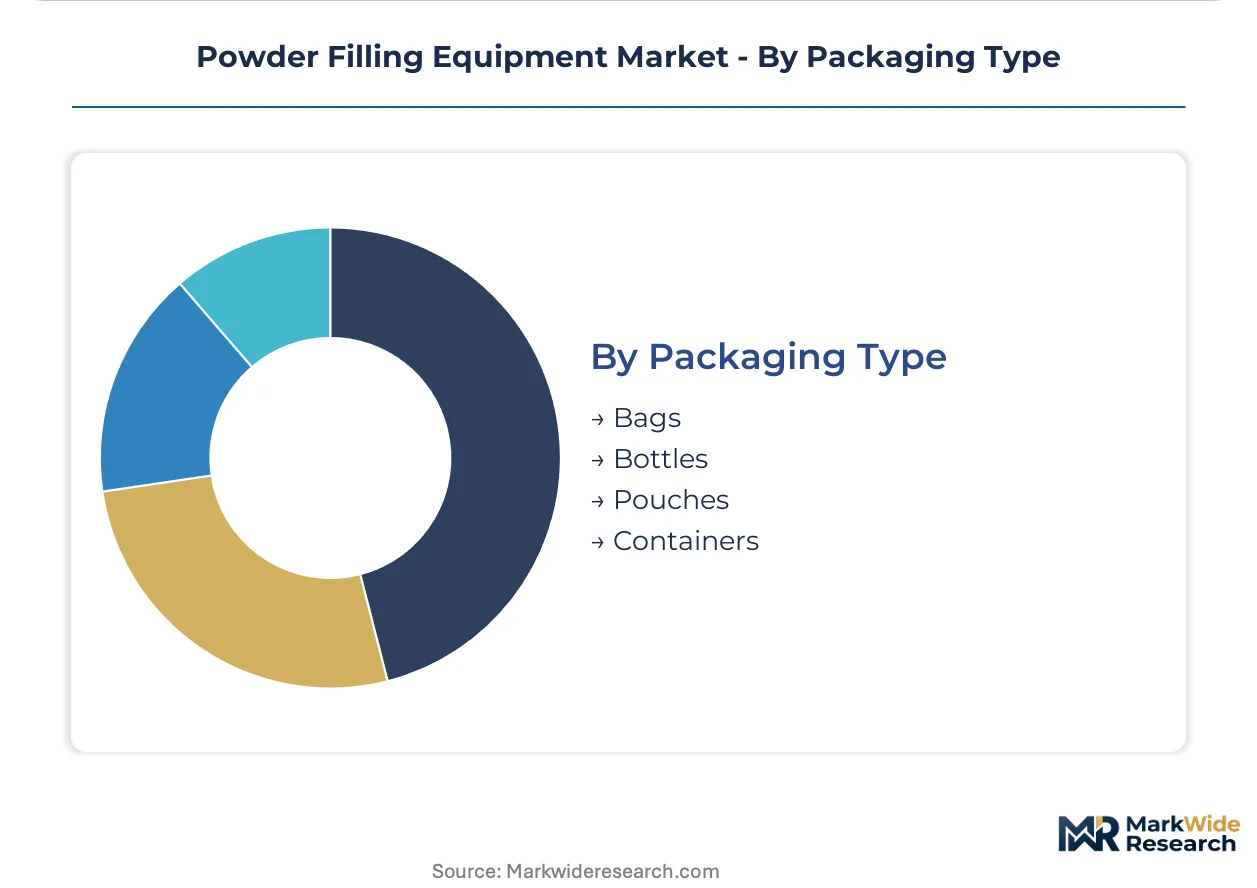
Container format selection increasingly determines filler attach rates as flexible packaging displaces rigid formats in key end-use segments.
- Bottles:Rigid HDPE and glass containers remain standard for pharmaceutical tablets and capsules. Integrated desiccant insertion and capping stations extend line complexity.
- Pouches:Pre-made stand-up formats with integrated spouts displace rigid containers in sports nutrition. This shift erodes auger filler attach rates where equipment suppliers lack form-fill-seal integration.
- Bags:Open-mouth and valve bag systems serve industrial chemical and food ingredient bulk operations. Dust containment architecture dominates specification criteria.
- Containers:Wide-mouth jars for protein powders and supplement blends require specialized auger geometries to prevent bridging and ratholing.
Bottles retain the largest installed base; pouches are climbing the fastest as brand owners seek shelf differentiation and logistics efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel anchors pharmaceutical-grade equipment specification through Swissmedic-validated manufacturing clusters serving Novartis and Roche supply chains. German industrial corridors and Indian nutraceutical hubs pull capacity toward divergent equipment tiers.
Germany
Baden-Württemberg and Bavaria concentrate servo-driven electromechanical platform demand from Merck KGaA and Boehringer Ingelheim operations. EU MDR Article 10.4 post-market surveillance mandates force Heidelberg and Munich equipment buyers to pre-qualify suppliers against EUDAMED database requirements. Stuttgart's automation engineering talent pool constrains deployment velocity for Beckhoff and Siemens architecture commissioning.
Switzerland
Swissmedic conformity protocols in Basel and Zürich drive specification for documented IQ/OQ/PQ qualification trails with full material traceability. The country's medical device manufacturing density exceeds any European peer per capita. Lonza and Bachem operations in Visp and Bubendorf anchor aseptic line demand for GEA Group and Syntegon Technology platforms.
India
Pune and Hyderabad industrial corridors concentrate semi-automatic auger filler procurement under the PLI scheme for domestic nutraceutical manufacturing. FSSAI packaging regulations and CDSCO pharmaceutical oversight create dual compliance frameworks. Contract packagers in Ahmedabad now self-perform auger refurbishment through independent distributors rather than OEM service contracts.
United States
FDA 21 CFR Part 11 compliance documentation extends pharmaceutical equipment sales cycles by 8-14 months in New Jersey and North Carolina manufacturing clusters. EPA NESHAP dust containment standards redirect chemical sector capex toward enclosed filling architectures qualifying for accelerated depreciation. Protein powder contract manufacturers in Utah and Colorado face SKU proliferation below 500-unit batch sizes.
Vietnam
Japanese and South Korean supplement brands contract manufacturing in Binh Duong and Dong Nai provinces lacks domestic precision filling capacity. The country's national pharmaceutical regulator has not yet harmonized equipment validation protocols with PIC/S standards. European mid-tier suppliers face import substitution potential as local packaging operations scale beyond manual filling methods.
Powder Filling Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure consolidating around three tiers. Swiss and German engineering houses anchor premium pharmaceutical specification through integrated validation documentation capabilities. Mid-tier European fabricators and Asian cost-optimized specialists split nutraceutical and food-processing procurement. Competitive moves concentrate on servo motion programming talent acquisition in southern Germany and strategic partnerships for continuous manufacturing integration.
Within the premium pharmaceutical tier, GEA Group and Syntegon Technology occupy positions defined by hygienic design expertise and aseptic line integration. Krones AG exemplifies the beverage powder packaging archetype through container handling system integration. Among diversified packaging conglomerates, Tetra Pak and Coesia Group represent scale-driven positions spanning multiple filling technologies beyond powder-specific applications.
| Leading Market Players |
|---|
| Tetra Pak |
| Coesia Group |
| Krones AG |
| ProMach |
| Serac Group |
| Syntegon Technology |
| GEA Group |
| Barry-Wehmiller |
| IMA Group |
| Others |
Value Network & Pricing Analysis
Backward integration into servo drive and load-cell component manufacturing anchors pricing power for German and Swiss equipment OEMs serving EU MDR-validated pharmaceutical lines. This captive production of precision dosing subsystems insulates premium tier suppliers from nickel price volatility in Grade 316L stainless steel while forcing mid-tier competitors to absorb commodity metal cost swings.
Pricing Analysis
Yield-based pricing anchors pharmaceutical equipment contracts, with buyers paying premiums for documented batch consistency and uptime guarantees rather than capital cost alone. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-validated servo platforms from pneumatic food-processing units and semi-automatic nutraceutical fillers. Pricing pressure stems from Indian contract packagers rejecting bundled after-sales contracts in favor of independent spare part sourcing. Food and beverage buyers exhibit highest price sensitivity, while Basel and Munich pharmaceutical clusters accept 40-60% capital premiums for qualification documentation.
Supply Chain Analysis
Dual-sourcing requirements for Beckhoff and Siemens servo drives force European OEMs to qualify secondary automation suppliers in northern Italy alongside primary German vendors. Component fabrication concentrates in Germany, Switzerland, and Italy, with Grade 316L stainless steel sheet metal drawing from Indonesian nickel concentrate through Dutch and Belgian processors. Single-source vulnerability sits with southern Germany's concentrated Beckhoff programming talent pool. Distribution runs through direct OEM sales teams for pharmaceutical accounts and independent distributors serving Indian nutraceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo motion programming talent scarcity props pricing for electromechanical platforms, constraining supply expansion even as EU MDR mandates accelerate replacement demand. This bottleneck sustains margin premiums for incumbents with qualified commissioning engineers.
For Market Incumbents: Anchor defensive positioning through captive servo drive calibration facilities in Stuttgart and Munich, insulating against talent poaching from Italian automation houses. Deepen backward integration into load-cell manufacturing to offset Grade 316L price volatility. Prioritize EUDAMED database pre-qualification to filter mid-tier competitors lacking regulatory affairs bandwidth. For New Entrants and Emerging Players: Enter via contract manufacturing partnerships with Japanese and South Korean supplement brands in Vietnam's Binh Duong province, exploiting the absence of domestic precision filling capacity. Target semi-automatic auger filler segments where European incumbents disengage on price. Pursue tool-less changeover capability as the primary go-to-market wedge against legacy pneumatic suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified packaging conglomerates seeking pharmaceutical validation capabilities. Five-to-ten year viability favors mid-tier European fabricators with existing EU MDR documentation infrastructure over greenfield automation ventures. Watch FDA 21 CFR Part 11 compliance timeline compression as the inflection signal—accelerated validation requirements favor acquired capability over organic buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Servo Drive Talent Acquisition | Beckhoff and Siemens certified engineers in southern Germany command premium retention packages from GEA Group and Syntegon Technology. |
| EUDAMED Database Pre-Qualification | Swissmedic conformity protocols force Heidelberg equipment buyers to filter suppliers lacking post-market surveillance architecture. |
| Continuous Manufacturing Integration | Direct compression tableting lines at Lonza and Bachem demand real-time powder feed convergence with PAT process analytical technology. |
| Independent Spare Parts Distribution | Ahmedabad contract packagers now self-perform auger refurbishment through third-party distributors, eroding OEM service attach rates. |
| Enclosed Filling Architecture Certification | EPA NESHAP compliance qualifies chemical sector buyers for accelerated depreciation, redirecting capex from open-frame designs. |
Research Methodology
Trade association filings, EU MDR guidance documents, and SEC equipment manufacturer disclosures formed the secondary backbone, cross-referenced against primary interviews with pharmaceutical validation engineers, nutraceutical contract packaging operations directors, and stainless steel procurement leads at Baden-Württemberg fabricators. Bottom-up triangulation combined installed base estimates from regional industrial clusters with top-down revenue reconciliation against public filings. Conversations with FDA inspection preparation consultants and independent validation engineers in Ahmedabad supplied aftermarket service pattern intelligence.
Bottom-up modeling segmented the analysis window by product type, end-user regulatory burden, actuation technology, and packaging format displacement trends. Value projections derived from unit economics across pharmaceutical-grade servo platforms, semi-automatic nutraceutical fillers, and pneumatic food-processing equipment. CAGRs incorporated equipment replacement cycles tied to EU MDR Article 10.4 post-market surveillance mandates and FDA 21 CFR Part 11 compliance documentation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel supply disruption scenarios or accelerated FDA validation timeline compression. Deviation in servo motion programming talent availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Packer Market
Packaging Equipment
Filling Equipment Market
Packaging Equipment
Laser Coding Equipment Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
Packing Belt Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Global End-Of-Line Packaging Market