
 Can Seamers Market | 2026-2036
Can Seamers Market Size, Share, and Industry Trends Forecast 2026-2036
Can Seamers Market Intelligence
The divergence between premium and commodity tiers is hardening in can seamer procurement. Beverage manufacturers now demand servo-driven precision for aluminum sleek cans, while food processors prioritize throughput over seam cosmetics. JBT Corporation leverages its North American service density to anchor high-volume beverage contracts. Ferrum Packaging AG differentiates through Swiss-engineered tooling for irregular can geometries. Krones AG extends its filling-line integration capability to control seamer placement in greenfield breweries.
Can seamers are machines that curl and interlock can body and end materials to form hermetic double seams, typically achieving overlap values of 1.0–1.5 mm and body hook lengths of 1.8–2.2 mm to ensure microbiological integrity in shelf-stable packaging. Their primary purpose is to create pressure-resistant closures for carbonated beverages, retorted foods, and aerosol products. Fully automatic seamers dominate capital expenditure among beverage manufacturers seeking line speeds exceeding 2,000 cans per minute, while semi-automatic units retain relevance in craft and pilot-scale operations where batch flexibility outweighs throughput. Electromechanical technology leads new installations for precision and energy efficiency, though pneumatic systems persist in legacy chemical packaging environments.
FDA food-contact notification requirements and USDA FSIS shelf-stable meat regulations shape seam integrity validation protocols in the United States, while ISO 9001 and 3-A Sanitary Standards govern equipment qualification for international dairy and beverage exports. The EU Machinery Directive and CE marking constrain design modifications for European-bound equipment, lengthening approval cycles for non-integrated suppliers. Stakeholders must monitor evolving aluminum alloy specifications and deposit-return scheme expansions, as both will redefine seamer tooling compatibility and regional equipment specifications.
Market Dynamics
Servo-driven electromechanical seamer architectures are displacing pneumatic legacy systems as beverage manufacturers chase aluminum sleek can compatibility and energy efficiency mandates. This technology pivot concentrates procurement power among OEMs with integrated motion control expertise.
Growth Catalysts
- Deposit-return scheme expansion:Germany's DRS expansion and California's SB 1013 implementation are forcing can line retrofits to handle lighter aluminum specifications, driving replacement cycles for legacy seamers.
- Ready-to-drink beverage scaling:Hard seltzer and canned cocktail producers in the United States are commissioning dedicated canning lines, prioritizing servo precision for carbonation retention in 12-oz sleek formats.
- FDA seam integrity protocols:Updated FDA food-contact notification requirements for double-seam validation are compelling processors to upgrade from semi-automatic to fully automatic inspection-integrated systems.
Market Restraints
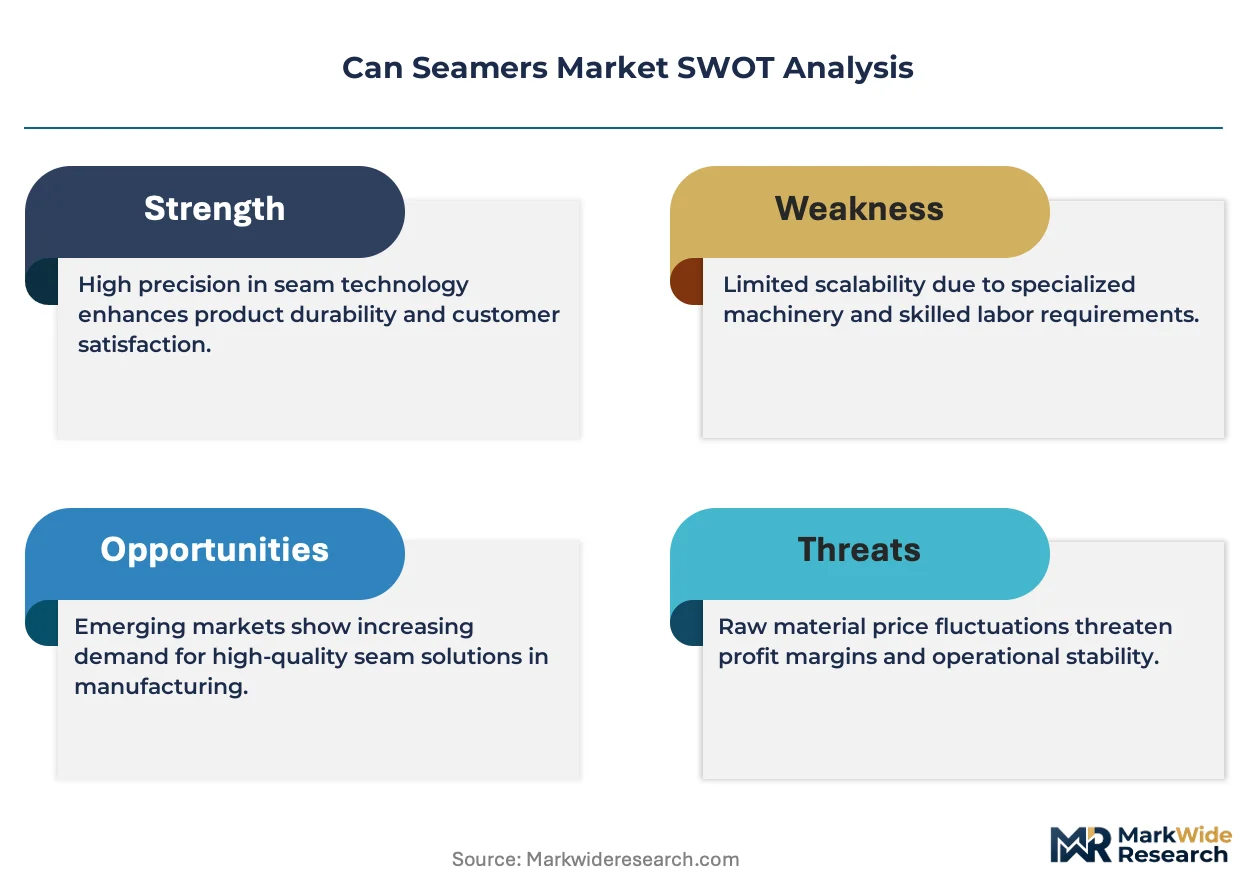
- Aluminum alloy volatility:3104 and 3004 alloy price swings force seamer OEMs to absorb tooling recalibration costs or pass through to capital-constrained craft brewers.
- Swiss-German tooling concentration:Precision roll forming and chuck tooling supply concentrates among Alpine region specialists, creating single-source vulnerability for North American seamer assemblers.
- Pneumatic system lock-in:Chemical and aerosol packagers face stranded asset risk as electromechanical platforms dominate R&D investment, freezing upgrade paths for legacy pneumatic installations.
Strategic Opportunities
- India beverage packaging formalization:FSSAI-mandated shelf-stable standards for dairy and RTD tea are creating first-mover advantage for seamer OEMs establishing local service networks in Maharashtra and Karnataka.
- Retort pouch-to-can conversion:Pet food processors are pivoting from flexible retort to metal cans for premium positioning, opening seam specification work for irregular geometries.
- CE marking acceleration:The EU Machinery Directive's 2027 enforcement window for updated safety categories is compressing approval timelines, favoring integrated filling-seaming line suppliers with established Notified Body relationships.
Industry Challenges
- Mechatronics talent scarcity:Seamer OEMs compete with automotive and robotics sectors for servo tuning and motion programming specialists, elongating commissioning timelines for complex multi-head installations.
- ISO 9001-3-A dual certification burden:Dairy and beverage export equipment requires simultaneous quality and sanitary standard validation, creating documentation bottlenecks for mid-tier manufacturers without dedicated compliance functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Can Seamers Market |
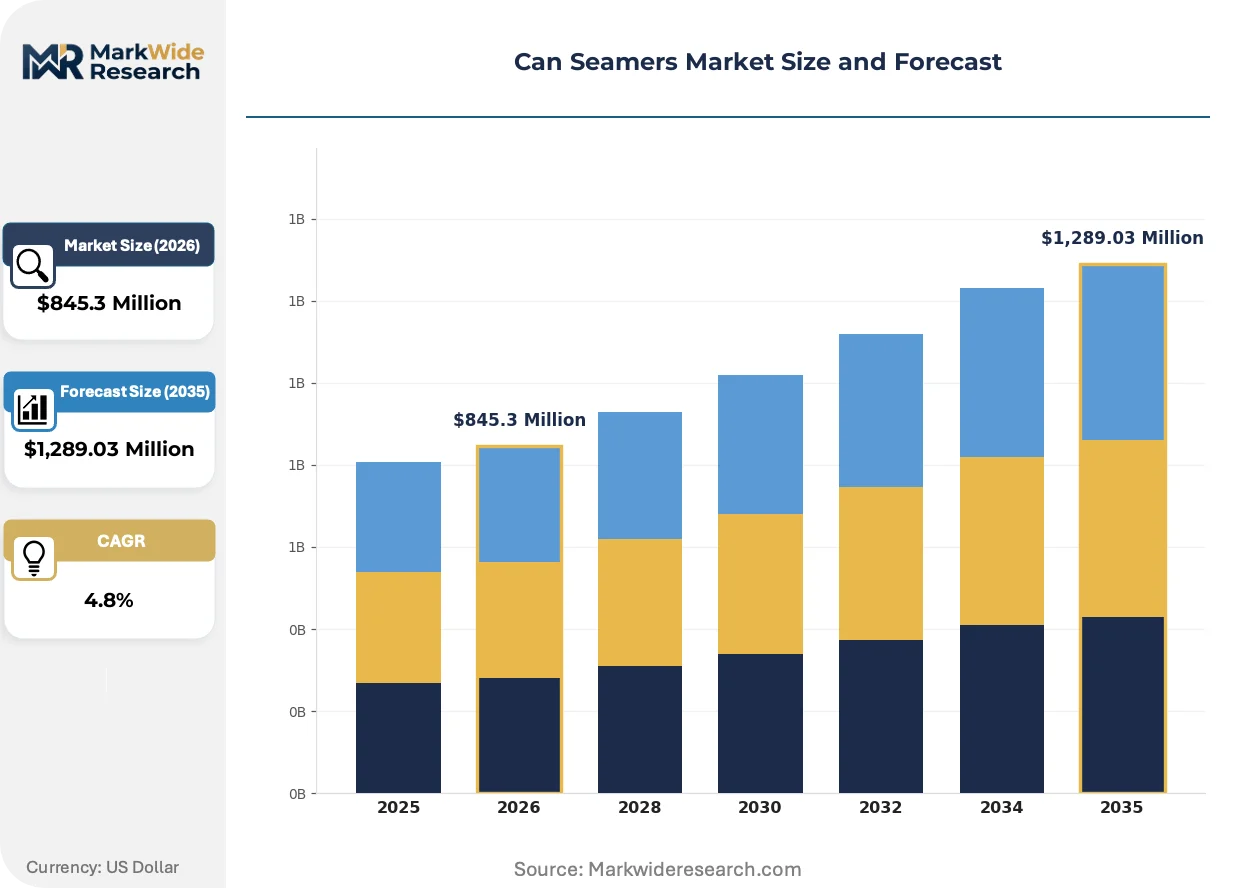
| Market Size in 2026 | $845.3 Million |
| Market Size in 2035 | $1,289.03 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Seamers, Semi-Automatic Seamers, Fully Automatic Seamers, Electric Seamers End User: Beverage Manufacturers, Food Processors, Chemical Companies, Packaging Studios Application: Canning, Preserving, Packaging, Food Processing Technology: Electromechanical, Pneumatic, Hydraulic, Mechanical |
| Companies Covered | CFT Group, ZACMI, Ferrum Packaging AG, Toyo Seikan, Swiss Can Machinery AG, Pneumatic Scale Angelus, JBT Corporation, Hefei Zhongchen, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Can Seamers Market Strategic Shifts & Innovations
Active feedback control and predictive maintenance architectures are redefining seamer performance guarantees. OEMs now bundle uptime commitments with hardware sales, compressing traditional service revenue models.
Direct-drive servo seamer heads with integrated torque feedback are electrifying precision control in high-speed beverage applications. Coca-Cola and PepsiCo bottlers in the southeastern United States are specifying these architectures for 2,500+ cans-per-minute lines. The technology is electrifying competitive differentiation around seam consistency metrics rather than raw throughput specifications.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is indirectly pressuring seamer cooling system redesigns for hot-fill applications. Equipment suppliers must now validate thermal management without conventional refrigerant-based cooling loops. Italian and Spanish tomato paste packagers are piloting water-cooled chuck alternatives ahead of 2030 compliance deadlines.
After-sales service unbundling is fragmenting buyer-supplier relationships in craft beverage segments. Regional canning line distributors now source third-party seamer maintenance, bypassing OEM service contracts. This pattern is most visible in Colorado and Oregon, where mobile canning operators prioritize local technician availability over factory-authorized support networks.
Can Seamers Market Segmentation
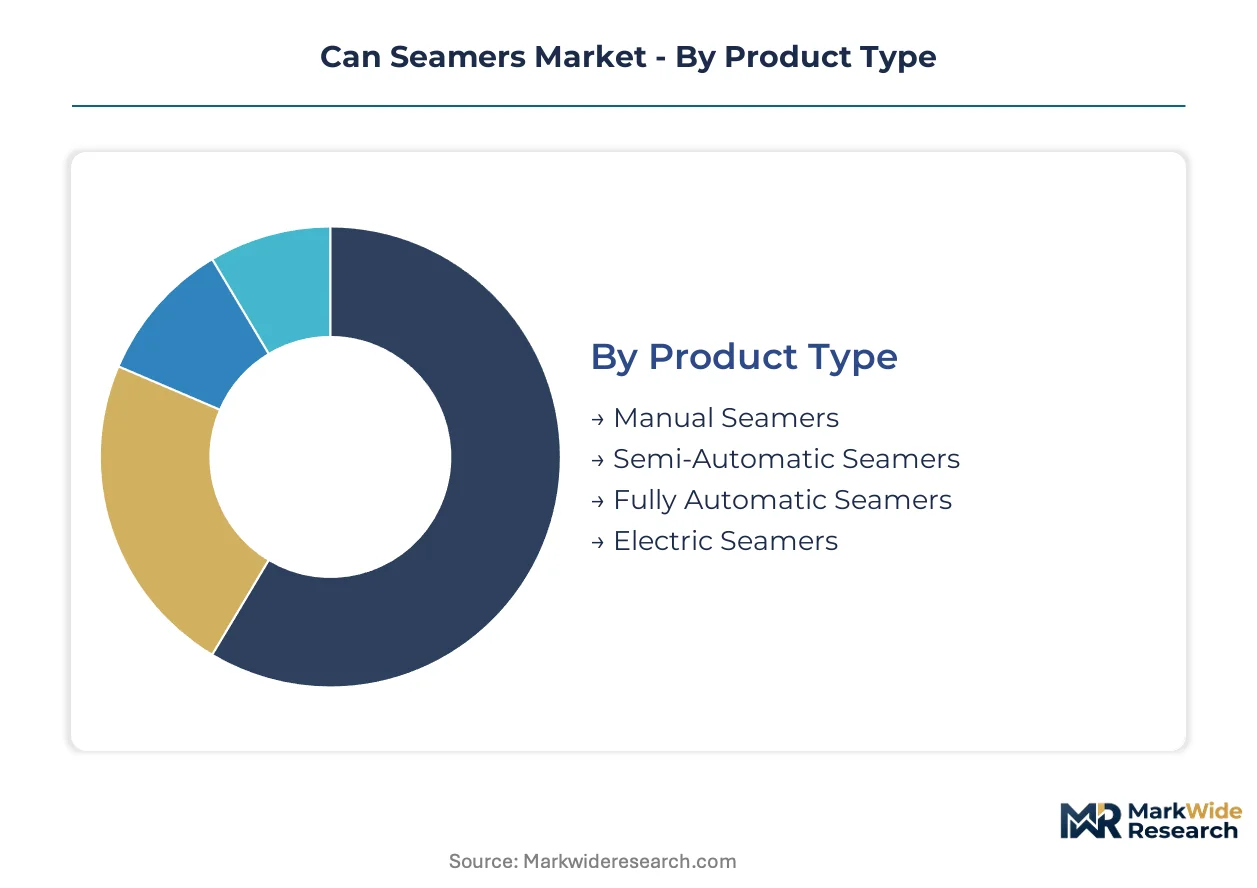
Seamer procurement patterns diverge sharply across equipment tiers and end-use requirements. Beverage manufacturers prioritize servo precision for aluminum compatibility, while food processors balance throughput against regulatory compliance burdens. Understanding these segment dynamics clarifies where upgrade cycles concentrate and which technology platforms capture replacement expenditure.
Product Type:
Replacement cycles accelerate where legacy pneumatic architectures face energy efficiency mandates and new aluminum alloy specifications.
- Fully Automatic Seamers:Integrated servo-driven systems achieve line speeds exceeding 2,000 cans per minute with active torque feedback for seam consistency. Coca-Cola and PepsiCo bottlers in the southeastern United States specify these architectures for carbonation retention in sleek can formats, though mechatronics talent scarcity elongates commissioning timelines for multi-head installations.
- Semi-Automatic Seamers:Batch-flexible units retain relevance in craft beverage and pilot-scale operations where changeover speed outweighs raw throughput. Colorado and Oregon mobile canning operators favor these systems for portfolio diversification, yet regional distributors increasingly source third-party maintenance, fragmenting OEM service relationships.
- Manual Seamers:Entry-level units serve artisanal producers and packaging studios with sub-50 cans per hour requirements.
- Electric Seamers:Compact electromechanical designs target emerging market formalization where grid stability permits precision control without pneumatic infrastructure.
Fully automatic seamers sit at the top of the volume ranking, with electric seamers climbing the fastest as emerging markets bypass pneumatic legacy entirely.
End User:
Margin structures and compliance burdens reshape procurement authority across customer categories.
- Beverage Manufacturers:Carbonated soft drink and ready-to-drink alcohol producers command the largest capital expenditure flows, prioritizing servo precision for pressure-resistant closures in aluminum sleek cans. Hard seltzer and canned cocktail scaling in the United States drives dedicated line commissioning, though aluminum 3104 and 3004 alloy volatility forces tooling recalibration cost absorption.
- Food Processors:Shelf-stable meat and retorted vegetable packagers face FDA and USDA FSIS seam integrity validation protocols, compelling migration from semi-automatic to inspection-integrated systems. Pet food processors pivoting from retort pouches to metal cans for premium positioning create specification work for irregular geometries.
- Chemical Companies:Aerosol and specialty chemical packagers confront stranded asset risk as OEM R&D investment concentrates on electromechanical platforms, freezing upgrade paths for legacy pneumatic installations.
- Packaging Studios:Contract canning operations and mobile canning services prioritize technician availability over factory-authorized support networks, unbundling after-sales service relationships.
Beverage manufacturers anchor procurement volume, with food processors expanding most quickly under regulatory pressure.
Application:
Process temperature and microbiological requirements dictate seamer specification intensity.
- Canning:Carbonated beverage applications demand hermetic double seams with 1.0–1.5 mm overlap values and 1.8–2.2 mm body hook lengths for pressure resistance. Hot-fill tomato paste packagers in Italy and Spain pilot water-cooled chuck alternatives ahead of EU F-Gas Regulation compliance deadlines.
- Preserving:Retort-processed shelf-stable foods require seam architectures validated for thermal cycling without integrity compromise.
- Packaging:Aerosol and specialty chemical closures prioritize mechanical robustness over cosmetic seam finish.
- Food Processing:Integrated filling-seaming lines for dairy and beverage exports require simultaneous ISO 9001 and 3-A Sanitary Standards certification, creating documentation bottlenecks for mid-tier manufacturers.
Canning commands the dominant application share, with preserving gaining share fastest as retort pouch conversion accelerates.
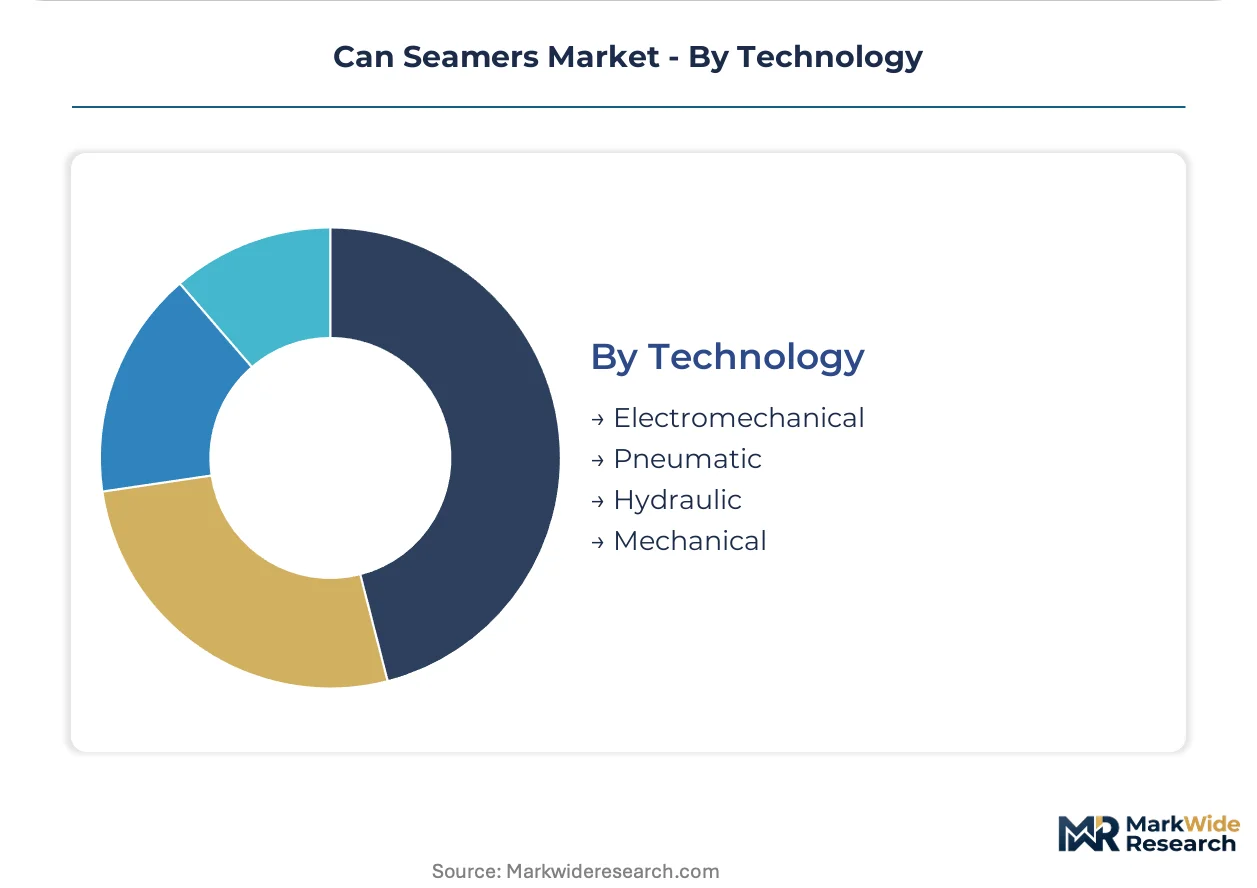
Technology:
Energy efficiency mandates and precision requirements are reconfiguring the technology mix.
- Electromechanical:Direct-drive servo heads with integrated torque feedback electrify competitive differentiation around seam consistency rather than raw throughput. Krones AG extends filling-line integration capability to control seamer placement in greenfield breweries, while JBT Corporation leverages North American service density for high-volume beverage contracts.
- Pneumatic:Legacy chemical and aerosol installations face R&D investment starvation as OEMs concentrate on servo architectures, creating stranded asset vulnerability.
- Hydraulic:Heavy-duty applications in irregular can geometries retain niche relevance where force modulation exceeds electromechanical torque limits.
- Mechanical:Pure mechanical systems persist in cost-constrained emerging markets where electronic maintenance capability remains scarce.
Electromechanical technology leads installed base value, with hydraulic systems showing the steepest expansion trajectory in irregular geometry specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechatronics talent pools in the United States, Germany, and Switzerland anchor precision seamer engineering, while emerging markets in India and Brazil build localized service networks around beverage packaging formalization.
United States
Hard seltzer and canned cocktail producers in Colorado and the Pacific Northwest commission dedicated canning lines for 12-oz sleek formats. FDA food-contact notification requirements for double-seam validation compel processors to upgrade from semi-automatic to fully automatic inspection-integrated systems. Mobile canning operators in Oregon unbundle after-sales service relationships, sourcing third-party maintenance over factory-authorized support networks.
Germany
Beverage manufacturers retrofit can lines to handle lighter aluminum specifications under deposit-return scheme expansion mandates. The EU Machinery Directive and CE marking constrain design modifications, lengthening approval cycles for non-integrated suppliers. Bavarian and Baden-Württemberg precision tooling specialists concentrate roll forming and chuck supply, creating single-source vulnerability for North American seamer assemblers.
India
FSSAI-mandated shelf-stable standards for dairy and RTD tea create first-mover advantage for seamer OEMs establishing local service networks. Maharashtra and Karnataka industrial corridors attract filling-line integrators seeking to capture formalizing beverage packaging demand. Grid stability improvements in these states permit electromechanical precision control without pneumatic infrastructure dependency.
Italy
Tomato paste packagers in Emilia-Romagna and Campania pilot water-cooled chuck alternatives ahead of EU F-Gas Regulation compliance deadlines for 2030. The phasedown of hydrofluorocarbon refrigerants pressures seamer cooling system redesigns for hot-fill applications. Northern Italian equipment suppliers validate thermal management without conventional refrigerant-based cooling loops.
Brazil
Contract canning operations in São Paulo and Minas Gerais prioritize technician availability over factory-authorized support networks, fragmenting OEM service relationships. ANVISA shelf-stable beverage regulations drive migration toward inspection-integrated seamer architectures. Local distributors source third-party maintenance for semi-automatic units serving craft beverage portfolio diversification.
Can Seamers Market Key Industry Players
Top-tier vendors anchor integrated filling-seaming line supply, while mid-tier fabricators compete on regional service density and batch-flexible system configurations. The vendor base stratifies across three archetypes: precision tooling specialists with Alpine engineering heritage, North American service-heavy integrators, and emerging-market cost-optimized assemblers. Dominant competitive moves include strategic partnerships with aluminum alloy suppliers for tooling recalibration cost sharing, and geographic expansion through local distributor acquisition in India and Brazil.
Within the precision-tier segment, Ferrum Packaging AG and Swiss Can Machinery AG exemplify Swiss-engineered tooling dominance for irregular can geometries. JBT Corporation occupies a position among North American service-dense integrators leveraging high-volume beverage contract anchoring. Krones AG sits within the filling-line integration archetype, extending brewery control system capability to seamer placement in greenfield projects. These three represent distinct strategic postures: Alpine precision specialization, continental service network density, and end-to-end line integration.
| Leading Market Players |
|---|
| CFT Group |
| ZACMI |
| Ferrum Packaging AG |
| Toyo Seikan |
| Swiss Can Machinery AG |
| Pneumatic Scale Angelus |
| JBT Corporation |
| Hefei Zhongchen |
| Krones AG |
| Others |
Cost & Logistics Intelligence
Captive tooling production among Alpine precision specialists anchors both supply security and pricing power for high-specification seamer architectures. This backward integration into roll forming and chuck manufacturing insulates Ferrum Packaging AG and Swiss Can Machinery AG from raw material volatility while commanding premium positioning against North American service-integrators.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across equipment tiers. OEMs like JBT Corporation and Krones AG bundle uptime commitments with hardware sales, while regional distributors in Colorado and Oregon unbundle third-party maintenance for craft operators. Price differentiation hinges on ISO 9001-3-A dual certification burden and servo precision specifications, with electromechanical platforms commanding premiums over pneumatic legacy. Cost compression in semi-automatic tiers intensifies because aluminum alloy volatility forces tooling recalibration cost absorption. Craft beverage manufacturers exhibit highest price sensitivity; Coca-Cola and PepsiCo bottlers prioritize seam consistency metrics over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from FDA-validated beverage processors mandate multi-supplier qualification for critical tooling components. Geographic supply concentration centers on Switzerland, Germany, and the United States for precision roll forming and motion control systems. Raw material dependencies draw from 3104 and 3004 aluminum alloys, high-grade bearing steel, and servo drive electronics. Single-source vulnerability from Bavarian and Baden-Württemberg tooling specialists creates structural risk for North American assemblers. Distribution runs through OEM-direct channels for fully automatic lines and regional distributors for batch-flexible semi-automatic units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's FSSAI-mandated formalization and Germany's deposit-return scheme retrofit cycles, with regulatory compliance cost differentials creating first-mover windows for service network establishment.
For Market Incumbents: Deploy certification leverage to lock out mid-tier competitors lacking dedicated compliance functions. JBT Corporation and Krones AG should deepen ISO 9001-3-A dual certification infrastructure to extend documentation bottlenecks. Capacity addition in Maharashtra and Karnataka industrial corridors captures India's FSSAI-mandated shelf-stable formalization before local assemblers mature. Threat of mechatronics talent scarcity from automotive sector competition demands accelerated servo tuning specialist recruitment. For New Entrants and Emerging Players: Launch via mobile canning operator channels in Colorado and Oregon where after-sales service unbundling fragments OEM relationships. India's dairy and RTD tea segments offer most penetrable white-space under FSSAI pressure. Pet food processors pivoting from retort pouches to metal cans create specification entry points for irregular geometry expertise without challenging beverage incumbents head-on. For Investors and Strategic Acquirers: Roll-up economics work for regional distributor networks because OEM service contract fragmentation in craft beverage segments enables margin consolidation. Five-to-ten year viability hinges on electromechanical platform transition completion before pneumatic legacy strands chemical packaging assets. Acquisition target archetype: Alpine precision tooling specialists with Swiss-engineered chuck IP and established Notified Body relationships. Signal to watch: FSSAI enforcement intensity in Maharashtra and Karnataka as Indian beverage packaging formalization accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tooling Manufacturing | Captive chuck production insulates Ferrum Packaging AG from Alpine single-source vulnerability. |
| Local Service Network Establishment | Maharashtra and Karnataka presence captures FSSAI-mandated Indian dairy formalization demand. |
| CE Marking Acceleration Program | Established Notified Body relationships compress EU Machinery Directive approval timelines. |
| Predictive Maintenance Platform Launch | Uptime commitments bundled with hardware sales compress traditional OEM service revenue models. |
| Water-Cooled Chuck Development | Italian tomato paste packagers pilot thermal management ahead of EU F-Gas Regulation deadlines. |
Research Approach
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through customs data and SEC filings, technical specification review — were reconciled to construct segment-level demand estimates. Stakeholder roles included maintenance directors at Coca-Cola and PepsiCo bottlers, aftermarket service heads at JBT Corporation and Krones AG, and craft brewery operators in Colorado and Oregon. Secondary sources encompassed FDA food-contact notification databases, EU Machinery Directive guidance documents, and FSSAI shelf-stable standard notifications. Bottom-up equipment shipment tallies and top-down beverage packaging capital expenditure flows were cross-referenced for triangulation.
Historical shipment trajectories were cross-referenced against panel input from seamer OEM technical directors and filling-line integrators. Segmentation dimensions modeled across the analysis window encompassed equipment automation tier, end-use industry vertical, technology architecture, and regional regulatory cluster. CAGRs were derived from slope consistency tests across historical baselines and forward projection panels. Industry-specific forecast inputs included aluminum alloy specification migration timelines and deposit-return scheme implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price volatility and mechatronics talent scarcity conditions. Projections reflect assumptions regarding FSSAI enforcement consistency, EU F-Gas Regulation phasedown adherence, and servo platform R&D concentration. Deviation in FDA seam integrity protocol stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Packing Belt Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Packer Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Global Shrink Sleeve Applicator Market
Packaging Equipment
Rotary Band Heat Sealer Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Laser Coding Equipment Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Single Use Mixer Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Global 2-Shot Injection Molding Market