
 Industrial Heat Sealers Market | 2026-2036
Industrial Heat Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Heat Sealers Market Analytics
EU MDR is repositioning validation requirements for sterile barrier systems, forcing equipment upgrades across European pharmaceutical packaging lines. Bosch Packaging Technology leverages its integrated line solutions to sustain premium positioning in automated pouch sealing. Multivac anchors its competitive stance through deep specialization in vacuum chamber technology for medical device packaging. Ishida competes aggressively on inspection-integrated sealing systems for food processing applications.
Industrial heat sealers are thermal bonding machines that apply controlled temperature, pressure, and dwell time to fuse thermoplastic films, foils, or coated papers into hermetic seals, typically operating between 100°C and 300°C depending on substrate composition. These systems serve critical functions in maintaining product sterility, extending shelf life, and ensuring tamper evidence across pharmaceutical, food, and electronics supply chains. Pouch sealers dominate installed base volumes due to universal deployment across flexible packaging lines, while ultrasonic technology captures expanding share in electronics cleanrooms where thermal degradation of sensitive components must be avoided. Vacuum technology commands margin concentration in pharmaceutical applications where ISO 11607 compliance for sterile barrier integrity is mandatory.
FDA enforces 21 CFR Part 11 for electronic records in pharmaceutical sealing validation, while EU MDR imposes Unique Device Identification traceability on sterile packaging workflows. China's NMPA aligns with international sterile barrier standards through harmonized GB testing protocols, tightening market access for non-compliant equipment imports. Stakeholders must monitor regulatory divergence between FDA process validation requirements and EU MDR technical documentation demands when configuring global equipment portfolios.
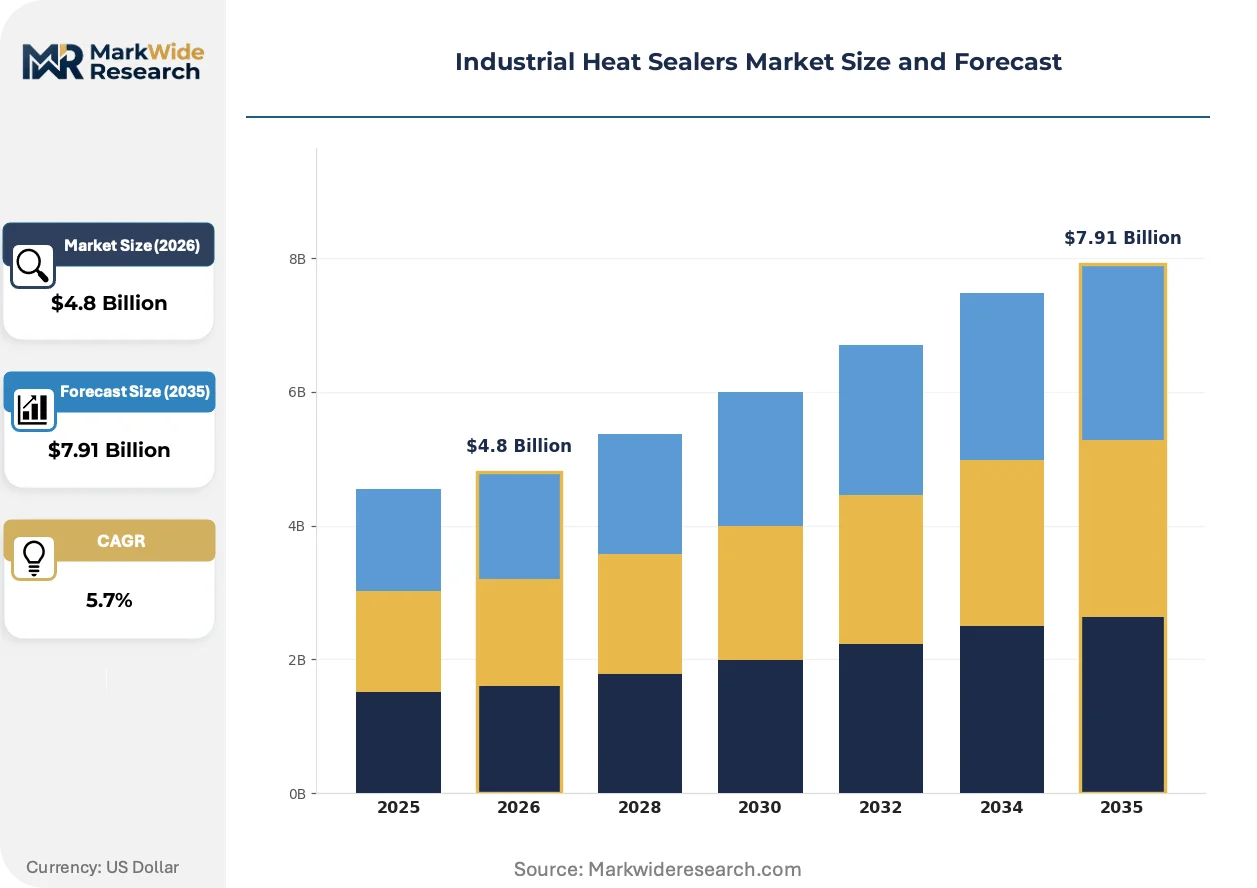
Market Dynamics
Impulse sealing technology is compressing energy consumption benchmarks across pharmaceutical cleanrooms while EU MDR traceability mandates force wholesale equipment replacement cycles in European sterile barrier packaging lines.
Growth Catalysts
- EU MDR traceability mandates:Pharmaceutical manufacturers in Germany are expanding automated sealing lines to comply with Unique Device Identification requirements for sterile packaging workflows.
- Electronics contract manufacturing clusters:Demand is concentrating in China's Yangtze River Delta where precision sealing for moisture-sensitive components drives equipment procurement.
- Impulse heat technology:Energy efficiency gains are displacing constant heat systems in cleanroom environments, reducing thermal cycling waste and utility costs.
Market Restraints
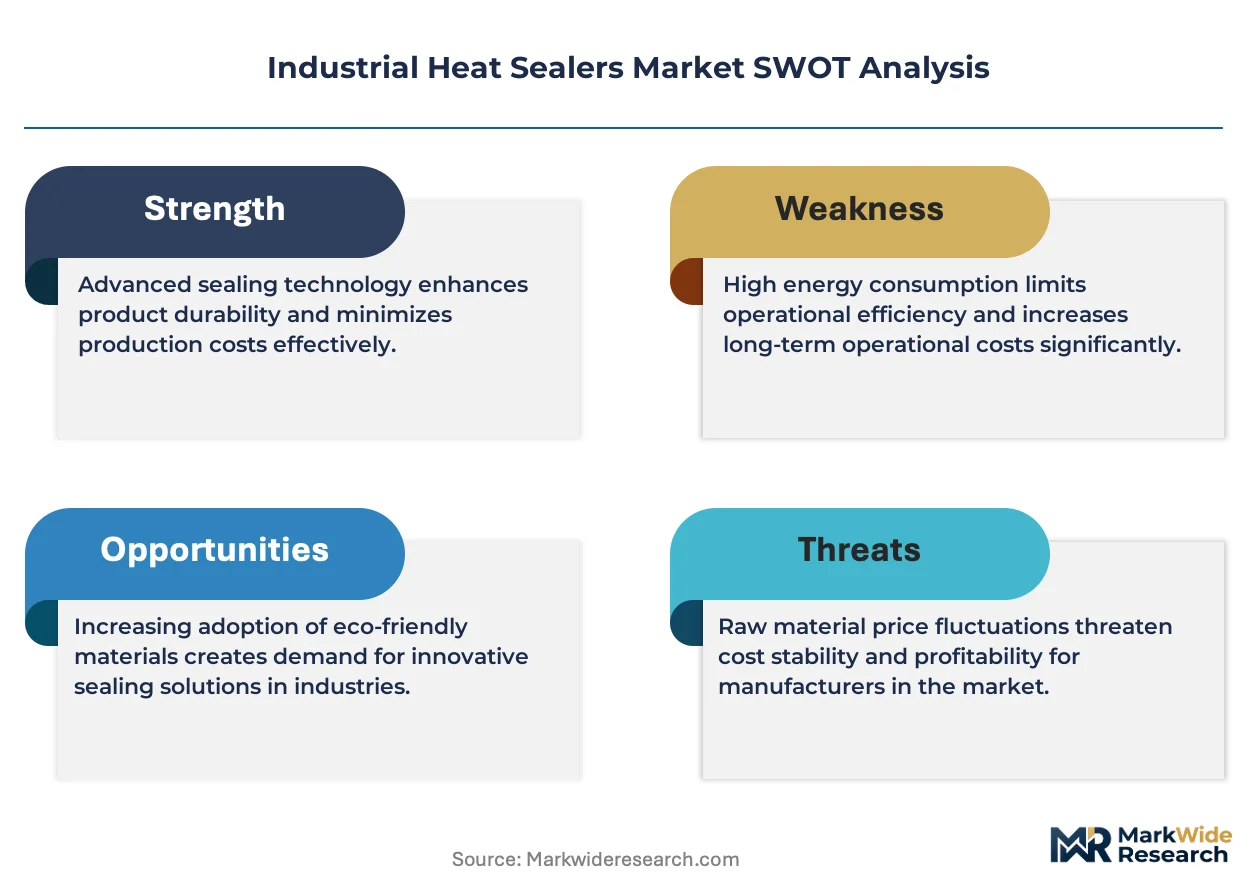
- Stainless steel and precision heating element costs:Input material volatility constrains margin flexibility for mid-tier equipment manufacturers serving price-sensitive food processing segments.
- Regional supply concentration:Control system electronics and servo motor sourcing clusters in East Asian manufacturing hubs, exposing lead time vulnerabilities to trade friction.
- Ultrasonic sealing substitution:Non-thermal bonding technology captures share in electronics cleanrooms where thermal degradation of sensitive substrates must be avoided.
Strategic Opportunities
- Indian pharmaceutical packaging expansion:CDSCO alignment with international sterile barrier standards creates equipment upgrade demand as domestic API manufacturers integrate downstream into finished dosage forms.
- Dual carbon policy compliance:China's MEE energy efficiency mandates accelerate replacement of legacy constant heat sealers with impulse systems in state-owned pharmaceutical facilities.
- Inspection-integrated sealing convergence:Vision system and leak detection technology bundling opens premium positioning in medical device packaging lines requiring ISO 11607 validation.
Industry Challenges
- Validation engineering talent scarcity:FDA 21 CFR Part 11 and EU MDR technical documentation requirements outpace qualified personnel supply for pharmaceutical equipment commissioning.
- Legacy system integration friction:Retrofitting impulse technology into existing constant heat production lines demands custom mechanical engineering and extended downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Heat Sealers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouch Sealers, Cap Sealers, Foot Sealers, Handheld Sealers Technology: Impulse, Constant Heat, Ultrasonic, Vacuum End User: Food Processing, Pharmaceutical, Electronics, Packaging Material: Plastic, Aluminum, Paper, Composite |
| Companies Covered | Bosch Packaging Technology, IMA Group, PAC Machinery, Allpax Products, Dorner Mfg, Multivac, Ishida, Leister Technologies, IMPAK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Heat Sealers Market Evolving Landscape
Equipment functionality is bifurcating between energy-optimized impulse systems for high-volume food and electronics applications and precision-validated sealing platforms for regulated pharmaceutical sterile barrier workflows.
Ultrasonic sealing technology is absorbing share in electronics cleanroom packaging where thermal bonding risks component damage from localized heat exposure. Semiconductor and display manufacturers in Korea and Taiwan are specifying non-thermal systems for moisture barrier bag sealing of static-sensitive devices. The technology is absorbing applications previously dominated by constant heat impulse sealers, compressing the addressable market for thermal systems in precision electronics segments.
EU MDR sterile barrier documentation requirements are forcing equipment architecture changes across European pharmaceutical packaging lines. Technical file compilation for ISO 11607 compliance now demands integrated process validation data capture, pressure traceability, and seal integrity documentation. Vacuum chamber sealing systems for medical device pouches face the most intensive reconfiguration burden as notified bodies enforce stricter design dossier scrutiny.
Buyer preference is consolidating around equipment-as-a-service models that unbundle capital expenditure from validation support and maintenance obligations. Contract manufacturers in China's Yangtze River Delta increasingly specify operational leasing with embedded technical service rather than outright equipment purchase. Pharmaceutical CDMOs in Switzerland and Germany are piloting similar arrangements to preserve balance sheet flexibility during EU MDR transition periods.
Industrial Heat Sealers Market Segmentation
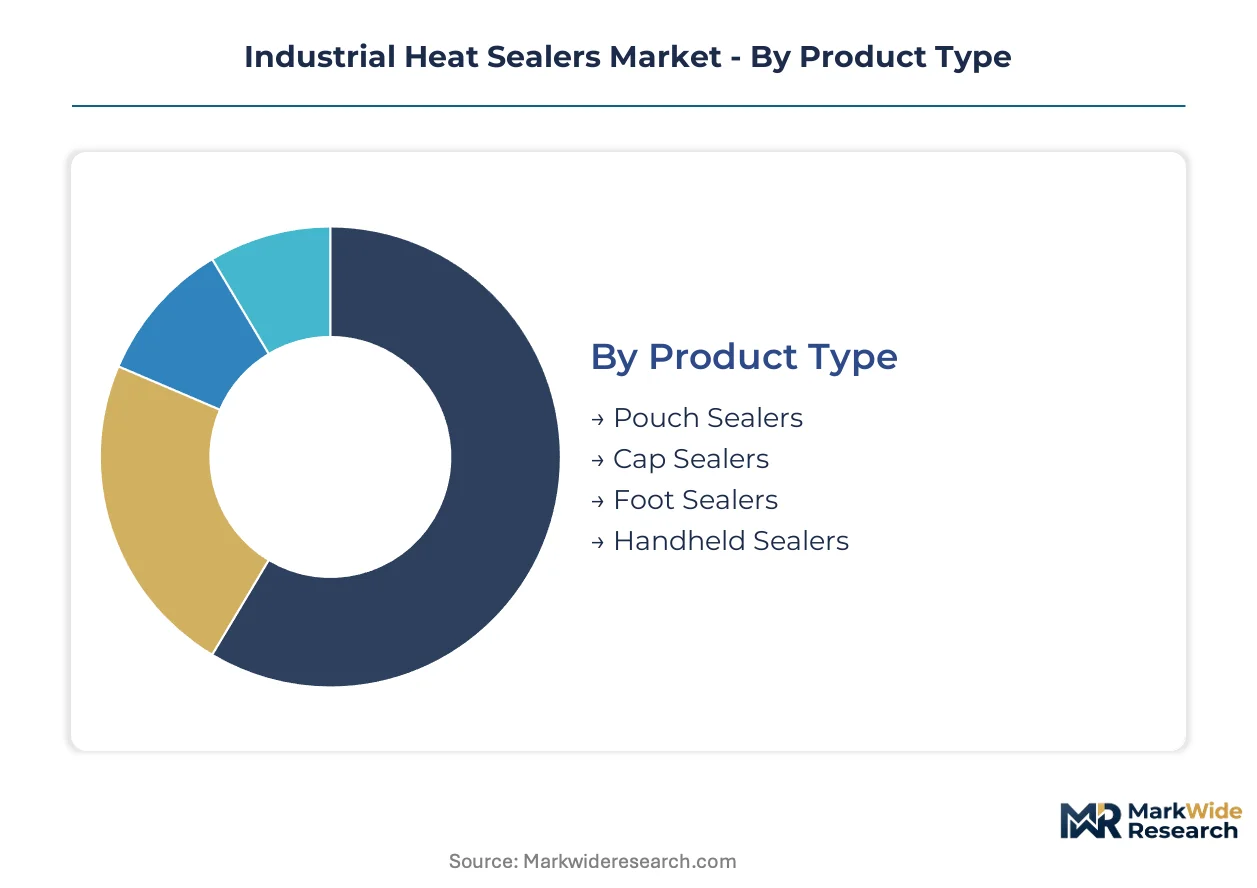
Equipment specification varies sharply across sealing applications, with thermal profile requirements and validation burdens diverging between food throughput demands and pharmaceutical sterile barrier mandates. Buyers prioritize energy efficiency in high-volume lines while precision validation dominates regulated medical packaging procurement.
Product Type:
Capital intensity and line integration depth drive purchasing decisions, with automated pouch systems commanding premium positioning against portable alternatives.
- Pouch Sealers:Continuous-band and rotary configurations fuse thermoplastic films at 100-300°C with controlled dwell pressure for flexible packaging lines. Pharmaceutical manufacturers in Germany deploy validated pouch systems for EU MDR sterile barrier workflows, integrating vacuum draw-down and seal integrity verification.
- Cap Sealers:Induction and conduction systems apply electromagnetic or conductive heat to aluminum foil liners for bottle and jar closure hermeticity. Food processors in China's Yangtze River Delta specify high-speed cap sealing for beverage export lines, prioritizing throughput over thermal precision.
- Foot Sealers:Pedal-actuated impulse units deliver portable thermal bonding for low-volume operations and field repair applications.
- Handheld Sealers:Battery-powered and corded impulse guns enable mobile sealing for warehouse logistics and emergency packaging restoration.
Pouch sealers lead on scale; handheld sealers lead on momentum as contract manufacturers adopt flexible deployment models.
Technology:
Energy consumption benchmarks and substrate thermal sensitivity determine technology selection across cleanroom and production floor environments.
- Impulse:Resistive heating elements activate only during seal cycle, cutting energy waste versus constant heat systems. China's MEE dual carbon policy accelerates impulse adoption in state-owned pharmaceutical facilities, displacing legacy constant heat infrastructure.
- Constant Heat:Maintained temperature platens deliver continuous sealing for high-throughput food processing where thermal cycling delays are unacceptable.
- Ultrasonic:High-frequency mechanical vibration generates frictional heat at material interface without bulk temperature rise. Electronics manufacturers in Korea specify ultrasonic systems for moisture barrier bags protecting static-sensitive semiconductors, avoiding thermal degradation risks.
- Vacuum:Chamber systems extract atmosphere before sealing to preserve sterile barrier integrity for medical device packaging.
Impulse technology dominates installed base volume; ultrasonic configurations are climbing the fastest as electronics cleanroom specifications tighten.
End User:
Regulatory validation burden and throughput economics create distinct procurement profiles across vertical applications.
- Food Processing:High-speed pouch and cap sealing for shelf-life extension and tamper evidence in packaged goods manufacturing.
- Pharmaceutical:Validated sterile barrier systems for ISO 11607 compliance, with integrated process data capture for FDA 21 CFR Part 11 and EU MDR traceability.
- Electronics:Precision moisture barrier sealing for static-sensitive components in semiconductor and display manufacturing clusters.
- Packaging:Contract manufacturing services spanning multiple substrate types with flexible equipment configurations.
Food processing leads on scale; pharmaceutical leads on equipment value per line.
Material:
Substrate thermal properties and barrier performance requirements dictate sealing temperature windows and validation protocols.
- Plastic:Polyethylene, polypropylene, and polyester films dominate flexible packaging with melt temperatures between 110-260°C.
- Aluminum:Foil laminates and induction-sealable liners provide oxygen and moisture barriers for pharmaceutical and food applications.
- Paper:Polyethylene-coated papers and wax-impregnated stocks for disposable medical packaging and quick-service food containers.
- Composite:Multi-layer structures combining plastic, foil, and paper substrates for specialized barrier performance.
Plastic leads on scale; composite materials lead on specification intensity for sterile barrier applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German validation engineers and Chinese electronics technicians anchor the geographic distribution of heat sealer procurement, with regulatory divergence between FDA and EU MDR creating distinct equipment specification clusters.
Germany
Pharmaceutical CDMOs in Baden-Württemberg expand automated pouch sealing lines to satisfy EU MDR sterile barrier documentation. The German national pharmaceutical regulator enforces ISO 11607 validation protocols through notified body scrutiny. Stuttgart and Karlsruhe host concentrated medical device packaging operations where vacuum chamber systems face intensive reconfiguration.
China
Electronics contract manufacturers in the Yangtze River Delta drive precision sealing demand for moisture-sensitive semiconductor components. The Ministry of Ecology and Environment accelerates impulse technology adoption through dual carbon energy efficiency mandates. Suzhou and Wuxi cluster precision packaging operations where equipment-as-a-service leasing models displace outright purchase.
United States
Food processors in the Midwest prioritize high-throughput constant heat systems for shelf-life extension applications. FDA enforces 21 CFR Part 11 electronic records requirements for pharmaceutical sealing validation workflows. Chicago and Minneapolis anchor flexible packaging manufacturing where stainless steel input costs constrain mid-tier equipment margins.
South Korea
Display and semiconductor manufacturers specify ultrasonic sealing systems to avoid thermal degradation of static-sensitive substrates. The Korean Ministry of Trade, Industry and Energy supports cleanroom packaging technology upgrades through industrial innovation programs. Seoul and Suwon concentrate electronics packaging operations where non-thermal bonding displaces legacy impulse systems.
India
Domestic API manufacturers integrate downstream into finished dosage forms, creating sterile barrier equipment demand in Maharashtra and Gujarat. CDSCO alignment with international standards drives validation-intensive procurement decisions. Mumbai and Ahmedabad host expanding pharmaceutical packaging clusters where ISO 11607 compliance separates premium from commodity equipment tiers.
Industrial Heat Sealers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment specification tiers, with the vendor base separating into consolidated premium-positioned integrators and fragmented regional fabricators. Three strategic archetypes dominate: integrated line solution providers, vacuum chamber technology specialists, and inspection-integrated system vendors. Capacity expansion and technology licensing represent the dominant competitive moves, with players pursuing geographic reach through partnership networks rather than direct investment.
Among Germany-based equipment integrators, Bosch Packaging Technology and Multivac occupy positions anchoring the premium tier through deep line integration and vacuum specialization respectively. PAC Machinery represents the North American mid-market archetype with focused pouch sealing configurations. These three exemplify how geographic origin and corporate structure signal strategic positioning: GmbH and AG suffixes cluster around validated pharmaceutical systems, while Inc.-structured entities concentrate on food processing throughput optimization.
| Leading Market Players |
|---|
| Bosch Packaging Technology |
| IMA Group |
| PAC Machinery |
| Allpax Products |
| Dorner Mfg |
| Multivac |
| Ishida |
| Leister Technologies |
| IMPAK Corporation |
| Others |
Value Network & Pricing Analysis
Impulse heat technology migration simultaneously compresses energy operating costs and concentrates procurement leverage among German and Chinese system integrators capable of delivering validated pharmaceutical lines. Equipment-as-a-service leasing models in China's Yangtze River Delta unbundle capital expenditure from technical support, reshaping how contract manufacturers evaluate total cost of ownership against upfront purchase alternatives.
Pricing Analysis
Equipment-as-a-service bundling separates premium-positioned integrators from transaction-focused fabricators across three distinct pricing tiers. Price differentiation rests on EU MDR validation documentation depth and after-sales service embedding, with pharmaceutical CDMOs in Switzerland and Germany showing lowest price sensitivity due to compliance risk exposure. Cost compression in mid-tier food processing equipment intensifies as stainless steel input volatility constrains margin flexibility. Portable foot and handheld sealers face acute buyer price sensitivity among warehouse logistics operators prioritizing deployment flexibility over performance specifications.
Supply Chain Analysis
Validation engineering talent scarcity in Germany and servo motor sourcing concentration in East Asian manufacturing hubs tether equipment delivery timelines to workforce availability fluctuations. Control system electronics and precision heating elements draw from China, Japan, and South Korea, creating single-source vulnerability for semiconductor-dependent automation components. Tariff exposure on precision motion control imports extends lead times for European pharmaceutical line expansions. Distribution runs through authorized integrator networks rather than direct manufacturer sales, with regional service capabilities determining competitive positioning in sterile barrier validation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in impulse technology retrofits and inspection-integrated system bundling, with energy efficiency gains and ISO 11607 compliance premiums offsetting stainless steel cost volatility.
For Market Incumbents: Hedge against ultrasonic sealing substitution in electronics cleanrooms by deepening vacuum chamber specialization for EU MDR pharmaceutical workflows. Acquire validation engineering capabilities in Germany and Switzerland to address talent scarcity constraining equipment commissioning timelines. Expand equipment-as-a-service leasing infrastructure in China's Yangtze River Delta to match contract manufacturer procurement preferences. For New Entrants and Emerging Players: Ultrasonic sealing platforms for moisture-sensitive semiconductor packaging offer a technology-first wedge into Korea's display manufacturing clusters. Target Indian pharmaceutical packaging expansion in Maharashtra and Gujarat where CDSCO alignment with international standards creates upgrade demand among domestic API manufacturers integrating downstream. Pursue partnership-based go-to-market models with established regional integrators lacking non-thermal bonding expertise. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier pouch sealing fabricators serving food processing segments facing stainless steel margin compression. Long-term viability hinges on regulatory validation depth rather than throughput specifications, favoring targets with embedded pharmaceutical compliance capabilities. Monitor EU MDR notified body enforcement intensity as the inflection signal for sterile barrier equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Impulse Technology Retrofit Programs | China's MEE dual carbon policy accelerates state-owned pharmaceutical facility upgrades. |
| Validation Engineering Talent Acquisition | FDA 21 CFR Part 11 and EU MDR documentation demands outpace qualified personnel supply. |
| Equipment-as-a-Service Leasing Expansion | Yangtze River Delta contract manufacturers specify operational leasing over capital purchase. |
| Ultrasonic Sealing Platform Development | Korea's semiconductor manufacturers specify non-thermal systems for static-sensitive components. |
| Inspection-Integrated System Bundling | Vision system convergence opens premium positioning in ISO 11607 medical device lines. |
Research Methodology
Coverage spans Germany, China, the United States, South Korea, and India, with primary inputs from each market's equipment procurement clusters. The approach combines interviews with pharmaceutical packaging engineers, electronics contract manufacturing technicians, food processing plant managers, and aftermarket service directors alongside secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and customs trade flow data. Bottom-up equipment shipment analysis and top-down end-use demand modeling provide triangulation across the analysis window.
Rate-of-change decomposition separates volume growth from price mix effects across technology type, end-use vertical, and regional regulatory cluster dimensions. The analytical framework models impulse, constant heat, ultrasonic, and vacuum configurations through the projection horizon, with CAGRs derived from equipment replacement cycle analysis and regulatory mandate timing. Forecast inputs include EU MDR implementation enforcement trajectories, China's dual carbon policy compliance deadlines, and electronics manufacturing cluster expansion plans in the Yangtze River Delta and Seoul-Suwon corridor.
The model holds under steady regulatory enforcement intensity and stable trade flow conditions; deviation in tariff regimes or notified body capacity constraints would shift equipment procurement timing. Forecasts reflect documented assumptions regarding technology substitution rates and validation engineering labor availability. Practitioners should monitor EU MDR technical documentation scrutiny levels and East Asian control component export licensing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Plastic Waste Sorting Equipment Market
Packaging Equipment
Global Pack Conveyors Market
Packaging Equipment
Bottle-Capping Equipment Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Depalletizers Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Packaging Equipment Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Refrigerated Display Cases Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Inflatable Void Fill System Market