
 Multi-Layer Blow Molded Containers Market | 2026-2036
Multi-Layer Blow Molded Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Layer Blow Molded Containers Market Outlook
The performance gap between premium barrier-grade containers and commodity single-use packaging is broadening. Amcor plc leverages its global manufacturing footprint to sustain high-barrier product lines for pharmaceutical and food clients. Berry Global Inc. anchors North American supply through extensive blow molding capacity and resin compounding expertise.
Multi-layer blow molded containers are engineered plastic vessels produced through sequential extrusion or co-extrusion blow molding, combining distinct polymer layers to achieve oxygen barrier, moisture resistance, or chemical compatibility within wall thicknesses typically ranging from 0.5 to 3.0 millimeters. These structures serve critical protective functions for oxygen-sensitive foods, aggressive chemicals, and UV-degradable pharmaceuticals. Bottles command the largest volume share within food and beverage applications where extended shelf life drives specification. Polyethylene dominates material selection for chemical and household segments due to cost-efficiency and processing latitude, while PET layers penetrate premium beverage and personal care lines where clarity and recyclability matter.
FDA food contact regulations in the United States, EFSA migration limits under EU framework, and REACH substance restrictions collectively dictate layer composition, adhesive selection, and recycling pathway documentation. Compliance cost is rising fastest for converters serving multiple jurisdictions with divergent notification requirements. Stakeholders must evaluate whether regional certification investments or standardized global formulations offer superior capital efficiency as barrier specifications tighten.
Market Dynamics
Europe's F-Gas Regulation and REACH substance restrictions are forcing converters to reformulate adhesive layers and document recycling pathways, compressing margins for multi-jurisdiction suppliers while creating compliance moats for specialized compounders.
Growth Catalysts
- High-barrier food packaging procurement:Retailers and brand owners specify oxygen transmission rates below 0.1 cc/package/day for extended shelf-life dairy and ready-to-eat meals, pulling demand toward ethylene vinyl alcohol coextrusion systems.
- REACH SVHC notification thresholds:The European Chemicals Agency's tightening substance restrictions compel layer redesign away from legacy adhesives, creating replacement demand for compliant tie-layer technologies.
- Germany's chemical processing corridor:Industrial cluster concentration around Ludwigshafen and Leverkusen generates captive demand for fluoropolymer-lined chemical containers with multi-layer chemical resistance.
Market Restraints
- Ethylene vinyl alcohol resin supply concentration:Three Asian petrochemical groups control over 70 percent of global EVOH capacity, exposing converters to input price volatility and allocation risk during supply shocks.
- Multi-layer recycling incompatibility:Current mechanical recycling infrastructure cannot separate bonded polymer layers, limiting post-consumer feedstock qualification for food-contact applications under FDA and EFSA frameworks.
- Fluoropolymer layer substitution pressure:Per- and polyfluoroalkyl substance restrictions under EU and US state-level regulations threaten barrier performance in aggressive chemical applications.
Strategic Opportunities
- India's packaged food modernization:FSSAI enforcement of food-grade packaging standards and cold chain expansion create first-mover advantage for barrier-certified container suppliers in dairy and edible oils.
- Digital printing integration:Direct-to-object inkjet systems eliminate label substrates and enable lot-level traceability, converging decoration technology with smart packaging functionality for pharmaceutical serialization mandates.
- EU Green Deal packaging waste targets:The 2030 recyclability mandate and extended producer responsibility fee structures reward designs with compatible layer chemistries and monomaterial-like separation characteristics.
Industry Challenges
- Coextrusion die engineering expertise:The specialized knowledge required for multi-manifold die design and layer thickness distribution control concentrates among retiring technical specialists, constraining capacity expansion.
- Migration testing protocol complexity:Simulant selection and contact condition validation for novel layer combinations extend certification timelines by 12-18 months under EU 10/2011 and FDA 21 CFR frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Layer Blow Molded Containers Market |
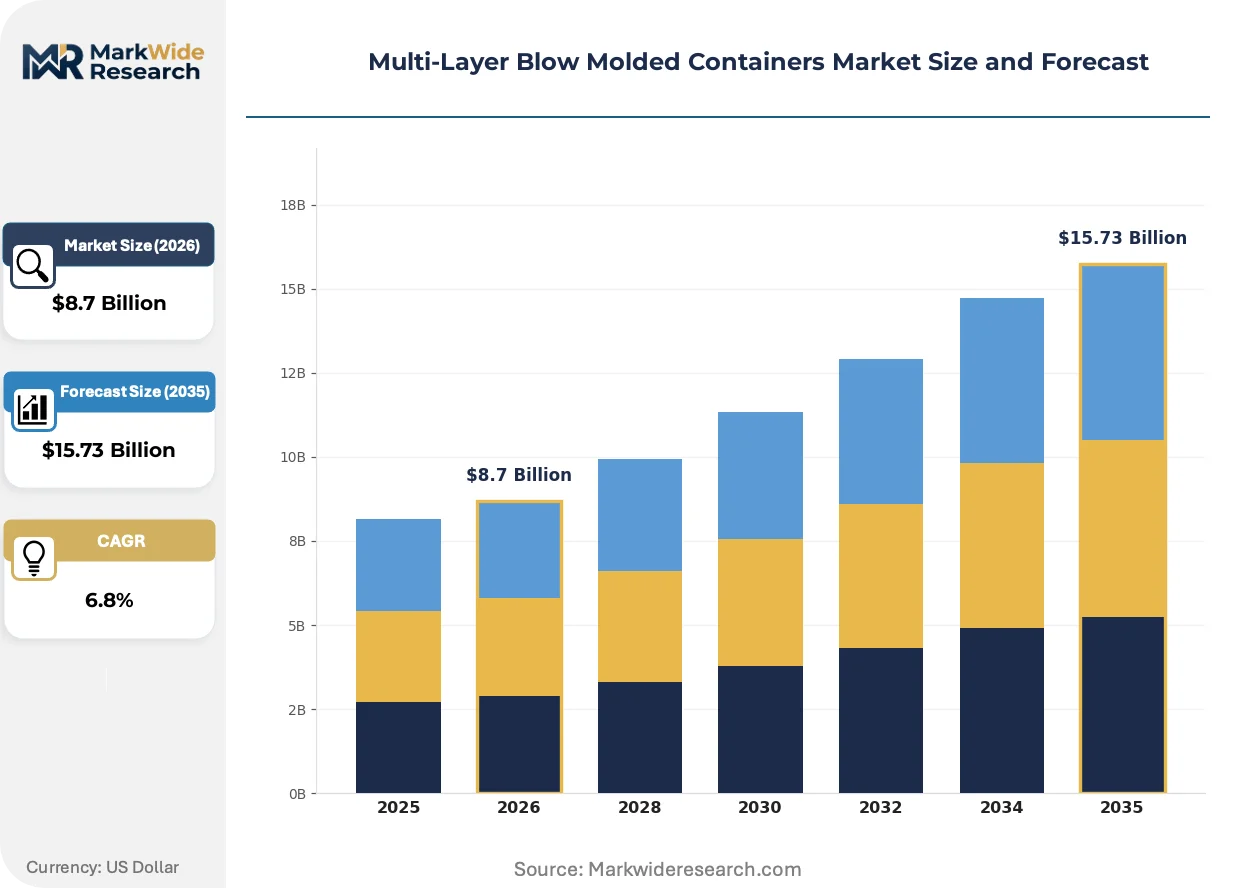
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jars, Bottles, Containers, Pails Material: Polyethylene, Polypropylene, PET, PLA Application: Food Packaging, Beverage Packaging, Personal Care, Household Products End User: Food Industry, Pharmaceutical Sector, Consumer Goods, Chemical Sector |
| Companies Covered | Amcor plc, Graham Packaging Company, Berry Global Inc., Plastipak Holdings, Inc., ALPLA, Comar, Silgan Holdings, Alpha Packaging, Resilux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Layer Blow Molded Containers Market Strategic Shifts
Digital process control and material informatics are compressing development cycles for barrier formulations while regulatory pressure on fluorinated chemistries accelerates search for non-fluorine high-barrier alternatives.
Sequential coextrusion blow molding with real-time thickness gauging is automating layer distribution control across pharmaceutical and food container production. Contract manufacturers serving FDA-regulated drug packaging are adopting these systems fastest, replacing manual sampling protocols with closed-loop feedback that reduces material giveaway and deviation reports.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is forcing reformulation of polyurethane insulation layers in temperature-controlled containers. German and French converters are pivoting toward hydrocarbon and hydrofluoroolefin alternatives, though thermal performance gaps persist in ultra-low-temperature vaccine distribution applications.
Brand-owner sustainability scorecards now weight post-consumer recycled content and design-for-recycling certification above unit cost in supplier selection. Major European retailers are consolidating blow molded container procurement around converters with documented recycling pathway partnerships, compressing vendor pools and privileging integrated resin-to-container operations with chemical recycling offtake agreements.
Multi-Layer Blow Molded Containers Market Segmentation
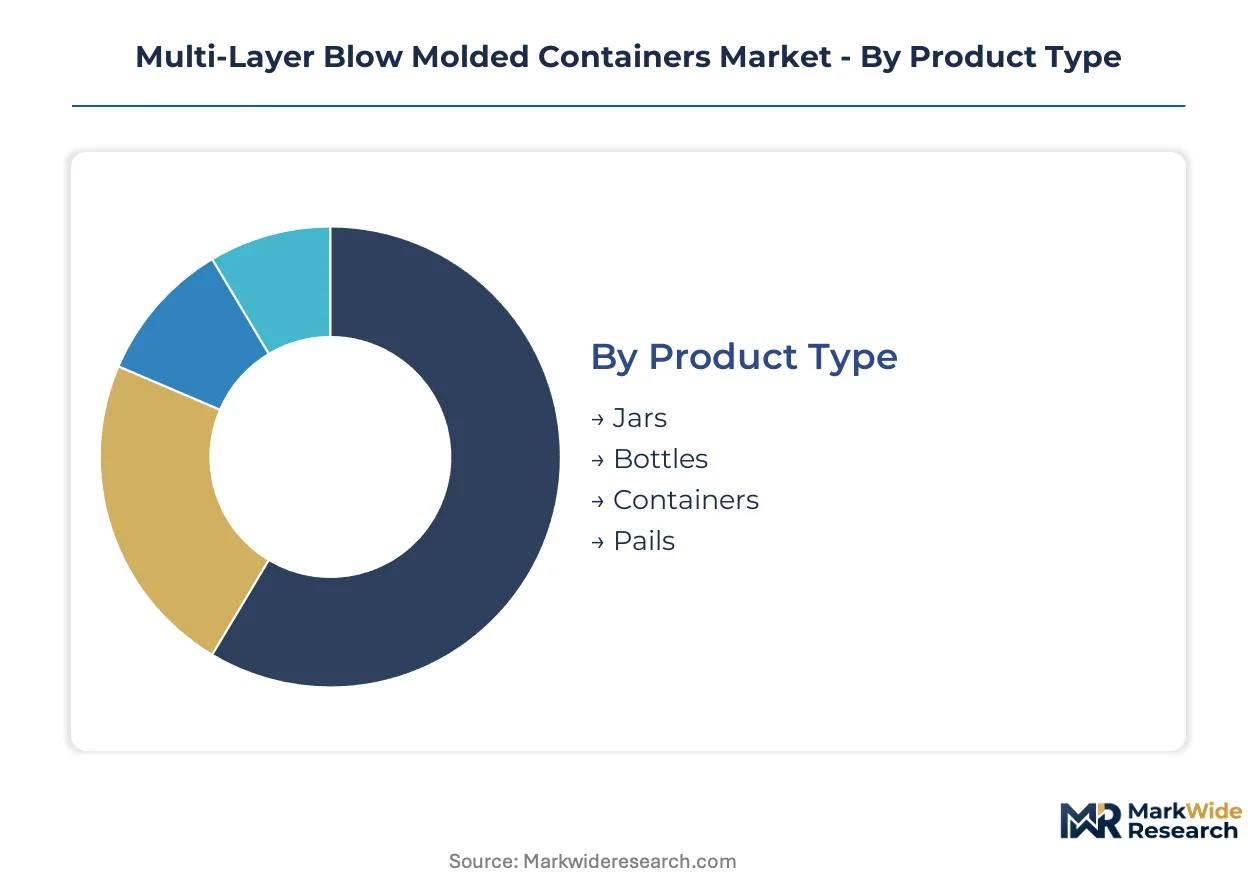
Multi-layer blow molded containers serve divergent performance requirements across oxygen-sensitive foods, aggressive chemicals, and UV-degradable pharmaceuticals. Segment-specific barrier specifications dictate coextrusion system complexity, resin selection, and compliance documentation burden.
Product Type:
Capital intensity escalates with container complexity and layer count, with pharmaceutical-grade bottles demanding the most sophisticated multi-manifold die systems.
- Bottles:Cylindrical vessels with neck finishes accommodate screw caps and dispensing closures for beverages, condiments, and liquid pharmaceuticals. Extended shelf-life dairy and ready-to-eat meal packaging in Germany's retail channel specify oxygen transmission rates below 0.1 cc/package/day, pulling procurement toward ethylene vinyl alcohol coextrusion systems.
- Containers:Rectangular and oval configurations optimize pallet density for chemical and household product distribution. Ludwigshafen's chemical processing corridor generates captive demand for fluoropolymer-lined variants with multi-layer chemical resistance against aggressive solvents.
- Jars:Wide-mouth configurations serve viscous food products and personal care creams requiring scoop access and resealability.
- Pails:Industrial-scale vessels with handles and tamper-evident lids address bulk chemical and food service applications.
Bottles absorb the bulk of installed capacity; containers are expanding most quickly.
Material:
Raw material selection determines processing latitude, barrier performance, and end-of-life pathway eligibility under evolving EFSA and FDA frameworks.
- Polyethylene:HDPE and LDPE layers dominate cost-driven chemical and household segments due to extrusion efficiency and moisture resistance. REACH SVHC notifications are forcing reformulation away from legacy adhesive tie-layers, creating replacement demand for compliant polyethylene-based bonding technologies.
- PET:Clarity and established mechanical recycling infrastructure position polyethylene terephthalate in premium beverage and personal care lines. EU Green Deal packaging waste targets reward PET's monomaterial-like separation characteristics compared to incompatible multi-layer alternatives.
- Polypropylene:High melting point and chemical resistance suit hot-fill applications and aggressive product contact.
- PLA:Bio-based polylactic acid layers address brand-owner sustainability scorecards though thermal limitations constrain high-barrier applications.
Polyethylene commands the greatest production volume; PET climbs the fastest on premium beverage demand.
Application:
Application-driven specification divergence creates distinct supplier pools, with food and pharmaceutical converters maintaining separate certification portfolios.
- Food Packaging:Oxygen and moisture barriers extend shelf life for dairy, edible oils, and ready-to-eat meals. India's FSSAI enforcement of food-grade standards and cold chain expansion create first-mover positioning for barrier-certified suppliers in Mumbai and Delhi industrial zones.
- Beverage Packaging:CO2 retention and oxygen exclusion preserve carbonation and flavor stability in beer, juice, and functional drinks.
- Personal Care:UV resistance and fragrance barrier properties protect premium formulations from degradation and leakage.
- Household Products:Chemical compatibility and child-resistant closure integration address bleach, detergent, and solvent containment.
Food packaging anchors supplier revenue; beverage applications gain share fastest on premiumization trends.
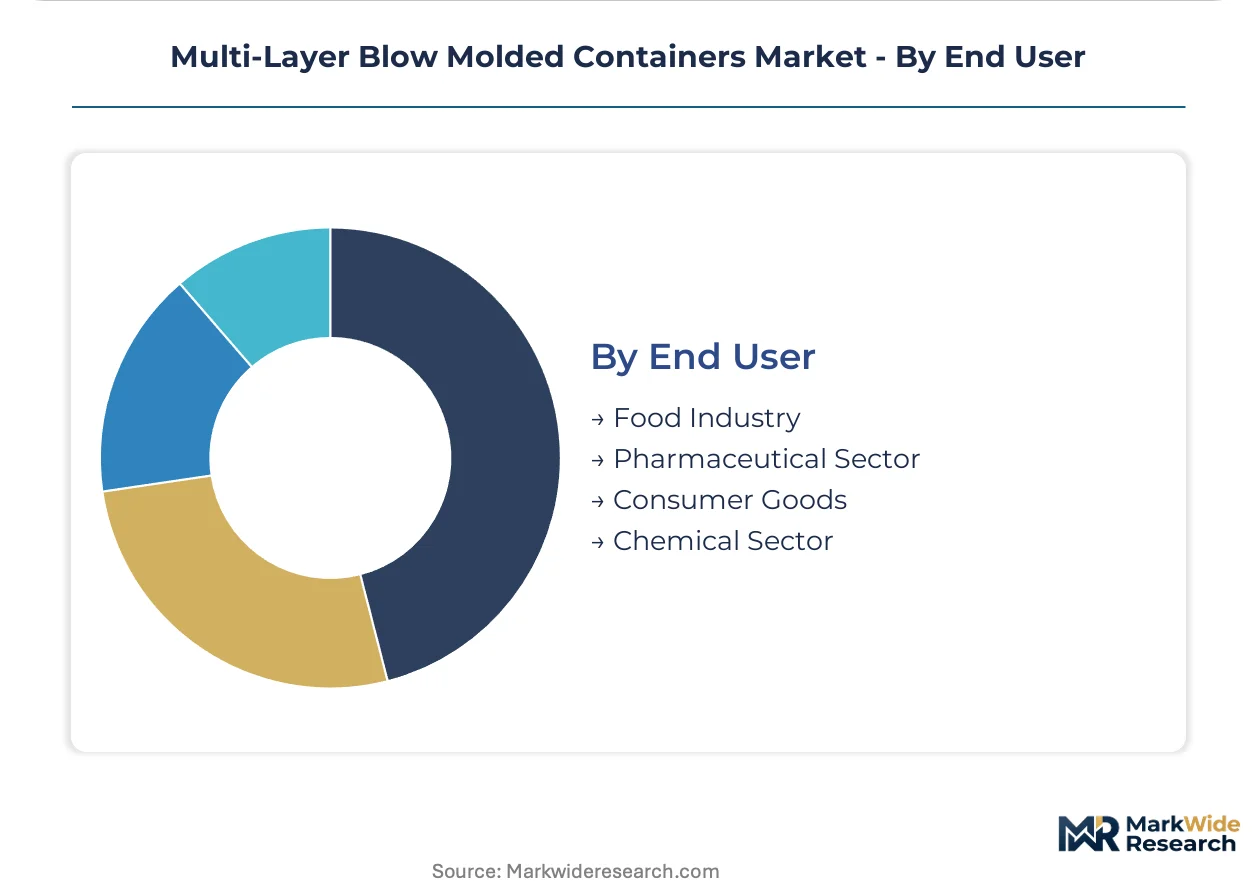
End User:
End-user regulatory exposure shapes converter capability requirements, with pharmaceutical and food sectors imposing the most stringent migration testing protocols.
- Food Industry:Processors and retailers specify lot-level traceability and extended shelf-life performance. EU 10/2011 migration limits and FDA 21 CFR food contact notifications collectively dictate layer composition and adhesive selection for converters serving dual-jurisdiction brand owners.
- Pharmaceutical Sector:FDA-regulated drug packaging demands real-time thickness gauging and closed-loop process control to minimize deviation reports. Sequential coextrusion systems with automated layer distribution are replacing manual sampling protocols fastest in this segment.
- Consumer Goods:Brand-owner sustainability scorecards weight post-consumer recycled content and design-for-recycling certification above unit cost in supplier selection.
- Chemical Sector:Aggressive product contact requires fluoropolymer or ethylene vinyl alcohol barrier layers with documented chemical resistance.
The food industry consumes the majority of unit volume; pharmaceutical sector procurement shows the steepest expansion trajectory on serialization and traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen's chemical processing corridor anchors European demand for fluoropolymer-lined containers, while procurement concentrates in Germany's industrial clusters and extends through cross-border supply chains into neighboring jurisdictions.
Germany
BASF's Ludwigshafen complex and Leverkusen's Bayer operations generate captive demand for aggressive chemical containment. REACH SVHC notifications compel layer redesign away from legacy adhesives, tightening compliance documentation. The Rhine-Neckar metropolitan region hosts specialized compounders developing compliant tie-layer technologies for EVOH barrier systems.
United States
FDA-regulated pharmaceutical packaging drives specification for real-time thickness gauging systems. EPA and state-level PFAS restrictions threaten fluoropolymer barrier layers in chemical applications. New Jersey's pharmaceutical corridor and Texas's petrochemical complexes concentrate blow molding capacity for dual food-contact and industrial segments.
India
FSSAI enforcement of food-grade packaging standards accelerates barrier-certified container procurement for dairy and edible oils. Cold chain infrastructure expansion in Mumbai and Delhi industrial zones creates first-mover positioning for compliant suppliers. Maharashtra's packaging converters are upgrading coextrusion capacity to meet migration testing protocols.
China
GB standards for food contact materials and dual carbon goals reshape resin selection and recycling pathway documentation. Yangtze River Delta converters serve multinational brand owners with multi-jurisdiction compliance requirements. Shanghai's chemical industrial zone demands fluoropolymer alternatives for aggressive solvent containment.
France
ANSM pharmaceutical serialization mandates pull demand toward closed-loop process control systems. EU Green Deal packaging waste targets reward designs with monomaterial-like separation characteristics. Lyon-Saint-Étienne's chemical valley generates demand for high-barrier containers in specialty chemical distribution.
Multi-Layer Blow Molded Containers Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier certification tiers, with pharmaceutical-grade qualification creating separation from standard food-contact supply. The vendor base stratifies between integrated resin-to-container operators, specialized pharmaceutical converters, and regional packaging fabricators. Three archetypes dominate: global diversified packaging groups with multi-jurisdiction certification portfolios, mid-cap specialists with captive EVOH compounding relationships, and contract manufacturers serving FDA-regulated drug packaging. Capacity expansion and recycling pathway partnerships constitute the dominant competitive moves as brand-owner sustainability scorecards reshape procurement criteria.
Among the integrated packaging groups, Amcor plc and Berry Global Inc. exemplify scale-driven archetypes with global manufacturing footprints sustaining high-barrier product lines. Graham Packaging Company occupies a position within the mid-cap specialist tier, representing converters with extensive blow molding capacity and resin compounding expertise anchored in North American supply chains. These three entities illustrate how certification depth and geographic coverage determine competitive positioning across divergent end-use specifications.
| Leading Market Players |
|---|
| Amcor plc |
| Graham Packaging Company |
| Berry Global Inc. |
| Plastipak Holdings, Inc. |
| ALPLA |
| Comar |
| Silgan Holdings |
| Alpha Packaging |
| Resilux |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical procurement committees and European chemical processors anchor demand concentration, binding pricing power to barrier certification tiers and REACH compliance documentation rather than commodity resin costs. This buyer structure elevates value-based contracting for oxygen transmission performance while compressing margins on standard food-contact grades.
Pricing Analysis
Yield-based pricing anchors pharmaceutical container contracts, with real-time thickness gauging guarantees and deviation report minimization commanding 40-60% premiums over standard food-contact tiers. Price differentiation separates FDA-validated serialization-ready lines from commodity dairy packaging, with EVOH barrier layers and compliant tie-layer adhesives as the primary cost drivers. Pricing pressure stems from Asian petrochemical EVOH supply concentration, exposing converters to allocation risk during supply shocks. Small regional fabricators serving household products exhibit the highest price sensitivity, while pharmaceutical contract manufacturers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany's Rhine-Neckar corridor and Texas's petrochemical complex operate hub-and-spoke patterns for fluoropolymer-lined chemical containers and high-barrier pharmaceutical bottles. Manufacturing concentrates in Germany, the United States, and China, with Yangtze River Delta converters serving multinational brand owners with multi-jurisdiction compliance requirements. Raw material sourcing draws from Asian EVOH resin producers, North American polyethylene compounders, and European adhesive specialists. Single-source vulnerability in ethylene vinyl alcohol supply creates structural exposure to petrochemical allocation decisions. Distribution runs through converter-direct pharmaceutical packaging partnerships and retailer-consolidated procurement pools for food applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with EVOH compounding capability and chemical recycling offtake agreements as the decisive upstream levers separating premium-margin players from commodity converters.
For Market Incumbents:Hedge against Asian EVOH supply concentration by securing captive compounding relationships or backward integration into barrier resin production. Pharmaceutical serialization mandates and EU Green Deal recyclability targets threaten converters without documented recycling pathway partnerships. Capacity expansion in India's Maharashtra and Delhi industrial zones captures FSSAI enforcement tailwinds while competitors face 12-18 month migration testing delays.
For New Entrants and Emerging Players:Mid-tier dairy processors in India's cold chain expansion zones represent the most penetrable buyer archetype, underserved by barrier-certified suppliers with FSSAI-compliant documentation. White-space targets include edible oil packaging in Mumbai's industrial corridor and temperature-controlled vaccine distribution containers using hydrocarbon-blown polyurethane insulation. A certification-first go-to-market angle, front-loading migration testing investment, bypasses incumbent compliance moats.
For Investors and Strategic Acquirers:The window for entry favors mid-cap specialists with captive EVOH relationships and pharmaceutical-grade qualification portfolios. Long-term viability hinges on integrated resin-to-container operations with chemical recycling offtake agreements, as brand-owner sustainability scorecards reshape procurement criteria. The signal to watch is EU extended producer responsibility fee structure implementation, which will accelerate vendor consolidation around documented recycling pathway holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Compounding | Captive barrier resin supply insulates against Asian petrochemical allocation volatility and REACH-driven reformulation cycles. |
| Chemical Recycling Offtake Partnerships | Documented recycling pathways qualify converters for EU Green Deal extended producer responsibility fee reductions and retailer sustainability scorecards. |
| Real-Time Thickness Gauging Deployment | Closed-loop process control minimizes pharmaceutical deviation reports and supports FDA-regulated drug packaging qualification. |
| FSSAI Certification Investment in India | First-mover positioning in Mumbai and Delhi industrial zones captures dairy and edible oil packaging modernization demand. |
| Hydrocarbon Blowing Agent Transition | EU F-Gas Regulation compliance for temperature-controlled containers preserves access to German and French vaccine distribution channels. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at blow molding facilities, procurement leads at pharmaceutical and food brand owners, distribution channel partners, and technical R&D directors specializing in multi-manifold die systems. Bottom-up capacity modeling triangulated against top-down demand segmentation validated volume estimates across the analysis window.
Reconciliation of production capacity databases, resin consumption customs records, and end-use procurement surveys informed the analytical framework. Segmentation dimensions modeled include product complexity tier, barrier performance specification, end-use regulatory exposure, and regional compliance cluster. CAGRs were derived from installed capacity expansion timelines and buyer procurement intention surveys. Industry-specific forecast inputs incorporated EVOH resin supply allocation patterns and pharmaceutical serialization mandate implementation trajectories.
Revisions become necessary when REACH SVHC notification thresholds tighten, F-Gas Regulation phase-down schedules accelerate, or Asian petrochemical EVOH supply experiences allocation disruption. Forecasts reflect documented assumptions about regulatory enforcement intensity and resin supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Oblong Container Market
Containers
Cups and Lids Market
Containers
Shipping Container Liners Market
Containers
APAC Container Technology Market
Containers
North America Plastic Bottles and Containers Market
Containers
Americas Container Technology Market
Containers
Global Cardboard Box and Container Market
Containers
Collapsible Food Packaging Containers Market
Containers
Takeout Containers Market
Containers
PVC Container Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Takeaway Containers Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Algeria Container Glass Market
Containers
Slip Lid Can Market
Containers
Injection Molding Containers Market