
 Blood Meal Market | 2026-2036
Blood Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Meal Market Intelligence
Advanced spray-drying and atomization technology is tilting the production landscape toward higher-purity, more soluble blood meal products. Darling Ingredients leverages its global rendering network to achieve significant economies of scale in processing. Allanasons Pvt Ltd specializes in supplying certified products to international markets from its base in India. Sanimax positions itself with sustainable rendering solutions that appeal to environmentally conscious buyers across North American agricultural markets.
Blood meal is a high-protein byproduct derived from animal blood, processed through coagulation and drying into a fine powder. It serves as a potent organic fertilizer and a key protein source in animal diets, characterized by its nitrogen content often exceeding 12%. The animal feed application constitutes the largest volume segment due to its use in aquaculture and poultry rations. However, demand from organic farming is expanding rapidly, driven by the need for natural soil amendments and fertilizers.
Regulatory frameworks from bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern its use in animal feed, setting strict standards for pathogen control. Concurrently, organic certification programs, such as those overseen by the USDA or compliant with EU regulations, dictate purity and processing requirements for its use in agriculture. Navigating the divergent safety protocols and organic standards across key export markets remains a critical task for producers.
Market Dynamics
The central structural force shaping the blood meal market is the escalating competition for a finite supply of raw material between two distinct, high-value demand streams: animal feed and organic agriculture, a dynamic intensified by sustainability mandates like the EU Green Deal.
Growth Catalysts
- Organic Farming Mandates:Policies like the EU Green Deal's farm-to-fork strategy and USDA organic standards create sustained demand for blood meal as a high-nitrogen, natural fertilizer, displacing synthetic alternatives.
- Aquaculture Feed Demand:The expansion of aquaculture, particularly for carnivorous species like salmon and shrimp, requires high-protein feed ingredients, for which blood meal is a cost-effective and nutritionally valuable component.
- Processing Technology:Advances in spray-drying and atomization improve the solubility, digestibility, and handling characteristics of blood meal, expanding its applicability in premium feed and fertilizer formulations.
Market Restraints
- Regulatory Divergence:Conflicting safety and pathogen control standards for animal byproducts, such as those between the U.S. FDA and the European Food Safety Authority (EFSA), complicate international trade and increase compliance costs.
- Feed Ingredient Substitution:The animal feed sector faces constant price-based substitution pressure from other protein sources, including fish meal, poultry meal, and soy protein concentrate, limiting pricing power for blood meal producers.
- Raw Material Volatility:Supply is entirely dependent on slaughterhouse output, making it susceptible to fluctuations in the livestock market, disease outbreaks, and culling programs, which can create price and availability instability.
Strategic Opportunities
- Specialty Pet Food:The demand for high-protein, grain-free, and novel protein diets in the premium pet food segment presents an opportunity for high-purity, certified blood meal as a functional ingredient.
- Bio-Fertilizer Formulations:There is an opportunity to develop enhanced fertilizer products by combining blood meal with beneficial microbes, biostimulants, or other organic materials to improve soil health and nutrient uptake.
- Underpenetrated Markets:Expanding into nascent aquaculture markets in Southeast Asia, such as Vietnam and Indonesia, and parts of Latin America offers significant growth potential for exporters.
Industry Challenges
- Certification Complexity:Navigating the dual certification pathways for animal feed safety and organic agricultural use requires significant investment in documentation, process segregation, and third-party audits.
- Logistical Segregation:Maintaining separate supply chains for certified organic and conventional blood meal to prevent cross-contamination adds complexity and cost to storage, handling, and transportation.
- Energy-Intensive Processing:The drying process, particularly spray-drying, is energy-intensive, exposing producers to volatile energy costs and increasing pressure to invest in more efficient technologies or renewable energy sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Meal Market |
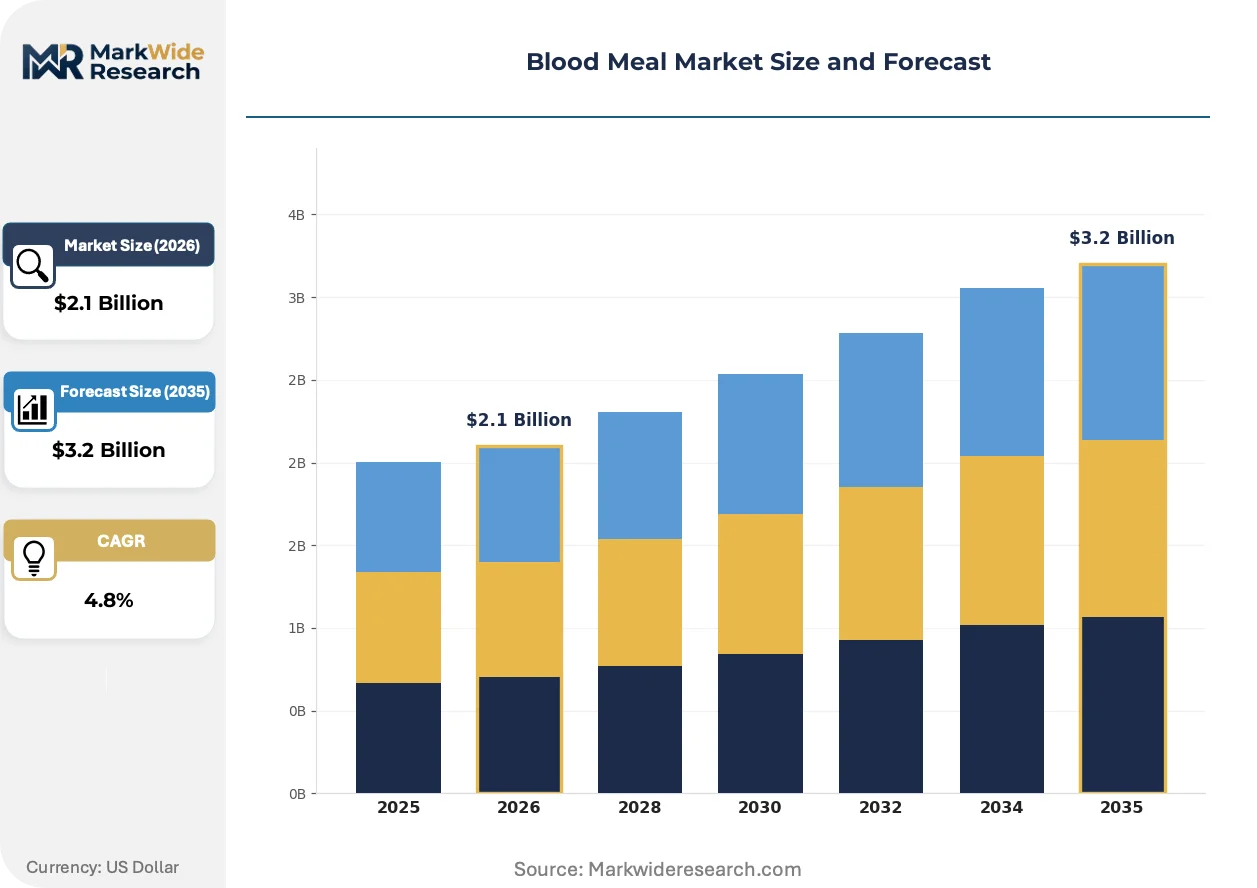
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Pellets, Granules, Liquid Concentrate Application: Organic Farming, Animal Feed, Fertilizer Production, Soil Amendment End User: Crop Growers, Livestock Farms, Greenhouses, Hydroponic Farms Packaging Type: Bags, Bulk Sacks, Drums, Pails, Sachets |
| Companies Covered | Valley Proteins, Inc., Allanasons Pvt Ltd, Darling Ingredients, Boyer Valley Company, APC, Inc., Sanimax, Terramar Chile, Ridley Corporation Limited, West Coast Reduction Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Meal Market Strategic Shifts & Innovations
Processing innovations are fundamentally upgrading blood meal from a commodity byproduct into a specialized, high-performance ingredient. This shift is enabling producers to target specific functional benefits in both animal nutrition and advanced agricultural applications, creating new value streams.
Advanced spray-drying and atomization processes are key technologies that enhance the solubility and digestibility of blood meal. Premium end-users in aquaculture and young animal nutrition are the primary adopters, seeking consistent particle size and flowability. As a result, the product's core value proposition is migrating from a basic protein source to a functional ingredient valued for its physical and nutritional performance.
The EU Green Deal and its associated farm-to-fork strategy are creating a powerful regulatory pull for organic inputs across member states. This framework directly incentivizes the substitution of synthetic nitrogen fertilizers with natural alternatives like blood meal. Organic horticulture and viticulture segments in countries such as France, Spain, and Italy are most directly impacted, increasing their procurement of certified organic blood meal.
A distinct behavioral shift among buyers in the organic agriculture sector involves demanding greater supply chain transparency. These buyers now often require certification that the blood meal originates from animals raised without antibiotics or GMO feed. This disrupts traditional, commingled supply chains and favors producers who can offer source-verified, identity-preserved products, a trend highly visible in California's specialty crop markets.
Blood Meal Market Segmentation
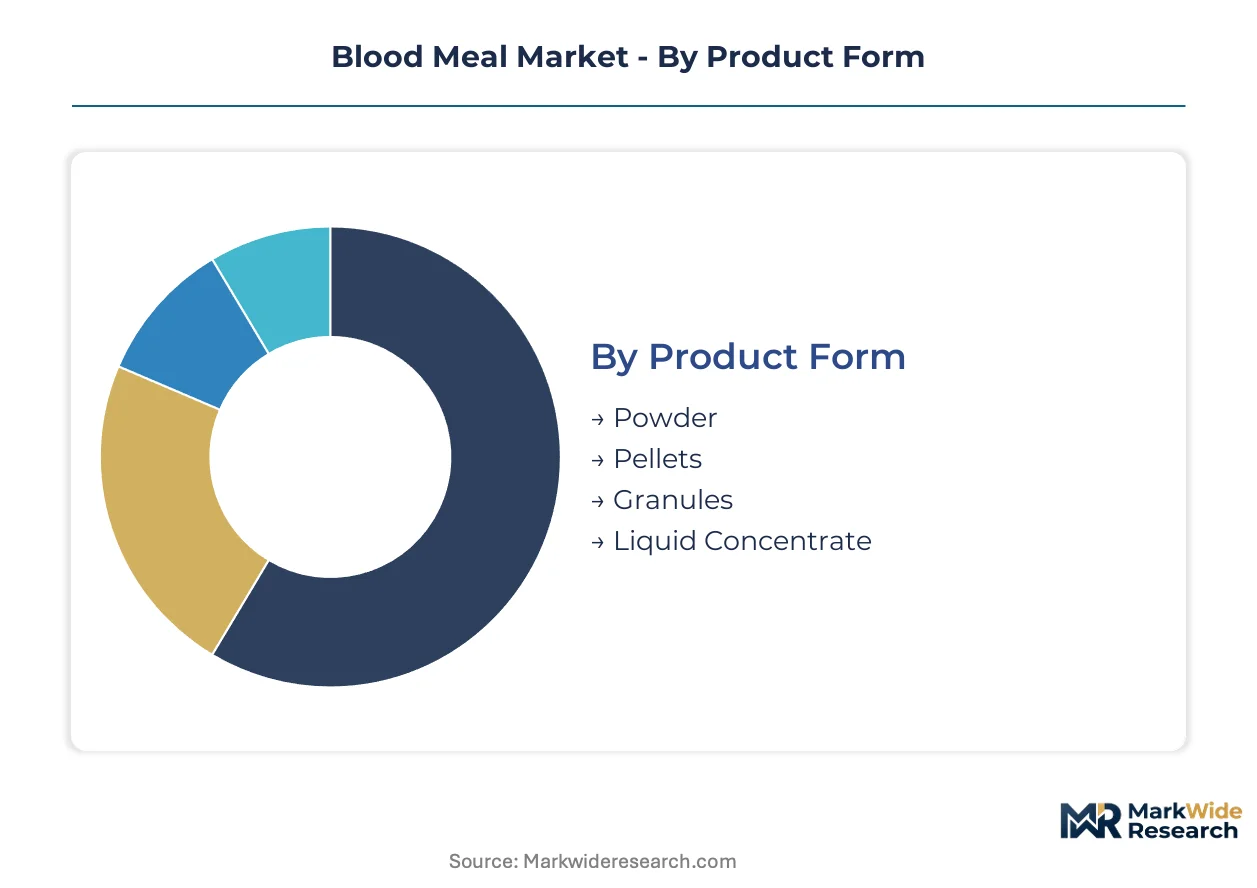
Market segmentation provides a granular view of the blood meal industry, dissecting its structure by product form, application, end-user, and packaging type. This detailed breakdown illuminates distinct demand patterns and value propositions, allowing producers to tailor offerings and market strategies effectively.
Product Form:
The product form dimension captures the physical state and processing level of blood meal offerings, directly impacting handling, application methods, and target end-uses.
- Powder:This fine, dry form of blood meal is highly concentrated, offering excellent bioavailability and ease of mixing into animal feed rations or fertilizer blends. Demand concentrates in large-scale feed mills and agricultural operations across the United States, where consistent particle size is crucial for efficient formulation.
- Liquid Concentrate:Processed for enhanced solubility and often stabilized, this form allows for precise dosing and integration into liquid feeding systems or fertigation programs. Aquaculture in Norway heavily utilizes liquid concentrates for specialized fish feed formulations, driven by performance and consistent nutrient delivery.
- Pellets:Compressed granular forms of blood meal offer improved handling, reduced dust, and slower nutrient release in soil applications.
- Granules:These larger, irregular particles are ideal for broadcasting as a slow-release organic fertilizer in broadacre farming.
Powder commands the established base. The steepest expansion runs through Liquid Concentrate.
Application:
Different application methods dictate specific product characteristics and regulatory compliance, influencing market demand across diverse agricultural sectors.
- Animal Feed:Blood meal serves as a vital protein source in livestock, poultry, and aquaculture diets, valued for its high nitrogen content and amino acid profile. This application dominates volume in Brazil and the United States, driven by large-scale meat and dairy production.
- Organic Farming:As a natural, high-nitrogen fertilizer, blood meal supports organic crop production by enhancing soil fertility and plant growth without synthetic inputs. The EU Green Deal's farm-to-fork strategy in France and Germany significantly boosts demand in this segment.
- Fertilizer Production:Blood meal is incorporated into blended organic fertilizers, providing a concentrated nitrogen component for balanced nutrient products.
- Soil Amendment:Used directly to improve soil structure and nutrient content, blood meal supports healthy microbial activity and long-term soil health.
Animal Feed represents the largest volume application. Organic Farming is expanding most quickly.
End User:
End-user requirements drive demand for specific blood meal formulations, reflecting varied operational scales and agricultural practices.
- Livestock Farms:These operations utilize blood meal primarily as a protein supplement in feed for cattle, swine, and poultry to optimize growth and production. Large commercial farms in the United States and Argentina are significant consumers.
- Crop Growers:Farmers cultivating various crops employ blood meal as an organic fertilizer to enrich soil and provide essential nitrogen for plant development. Organic vegetable growers in California represent a key demand cluster.
- Greenhouses:Controlled environment agriculture uses blood meal for precise nutrient delivery to high-value horticultural crops.
- Hydroponic Farms:Although less common, some hydroponic systems integrate highly soluble blood meal derivatives for organic nutrient solutions.
Livestock Farms consume significant volumes for animal nutrition. Hydroponic Farms are gaining share fastest.
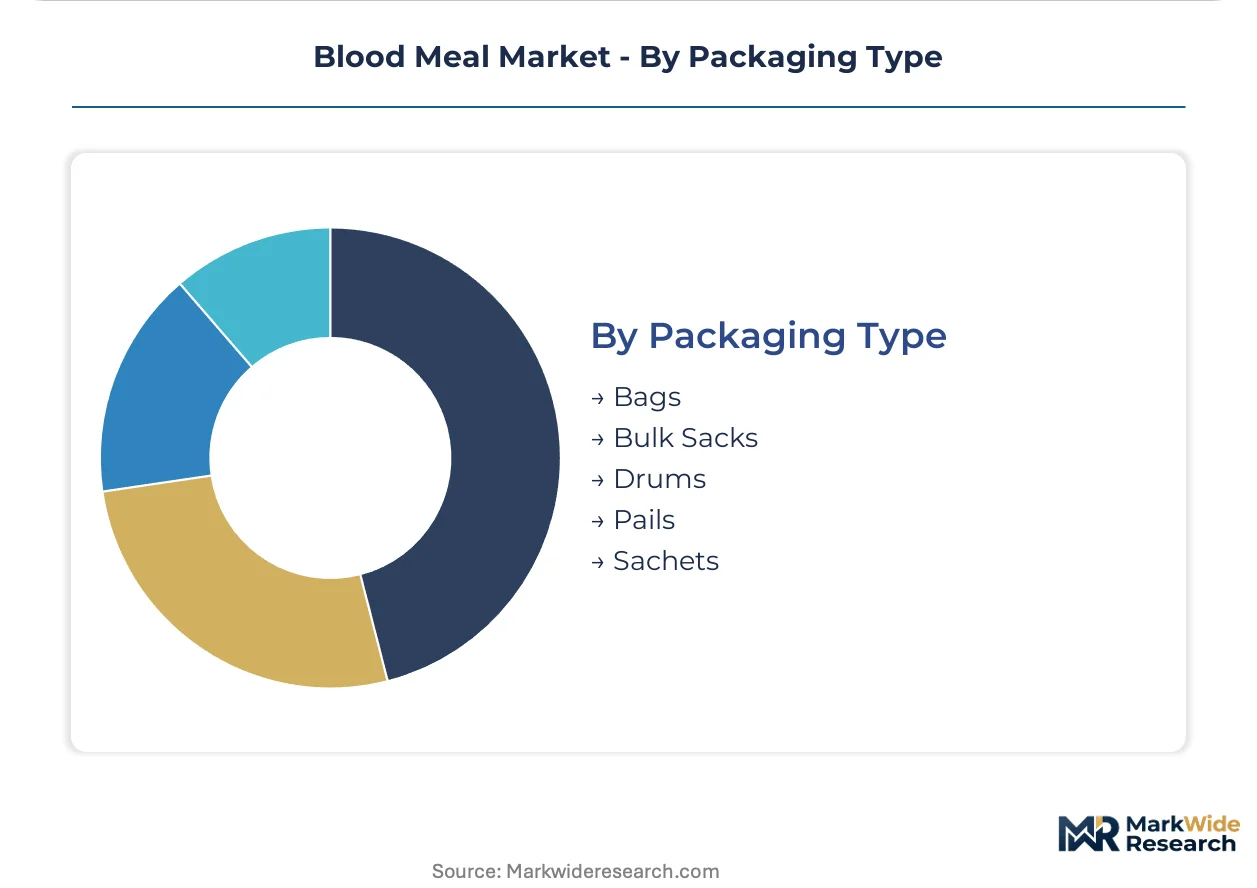
Packaging Type:
Packaging types primarily address logistical efficiency, storage requirements, and the scale of end-user operations.
- Bulk Sacks:Large industrial bags, typically 500-1000 kg, are used for high-volume shipments to feed manufacturers and large agricultural distributors. This packaging is prevalent in major agricultural hubs in Brazil.
- Bags:Smaller, typically 25-50 kg bags, cater to individual farmers, smaller feed mills, and garden supply stores for easier handling and distribution. Demand is widespread across Europe for organic garden centers.
- Drums:Robust containers, often used for liquid concentrate forms, ensure safe transport and storage for specialized applications.
- Pails:Smaller, resealable containers provide convenience for niche applications or smaller-scale users requiring precise quantities.
- Sachets:Very small, portion-controlled packets target hobby gardeners or specialty organic input suppliers.
Bags serve a broad base of users. Sachets are climbing the fastest for specialty applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global blood meal market exhibits a complex interplay of regional supply and demand, with significant export capacities in major livestock-producing nations balancing import needs from specialized agricultural and aquaculture hubs. This dynamic shapes trade flows and pricing structures across continents. Key agricultural regions drive both production and consumption.
United States
United States demand for blood meal is substantial, driven by large-scale livestock farms and a rapidly expanding organic agriculture sector. USDA organic standards mandate the use of natural inputs, supporting demand for high-nitrogen fertilizers. Organic vegetable growers in California represent a key demand cluster, requiring source-verified, identity-preserved products.
Brazil
Brazil's vast livestock industry consumes significant volumes of blood meal for animal nutrition, particularly in poultry and swine rations. ANVISA regulations govern the processing and use of animal byproducts in feed formulations. Major agricultural hubs, especially in the Mato Grosso region, see high demand for bulk sack packaging to support large-scale feed mills.
France
French organic farming mandates, influenced by the EU Green Deal's farm-to-fork strategy, create sustained demand for natural fertilizers. This policy framework incentivizes the substitution of synthetic nitrogen fertilizers with organic alternatives. Organic horticulture and viticulture segments in the Bordeaux region are significantly increasing their procurement of certified organic blood meal.
India
India's expanding aquaculture sector and domestic animal feed production drive demand for high-protein blood meal. FSSAI standards ensure the safety and quality of feed ingredients derived from animal byproducts. Nascent aquaculture markets in coastal regions like Andhra Pradesh offer significant growth potential for exporters of specialized feed components.
Norway
Norwegian aquaculture heavily utilizes blood meal, particularly liquid concentrates, for specialized fish feed formulations in its salmon industry. EFSA guidelines, which Norway often aligns with, set strict standards for pathogen control in animal byproducts used in feed. The aquaculture industry along the western coast, around Bergen, is a primary adopter of these premium, highly soluble products.
Blood Meal Market Key Industry Players
On the supply side, the industry is characterized by a blend of large, vertically integrated processors and specialized niche players. This structure creates a tiered competitive environment, with scale producers dominating commodity segments and smaller firms focusing on high-value, certified products. Dominant competitive moves include strategic partnerships for raw material sourcing and continuous investment in advanced processing technology to enhance product purity. Companies also engage in geographic expansion to capture demand in underpenetrated markets.
Specialists in sustainable rendering solutions occupy a distinct position within the market, exemplified by Sanimax, which appeals to environmentally conscious buyers across North American agricultural markets. Darling Ingredients, leveraging its extensive global rendering network, represents scale-driven efficiency and achieves significant economies of scale in processing. This allows them to serve a broad base of customers seeking consistent, high-volume supply. Furthermore, Allanasons Pvt Ltd, based in India, anchors the supply of certified products to international markets, demonstrating a strong focus on export-oriented quality and navigating complex global regulatory frameworks.
| Leading Market Players |
|---|
| Valley Proteins, Inc. |
| Allanasons Pvt Ltd |
| Darling Ingredients |
| Boyer Valley Company |
| APC, Inc. |
| Sanimax |
| Terramar Chile |
| Ridley Corporation Limited |
| West Coast Reduction Ltd |
Cost & Logistics Intelligence
Transatlantic shipping lanes' fluctuating fuel costs directly influence blood meal pricing, shaping how concentrated supply from the Americas differentiates into specialty products for European and Asian markets. This dynamic impacts both commodity and premium segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake for specialized blood meal products. Pricing stratifies across premium, standard, and economy tiers based on certification level and processing purity, with spray-dried variants commanding higher prices. Pricing softness stems from intense competition with alternative protein sources in the animal feed sector. While animal feed manufacturers exhibit high price sensitivity, organic farming and specialty pet food segments prioritize quality and certification over lowest cost.
Supply Chain Analysis
Pathogen control regulations, like those from the U.S. FDA and EFSA, limit international trade flows of animal byproducts. Supply concentrates in major livestock-producing nations such as the United States, Brazil, and India, which draw from slaughterhouse output. The entire supply chain relies on consistent animal blood availability, creating volatility risks from disease outbreaks or culling programs. Distribution runs through a network of global ingredient distributors and specialized regional suppliers serving feed mills and organic fertilizer blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood meal market requires a robust substitution defense strategy. Incumbents must navigate the constant threat from alternative protein sources like fish meal and soy protein concentrate, particularly in high-volume animal feed applications.
For Market Incumbents: Harden existing processing infrastructure by investing in advanced spray-drying and atomization technologies to produce higher-purity products. Secure long-term raw material sourcing agreements with slaughterhouses to mitigate supply volatility driven by livestock market fluctuations. Invest in dual certification pathways, addressing both animal feed safety and organic agricultural standards, to counter regulatory divergence. This approach helps defend margins against price erosion from generic alternatives.
For New Entrants and Emerging Players: Certified organic horticulture in European markets, particularly viticulture in France and Italy, represents a penetrable entry point for specialized blood meal. Nascent aquaculture markets in Vietnam and Indonesia also offer significant growth potential for high-protein feed ingredients. Offer source-verified, identity-preserved products that meet strict organic and pathogen-free standards to differentiate from commodity players. Focus on direct supply relationships with high-value crop growers and specialized aquaculture farms.
For Investors and Strategic Acquirers: The EU Green Deal's farm-to-fork strategy reshapes the acquisition landscape, favoring producers of natural, certified inputs. Long-term viability rests on the sustained demand from organic agriculture and expanding aquaculture sectors. Target mid-sized processors with proprietary spray-drying technology or established supply chains for certified organic blood meal. A signal to watch is the global proliferation of stringent organic farming mandates and sustainability frameworks beyond Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Spray-Drying Technology | Enhances product solubility and purity for premium feed and fertilizer applications. |
| Secure Long-Term Raw Material Contracts | Mitigates supply volatility from slaughterhouse output fluctuations in Brazil. |
| Obtain Dual Organic and Feed Certifications | Unlocks access to both high-value organic farming and animal feed markets in the US. |
| Expand into Southeast Asian Aquaculture | Captures demand from rapidly growing carnivorous fish and shrimp farming in Vietnam. |
| Develop Bio-Fertilizer Formulations | Creates higher-value products by combining blood meal with beneficial microbes for European crop growers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of USDA reports, EFSA guidelines, and FSSAI standards. This involved in-depth interviews with feed mill managers, organic farm operators, rendering plant directors, and aquaculture specialists. The approach triangulated insights from these industry stakeholders with published data, employing both bottom-up market sizing and top-down validation.
Forecast inputs considered include historical market performance, projected livestock slaughter rates, and organic farmland expansion across the analysis window. The analytical framework modeled segmentation dimensions such as product form, application, end-user, packaging type, and regional regulatory compliance. Compound annual growth rates were derived through regression analysis on historical data and projected growth drivers.
Stress conditions across regulatory stability and major disease control scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about consistent raw material supply and stable trade policies. Material shifts in global livestock health or international trade agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Premix Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Europe Ruminant Feed Market
Agricultural Commodities
Bladderpod Oil Market