
 Brazil Agricultural Machinery Market | 2026-2036
Brazil Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Agricultural Machinery Market Outlook
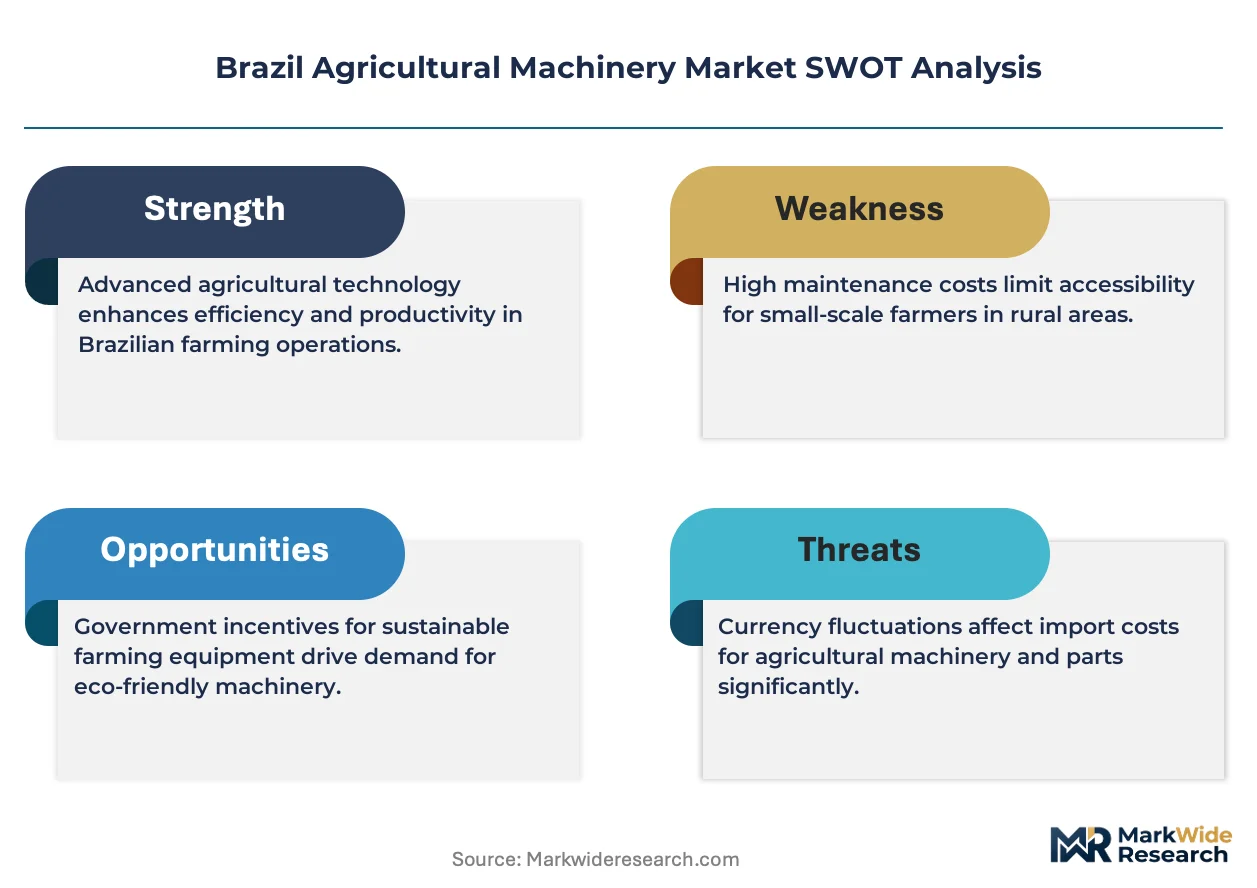
Dealer networks in Brazil's agricultural machinery sector is tilting toward integrated service-and-financing hubs in the Midwest grain belt. Deere & Company anchors its presence through captive financing arms and precision agriculture training centers. CNH Industrial N.V. competes via Case IH and New Holland brand dual-channel coverage across Mato Grosso and Paraná. Maquinas Agricolas Jacto S/A specializes in localized sprayer and precision application equipment for tropical crop profiles.
Brazil agricultural machinery encompasses tractors, harvesters, tillage implements, and planting equipment engineered for tropical soil conditions, high-clearance crop requirements, and extended seasonal duty cycles exceeding standard temperate-market specifications. These machines integrate reinforced frames, corrosion-resistant coatings, and high-torque powertrains to sustain continuous operation during compressed planting and harvest windows. Tractors occupy the largest installed base due to universal applicability across soil preparation, transport, and auxiliary power tasks, while precision farming technology commands expanding margin pools as GPS-guided autosteer and variable-rate application retrofit kits penetrate mid-tier fleet upgrades. Harvesters represent the most capital-intensive segment, with self-propelled combines and sugarcane harvesters driving replacement cycles tied to commodity price liquidity and credit availability.
ANVISA regulates operator safety standards and emissions certification for agricultural equipment sold in Brazil, while the Central Bank's rural credit directives through Plano Safra shape equipment financing terms and seasonal purchasing patterns. INMETRO conformity assessment mandates govern fuel efficiency labeling and engine emissions testing, directly influencing manufacturer product development priorities and import compliance costs. Stakeholders must monitor how RenovaBio carbon intensity requirements and potential Euro Stage V alignment timelines reshape engine technology roadmaps and fleet replacement economics.
Market Dynamics
PROTRATOR subsidy disbursements and RenovaBio carbon intensity mandates are compressing equipment replacement cycles while forcing engine technology transitions across Brazil's mechanized farming belt. Large-scale operators in Mato Grosso and Goiás now face simultaneous financing access and compliance recalibration pressures.
Growth Catalysts
- Plano Safra credit expansion:Central Bank rural credit directives are extending subsidized financing terms to mid-tier fleet operators previously excluded from formal equipment lending channels.
- Sugarcane mechanization mandates:State-level burning restrictions in São Paulo and Paraná are compelling harvester fleet upgrades among sugar-ethanol processors.
- Precision agriculture retrofit demand:GPS-guided autosteer and variable-rate application kits are penetrating second-hand tractor markets as owner-operators seek yield optimization without full fleet replacement.
Market Restraints
- Steel and tire input volatility:Domestic component costs fluctuate with import dependency for high-grade alloys and radial tire compounds, compressing manufacturer margin buffers.
- Import concentration risk:Powertrain and precision electronics sourcing clusters in Germany, Japan, and the United States expose assemblers to currency and logistics disruptions.
- ANVISA emissions certification lag:Protracted approval timelines for Euro Stage V-aligned engines delay product launches versus competitor access in Argentina and Paraguay.
Strategic Opportunities
- MATOPIBA frontier penetration:Undermechanized soybean expansion zones across Maranhão, Tocantins, Piauí, and Bahia present first-mover fleet establishment potential.
- RenovaBio carbon credit monetization:Biofuel processors can capture machinery-related carbon intensity reductions for compliance trading, creating equipment financing co-investment structures.
- Telematics-channel convergence:Dealer networks are integrating remote diagnostics platforms with captive financing arms to lock in multi-year service contracts.
Industry Challenges
- Precision agriculture technician scarcity:GPS calibration, drone operation, and data analytics competencies outpace vocational training pipeline output in Cerrado belt states.
- Legacy fleet integration friction:Retrofit kit compatibility with pre-2015 tractor architectures limits upgrade penetration among debt-constrained owner-operators.
- INMETRO conformity timeline compression:Accelerated fuel efficiency labeling mandates force simultaneous engineering and certification resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Agricultural Machinery Market |
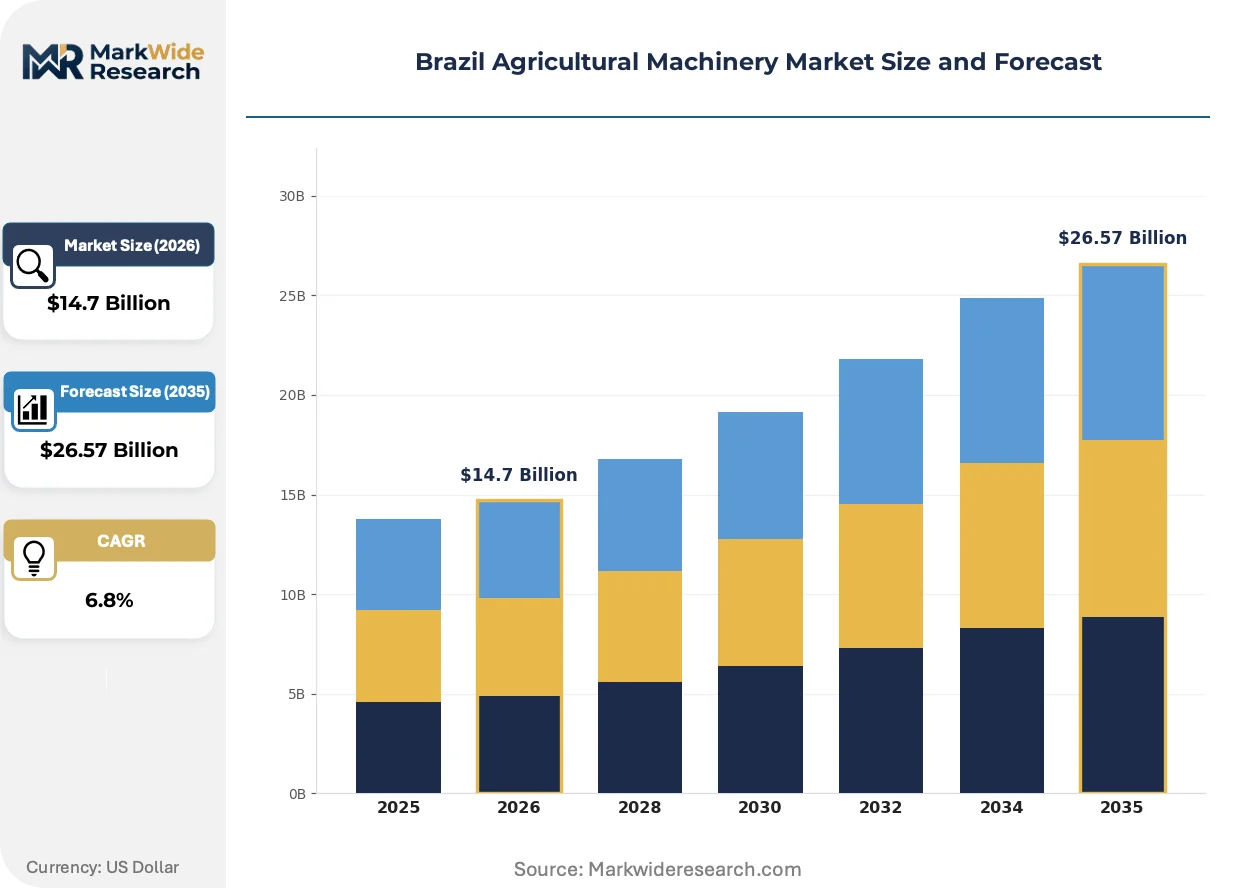
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Plowing Equipment, Seeders Application: Crop Production, Soil Preparation, Irrigation, Fertilization Technology: Automation, Precision Farming, GPS Tracking, IoT Integration End User: Farmers, Agricultural Cooperatives, Enterprises, Government Agencies |
| Companies Covered | Mahindra & Mahindra Ltd, Claas KGaA mbH, Deere & Company, Maquinas Agricolas Jacto S/A, Stara S/A, CNH Industrial N.V., Kubota Corporation, Bucher Industries AG, AGCO Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Agricultural Machinery Market Strategic Shifts
Electrification pathways and connected fleet management are restructuring capital deployment patterns across Brazilian agricultural operations. Equipment intelligence now penetrates earlier in ownership cycles than previously observed.
Autonomous planting systems integrating LiDAR terrain mapping with real-time seed-depth adjustment are collapsing the operational gap between experienced operator judgment and standardized precision. Large-scale cooperatives in Rio Grande do Sul are piloting these platforms during compressed soybean planting windows. The technology is collapsing traditional reliance on seasonal skilled labor availability while compressing per-hectare establishment cost variance.
ANVISA and INMETRO are tightening concurrent emissions and safety certification requirements for self-propelled harvesters entering the Brazilian market. Manufacturers must now submit combined documentation packages addressing operator protection standards and carbon intensity benchmarks. This regulatory bundling most acutely affects sugarcane harvester segments where fleet turnover rates already lag grain equipment replacement cycles.
Leasing structures with embedded maintenance and technology refresh clauses are displacing outright purchase dominance among mid-scale operators in Paraná and Santa Catarina. Dealer finance arms structure these contracts around guaranteed residual values and telemetry-verified utilization rates. Southern soybean producers increasingly favor this model to preserve working capital for input procurement while securing predictable equipment access.
Brazil Agricultural Machinery Market Segmentation
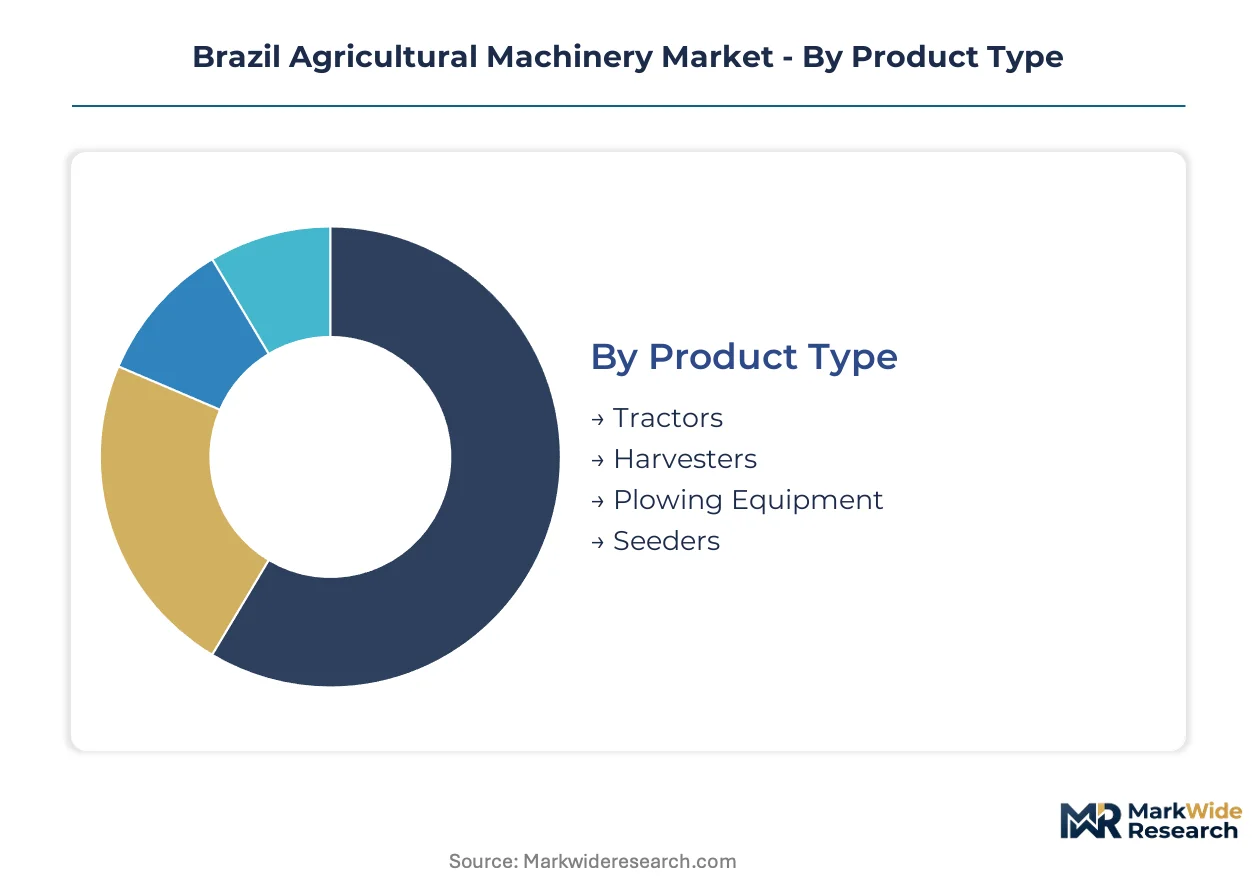
Equipment replacement cycles vary dramatically across Brazil's agricultural machinery fleet, with compressed harvest windows and PROTRATOR subsidy timing creating distinct turnover rhythms by product category. Understanding these temporal patterns reveals where financing flows concentrate and where technology transitions face the greatest friction.
Product Type:
Harvesters turn over fastest—tied to commodity price liquidity and sugarcane mechanization mandates—while plowing equipment cycles stretch longest due to structural simplicity and repairability.
- Tractors:Universal workhorses powering soil preparation, transport, and auxiliary tasks across Brazilian farms. Demand concentrates in Mato Grosso and Goiás where large-scale operators expand mechanized fleets to match soybean frontier expansion; PROTRATOR subsidies and Plano Safra credit terms directly shape purchasing seasonality here.
- Harvesters:Self-propelled combines and sugarcane harvesters represent the most capital-intensive segment with replacement cycles most sensitive to credit availability. São Paulo and Paraná sugar-ethanol processors face state-level burning restrictions that compress fleet upgrade timelines; RenovaBio carbon intensity benchmarks add compliance-driven turnover pressure.
- Plowing Equipment:Tillage implements engineered for Cerrado abrasive soils and extended duty cycles. Reinforced frames and replaceable wear components extend service life beyond powered equipment categories.
- Seeders:Precision planting equipment with variable-rate capability gaining traction among cooperatives. MATOPIBA frontier expansion in Maranhão and Tocantins drives first-mover demand for mechanized establishment.
Tractors dominate installed base. Harvesters are where expansion concentrates.
Application:
Margin pools diverge sharply by task—soil preparation commands volume, while precision application captures technology premiums.
- Crop Production:Harvesting and grain handling operations at the core of Brazilian agricultural output. Large-scale enterprises in the southern soybean frontier prioritize combine capacity to minimize weather-driven yield loss during compressed windows.
- Soil Preparation:Tillage and land conditioning tasks consuming the highest machinery hours annually. Cerrado belt operators demand corrosion-resistant coatings and high-torque powertrains for continuous operation.
- Irrigation:Center-pivot and drip system mechanization expanding in drought-prone zones. Government agency procurement in semi-arid Northeast regions supports infrastructure development.
- Fertilization:Variable-rate application equipment integrating with precision farming platforms. Agricultural cooperatives in Rio Grande do Sul pilot autonomous systems for real-time adjustment.
Soil preparation absorbs the greatest equipment hours. Fertilization is climbing the fastest on technology attach rates.
Technology:
Adoption timelines separate retrofit-ready platforms from integrated native systems, with dealer service capabilities determining penetration speed.
- Automation:Autonomous planting and harvesting systems collapsing labor dependency. Large-scale cooperatives pilot LiDAR terrain mapping during compressed soybean windows in Rio Grande do Sul.
- Precision Farming:GPS-guided autosteer and variable-rate application retrofit kits penetrating mid-tier tractor markets. Owner-operators seek yield optimization without full fleet replacement.
- GPS Tracking:Fleet location and utilization monitoring standardizing across financed equipment. Telemetry-verified rates underpin leasing structures with embedded maintenance clauses.
- IoT Integration:Remote diagnostics platforms converging with captive financing arms. Dealer networks lock multi-year service contracts through connected fleet management.
Precision farming dominates retrofit activity. Automation is gaining share fastest on labor scarcity.
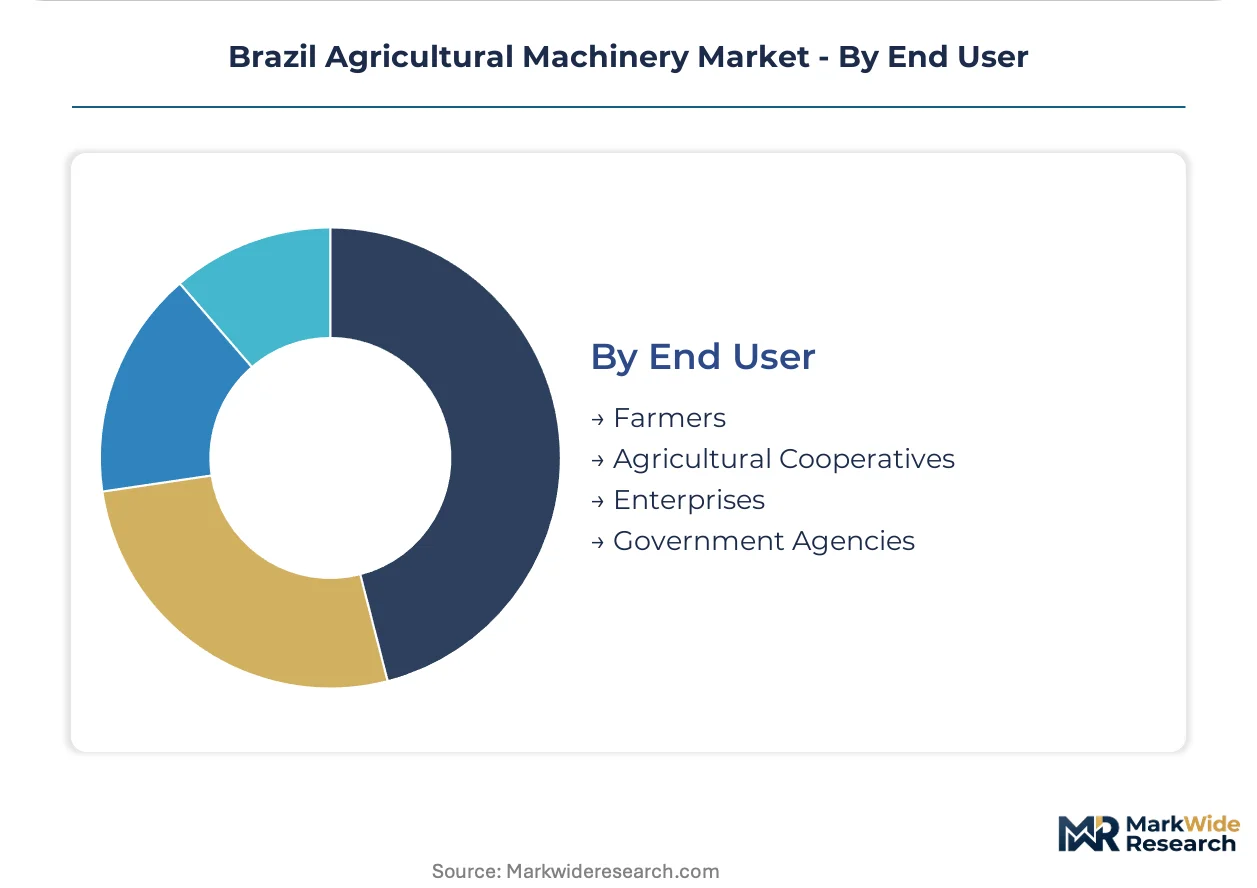
End User:
Scale determines financing access and technology adoption sequencing, with formal credit channels filtering by collateral and operational history.
- Farmers:Individual owner-operators spanning subsistence to mid-scale commercial operations. Debt-constrained producers face retrofit compatibility limits with pre-2015 tractor architectures.
- Agricultural Cooperatives:Member-owned enterprises pooling capital for fleet acquisition and technology pilots. Southern Brazil cooperatives lead autonomous system trials and carbon credit monetization structures.
- Enterprises:Large-scale farming companies with direct manufacturer relationships and dedicated precision agriculture technicians. Midwest grain belt operators anchor demand for integrated service-and-financing hubs.
- Government Agencies:Public procurement for research stations, extension services, and infrastructure development. INMETRO conformity requirements shape tender specifications and approval timelines.
Enterprises dominate technology-forward procurement. Cooperatives are where financing innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA emissions certification timelines and Central Bank rural credit directives through Plano Safra anchor regional equipment demand patterns across Brazil's agricultural machinery belt. State-level mechanization mandates and frontier expansion zones reshape sub-national procurement concentration.
Mato Grosso
Soybean and corn producers in Mato Grosso expand mechanized planting and harvesting fleets to match Cerrado frontier output growth. PROTRATOR subsidy disbursements concentrate purchasing seasonality during Plano Safra credit windows. Rondonópolis and Sorriso anchor integrated service-and-financing hub development for large-scale operators.
Goiás
Large-scale farming enterprises in Goiás face simultaneous financing access and compliance recalibration pressures from RenovaBio mandates. State agricultural credit programs complement federal PROTRATOR allocations for mid-tier fleet operators. Rio Verde and Catalão host precision agriculture training centers and dealer network consolidation.
São Paulo
Sugar-ethanol processors in São Paulo confront state-level burning restrictions that compress sugarcane harvester fleet upgrade timelines. RenovaBio carbon intensity benchmarks add compliance-driven turnover pressure beyond commodity price cycles. Piracicaba and Ribeirão Preto concentrate biofuel processor procurement and equipment financing co-investment structures.
Paraná
Southern soybean producers in Paraná favor leasing structures with embedded maintenance clauses to preserve working capital for input procurement. Case IH and New Holland brand dual-channel coverage penetrates mid-scale operator segments. Cascavel and Londrina anchor telemetry-verified utilization rate contracting and multi-year service contract lock-ins.
Rio Grande do Sul
Agricultural cooperatives in Rio Grande do Sul pilot autonomous planting systems and carbon credit monetization structures. GPS-guided autosteer retrofit demand penetrates second-hand tractor markets among debt-constrained owner-operators. Passo Fundo and Cruz Alta host precision agriculture technician training pipelines and LiDAR terrain mapping trials.
Brazil Agricultural Machinery Market Competitive Environment
Full-line multinational assemblers and specialized regional fabricators split the market across distinct capital intensity and technology integration vectors. Dealer captive financing arms and precision agriculture service capabilities determine customer lock-in effectiveness. Three archetypes dominate: integrated technology-platform providers, regional application specialists, and scale-driven volume manufacturers. Geographic expansion through distribution partnerships and portfolio diversification into precision retrofit kits represent the dominant competitive moves reshaping positioning.
Among integrated technology-platform providers, Deere & Company and CNH Industrial N.V. exemplify archetypes combining captive financing with precision agriculture infrastructure. Maquinas Agricolas Jacto S/A occupies a position within the regional application specialist tier, anchoring localized equipment adaptation for tropical crop profiles. Mahindra & Mahindra Ltd represents scale-driven volume manufacturing origins, while Claas KGaA mbH and AGCO Corporation sit within European-rooted harvester technology traditions. Kubota Corporation anchors compact tractor and utility equipment positioning across mid-tier fleet segments.
| Leading Market Players |
|---|
| Mahindra & Mahindra Ltd |
| Claas KGaA mbH |
| Deere & Company |
| Maquinas Agricolas Jacto S/A |
| Stara S/A |
| CNH Industrial N.V. |
| Kubota Corporation |
| Bucher Industries AG |
| AGCO Corporation |
| Others |
Value Chain & Pricing Dynamics
Idle assembly capacity in São Paulo's industrial corridor is compressing manufacturer pricing power while accelerating supplier consolidation negotiations. Brazilian assemblers face simultaneous margin pressure from imported powertrain costs and domestic financing subsidy timing that concentrates purchasing into narrow seasonal windows.
Pricing Analysis
Price spreads between Mato Grosso and Paraná dealer networks reflect transportation cost differentials and captive financing penetration gaps. Three-tier pricing structure across premium integrated-technology, standard full-line, and economy utility equipment segments dominates the market. Cost compression in mid-tier tractor segments is intensifying because PROTRATOR subsidy caps limit pass-through of steel and tire input volatility. Smallholder owner-operators in the Northeast exhibit highest price sensitivity, while large-scale enterprises in the Cerrado belt prioritize technology attach rates over unit cost.
Supply Chain Analysis
Contract manufacturing for precision electronics and GPS modules concentrates among Taiwanese and South Korean foundries serving Brazilian OEM assembly plants. Powertrain sourcing draws from German, Japanese, and United States component clusters, creating currency-hedging complexity for domestic assemblers. Single-source vulnerability in high-grade alloy forgings for harvester frames represents the dominant structural risk. Distribution runs through manufacturer-captive financing arms and regional dealer hubs that integrate service contracts with equipment delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across technology integration levels creates viable entry points as precision agriculture retrofit demand outpaces dealer service capacity in Brazil's Cerrado belt states.
For Market Incumbents: Insulate precision agriculture technician pipelines through vocational partnerships in Rio Grande do Sul and Mato Grosso to counter emerging entrant poaching. Deepen backward integration into telematics platform development to reduce dependency on German and Japanese electronics sourcing clusters. Channel control through embedded maintenance contracts locks in multi-year revenue visibility against price-focused competitors. For New Entrants and Emerging Players: MATOPIBA frontier zones in Maranhão and Tocantins represent the most penetrable entry point for first-mover fleet establishment among undermechanized soybean expansion operations. Precision application equipment for tropical crop profiles offers product differentiation with lower capital intensity than full-line harvester competition. Go-to-market execution through agricultural cooperative procurement committees bypasses incumbent dealer network saturation in established grain belts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across autonomous planting and harvesting system development, favoring specialized technology providers over scale-driven volume manufacturers. Acquisition targets should exhibit proven INMETRO certification pathways and established Plano Safra financing relationships. Monitor PROTRATOR subsidy allocation shifts and RenovaBio compliance timeline acceleration as early signals of fleet replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Training Center Expansion | Deere & Company and CNH Industrial N.V. anchor technician pipelines in Goiás and Mato Grosso to lock in cooperative procurement relationships. |
| RenovaBio Carbon Credit Monetization Partnership | Biofuel processors in São Paulo co-invest in harvester fleet upgrades to capture machinery-related carbon intensity reductions for compliance trading. |
| MATOPIBA Frontier Dealer Network Establishment | First-mover service-and-financing hubs in Maranhão and Tocantins secure early fleet relationships before incumbent saturation. |
| Telematics Platform Integration with Captive Finance | Remote diagnostics convergence with multi-year service contracts preserves margin pools as hardware commoditization accelerates. |
| Retrofit Kit Compatibility Certification Program | Pre-2015 tractor architecture support expands addressable market among debt-constrained owner-operators in southern soybean regions. |
Study Parameters
Operator-level perspectives from fleet managers at large-scale farming enterprises, precision agriculture technicians, dealer network financing officers, and sugar-ethanol processor procurement directors anchored the qualitative base. Secondary validation drew from ANVISA emissions certification filings, Central Bank Plano Safra credit disbursement records, INMETRO conformity assessment databases, and commodity price liquidity indices. Bottom-up equipment unit economics triangulated against top-down regional agricultural output projections to establish market sizing.
Scenario-bracketing around PROTRATOR subsidy continuity, RenovaBio compliance acceleration, and currency volatility bands structured the analytical framework across the analysis window. Segmentation modeling incorporated product type, application task, technology integration level, and end-user scale tier. CAGRs derived from historical replacement cycle patterns, credit availability indices, and frontier expansion zone mechanization rates. Forecast inputs included commodity price correlation coefficients and seasonal purchasing concentration factors.
Practitioners should monitor ANVISA emissions certification timeline shifts and Central Bank rural credit directive modifications for early signals of demand inflection. Forecasts reflect assumptions regarding subsidy program continuity, regulatory alignment with Euro Stage V standards, and import logistics stability. Quarterly review of steel and tire input cost indices, currency hedging contract rollovers, and MATOPIBA infrastructure development milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market