
 Corn Hydrolysate Market | 2026-2036
Corn Hydrolysate Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Hydrolysate Market Analysis
Buyer consolidation among multinational food manufacturers is recalibrating procurement leverage across the corn hydrolysate value chain. ADM leverages its integrated grain-processing network to secure feedstock cost advantages for hydrolysate production. Tate & Lyle PLC anchors its position through specialized enzyme technologies that control hydrolysis depth and flavor profiles. Cargill competes by extending its global distribution infrastructure into emerging nutraceutical channels.
Corn hydrolysate is an enzymatically hydrolyzed corn protein product containing peptides, free amino acids, and reducing sugars, typically manufactured through controlled proteolysis at temperatures between 50°C and 60°C with pH monitoring between 6.0 and 8.0. Its primary industrial purpose centers on delivering Maillard-reactive precursors for savory flavor development and providing plant-derived nitrogen sources for fermentation media. Powder Hydrolysate commands the largest volume share due to superior shelf stability and ease of dry blending in seasoning formulations. Liquid Hydrolysate registers the fastest expansion as clean-label broth and sauce manufacturers prioritize minimally processed ingredients with visible provenance.
The US FDA oversees GRAS self-affirmation pathways for novel hydrolysate compositions, while the USDA monitors organic certification claims for hydrolysate sold under the Form segment. The EPA regulates wastewater discharge from enzymatic processing facilities, directly influencing plant location decisions and capital intensity for new entrants. Stakeholders must monitor evolving enzyme patent expirations and carbon accounting requirements for fermentation-derived alternatives that could displace conventional hydrolysate in select applications.
Market Dynamics
Buyer consolidation among multinational food manufacturers is recalibrating procurement leverage across the corn hydrolysate value chain, forcing suppliers to demonstrate enzymatic precision and carbon-accounting transparency that smaller compounders cannot match.
Growth Catalysts
- US FDA GRAS Streamlining:The updated notification framework for hydrolyzed proteins accelerates market entry for novel suppliers, reducing regulatory friction that previously delayed commercialization of customized hydrolysate compositions.
- Clean-Label Formulation:Food and beverage manufacturers actively replace synthetic flavor enhancers with corn hydrolysate as a visible, plant-derived ingredient satisfying consumer scrutiny of ingredient lists.
- Fermentation Media Expansion:Biopharmaceutical and cultured-meat producers increasingly specify corn hydrolysate as a nitrogen source, creating pull-through demand from precision fermentation facilities in the United States and Western Europe.
Market Restraints
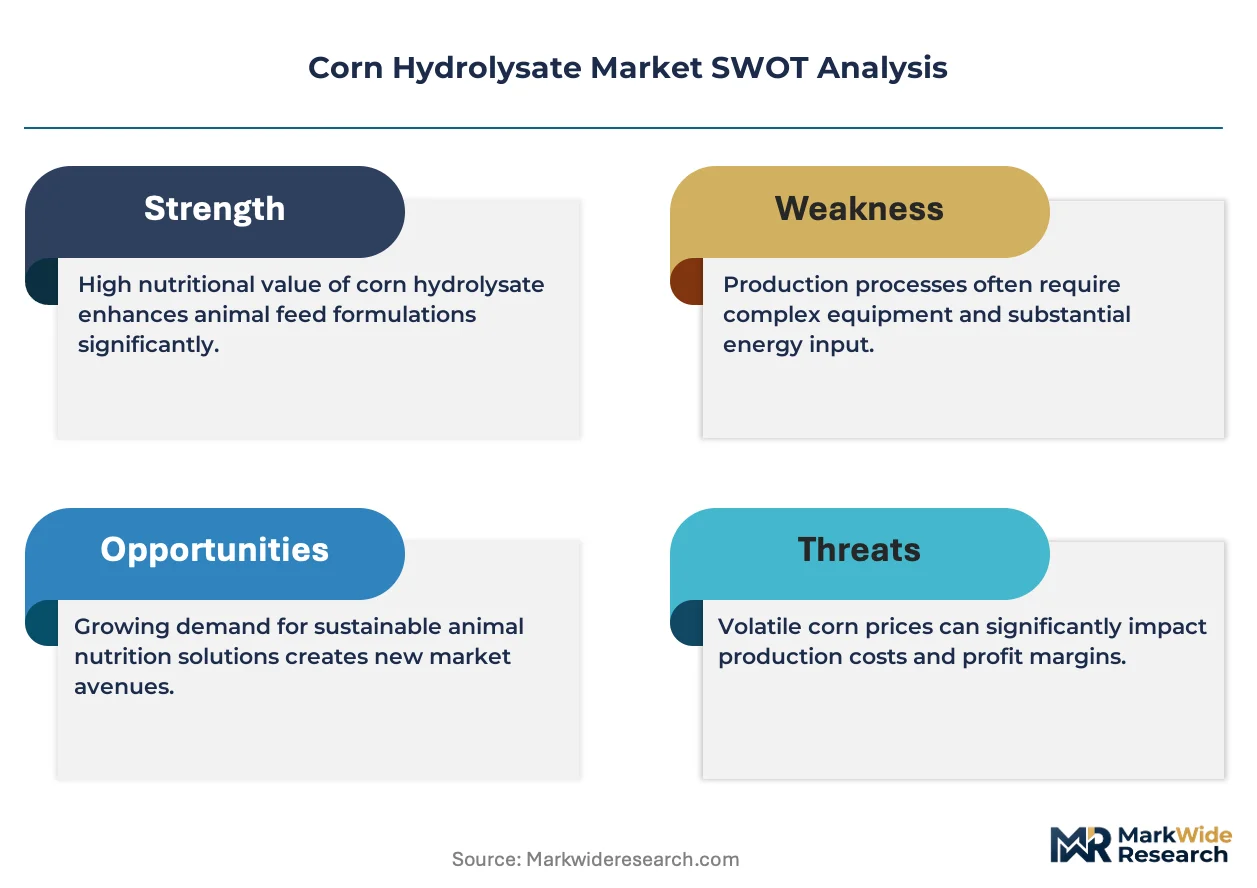
- Feedstock Concentration:Corn supply volatility tied to Midwestern US weather patterns and ethanol policy shifts creates input cost instability that compresses margin predictability for hydrolysate manufacturers.
- Enzyme Patent Thickets:Proprietary protease technologies held by specialized enzyme houses limit process optimization freedom for mid-scale producers seeking to differentiate through hydrolysis depth control.
- Wastewater Regulatory Burden:EPA discharge requirements for high-BOD enzymatic processing effluent elevate capital intensity for new plant construction, particularly constraining greenfield entrants in water-stressed regions.
Strategic Opportunities
- Organic Certification Pathway:USDA organic hydrolysate commands substantial premia in premium broth and sauce applications where supply scarcity currently limits category expansion.
- Nutraceutical Channel Penetration:Sports nutrition and clinical nutrition formulators in Germany and Japan are piloting corn hydrolysate as a hypoallergenic alternative to dairy and soy peptides.
- Carbon Accounting Integration:Lifecycle assessment methodologies aligned with EU Green Deal requirements enable suppliers to capture value from verified low-carbon hydrolysate production.
Industry Challenges
- Enzyme Procurement Expertise:Formulators struggle to source protease specialists capable of tuning hydrolysis kinetics for specific Maillard-reactive precursor profiles, creating bottlenecks in product development cycles.
- Legacy Equipment Retrofit Costs:Existing spray-drying and evaporation infrastructure at corn processing facilities requires substantial modification to handle hydrolysate viscosity and hygroscopicity characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Hydrolysate Market |
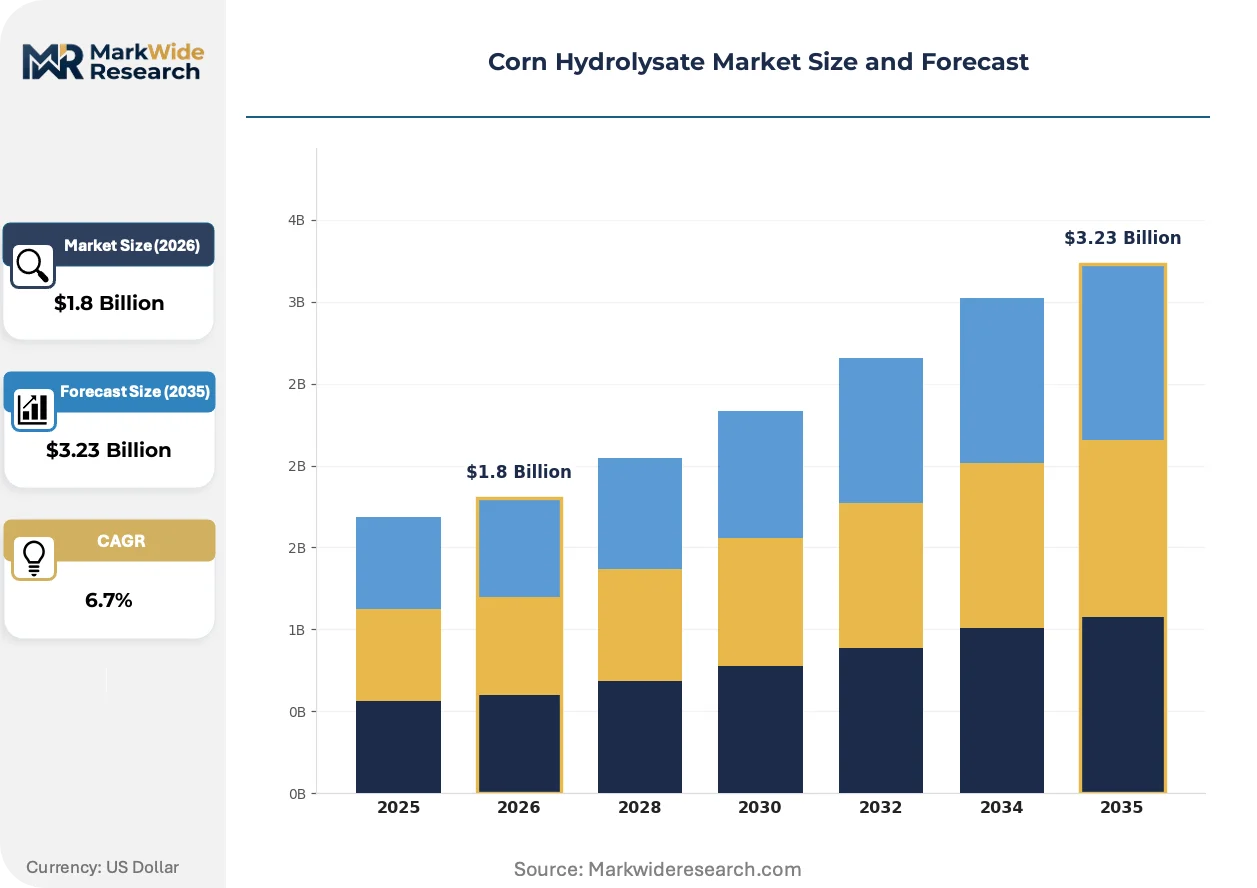
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Hydrolysate, Powder Hydrolysate, Granular Hydrolysate, Spray-Dried Hydrolysate Application: Food & Beverage, Animal Feed, Pharmaceuticals, Cosmetics Form: Organic, Non-Organic, Fermented, Concentrated End User: Food Manufacturers, Nutraceutical Companies, Agricultural Producers, Personal Care Brands |
| Companies Covered | ADM, Tate & Lyle PLC, Cargill, Roquette Frères, Ingredion Incorporated, Sensient Technologies, Givaudan SA, Kerry Group Plc, Döhler GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Hydrolysate Market Emerging Trajectories
Enzymatic process control and regulatory transparency are converging to reshape how hydrolysate suppliers differentiate, with precision fermentation feedstock demand and carbon-verified supply chains emerging as decisive competitive axes.
Immobilized enzyme reactor technology is modularizing production economics for mid-scale hydrolysate manufacturers. Specialty enzyme suppliers in Denmark and the Netherlands now license fixed-bed protease systems that enable batch-to-batch consistency previously achievable only at integrated grain processors. This technology is modularizing capital requirements, allowing regional compounders to enter clean-label savory flavor supply without captive fermentation capacity.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration infrastructure upgrades across enzymatic processing facilities. Hydrolysate manufacturers dependent on cold-chain stability for liquid product lines face compressed timelines to adopt natural refrigerant systems or absorb escalating compliance costs. German and Dutch processing clusters are responding fastest, consolidating spray-drying investments to reduce refrigerated storage dependency.
Direct contracting between hydrolysate producers and precision fermentation startups is displacing traditional distributor-mediated supply in biopharmaceutical nitrogen sourcing. Cultured-meat manufacturers in Singapore and the Netherlands now specify amino acid profiles and endotoxin thresholds that commodity hydrolysate cannot meet, forcing suppliers to invest in analytical certification infrastructure or exit high-margin specialty segments.
Corn Hydrolysate Market Segmentation
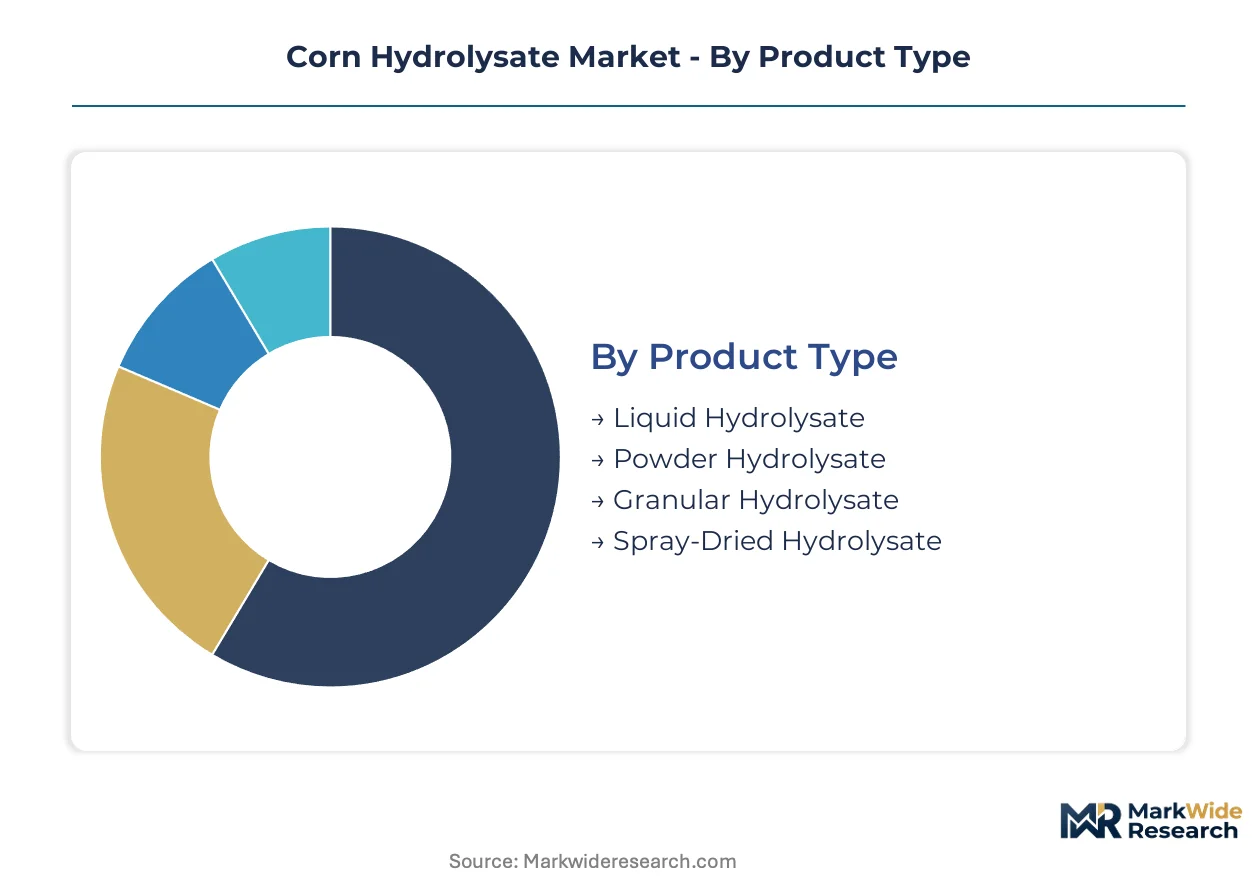
Corn hydrolysate procurement patterns diverge sharply across buyer sophistication tiers, with multinational formulators demanding enzymatic precision while regional compounders prioritize cost-stable feedstock security. Segmentation reveals how hydrolysis depth, physical form, and certification status partition addressable value pools.
Product Type:
Buyers differentiate primarily by handling economics and shelf-stability requirements, with liquid formats suging refrigerated supply chains and dry forms rewarding inventory flexibility.
- Liquid Hydrolysate:Unconcentrated aqueous solution containing 20-40% solids, prized by clean-label broth manufacturers for visible provenance and minimal processing claims. Demand clusters in refrigerated sauce production across the United States and Western Europe, where cold-chain infrastructure justifies premium positioning over spray-dried alternatives.
- Powder Hydrolysate:Spray-dried or roller-dried particulate with moisture content below 5%, dominating dry seasoning blends and savory flavor premixes. Volume concentrates at integrated grain processors in Iowa and Illinois, where captive corn supply and shared drying infrastructure compress unit economics below regional compounder reach.
- Granular Hydrolysate:Agglomerated particles engineered for reduced dusting and improved flow characteristics in high-speed packaging lines. Targeted at industrial soup manufacturers seeking handling efficiency.
- Spray-Dried Hydrolysate:Rapid-atomization product with controlled particle size distribution, specified by pharmaceutical fermentation media suppliers requiring consistent dissolution kinetics.
Powder Hydrolysate leads volumes today; Liquid Hydrolysate is gaining share fastest.
Application:
End-use margins vary threefold across segments, with pharmaceutical nitrogen sourcing commanding analytical certification premiums that food-grade volumes cannot support.
- Food & Beverage:Maillard-reactive precursor for savory flavors, clean-label taste enhancers, and plant-based broths. Formulators in Germany and Japan specify hydrolysate to replace autolyzed yeast extracts and synthetic flavor potentiators, with USDA organic certification unlocking 40-60% price premia in premium sauce categories.
- Animal Feed:Palatability enhancer and digestible protein source for aquaculture and pet nutrition rations. Demand localizes near Southeast Asian shrimp farming clusters and North American pet food manufacturing corridors, where corn gluten meal competition constrains pricing power.
- Pharmaceuticals:Defined nitrogen source for precision fermentation and cell culture media, requiring endotoxin testing and amino acid profile certification. Cultured-meat startups in Singapore and the Netherlands now contract directly for custom hydrolysate compositions.
- Cosmetics:Humectant and film-forming agent in hair care and skin conditioning formulations, representing niche volume with formulation flexibility requirements.
Food & Beverage dominates absolute consumption; Pharmaceuticals shows the steepest expansion trajectory.
Form:
Certification tier and processing history now outweigh physical specifications in buyer RFPs, with organic claims and fermentation-derived positioning commanding procurement priority.
- Organic:USDA-certified hydrolysate from non-GMO corn processed with organic-compliant enzymes, supply-constrained by limited certified grain handling infrastructure. Premium broth manufacturers in the United States and German natural food channels absorb scarcity-driven pricing.
- Non-Organic:Conventional grain-sourced hydrolysate serving cost-sensitive savory flavor and animal nutrition applications where certification adds no formulation value.
- Fermented:Secondary fermentation post-hydrolysis to modify peptide profiles and enhance umami intensity, piloted by Japanese seasoning houses for differentiated taste modulation.
- Concentrated:Reduced-moisture liquid or reconstituted powder formats targeting freight-sensitive export markets and high-solids fermentation inoculation.
Non-Organic maintains volume leadership; Organic climbs fastest as supply scarcity eases.
End User:
Customer scale and technical capability determine supplier engagement models, with multinational food manufacturers demanding dedicated enzymatic tuning that commodity traders cannot fulfill.
- Food Manufacturers:Integrated savory flavor compounders and clean-label sauce producers specifying hydrolysis depth, amino acid distribution, and Maillard reactivity indices. Procurement leverage concentrates among ten multinational buyers controlling 60% of North American and European contract volumes.
- Nutraceutical Companies:Sports nutrition and clinical peptide formulators piloting corn hydrolysate as hypoallergenic alternative to dairy and soy hydrolysates in German and Japanese markets.
- Agricultural Producers:Feed mill operators and aquaculture integrators sourcing palatability enhancers where corn gluten meal price spreads determine substitution economics.
- Personal Care Brands:Cosmetic formulators leveraging hydrolysate film-forming properties in hair conditioning and skin hydration applications with modest volume contribution.
Food Manufacturers anchor current demand; Nutraceutical Companies represent the emerging growth vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized enzyme technologists and precision fermentation scientists concentrate in established biotechnology corridors, anchoring regional production capabilities.
United States
Integrated grain processors dominate hydrolysate supply through captive corn sourcing and shared drying infrastructure. The FDA's streamlined GRAS notification framework accelerates novel composition approvals. Iowa and Illinois processing clusters leverage Midwestern corn belt proximity to compress feedstock logistics costs below import-dependent competitors.
Germany
Clean-label sauce manufacturers and natural food channels absorb scarcity-driven organic hydrolysate pricing. The EU F-Gas Regulation phase-down compels refrigeration infrastructure upgrades across enzymatic facilities. The Cologne-Düsseldorf corridor consolidates spray-drying investments to reduce cold-chain dependency for liquid product lines.
Netherlands
Cultured-meat startups in Wageningen and Eindhoven specify amino acid profiles and endotoxin thresholds that commodity hydrolysate cannot satisfy. The EU Green Deal carbon accounting requirements enable verified low-carbon hydrolysate suppliers to capture procurement premiums. Rotterdam-Antwerp logistics hubs facilitate direct contracting between producers and precision fermentation facilities.
Japan
Seasoning houses pilot secondary fermentation post-hydrolysis to modify peptide profiles and enhance umami intensity. METI guidance on fermentation-derived food ingredients shapes regulatory clarity for novel hydrolysate applications. The Kansai industrial belt concentrates umami technology expertise that drives differentiated taste modulation demand.
Singapore
Biopharmaceutical nitrogen sourcing from precision fermentation facilities creates pull-through demand for certified hydrolysate compositions. The national food agency's novel food regulatory framework accommodates cultured-meat media requirements. Biopolis research clusters anchor analytical certification infrastructure investments for specialty segment suppliers.
Corn Hydrolysate Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The market structure concentrates procurement leverage among ten multinational buyers controlling the majority of contract volumes. Three archetypes dominate: integrated grain processors with captive feedstock, specialized enzyme technology licensors, and regional compounders leveraging modular immobilized reactor systems. Capacity expansion and strategic enzyme licensing partnerships constitute the dominant competitive moves.
Among integrated processors, ADM and Cargill exemplify the feedstock-security archetype through their Midwestern grain network presence. Tate & Lyle PLC occupies a position within the enzyme-technology tier, representing specialized hydrolysis depth control capabilities. These three entities anchor the competitive spectrum from commodity volume to precision formulation.
| Leading Market Players |
|---|
| ADM |
| Tate & Lyle PLC |
| Cargill |
| Roquette Frères |
| Ingredion Incorporated |
| Sensient Technologies |
| Givaudan SA |
| Kerry Group Plc |
| Döhler GmbH |
| Others |
Supply Flow & Price Mechanics
Immobilized enzyme reactor licensing from Danish and Dutch technology providers is compressing capital barriers for mid-scale hydrolysate manufacturers while fragmenting supply concentration away from integrated grain processors. This modular production shift simultaneously erodes feedstock-security premia at legacy facilities and enables regional compounders to undercut on price through reduced refrigeration infrastructure.
Pricing Analysis
Enzyme licensing bundled with technical service contracts commands premium positioning against unbundled commodity enzyme procurement. Three-tier pricing structure across organic-certified, food-grade standard, and animal feed economy levels reflects USDA certification scarcity and analytical testing burdens. Cost compression in the standard tier is intensifying as immobilized reactor technology diffuses process control capabilities. Animal feed buyers exhibit highest price sensitivity due to corn gluten meal substitution elasticity, while pharmaceutical fermentation customers absorb premia for endotoxin-certified custom compositions.
Supply Chain Analysis
Workforce availability constraints in Iowa and Illinois processing clusters tether capacity expansion to agricultural engineering labor pools rather than capital deployment alone. Corn supply concentrates in the United States Midwest, with enzyme technology inputs drawing from Denmark and the Netherlands. Single-source vulnerability runs through proprietary protease licensing agreements held by specialized enzyme houses. Distribution runs through direct contracting with precision fermentation startups displacing traditional distributor mediation in pharmaceutical nitrogen sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in corn hydrolysate rests on carbon-accounting verification capturing EU Green Deal procurement premia and organic certification scarcity sustaining forty-to-sixty percent price tiers in premium sauce categories.
For Market Incumbents: Cement feedstock-security advantages through backward integration into certified organic corn handling infrastructure before USDA handling capacity expands. Defend against modular reactor entrants by embedding analytical certification services into long-term fermentation media contracts that regional compounders cannot replicate. For New Entrants and Emerging Players: The premium-to-economy price gap in organic hydrolysate offers white-space entry through toll-processing arrangements with existing grain elevators lacking enzymatic capabilities. Target German and Japanese nutraceutical channels with hypoallergenic positioning against dairy and soy peptides. Pursue direct contracting with cultured-meat startups specifying amino acid profiles as the go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders possessing immobilized reactor installations but lacking brand recognition in pharmaceutical channels. Long-term viability favors suppliers with dual capability in food-grade volume and analytical-certified specialty tiers. Watch enzyme patent expiration schedules as the inflection signal for process-optimization freedom and margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Technology Licensing | Fixed-bed protease systems from Danish suppliers enable batch-to-batch consistency without captive fermentation capacity. |
| Organic Certification Investment | USDA-compliant handling infrastructure unlocks forty-to-sixty percent premia in premium broth and sauce applications. |
| Carbon Accounting Integration | Lifecycle assessment methodologies aligned with EU Green Deal requirements capture procurement premiums from verified low-carbon production. |
| Direct Contracting with Precision Fermentation | Cultured-meat startups in Singapore and the Netherlands specify endotoxin thresholds that commodity hydrolysate cannot satisfy. |
| Spray-Drying Infrastructure Consolidation | German and Dutch processing clusters reduce cold-chain dependency as EU F-Gas Regulation phase-down compresses refrigeration timelines. |
Methodological Framework
Coverage spans the United States, Germany, the Netherlands, Japan, and Singapore, with primary inputs from each market cluster combining executive interviews with savory flavor compounders, precision fermentation scientists, enzyme technology licensors, and organic certification auditors. Secondary validation draws from FDA GRAS notification filings, USDA organic handling databases, EU F-Gas Regulation implementation schedules, and SEC disclosures from integrated grain processors. Bottom-up volume modeling triangulates against top-down value estimates derived from procurement leverage concentration among multinational food manufacturers.
Rate-of-change decomposition separates volume expansion from value mix-shift across the analysis window, modeling segmentation dimensions including physical form, certification tier, application end-use, and hydrolysis depth specifications. CAGRs were derived from trend extrapolation of enzymatic processing capacity additions, precision fermentation facility buildouts, and organic grain handling infrastructure investments. Forecast inputs incorporate enzyme patent expiration timelines and carbon accounting methodology adoption curves.
Caveats apply where Midwestern US weather patterns disrupting corn supply, accelerated EU refrigeration infrastructure compliance costs, or breakthrough fermentation-derived nitrogen alternatives could materially shift the outlook. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Peat Market
Agricultural Commodities
North America Corn Glucose Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Straw Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Cottonseed Hulls Market