
 Global Wood Chips Market | 2026-2036
Global Wood Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood Chips Market Foresight
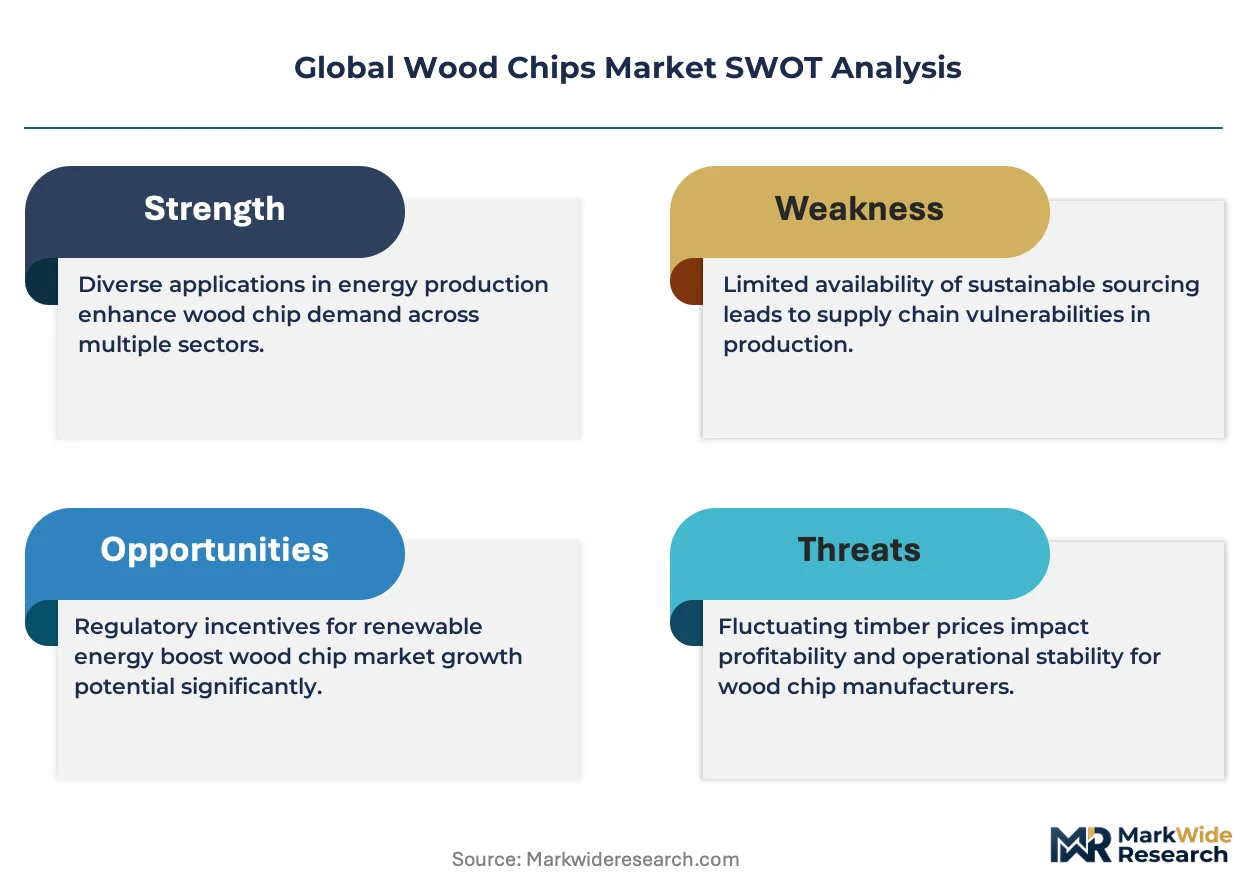
Project finance tied to carbon credit offtake agreements is tilting competitive dynamics toward capital-rich operators. Enviva leverages long-term power purchase agreements to anchor its export terminal network across the US Gulf and Atlantic coasts. Stora Enso sustains integrated pulp-to-paper operations in Finland and Sweden, capturing margin from captive softwood chip supply. West Fraser Timber dominates western Canadian fiber flows, converting sawmill residuals into specification-grade chips for Asian pulp mills.
Wood chips consist of mechanically shredded woody biomass, typically screened to 10–50 mm particle size with moisture content below 25 percent for industrial combustion and pulping applications. Their primary commercial purpose centers on energy conversion via direct firing or gasification, and on cellulose extraction for paper manufacturing. Softwood chips lead volume in pulp and paper applications due to superior fiber length and yield, while biomass wood chips represent the fastest-expanding category as utilities retrofit coal plants for co-firing under renewable portfolio standards. Hardwood chips command premium pricing in composite board manufacturing where density and binding characteristics determine panel performance.
The EU Green Deal and RED III sustainability criteria shape feedstock certification requirements, forcing exporters to demonstrate chain-of-custody compliance for forest-origin materials. EPA renewable fuel standards in the US and Japan's METI biomass feed-in tariff program create divergent quality specifications that fragment export market access. Stakeholders must monitor evolving carbon border adjustment mechanisms and national biomass sustainability protocols to align procurement strategies with regulatory enforcement timelines.
Market Dynamics
Co-firing mandates at coal-dependent utilities are restructuring procurement volumes and certification requirements across the wood chips value chain. Japan's METI feed-in tariff program and South Korea's renewable portfolio standards are pulling Asian-bound exports toward stricter sustainability documentation.
Growth Catalysts
- EU Green Deal enforcement:RED III sustainability criteria mandate chain-of-custody certification for biomass feedstocks, forcing import-dependent utilities to source only verified forest-origin materials. This regulatory pressure is consolidating supplier qualification pools.
- Pulp mill fiber demand:Southeast Asian paper manufacturers are expanding softwood chip consumption for packaging-grade kraft pulp, with Vietnam and Indonesia leading capacity additions.
- Co-firing retrofits:Biomass wood chips represent the fastest-expanding category as coal plant operators seek renewable energy credits under national decarbonization frameworks.
Market Restraints
- Feedstock cost volatility:Sawmill residual availability fluctuates with construction cycles and lumber pricing, compressing chip producer margins during housing downturns.
- Export terminal concentration:US Gulf and Atlantic coast loading capacity remains controlled by a handful of deepwater facility operators, creating bottleneck risk for inland fiber suppliers.
- Moisture specification divergence:EPA renewable fuel standards and Japan's METI quality protocols impose incompatible moisture content thresholds, fragmenting export market access.
Strategic Opportunities
- Carbon credit offtake finance:Project lenders are structuring term debt around verified emission reduction purchases, enabling capital-rich operators to lock in long-term supply contracts.
- Hardwood chip premium positioning:Composite board manufacturers in Germany and Austria pay density-driven premiums for specified hardwood fractions, opening margin expansion beyond commodity pulp grades.
- Integrated terminal-pellet-chip logistics:Multi-product export hubs on the US Atlantic seaboard allow cargo optimization across biomass formats based on vessel size and destination arbitrage.
Industry Challenges
- Certification timeline compression:FSC and PEFC chain-of-custody audits require 12-18 month implementation periods, delaying contract eligibility for new market entrants.
- Gasification reactor integration:Biomass power plant operators face technical complexity when retrofitting fluidized bed systems designed for coal to handle variable chip size distributions and ash content.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood Chips Market |
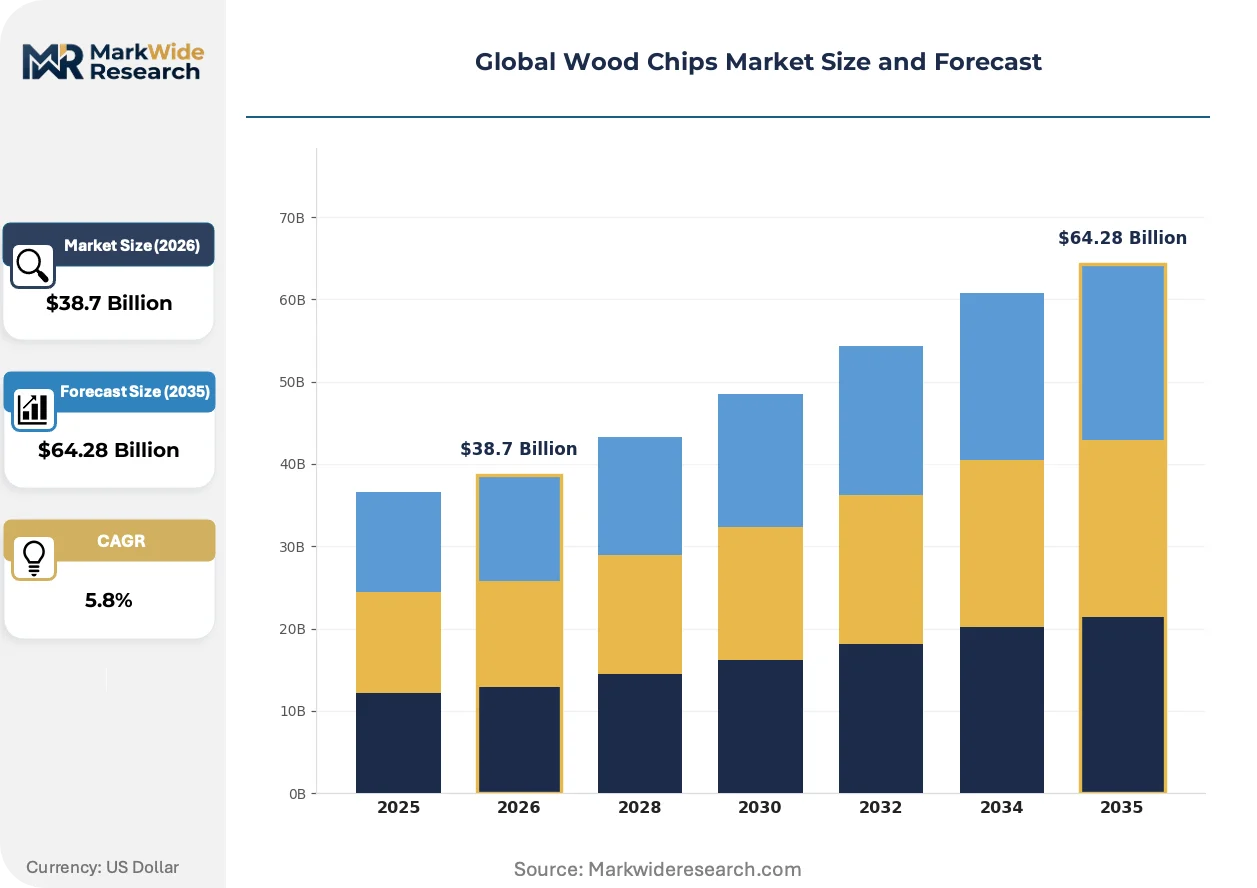
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardwood Chips, Softwood Chips, Mixed Wood Chips, Recycled Wood Chips, Biomass Wood Chips Application: Energy Production, Pulp & Paper, Horticulture Mulch, Animal Bedding, Composite Board Manufacturing End User: Pulp Mills, Biomass Power Plants, Landscaping Firms, Furniture Manufacturers, Agriculture Cooperatives Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Wholesale Dealers, Exporters |
| Companies Covered | Enviva, Stora Enso, West Fraser Timber, Sojitz Corporation, Oji Holdings Corporation, American Wood Resources, Cogent Forest Products, Mitsui & Co., Verdo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood Chips Market Shifts & Advancements
Torrefaction and steam explosion preprocessing technologies are altering fuel specification standards. Digitized forest-to-facility tracking systems are embedding compliance data directly into supply chain operations.
Densification preprocessing via torrefaction is collapsing the energy density gap between raw wood chips and coal, enabling higher substitution rates at retrofitted power stations. Japanese utilities are piloting 30% co-firing blends at existing thermal plants. The technology is collapsing traditional distinctions between biomass and fossil fuel logistics by permitting identical handling equipment.
EU Green Deal carbon border adjustment mechanisms are tightening documentation requirements for imported biomass feedstocks. Industrial consequence falls heaviest on Southeast Asian procurement officers now required to demonstrate deforestation-free sourcing back to forest stand level. Pulp and paper applications face accelerated audit frequency compared to energy-sector buyers.
Buyer consolidation among Japanese power utilities is compressing supplier negotiation leverage and extending contract durations. Spot market liquidity is thinning as Tokyo Electric and Chubu Electric shift toward five-year offtake agreements with fixed volume floors. The behavioral shift is most visible in contract structures for Vietnamese-origin softwood chips.
Global Wood Chips Market Segmentation
Wood chip specifications diverge sharply across end-use requirements, from moisture-sensitive pulp grades to densified fuel formats for power generation. Segmentation discipline separates commodity flows from premium-certified supply chains commanding sustainability premiums.
Product Type:
Mature grades dominate volume throughput while emerging categories capture policy-driven demand acceleration.
- Softwood Chips:Longer fiber length delivers superior yield in kraft pulp production. Demand concentrates in Vietnam and Indonesia where packaging-grade capacity is expanding fastest; fiber properties command specification premiums from Japanese pulp buyers.
- Biomass Wood Chips:Fastest-expanding category as utilities retrofit coal plants for co-firing under renewable portfolio standards. South Korean power utilities are scaling procurement of certified biomass chips under RPS mandates, with moisture content specifications tightening to below 20 percent for fluidized bed compatibility.
- Hardwood Chips:Density characteristics drive premium positioning in composite board manufacturing across Germany and Austria.
- Mixed Wood Chips:Lower-grade feedstock for regional heating plants with relaxed certification requirements.
- Recycled Wood Chips:Post-consumer wood waste streams processed for landscaping and animal bedding applications.
Softwood chips handle the majority of throughput; biomass wood chips are expanding most quickly on share.
Application:
Energy conversion applications are restructuring procurement specifications while fiber extraction remains the margin anchor.
- Pulp & Paper:Dominant value capture segment where fiber length, bark content, and moisture thresholds determine contract pricing. Southeast Asian kraft pulp mills in Vietnam and Indonesia are driving softwood chip import growth for packaging-grade output.
- Energy Production:Co-firing retrofits at coal-dependent utilities are fragmenting quality standards. Japan's METI feed-in tariff program and South Korea's RPS framework impose incompatible sustainability documentation requirements on exporters.
- Composite Board Manufacturing:Hardwood chip density specifications determine panel performance in European engineered wood products.
- Horticulture Mulch:Decorative and moisture-retention applications with lower certification barriers.
- Animal Bedding:Absorbency-driven demand from poultry and dairy operations with regional supply radius constraints.
Pulp and paper commands the value pool; energy production is gaining share fastest on policy momentum.
End User:
Industrial buyers are consolidating contract structures while fragmented agricultural demand retains spot-market characteristics.
- Pulp Mills:Volume anchor with integrated procurement teams managing multi-year offtake agreements. Japanese and South Korean mills are extending contract durations to secure certified fiber streams under tightening EU Green Deal traceability requirements.
- Biomass Power Plants:Technical complexity in retrofitting fluidized bed systems for variable chip specifications. Southeast Asian operators face compressed certification timelines as RED III chain-of-custody audits require 12-18 month implementation periods.
- Furniture Manufacturers:Hardwood chip demand for particleboard and medium-density fiberboard production.
- Landscaping Firms:Seasonal procurement patterns with localized supply radius preferences.
- Agriculture Cooperatives:Dispersed demand for bedding and mulch applications with price-sensitive purchasing behavior.
Pulp mills anchor contract volume; biomass power plants are climbing the fastest on procurement scale.
Distribution Channel:
Terminal concentration is forcing channel restructuring toward integrated logistics operators.
- Direct Sales:Long-term offtake agreements between integrated producers and utility buyers. Enviva's power purchase agreement-anchored export terminal network exemplifies direct channel control across the US Gulf and Atlantic coasts.
- Exporters:Deepwater facility operators managing certification compliance for Asian-bound cargo. US Gulf and Atlantic coast loading capacity bottleneck risk favors capital-rich terminal operators with multi-product biomass handling capabilities.
- Distributors:Regional intermediaries serving fragmented horticulture and bedding demand.
- Wholesale Dealers:Volume aggregation for domestic pulp and paper mill supply.
- E-commerce Platforms:Emerging channel for specialty graded chips in small-lot horticulture markets.
Direct sales channels handle the majority of industrial volume; exporter channels are gaining share fastest on Asian demand pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping fiber procurement geography. Net importers in East Asia pull volume from North American and European surplus regions, while regulatory divergence fragments compliance pathways.
United States
Deepwater terminal operators along the Gulf and Atlantic coasts aggregate inland fiber flows for Asian-bound cargo. EPA renewable fuel standards impose moisture content thresholds that diverge from Japanese specifications, forcing exporters to maintain dual-grade inventory. The US Southeast timber belt supplies specification-grade softwood chips to Japanese pulp mills through long-term offtake structures.
Japan
Power utilities concentrate procurement through Tokyo Electric and Chubu Electric, extending contract durations to five-year terms with fixed volume floors. METI feed-in tariff programs mandate sustainability documentation that exceeds EU baseline requirements. Port infrastructure at Yokkaichi and Nagoya anchors biomass receiving capacity for co-firing retrofits.
Vietnam
Packaging-grade kraft pulp mills expand softwood chip consumption faster than regional supply growth, deepening import dependence. Government industrial zone incentives attract Japanese and South Korean mill investment near Haiphong and Quang Ninh. RED III chain-of-custody compliance timelines compress procurement officer decision windows.
Germany
Composite board manufacturers in Bavaria and Baden-Württemberg pay density-driven premiums for specified hardwood fractions. EU Green Deal carbon border adjustment mechanisms tighten documentation requirements for imported feedstocks. Hamburg and Bremen terminals handle certified biomass transshipment for continental power utilities.
South Korea
Renewable portfolio standards drive procurement scale at state-affiliated power utilities, with moisture specifications tightening below 20 percent for fluidized bed compatibility. Busan and Incheon receiving infrastructure handles rising Vietnamese and Indonesian chip volumes. KOSPO and KEPCO consolidate supplier qualification pools under stricter sustainability audits.
Global Wood Chips Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. Terminal operators with captive export capacity anchor long-term supply relationships, while residual processors compete on specification-grade sorting. Three archetypes dominate: integrated forest-products conglomerates, dedicated biomass exporters, and sawmill-anchored chip converters. Capacity expansion and certification pre-qualification constitute the primary competitive vectors.
Among North American biomass exporters, Enviva exemplifies the terminal-anchored archetype through power purchase agreement-backed infrastructure. Stora Enso represents integrated Nordic forest-products control of captive softwood supply. West Fraser Timber occupies the sawmill-residual conversion tier, channeling western Canadian fiber into Asian pulp mill specifications.
| Leading Market Players |
|---|
| Enviva |
| Stora Enso |
| West Fraser Timber |
| Sojitz Corporation |
| Oji Holdings Corporation |
| American Wood Resources |
| Cogent Forest Products |
| Mitsui & Co. |
| Verdo |
| Others |
Supply & Pricing Matrix
Moisture specification divergence between EPA renewable fuel standards and Japan's METI protocols fragments export market access, compressing pricing tiers for dual-certified inventory while forcing supply chain bifurcation around incompatible quality thresholds. This regulatory chokepoint widens spreads between specification-grade softwood chips and commodity biomass grades as exporters absorb compliance duplication costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pulp mills locking multi-year volume floors and biomass utilities securing renewable energy credit-linked supply. Price differentiation centers on FSC/PEFC certification tier and moisture content precision, with sub-20 percent moisture grades commanding premiums from South Korean fluidized bed operators. Cost compression in standard-grade biomass chips is intensifying because sawmill residual supply fluctuates with construction cycles, squeezing processor margins during housing downturns. Spot-market liquidity is thinning fastest among Japanese power utilities consolidating procurement through Tokyo Electric and Chubu Electric, making these buyers least price-sensitive while regional heating plants remain most exposed to commodity volatility.
Supply Chain Analysis
Tariff exposure between Vietnam and EU destination markets under carbon border adjustment mechanisms dominates risk planning for Southeast Asian procurement officers now required to demonstrate deforestation-free sourcing. Geographic supply concentration centers on the US Southeast timber belt, western Canadian fiber flows, and Nordic softwood basins in Finland and Sweden. Raw material dependencies rest on sawmill residual streams, roundwood pulp logs, and post-industrial wood waste recovery networks. Single-source vulnerability concentrates at US Gulf and Atlantic coast deepwater terminals controlled by capital-rich operators with multi-product biomass handling capabilities. Distribution runs through integrated terminal-pellet-chip logistics hubs permitting cargo optimization across biomass formats based on vessel size and destination arbitrage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Torrefaction preprocessing threatens to collapse traditional distinctions between raw wood chips and coal-equivalent fuel logistics, forcing incumbents to defend specification-grade positioning against densified substitutes that enable higher co-firing substitution rates.
For Market Incumbents: Pre-empt torrefaction displacement by securing captive softwood supply through backward integration into southeastern US timber holdings or Nordic forest management concessions. Anchor terminal capacity with power purchase agreement-backed infrastructure before Japanese and South Korean utilities complete buyer consolidation into five-year offtake structures. Certification investment in RED III chain-of-custody compliance creates switching costs that delay new entrant contract eligibility for 12-18 month implementation periods. For New Entrants and Emerging Players: Build out hardwood chip fractionation capabilities targeting German and Austrian composite board manufacturers paying density-driven premiums for specified feedstock grades. Vietnam's packaging-grade kraft pulp expansion offers the most penetrable import growth corridor as government industrial zone incentives attract Japanese and South Korean mill investment near Haiphong. Go-to-market positioning should emphasize rapid FSC/PEFC audit completion to exploit compressed procurement officer decision windows under EU Green Deal enforcement timelines. For Investors and Strategic Acquirers: RED III sustainability criteria implementation reshapes the acquisition landscape toward terminal-anchored operators with pre-qualified supplier pools and multi-product biomass handling infrastructure. Long-term viability over the projection horizon favors capital-rich platforms capable of structuring project finance around carbon credit offtake agreements. The acquisition target archetype combines US Gulf or Atlantic coast deepwater terminal control with integrated pellet-chip logistics capabilities. Monitor carbon border adjustment mechanism enforcement intensity as the signal to watch for margin compression timing on non-certified supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Holdings | Captive fiber supply secures margin control against sawmill residual volatility cycles. |
| RED III Chain-of-Custody Certification | EU Green Deal compliance unlocks contract eligibility with import-dependent utilities. |
| Multi-Product Terminal Infrastructure | US Atlantic seaboard hubs optimize cargo across chip, pellet, and torrefied formats. |
| Hardwood Fractionation Capacity | Density-specified grades capture premium positioning in German composite board manufacturing. |
| Power Purchase Agreement Structuring | Long-term offtake anchors project finance for export terminal network expansion. |
Research Methodology
Initial hypotheses were tested against primary input from biomass procurement officers at Japanese and South Korean utilities, pulp mill fiber buyers in Vietnam and Indonesia, terminal operators along the US Gulf and Atlantic coasts, and sustainability certification auditors, then refined through secondary validation against customs trade data, EIA biomass fuel disclosures, FERC infrastructure filings, and EU RED III regulatory documentation. Bottom-up volume modeling across chip type, application, and end-user segments was triangulated with top-down market sizing from trade flow analysis and capacity utilization assessments.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by wood species, moisture specification tier, certification status, and regional regulatory framework, with CAGRs derived from regression analysis of historical trade volumes against policy implementation timelines and co-firing retrofit deployment schedules. Forecast inputs incorporated pulp mill capacity expansion announcements, renewable portfolio standard mandate trajectories, and torrefaction technology pilot program outcomes.
Stress conditions across sawmill residual availability fluctuations, carbon border adjustment mechanism enforcement intensity, and Japanese utility buyer consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and technology adoption curves, with revision triggers including RED III audit timeline compression, fluidized bed retrofit technical failures, and pulp grade specification divergence between Asian markets. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
Straw Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Alfalfa Powder Market
Agricultural Commodities
India Feed Amino Acids Market