
 China Fertilizers Market | 2026-2036
China Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
China Fertilizers Market Outlook
Horticultural plant cultivation is shifting toward high-value greenhouse operations, altering nutrient formulation requirements across the China Fertilizers Market. Yuntianhua Group leverages its phosphate mining assets to control upstream raw material costs. Kingenta Group specializes in compound fertilizer blends tailored to soil-specific deficiencies. Sinochem Group extends its distribution reach through port-accessible storage infrastructure along eastern coastal provinces.
China fertilizers encompass nitrogenous, phosphatic, potassic, and compound formulations synthesized through Haber-Bosch ammonia oxidation, phosphate rock acidulation, or potassium salt dissolution, with nutrient content expressed as N-P-K percentages and applied to correct soil macronutrient deficiencies in commercial agriculture. Compound formulations command widening margin pools as farmers seek multi-nutrient efficiency in single applications. Liquid forms gain traction in drip irrigation systems across water-scarce northern plains. Granular products retain dominance in broadacre field crops where mechanized spreading prevails.
MEE enforces ammonia emission caps and wastewater discharge limits that force retrofit investments at older urea plants, while GB standards mandate heavy metal limits in phosphate fertilizers to protect soil quality. China's dual carbon goals accelerate coal-to-gas feedstock transitions at nitrogen facilities. Stakeholders must monitor feedstock cost volatility and provincial carbon intensity benchmarks to align capacity planning with regulatory trajectories.
Market Dynamics
China's dual carbon goals from MEE are forcing a feedstock transition from coal to natural gas at nitrogen facilities, compressing margins for ammonia-based producers while specialty compound formulations capture widening margin pools.
Growth Catalysts
- Greenhouse horticulture expansion:High-value protected cultivation in Shandong and Jiangsu provinces is driving demand for water-soluble compound fertilizers with precise N-P-K ratios tailored to hydroponic systems.
- MEE ammonia emission caps:The Ministry of Ecology and Environment's tightening standards are accelerating technology upgrades at older urea plants, creating replacement demand for cleaner production capacity.
- Drip irrigation penetration:Water-scarce northern plains including Hebei and Henan are adopting fertigation systems that favor liquid and soluble fertilizer formulations over traditional granular products.
Market Restraints
- Phosphate rock import dependency:Concentrated Moroccan and Jordanian supply sources expose Chinese phosphatic fertilizer producers to shipping cost volatility and geopolitical supply disruptions.
- Coal-to-gas feedstock conversion costs:MEE carbon intensity benchmarks require capital-intensive retrofits at nitrogen facilities, stranding older coal-gasification assets before full depreciation.
- Soil acidification from over-application:Decades of excessive nitrogenous fertilizer use in intensive farming clusters has degraded soil pH levels, reducing nutrient uptake efficiency and creating substitution pressure toward soil amendments.
Strategic Opportunities
- Central Plains mechanization gap:Anhui and Hubei provinces retain significant smallholder acreage where professional crop service companies can displace direct farmer procurement through bundled input-application packages.
- Controlled-release coating technology:Polymer-coated urea convergence with precision agriculture hardware enables variable-rate application systems that reduce nutrient loss and command premium positioning.
- Rural e-commerce channel development:Alibaba's village-level Taobao stations and Pinduoduo's agricultural vertical are opening direct manufacturer-to-farmer distribution, bypassing traditional county-level dealer networks.
Industry Challenges
- Agronomy expertise shortage:Compound fertilizer blending requires soil-testing capabilities and prescription formulation skills that outpace technical training pipeline output in county extension services.
- GB standard compliance timelines:Heavy metal limits in phosphate fertilizers mandate raw material sourcing changes and process validation periods that delay product recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Fertilizers Market |
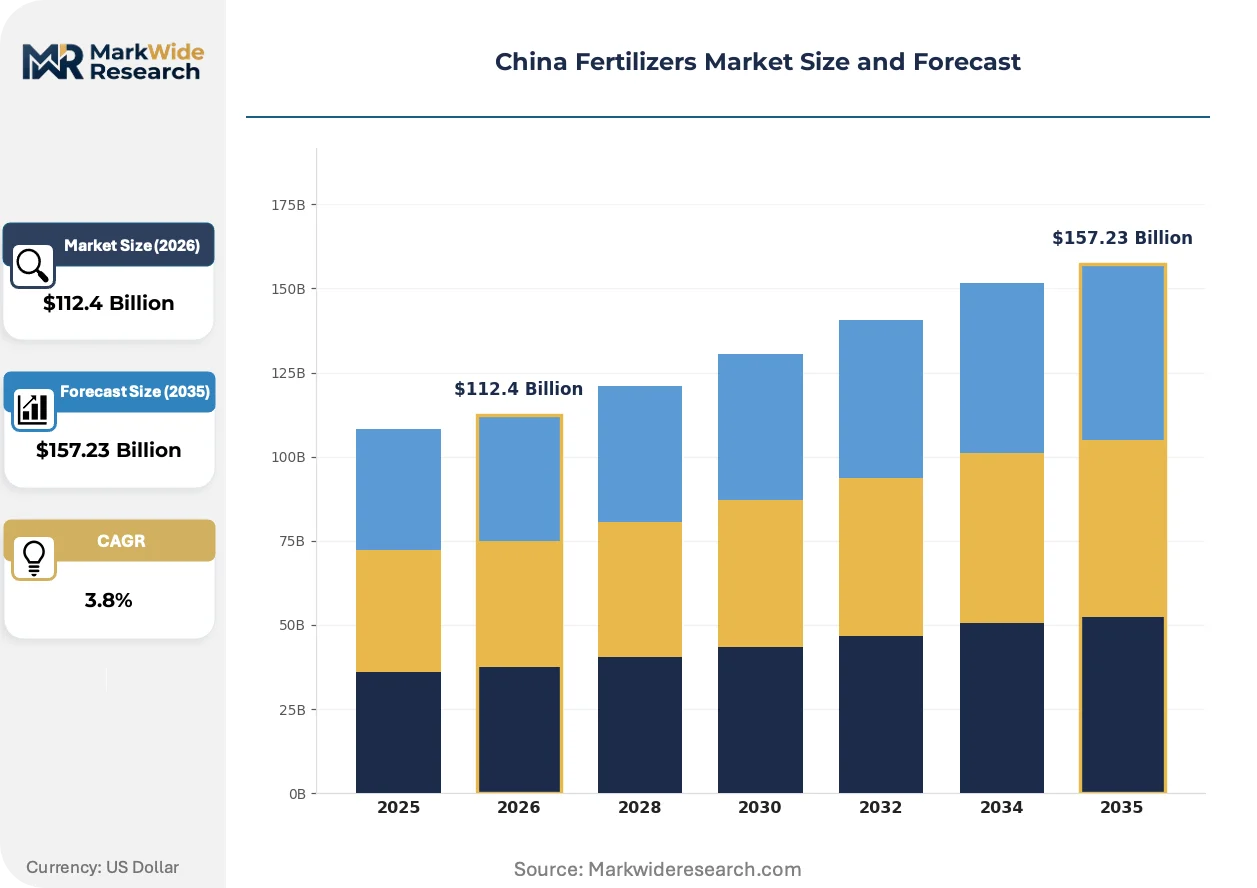
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $157.23 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen, Phosphorus, Potassium, Compound Application: Agricultural Crops, Horticultural Plants, Turf, Ornamental Plants Form: Granular, Liquid, Powder, Coated Distribution Channel: Online Sales, Retail Stores, Distributors, Wholesalers |
| Companies Covered | Yuntianhua Group, Yihua Group, Kingenta Group, Sinofert Holdings Limited, Xinyangfeng Agricultural Technology Co., Ltd., Henan Xinlianxin Chemicals Group Company Limited, Sinochem Group, Wengfu Group, Luxi Chemical Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Fertilizers Market Strategic Shifts
Digital agriculture platforms and precision application hardware are converging with advanced fertilizer formulations to reshape how nutrients are prescribed, distributed, and applied across China's fragmented farming landscape.
Variable-rate spreaders integrated with soil sensors and GPS mapping are automating nutrient application decisions that previously relied on farmer experience. Large-scale cooperatives in Heilongjiang and Inner Mongolia are deploying these systems fastest, attracted by per-hectare input cost reductions. The technology is automating the translation of soil test data into prescription maps, compressing the role of traditional agronomists in input selection.
MEE's dual carbon implementation rules are mandating energy consumption benchmarks that phase out fixed-bed gasification technology at nitrogen plants. Facilities in Shanxi and Shaanxi provinces face the steepest retrofit requirements due to aging coal-based infrastructure. Compound fertilizer producers with integrated ammonia capacity are responding by accelerating stranded asset write-downs and relocating production to coastal gas terminal access points.
County-level agricultural input dealers are consolidating as professional crop service companies bundle fertilizer supply with drone application and soil testing. This model displaces the traditional cash-and-carry transaction at rural supply cooperatives. The shift is most advanced in Jiangsu and Zhejiang, where labor costs and farm size thresholds first justified outsourced nutrient management services.
China Fertilizers Market Segmentation
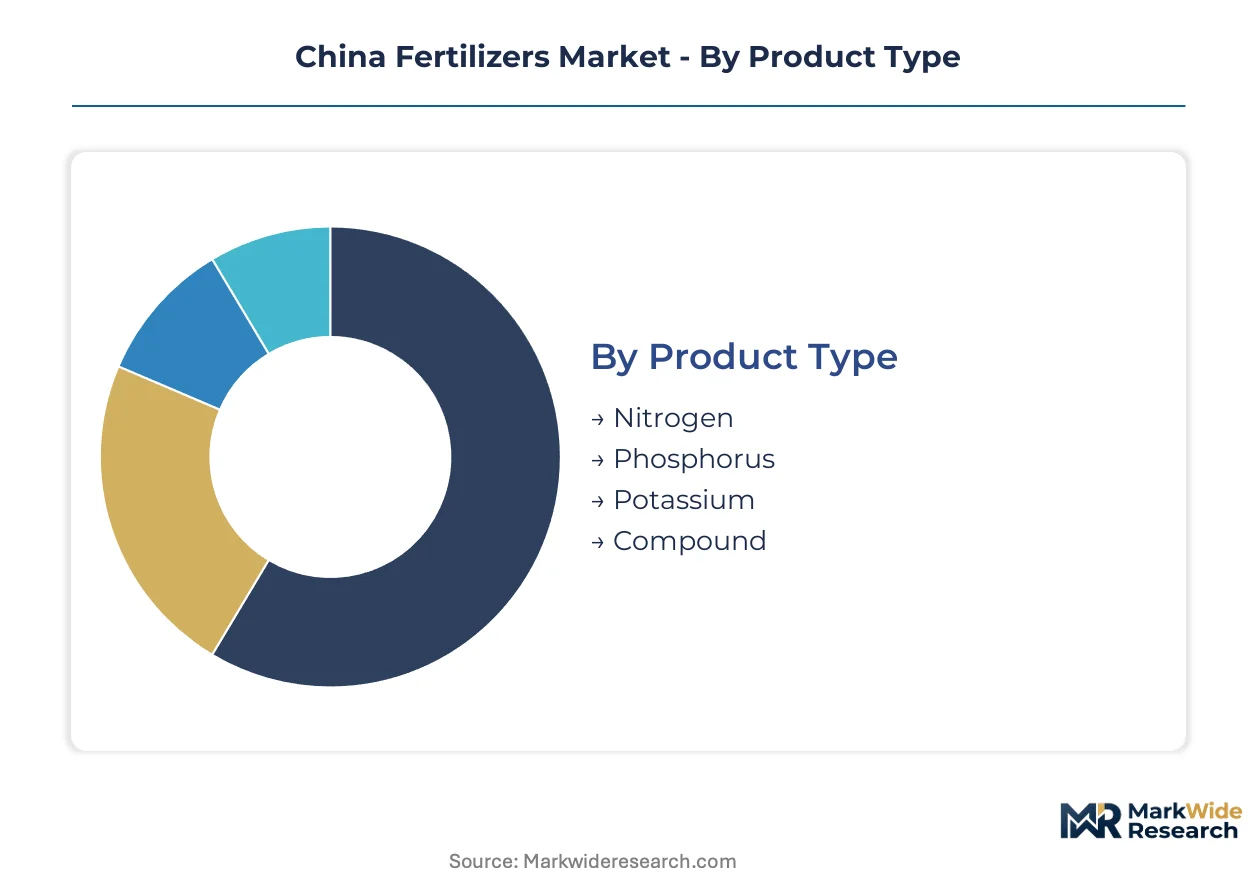
China's fertilizer market segments along four intersecting axes that determine procurement patterns, application technology, and margin capture. Product chemistry dictates feedstock exposure and regulatory compliance burden. Application context shapes formulation requirements and service intensity.
Product Type:
Technical specifications around nutrient content and synthesis pathway define cost structures and environmental compliance exposure across nitrogen, phosphorus, potassium, and compound categories.
- Nitrogen:Urea and ammonium-based formulations synthesized through Haber-Bosch ammonia oxidation dominate volume. Shandong and Henan intensive farming clusters drive procurement despite MEE emission caps forcing coal-to-gas retrofits at production facilities.
- Phosphorus:Phosphate rock acidulation yields superphosphate and diammonium phosphate with P2O5 content specifications. Import dependency on Moroccan and Jordanian rock concentrates exposes margin volatility from freight cost swings and geopolitical supply disruptions.
- Potassium:MOP and SOP formulations from potassium salt dissolution address sulfur-deficient soils. Xinjiang domestic mines and Canadian/Belarusian imports supply chloride-sensitive horticultural operations in Jiangsu greenhouse belts.
- Compound:Blended N-P-K formulations with micronutrient packages target soil-specific deficiencies. Water-soluble grades gain traction in fertigation systems across water-scarce Hebei plains.
Compound formulations lead on momentum; nitrogen maintains scale dominance despite regulatory compression.
Application:
End-use context determines nutrient formulation precision, service bundling requirements, and price realization potential across agricultural and specialty cultivation segments.
- Agricultural Crops:Broadacre field applications for wheat, corn, and rice prioritize cost-per-hectare efficiency. Mechanized spreading in Heilongjiang and Inner Mongolia cooperatives favors granular nitrogen-phosphorus blends.
- Horticultural Plants:Greenhouse vegetables and fruit operations demand water-soluble compounds with precise N-P-K ratios. Shandong and Jiangsu protected cultivation expansion drives premium formulation uptake.
- Turf:Golf courses and municipal landscaping require slow-release nitrogen with iron micronutrient packages. Coastal province municipalities in Zhejiang and Fujian concentrate procurement.
- Ornamental Plants:Nursery and floriculture operations specify acid-forming phosphorus sources and controlled-release coatings. Guangdong Pearl River Delta export-oriented cultivation anchors demand.
Agricultural crops dominate procurement volumes; horticultural plants command the steepest expansion trajectory through greenhouse intensification.
Form:
Physical state determines compatibility with application equipment, storage requirements, and nutrient loss characteristics across granular, liquid, powder, and coated variants.
- Granular:Hard prilled or extruded pellets suit mechanized broadcast spreaders. Broadacre field crops in Anhui and Hubei retain granular dominance where equipment penetration lags precision agriculture adoption.
- Liquid:Urea-ammonium nitrate solutions and suspension concentrates integrate with drip irrigation. Northern plains water scarcity accelerates fertigation conversion in Hebei and Henan.
- Powder:Fine-ground compounds for foliar spray and greenhouse mixing stations. Jiangsu high-value vegetable operations specify powder for hydroponic reservoir preparation.
- Coated:Polymer-sulfur encapsulated urea enables variable-rate precision application. Large-scale cooperatives in Heilongjiang deploy coated products with GPS-guided spreaders to reduce leaching losses.
Granular forms retain volume leadership; liquid formulations are expanding most quickly through irrigation infrastructure investment.
Distribution Channel:
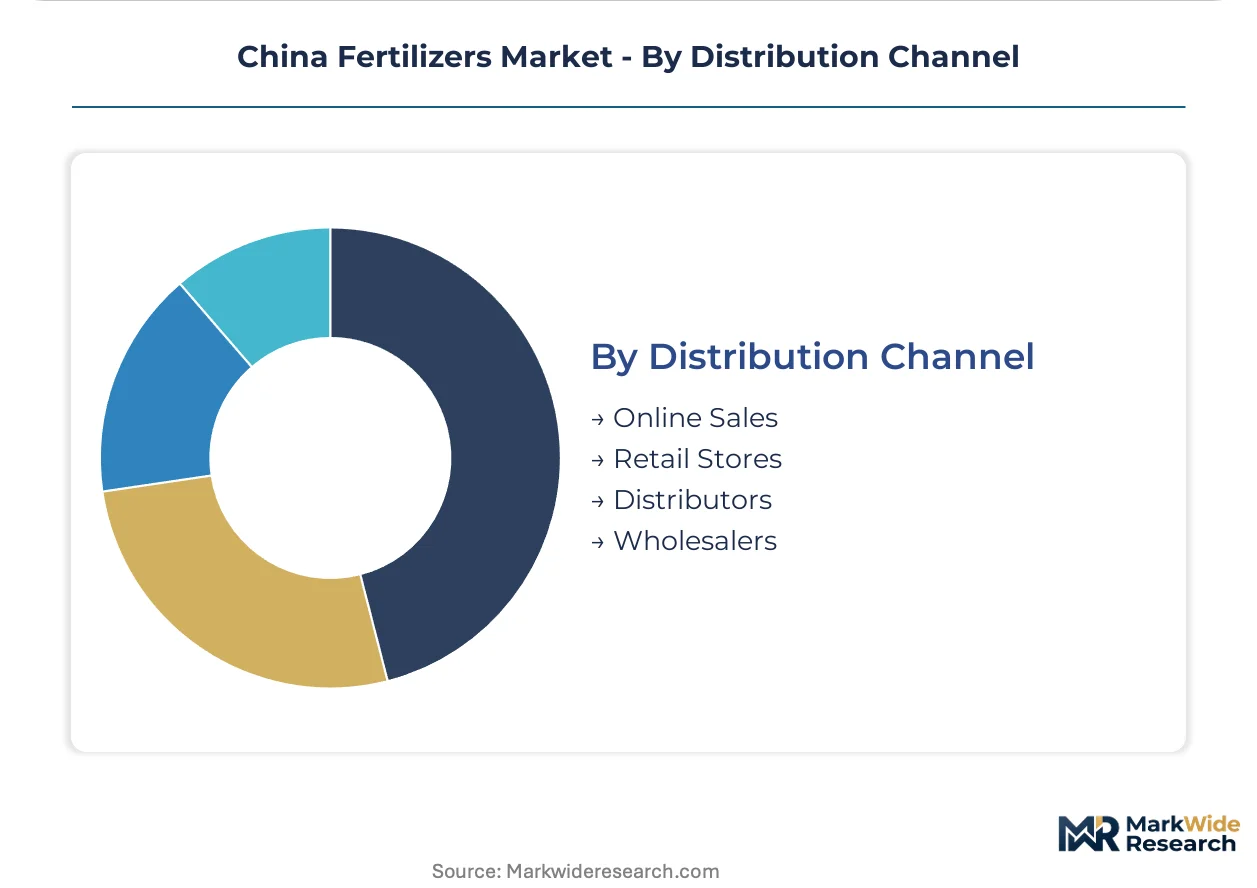
Channel structure determines customer reach, working capital intensity, and service bundling potential across digital platforms, retail networks, and wholesale intermediaries.
- Online Sales:Alibaba Taobao village stations and Pinduoduo agricultural verticals enable direct manufacturer-to-farmer transactions. Younger operators in Jiangsu and Zhejiang bypass county dealer markups through mobile procurement.
- Retail Stores:County-level agricultural supply cooperatives maintain physical presence for immediate fulfillment. Cash-and-carry transactions persist in Central Plains smallholder markets.
- Distributors:Regional warehousing networks with agronomy service capabilities. Professional crop service companies in Anhui bundle distribution with drone application and soil testing.
- Wholesalers:Volume aggregation for cooperative and state-farm procurement. Port-accessible storage infrastructure along eastern coastal provinces supports import compound blending.
Distributor networks lead on current revenue capture; online sales channels gain share fastest through rural e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Henan provinces anchor China's fertilizer procurement, with intensive farming clusters driving volume concentration in the North China Plain while provincial carbon intensity benchmarks reshape production geography.
Shandong Province
Greenhouse horticulture expansion in Weifang and Yantai drives water-soluble compound fertilizer uptake for high-value vegetable cultivation. MEE ammonia emission caps force coal-to-gas retrofits at nitrogen facilities clustered around Dongying petrochemical zones. The Shouguang vegetable production belt concentrates demand for precision N-P-K formulations tailored to hydroponic systems.
Henan Province
Wheat and corn rotation across the Central Plains sustains granular nitrogen-phosphorus blend consumption at scale. GB standards mandate heavy metal limits in phosphate fertilizers, compelling raw material sourcing shifts at Zhengzhou-area blending operations. The Xuchang agricultural machinery corridor mechanizes fertilizer application across cooperative-consolidated acreage.
Jiangsu Province
Protected cultivation in Suzhou and Nantong commands premium compound formulations with micronutrient packages for export-oriented vegetable production. Provincial dual carbon implementation rules accelerate energy consumption benchmarking at older urea plants. The Yangzhou port-accessible storage infrastructure supports import compound blending for coastal distribution.
Hebei Province
Water-scarce northern plains accelerate drip irrigation penetration favoring liquid urea-ammonium nitrate solutions over traditional granular products. MEE wastewater discharge limits constrain phosphate fertilizer production around Shijiazhuang industrial zones. The Zhangjiakou high-altitude vegetable belt adopts fertigation systems to reduce nutrient leaching losses.
Heilongjiang Province
Large-scale cooperatives in the Sanjiang Plain deploy GPS-guided variable-rate spreaders with polymer-coated urea for mechanized broadacre application. Provincial soil acidification from decades of nitrogen over-application creates substitution pressure toward soil amendments. The Harbin agricultural input distribution hub consolidates procurement for state-farm acreage.
China Fertilizers Market Competitive Environment
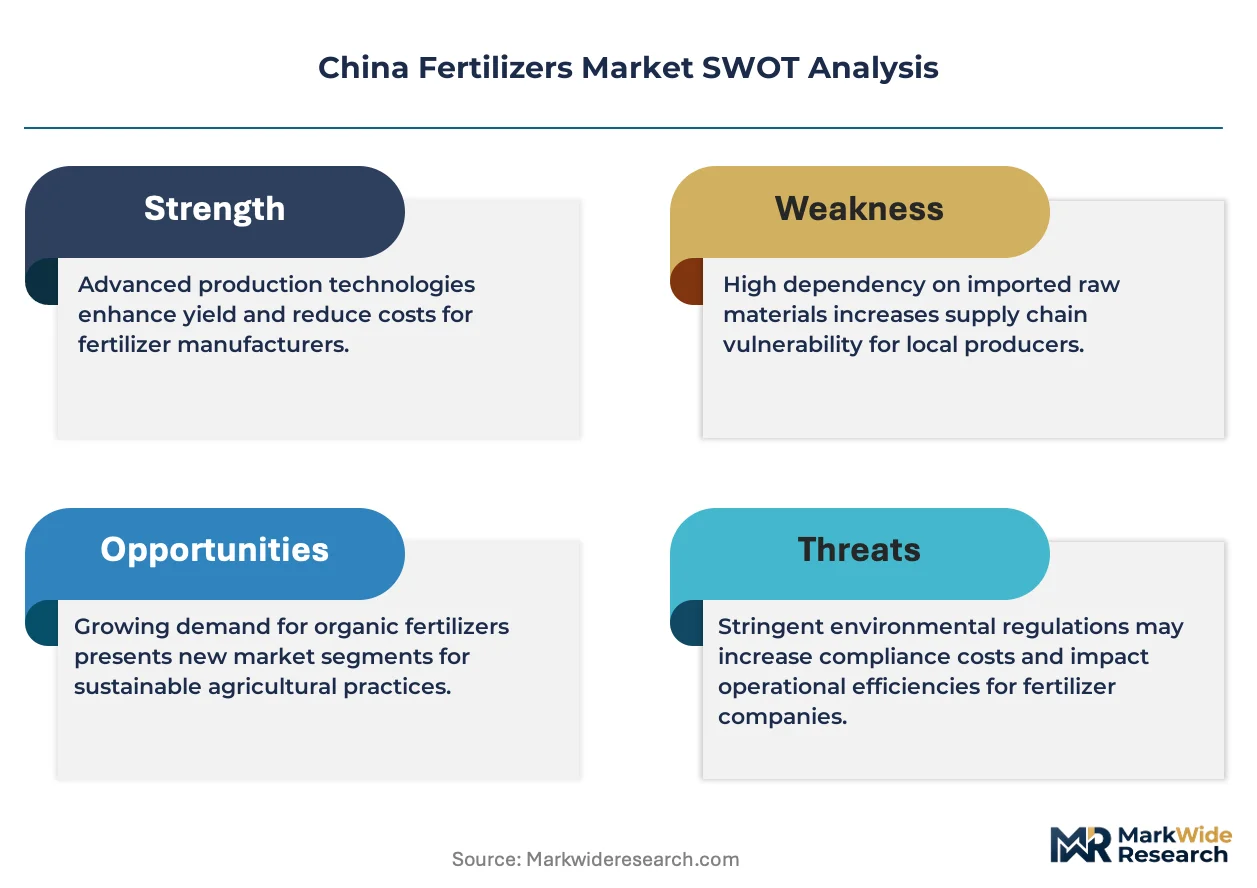
Capacity relocation dominates the current landscape as nitrogen producers abandon inland coal-gasification assets for coastal gas terminal access. The vendor base clusters around three strategic archetypes: state-owned integrated chemical conglomerates with captive phosphate mining, specialized compound fertilizer blenders with soil-testing service capabilities, and regional distributors consolidating into professional crop service companies. M&A activity concentrates on county-level dealer networks, while technology licensing partnerships proliferate for controlled-release coating formulations.
Among upstream-integrated producers, Yuntianhua Group and Wengfu Group occupy positions anchored by phosphate rock mining assets that buffer raw material cost volatility. Kingenta Group exemplifies the formulation-specialist archetype with soil-specific compound blending capabilities. Sinochem Group represents the distribution-scale tier through port-accessible storage infrastructure spanning eastern coastal provinces. These three archetypes reflect the market's segmentation between resource control, technical service intensity, and logistics reach.
| Leading Market Players |
|---|
| Yuntianhua Group |
| Yihua Group |
| Kingenta Group |
| Sinofert Holdings Limited |
| Xinyangfeng Agricultural Technology Co., Ltd. |
| Henan Xinlianxin Chemicals Group Company Limited |
| Sinochem Group |
| Wengfu Group |
| Luxi Chemical Group |
| Others |
Value Chain & Pricing Dynamics
State-farm procurement clusters in Heilongjiang and Inner Mongolia negotiate volume-based contract pricing that anchors the broader market's tiered structure across premium compound formulations and economy-grade nitrogen products.
Pricing Analysis
Distributor margins compress as professional crop service companies bundle application services with product supply, eroding traditional county-dealer markups. Price differentiation rests on soil-testing service inclusion and controlled-release coating technology. Pricing pressure intensifies from coal-to-gas feedstock conversion costs at nitrogen facilities. Smallholder farmers in Anhui and Hubei remain most price-sensitive; greenhouse operators in Shandong and Jiangsu absorb premiums for precision N-P-K formulations.
Supply Chain Analysis
Direct-to-farmer channels through Alibaba Taobao village stations and Pinduoduo agricultural verticals displace traditional wholesale intermediaries in Jiangsu and Zhejiang. Raw material sourcing draws from Moroccan phosphate rock, Canadian potash, and domestic Xinjiang potassium mines. Supply chain vulnerability centers on maritime shipping cost volatility for imported rock concentrate. Distribution runs through port-accessible storage infrastructure along eastern coastal provinces supporting import compound blending.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in specialty compound formulations as MEE emission caps force cost rationalization at commodity nitrogen producers and premium-tier demand accelerates in greenhouse horticulture.
For Market Incumbents: Acquire stranded coal-gasification assets in Shanxi and Shaanxi for coastal relocation to gas terminal access points. Consolidate county-level dealer networks into professional crop service companies bundling drone application and soil testing to defend against direct manufacturer-to-farmer digital channels. For New Entrants and Emerging Players: County-level agricultural input dealers in Anhui and Hubei represent the most penetrable channel layer for partnership-based entry. Target smallholder mechanization gaps through bundled input-application packages rather than commodity product supply. Establish agronomy service capabilities to differentiate from pure distribution plays. For Investors and Strategic Acquirers: State-owned chemical conglomerates are the most active acquirer in this space, consolidating phosphate mining assets and port-accessible storage infrastructure. Long-term viability favors compound fertilizer specialists with soil-testing service capabilities over pure commodity nitrogen exposure. Monitor MEE provincial carbon intensity benchmark enforcement as inflection indicator for stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | Yuntianhua and Wengfu Group control upstream rock supply against Moroccan import volatility. |
| Coastal Capacity Relocation | Nitrogen producers abandon inland coal assets for gas terminal access in Shandong and Jiangsu. |
| Controlled-Release Coating Technology Licensing | Polymer-encapsulated urea enables GPS-guided variable-rate application in Heilongjiang cooperatives. |
| Rural E-Commerce Channel Development | Alibaba and Pinduoduo platforms bypass traditional county dealer networks in Zhejiang. |
| Professional Crop Service Consolidation | Bundled input-application packages displace cash-and-carry transactions in Jiangsu and Zhejiang. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining discussions with plant managers at nitrogen and compound fertilizer facilities, procurement leads at agricultural cooperatives, distribution channel partners in county supply networks, and technical R&D directors at formulation specialists. Secondary validation drew from customs and trade data for phosphate rock and potash imports, MEE emission compliance disclosures, GB standard certification records, and provincial agricultural input statistics. Bottom-up capacity and consumption estimates triangulated against top-down market sizing.
Comparable historical periods anchored projections across the modeling period without reliance on single-year anomalies. Segmentation dimensions included product chemistry tier, application context, physical formulation, and distribution channel structure. CAGRs were derived from trend extrapolation adjusted for regulatory phase-in timelines and feedstock transition cost curves. Forecast inputs incorporated MEE dual carbon implementation enforcement intensity and greenhouse horticulture expansion rates in Shandong and Jiangsu.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Moroccan phosphate supply disruptions and MEE wastewater discharge limit expansion to additional provinces. Projections reflect assumptions around coal-to-gas retrofit completion rates and rural e-commerce penetration trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
GCC Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Africa Micronutrient Fertilizer Market