
 Artificial Fishing Baits Market | 2026-2036
Artificial Fishing Baits Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Fishing Baits Market Insights
Market Context
China is fragmenting artificial fishing bait production across coastal manufacturing zones and inland mold-making clusters. Rapala VMC Corporation leverages its Finnish design heritage with Asian contract manufacturing to sustain margin discipline across premium hard bait lines. Shimano anchors its position through proprietary resin formulations and tight control over Japanese domestic distribution. Pure Fishing Inc. competes via volume scale in North American big-box retail, while Daiwa differentiates through magnetic weight-transfer systems in saltwater plugs.
Technical Definition and Segment Structure
Artificial fishing baits are engineered lures designed to simulate prey morphology, reflectance, and kinematic behavior through controlled material density, hydrodynamic profiling, and embedded sound or vibration mechanisms; manufacturers injection-mold thermoplastic elastomers, machine aluminum alloy bodies, or hand-pour biodegradable polymers to achieve target sink rates and action patterns that trigger predatory fish strikes. Soft baits dominate unit volume due to low per-lure cost and high replacement frequency among recreational anglers, while hard baits concentrate value pools in tournament-grade segments where precision tolerances command price premiums. Metal spoons and jigs retain stable demand in commercial and industrial fisheries where durability under mechanical stress outweighs aesthetic refinement.
Regulatory Environment
The EPA monitors phthalate content in plastic formulations, while EU REACH restricts persistent organic compounds in rubber and foam components; California's Proposition 65 labeling requirements add compliance layers for brands distributing in the United States. ISO 14001 environmental management certifications increasingly gate access to European retail procurement programs. Stakeholders must monitor evolving material bans and traceability mandates to preserve market access and avoid stranded inventory in regulated jurisdictions.
Market Dynamics
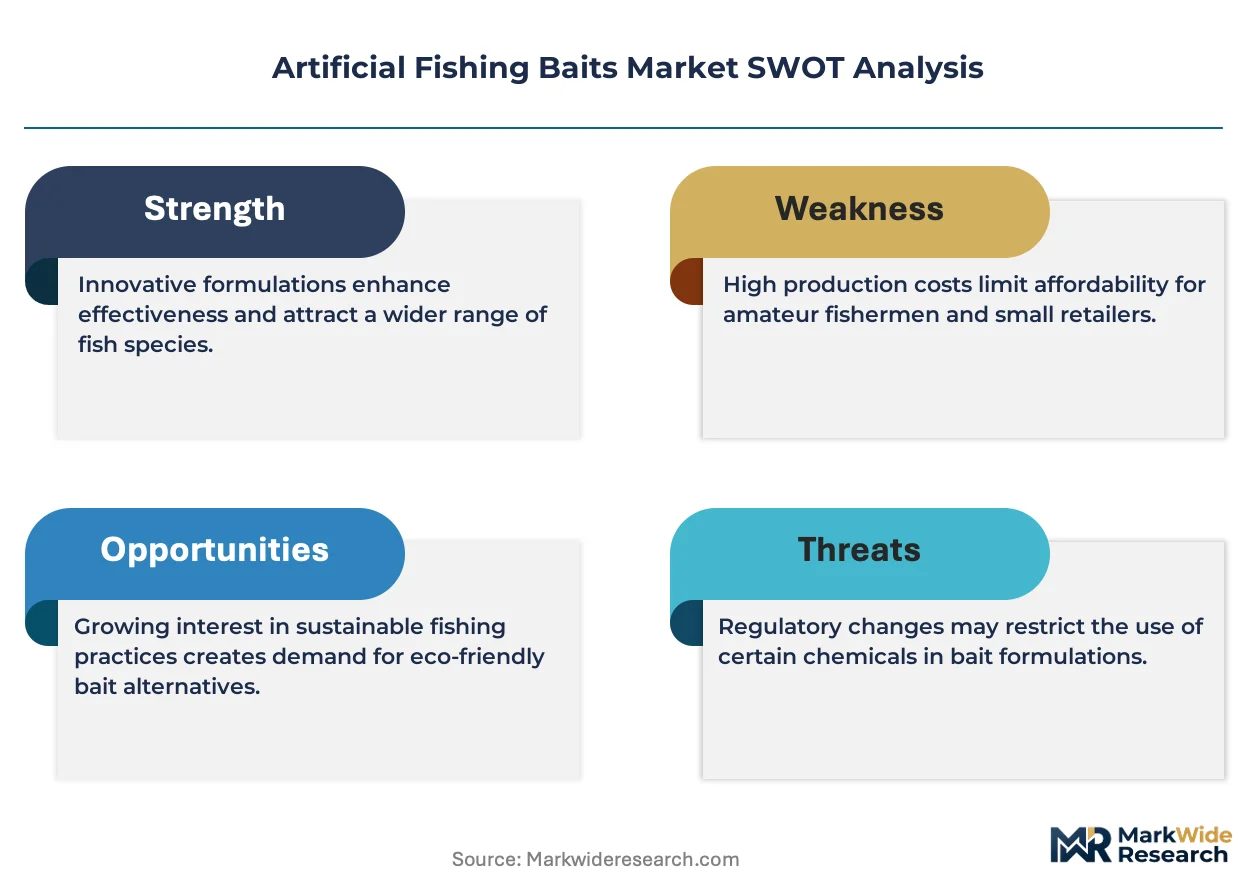
The artificial fishing baits market is being fundamentally restructured by regulatory pressure on petrochemical-derived plastics, forcing manufacturers to reformulate soft bait chemistries and requalify supply chains under stricter environmental frameworks.
Growth Catalysts
- Biodegradable polymer chemistry:Aliphatic polyester formulations derived from corn starch and castor oil now deliver comparable tensile strength to PVC-based soft baits. Recreational anglers in the Great Lakes basin are switching to these alternatives to avoid microplastic accumulation penalties.
- EU REACH substance restrictions:The European Chemicals Agency's tightening limits on phthalates and bisphenol-A in consumer products are accelerating R&D investment in non-toxic plasticizers. Manufacturers with compliant formulations gain preferential shelf placement in EU sporting goods retail.
- Tournament-grade precision molding:Bass fishing competitions in the southeastern United States reward consistent lure action. CNC-machined aluminum injection molds from Japanese toolmakers enable sub-millimeter repeatability that hand-pour operations cannot match.
Market Restraints
- Petrochemical feedstock volatility:Thermoplastic elastomer prices track naphtha and natural gas liquid indices. Mold-makers in China's Zhejiang province face margin compression when resin costs spike without corresponding pricing power in export contracts.
- Single-source concentrate dependence:Fluorescent dye and holographic flake suppliers concentrate in Guangdong province. Any disruption to Pearl River Delta logistics strands downstream bait finishing operations for weeks.
- Biodegradation rate mismatch:Current PLA-PHA blends degrade too quickly in warm freshwater, limiting their utility in subtropical fisheries. Anglers in Florida and Louisiana report lure disintegration before fish strikes occur.
Strategic Opportunities
- Smart lure connectivity:Integration of miniature accelerometers and Bluetooth Low Energy modules enables strike detection and cast analytics. Saltwater charter operators in the Gulf of Mexico are piloting subscription models bundling hardware with catch-data services.
- Direct-to-consumer microbatch channels:Artisanal bait makers in the American Midwest now sell limited-run colorways through Instagram storefronts. These channels bypass big-box retail slotting fees and capture 40-60 point gross margin premiums.
- California Proposition 65 compliance as market access tool:Brands that pre-certify products against the state's chemical warning requirements unlock distribution into specialty retailers who refuse non-compliant inventory. This creates defensive moats against late-adapting competitors.
Industry Challenges
- Master mold fabrication scarcity:Skilled patternmakers capable of hand-shaping balsa wood and urethane prototypes are retiring faster than apprentices replace them. Japanese lure houses now compete for the same Taiwanese carving specialists.
- Multi-jurisdiction labeling complexity:A single soft bait SKU requires distinct packaging for US EPA, EU REACH, and California OEHHA disclosure rules. SKU proliferation strains inventory management systems and increases working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Fishing Baits Market |
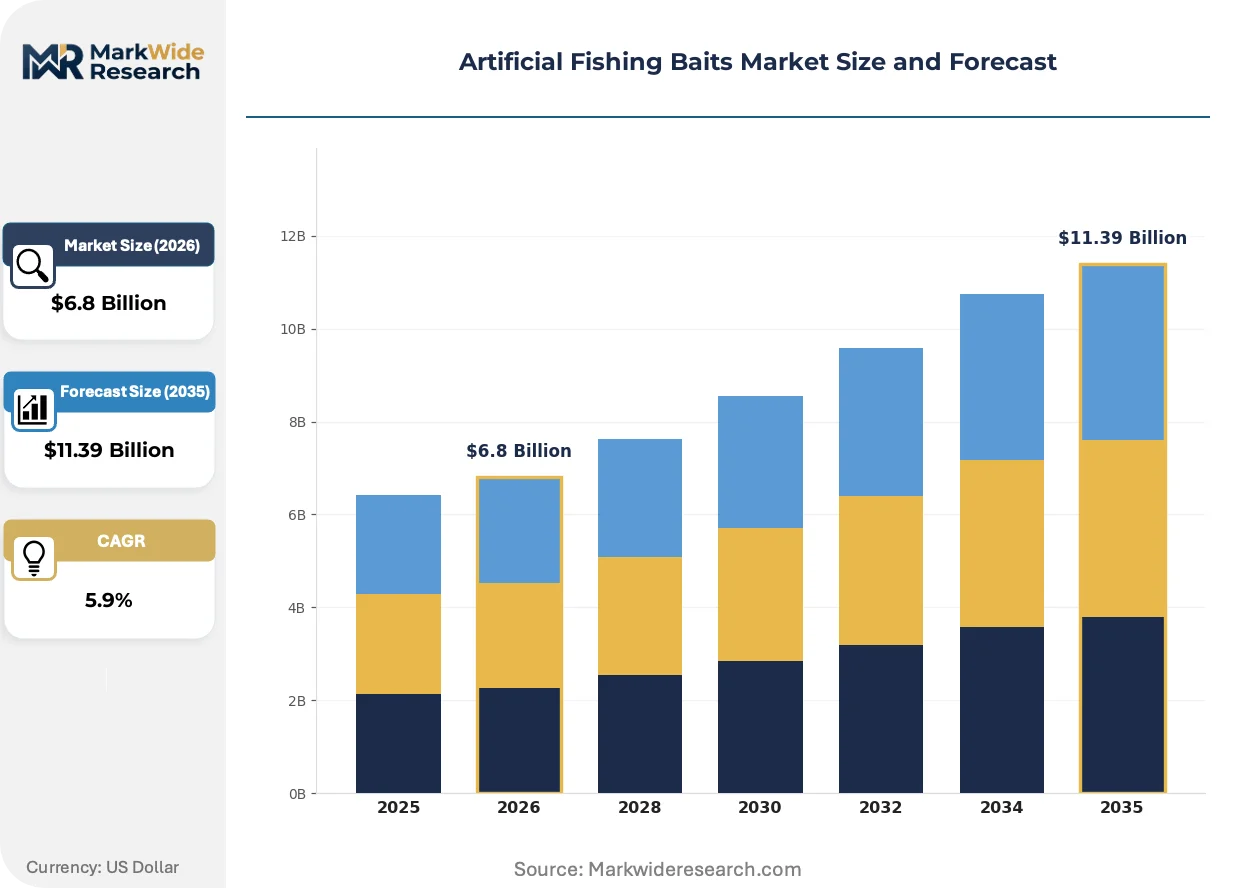
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Baits, Hard Baits, Jigs, Spoons Material: Plastic, Rubber, Foam, Metal End User: Recreational Anglers, Commercial Fishermen, Sports Fishing Enthusiasts, Industrial Fisheries Application: Freshwater Fishing, Saltwater Fishing, Ice Fishing, Fly Fishing |
| Companies Covered | Rapala VMC Corporation, Shimano, Daiwa, Pure Fishing Inc., Berkley, Gamakatsu, Eagle Claw, Duel Co. Ltd., Okuma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Fishing Baits Market Trends and Innovations
Active materials science and connected hardware are converging to transform how anglers select, deploy, and evaluate artificial baits. These developments are compressing product lifecycles and redistributing value toward data-integrated offerings.
Photonic crystal films and micro-prismatic reflective tapes now replace traditional foil laminates in hard bait construction. These nanostructured surfaces manipulate light interference patterns to simulate baitfish scale iridescence across wider viewing angles. Tournament anglers in Texas and Alabama are adopting these lures for low-light conditions where conventional finishes fail. The technology is rendering obsolete decades-old vacuum-metallization processes that dominated premium crankbait manufacturing.
REACH Annex XVII restrictions on microplastics in consumer products are forcing reformulation of soft bait tear-resistant additives. The European Chemicals Agency's 2023 guidance specifically targets synthetic polymer microparticles with dimension thresholds below five millimeters. German and French distributors now require batch-level compositional certificates before purchase order acceptance. Manufacturers serving EU markets are accelerating migration to bio-based thermoplastic polyurethane alternatives despite 15-25 percent raw material cost premiums.
Subscription-based lure curation services are displacing traditional retail discovery for recreational anglers. Monthly boxes from specialized operators deliver seasonal color-matched selections based on regional hatch data and water temperature algorithms. This model concentrates buyer relationships with data-rich platforms rather than brick-and-mortar tackle shops. The shift is most visible in the Pacific Northwest, where urban anglers lack proximity to specialty retailers but maintain high engagement with digital fishing communities.
Artificial Fishing Baits Market Segmentation
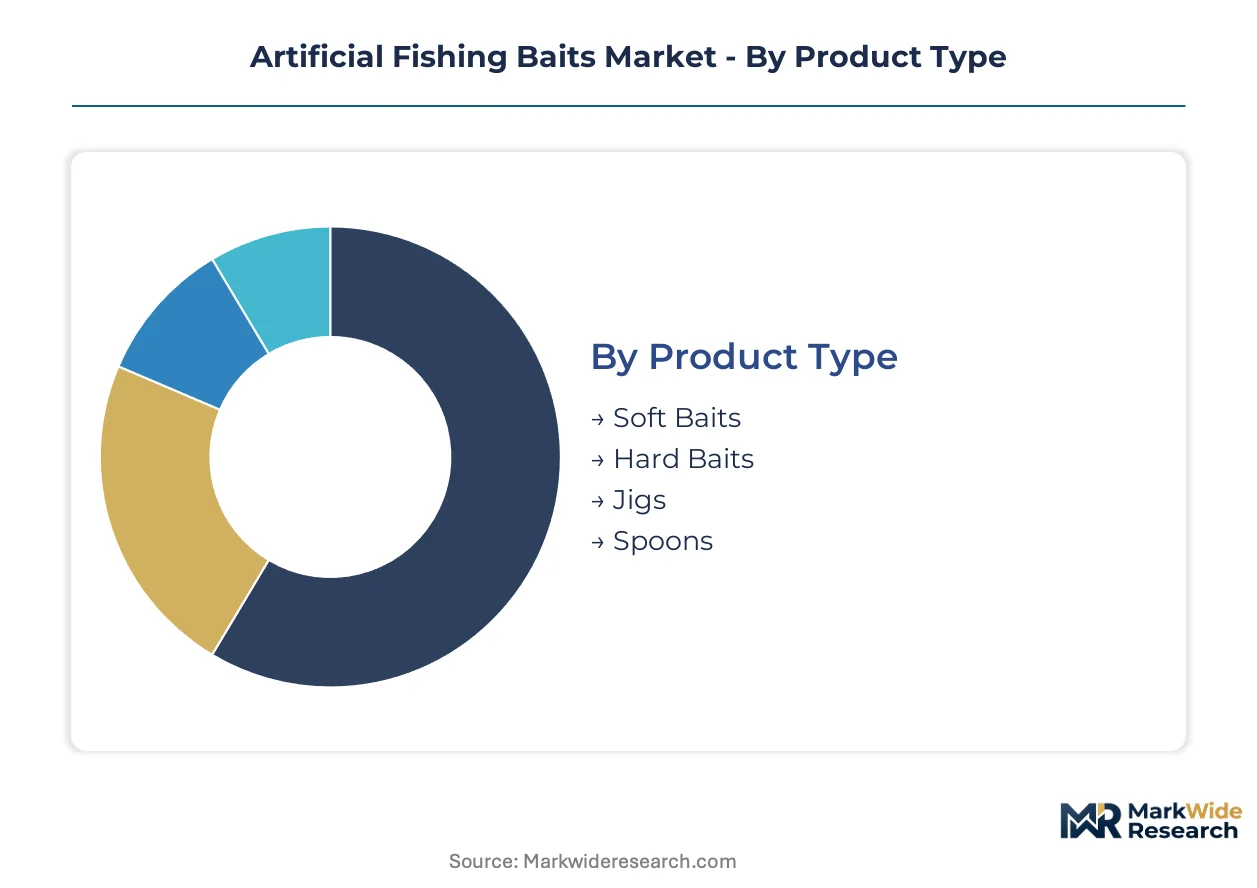
Segmentation in artificial fishing baits reveals how formulation chemistry, angler behavior, and hydrodynamic requirements fragment demand across distinct value pools. Manufacturers configure production lines differently for each slice, with material choices and molding tolerances determining margin capture.
Product Type:
Cost tier separates casual replacement purchases from precision-engineered tournament equipment where anglers pay multiples for consistent action.
- Soft Baits:Injection-molded thermoplastic elastomers and hand-poured biodegradable polymers deliver lifelike texture and scent dispersion. Recreational anglers in the Great Lakes basin are switching to corn-starch-derived formulations to avoid microplastic accumulation penalties under state environmental guidelines.
- Hard Baits:CNC-machined aluminum bodies and ABS shells house internal weight-transfer systems and rattle chambers. Bass tournament culture in Alabama and Texas sustains premium consumption where sub-millimeter tolerances command price premiums.
- Jigs:Lead or tungsten heads paired with silicone skirts target bottom-feeding species across freshwater and saltwater environments.
- Spoons:Stamped metal profiles with holographic finishes maintain stable demand in commercial fisheries where mechanical durability outweighs aesthetic refinement.
Hard baits hold installed capacity. Soft baits are rotating up the share rankings.
Material:
Application environment dictates material selection, with corrosion resistance and biodegradation rates filtering options for specific water chemistries.
- Plastic:PVC and TPE formulations dominate soft bait production, though REACH Annex XVII restrictions on phthalates are accelerating migration to bio-based thermoplastic polyurethane alternatives in EU-bound supply chains.
- Rubber:Natural and synthetic elastomers provide tear resistance for soft bait appendages and skirt materials.
- Foam:Buoyant closed-cell structures enable topwater presentations and fly fishing popper bodies where surface disturbance triggers strikes.
- Metal:Brass, stainless steel, and tungsten alloys concentrate in jig heads and spoon blanks where density and hardness resist predatory fish bite force.
Plastic maintains volume leadership. Metal is climbing the fastest in value-per-kilogram terms.
End User:
Customer type determines purchasing frequency, with recreational segments driving replacement cycles and commercial operators prioritizing unit durability.
- Recreational Anglers:Weekend and seasonal fishermen purchase soft baits in bulk for high-loss techniques like Texas-rigged worm fishing.
- Commercial Fishermen:Industrial-scale operations in Alaska and Louisiana deploy metal spoons and heavy jigs under mechanical stress where lure longevity reduces downtime.
- Sports Fishing Enthusiasts:Tournament competitors in Florida and California subscribe to curated monthly lure boxes matched to regional hatch patterns.
- Industrial Fisheries:Factory trawlers and processing vessels specify corrosion-resistant metal hardware for continuous operation in salt spray environments.
Recreational anglers hold installed capacity. Sports fishing enthusiasts are gaining share fastest.
Application:
Geography and climate filter demand, with water salinity and temperature ranges dictating lure action requirements and material stability.
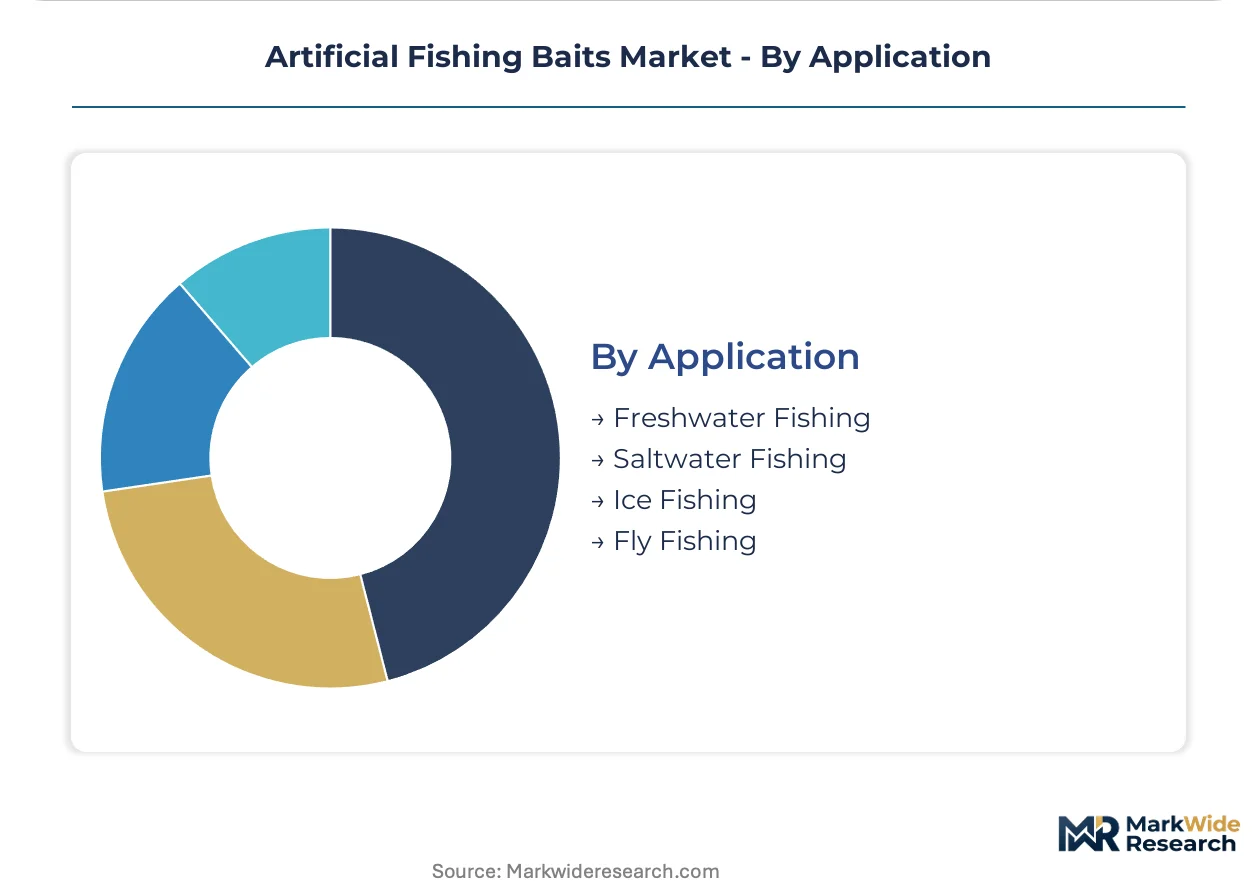
- Freshwater Fishing:Lakes and river systems in the Midwest and Southeast drive soft bait consumption where vegetation and structure cause frequent lure loss.
- Saltwater Fishing:Gulf of Mexico and Atlantic charter operators pilot smart lure connectivity with embedded accelerometers and Bluetooth strike detection.
- Ice Fishing:Compact jig profiles and glow-in-the-dark finishes target lethargic winter fish in Minnesota and Wisconsin lakes.
- Fly Fishing:Foam poppers and synthetic hair flies serve technical casters in Rocky Mountain trout streams where presentation delicacy matters.
Freshwater holds installed capacity. Saltwater is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA monitoring of phthalate content in plastic formulations anchors United States regulatory pressure, while EU REACH restrictions on persistent organic compounds reshape European material specifications and supply chain access.
United States
Bass tournament culture in Alabama and Texas sustains premium hard bait consumption where sub-millimeter tolerances command price premiums. California's Proposition 65 labeling requirements add compliance layers for brands distributing nationwide. Mold-making clusters in the American Midwest now serve artisanal bait makers selling direct-to-consumer through digital storefronts.
China
Production fragments across coastal manufacturing zones in Zhejiang province and inland mold-making clusters tracking naphtha and natural gas liquid indices. The country's national environmental regulator tightens oversight of chemical content in rubber and foam components. Pearl River Delta logistics disruptions strand downstream bait finishing operations for weeks when fluorescent dye and holographic flake supply chains stall.
Japan
Domestic distribution control and proprietary resin formulations anchor market position for precision-engineered lure manufacturers. METI standards influence regional adoption of environmental management certifications. Japanese toolmakers supply CNC-machined aluminum injection molds enabling sub-millimeter repeatability that hand-pour operations cannot match.
Germany
REACH Annex XVII restrictions on microplastics accelerate migration to bio-based thermoplastic polyurethane alternatives despite raw material cost premiums. ECHA guidance specifically targets synthetic polymer microparticles below five millimeters. German distributors now require batch-level compositional certificates before purchase order acceptance.
Finland
Design heritage combines with Asian contract manufacturing to sustain margin discipline across premium hard bait lines. EU environmental frameworks tighten material specifications across supply chains. Finnish engineering expertise concentrates in tournament-grade segments where precision tolerances differentiate product offerings.
Artificial Fishing Baits Market Competitive Landscape
Premium design houses and volume-scale manufacturers split the market across distinct value capture strategies. The vendor base concentrates around three strategic archetypes: heritage European design licensors, Japanese precision engineering specialists, and North American retail distribution platforms. Consolidation pressures intensify as regulatory compliance costs favor scaled players with dedicated certification resources. Geographic expansion and portfolio diversification represent the dominant competitive moves as companies seek to offset single-market regulatory risk.
Within the heritage design tier, Rapala VMC Corporation exemplifies European-origin positioning through Finnish engineering pedigree. Japanese precision specialists Shimano and Daiwa occupy positions emphasizing proprietary material science and domestic distribution control. These three anchors illustrate how regional regulatory specialization and manufacturing geography alignment create defensive positioning against REACH and EPA compliance fragmentation.
| Leading Market Players |
|---|
| Rapala VMC Corporation |
| Shimano |
| Daiwa |
| Pure Fishing Inc. |
| Berkley |
| Gamakatsu |
| Eagle Claw |
| Duel Co. Ltd. |
| Okuma |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province's thermoplastic elastomer molding capacity sets the baseline for downstream pricing power across artificial fishing bait tiers. When resin costs spike on naphtha index volatility, mold-makers lack pricing leverage in export contracts and absorb margin compression.
Pricing Analysis
Price spreads between Guangdong-produced economy soft baits and Japanese-engineered tournament hard baits exceed tenfold. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from REACH-compliant bio-based polymer cost premiums. Recreational weekend anglers show highest price sensitivity; bass tournament competitors demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentrates in Zhejiang province mold-making clusters and Guangdong finishing operations. Raw material dependencies center on naphtha-derived thermoplastic elastomers, Pearl River Delta fluorescent dyes, and Japanese CNC-machined aluminum injection tools. Single-source concentrate vulnerability in holographic flake supply creates structural risk. Distribution runs through North American big-box retail, European specialty dealers, and Asian direct-to-consumer digital storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU REACH compliance and California Proposition 65 certification creates defensive moats that favor scaled incumbents with dedicated compliance infrastructure.
For Market Incumbents: Pre-empt biodegradable formulation patent filings in aliphatic polyester chemistry before REACH Annex XVII tightens further. Consolidate master mold fabrication capacity by acquiring Taiwanese carving specialists facing generational succession gaps. Threat of artisanal microbatch competitors bypassing retail slotting fees demands channel control reinforcement. For New Entrants and Emerging Players: Direct-to-consumer microbatch channels in the American Midwest represent the most penetrable entry point for limited-run colorway differentiation. Bio-based soft bait white space in Florida and Louisiana subtropical fisheries addresses biodegradation rate mismatches. Instagram storefront go-to-market angles capture 40-60 point gross margin premiums absent big-box slotting fees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors smart lure connectivity platforms bundling hardware with catch-data subscription services. Long-term viability across the analysis window hinges on data-integrated offering scalability. Acquisition target archetype: connected hardware developers with Gulf of Mexico charter operator pilot relationships. Signal to watch: monthly box curation service subscriber retention rates as retail displacement indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Formulation Patent | REACH Annex XVII pre-compliance secures preferential EU retail shelf placement against late adopters. |
| Smart Lure Connectivity Platform | Bluetooth Low Energy strike detection enables subscription bundling with Gulf charter operators. |
| Direct-to-Consumer Digital Storefront | Instagram microbatch channels bypass big-box slotting fees and capture margin premiums. |
| Master Mold Fabrication Acquisition | Taiwanese carving specialist consolidation addresses generational skill scarcity in tournament-grade tooling. |
| California Proposition 65 Pre-Certification | Specialty retailer distribution unlock creates defensive moat against non-compliant competitors. |
Research Methodology
Initial hypotheses were tested against primary input from bait manufacturing plant managers, European sporting goods procurement leads, recreational angler community moderators, and Japanese lure house R&D directors and refined through secondary validation. Sources drew from customs and trade data, EPA enforcement actions, ECHA guidance documents, and SEC 10-K filings of publicly traded fishing equipment manufacturers. Bottom-up SKU-level volume estimates and top-down macroeconomic triangulation anchored forecast integrity.
Demand-supply-balance framing across the projection horizon modeled segmentation dimensions including product type, material chemistry, end-user archetype, and application environment. CAGRs were derived from iterative convergence of historical trajectory analysis and forward-looking regulatory scenario planning. Industry-specific forecast inputs incorporated REACH substance restriction timelines and Great Lakes basin microplastic accumulation penalty adoption curves.
Practitioners should monitor REACH Annex XVII amendment proposals, biodegradable polymer tensile strength breakthroughs, and smart lure connectivity pilot expansion rates for early signals of forecast revision triggers. Quarterly review of EU distributor batch-level certificate requirements and Florida angler lure disintegration complaint volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Europe Feed Amino Acids Market
Agricultural Commodities
Peat Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Alfalfa Powder Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
Roundwood Market