
 Europe Ruminant Feed Market | 2026-2036
Europe Ruminant Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ruminant Feed Market Foresight
Modular premix-to-complete-feed bundling is rebalancing buyer choice across European ruminant operations. Cargill Inc. leverages its integrated supply chain to anchor volume positions in northwestern dairy corridors. ForFarmers N.V. differentiates through regionally optimized formulations tailored to Dutch and Belgian herd profiles. Nutreco N.V. competes on R&D intensity, particularly in methane-inhibiting additive portfolios.
Europe ruminant feed encompasses formulated nutritional products designed for cattle, sheep, and goat digestion systems, typically comprising 12-18% crude protein in dairy concentrates and fiber-rich roughages processed through pelleting or total mixed ration blending to optimize rumen fermentation and milk yield. Concentrates and roughages together occupy the core volume positions, with concentrates capturing margin pools where protein optimization and energy density justify premium positioning. Additives represent the fastest-expanding segment as methane-reducing compounds and precision mineral premixes gain traction under sustainability-linked procurement protocols. Dairy farms constitute the dominant end-user channel, though beef feedlot consolidation in Eastern Europe is shifting volume concentration.
The EU Green Deal and Farm to Fork Strategy, enforced through EFSA feed additive authorizations and national-level environmental permits, are reshaping product formulation standards and market access conditions across member states. REACH compliance for novel feed ingredients adds a secondary gatekeeping layer that favors established suppliers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving methane-reduction mandates and carbon-accounting requirements that will determine which formulation portfolios retain commercial viability.
Market Dynamics
The EU Green Deal's methane-reduction mandates are compressing formulation timelines across northwestern European dairy corridors, forcing compound feed suppliers to requalify additive portfolios under tightened EFSA authorizations.
Growth Catalysts
- EFSA Feed Additive Pathway:Accelerated approvals for 3-nitrooxypropanol and other methane inhibitors are opening premium formulation tiers for suppliers with dedicated regulatory affairs capabilities.
- Dairy Cluster Consolidation:Herd expansion across Friesland and Lower Saxony is concentrating procurement volumes, enabling long-term supply contracts with embedded sustainability clauses.
- Precision Nutrition Hardware:Automated TMR mixing systems with real-time dry matter sensors are driving demand for customized concentrate blends calibrated to individual farm forage profiles.
Market Restraints
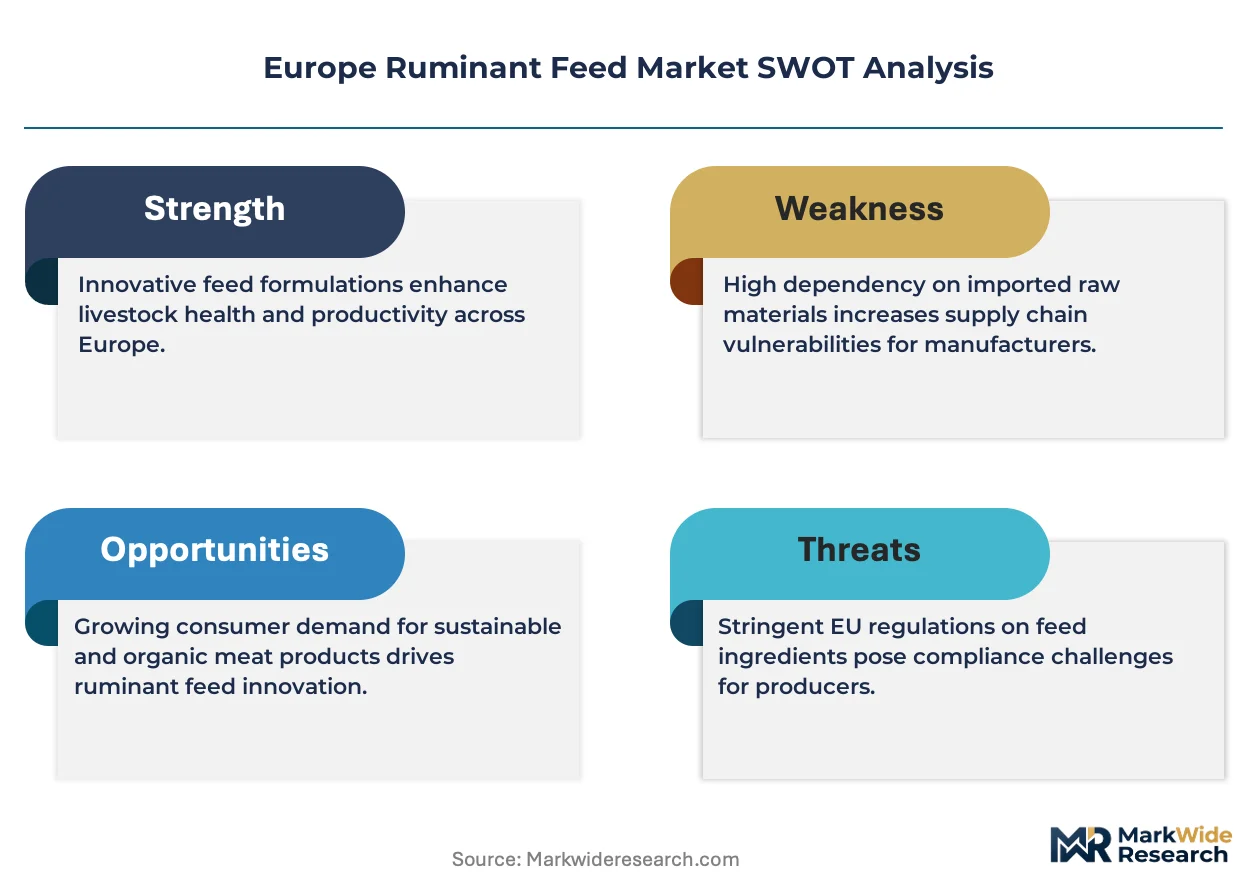
- Soybean Meal Price Volatility:Dependence on South American and Black Sea protein sources exposes margin pools to currency and climate-driven input cost swings.
- Phosphate Rock Supply Concentration:Moroccan and Russian dominance in phosphorus feedstock creates geopolitical concentration risk for mineral premix formulations.
- REACH Novel Ingredient Barriers:Registration timelines and toxicity data requirements for algae-derived proteins and insect meals delay commercialization by 18-36 months.
Strategic Opportunities
- Polish Beef Feedlot Modernization:Eastern European cattle finishing operations present underpenetrated demand for high-energy concentrates and beta-agonist-free formulations.
- Carbon-Accounting Integration:EU Green Deal farm-level emissions reporting requirements create service revenue streams for feed suppliers offering verified footprint data.
- Digital-Physical Convergence:Near-infrared spectroscopy combined with cloud-based ration optimization platforms enables outcome-based pricing tied to milk yield improvements.
Industry Challenges
- Rumen Microbiome Specialist Scarcity:Formulation teams lack sufficient expertise in methanogen inhibition mechanisms and host-microbe interaction modeling.
- Multi-Site Certification Complexity:FSSC 22000, GMP+, and national environmental permits create overlapping audit burdens for suppliers serving cross-border dairy cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ruminant Feed Market |
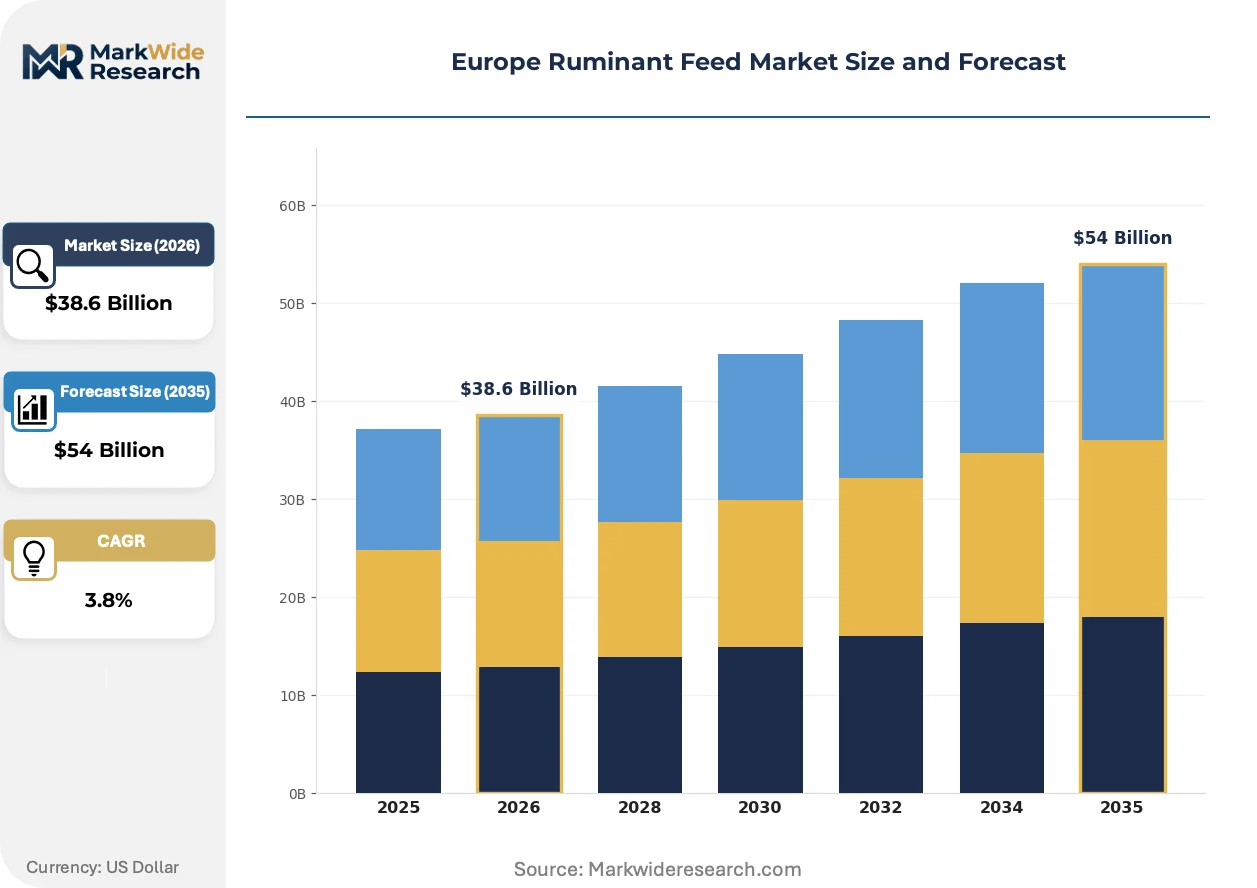
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Roughages, Supplements, Additives End User: Dairy Farms, Beef Farms, Feedlots, Commercial Producers Distribution Channel: Direct Sales, Online Sales, Retail Stores, Wholesalers Packaging Type: Bags, Bulk, Totes, Containers |
| Companies Covered | Nutreco N.V., ForFarmers N.V., Cargill Inc., Alltech Inc., Archer Daniels Midland, De Heus Beheer B.V., Royal Agrifirm Group, DLG Group, Avril Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ruminant Feed Market Shifts & Advancements
Formulation science and data infrastructure are converging to restructure how nutritional value is delivered, measured, and priced across European ruminant operations.
Microencapsulated butyrate and essential oil blends are expanding into high-performing dairy herds as rumen modulators that improve fiber digestibility while suppressing enteric methane output. Dutch and Danish cooperatives with 500-plus cow operations are piloting these additives at scale, creating tiered product lines that separate premium sustainability-certified feeds from standard concentrates.
EFSA's 2023 updated guidance on environmental risk assessment for feed additives is extending authorization timelines for novel compounds, particularly those derived from genetically modified microorganisms. Suppliers are responding by front-loading toxicology studies and establishing dedicated regulatory submission teams, with methane-reduction candidates receiving priority resource allocation.
Large dairy processors are consolidating feed procurement through cooperative buying platforms that aggregate volume across member farms and negotiate direct supply agreements. This disintermediation compresses distributor margins in the Netherlands and Germany while favoring compounders with integrated logistics networks capable of just-in-time delivery to multiple farm sites.
Europe Ruminant Feed Market Segmentation
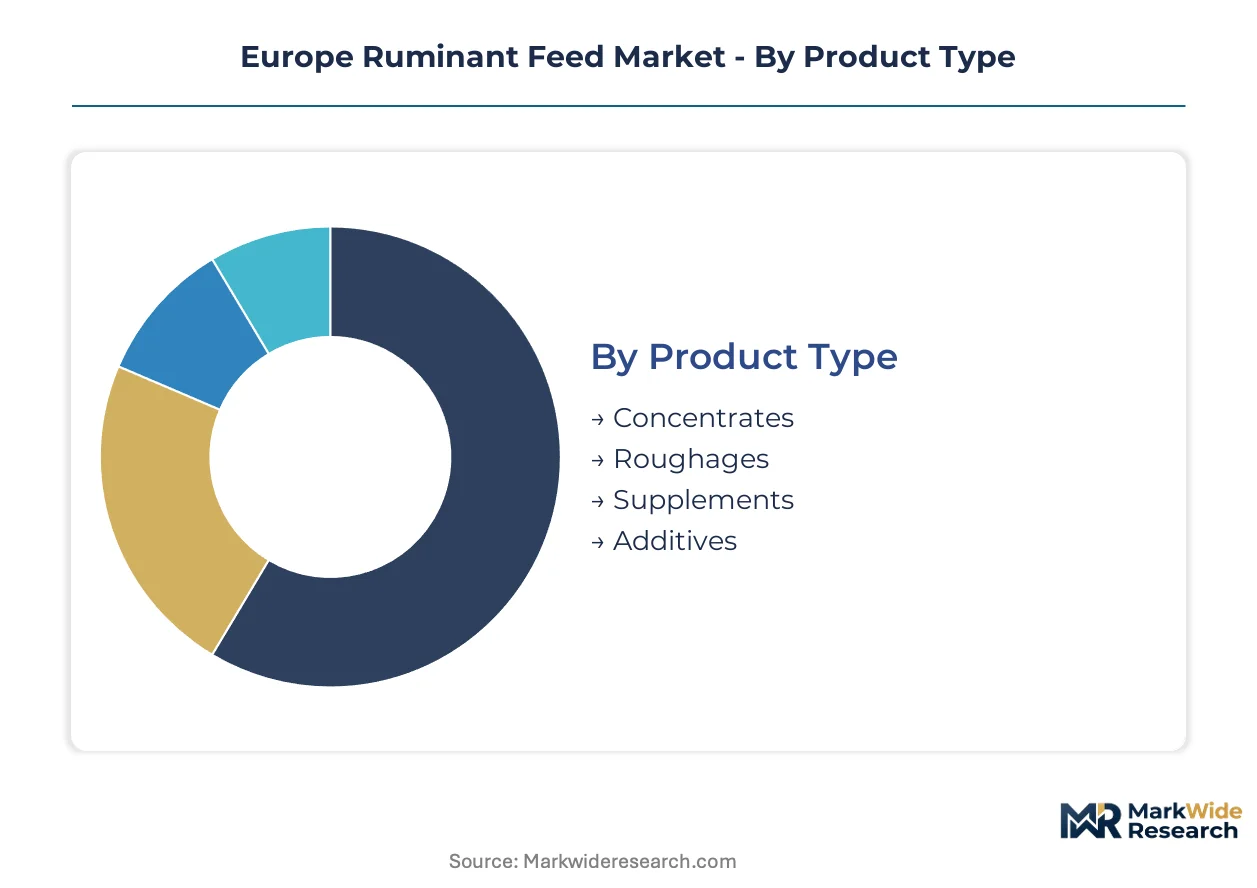
European ruminant feed procurement splits across four decision dimensions: product formulation complexity, end-use herd economics, channel efficiency, and logistics configuration. Buyers in northwestern dairy corridors weight these factors differently than Eastern European beef operators, creating distinct segment priorities within each category.
Product Type:
Formulation intensity and margin capture drive buyer selection, with energy density and protein optimization commanding premium positioning in high-output herds.
- Concentrates:Energy-dense formulations containing 18-24% crude protein, typically pelleted or meal-based, optimize milk yield in high-performing Holstein herds across Friesland and Lower Saxony. Dairy cooperatives in the Netherlands negotiate long-term concentrate contracts with embedded methane-reduction additive tiers.
- Additives:Microencapsulated butyrate, essential oil blends, and 3-nitrooxypropanol-based methane inhibitors represent the steepest expansion trajectory as EFSA accelerates environmental risk assessments. Dutch and Danish operations with 500-plus cow herds pilot these at scale, separating sustainability-certified feed lines from standard concentrates.
- Roughages:Fiber-rich forages including silage, hay, and straw processed through TMR blending systems support rumen fermentation baseline requirements.
- Supplements:Mineral premixes and vitamin complexes address specific herd deficiencies, with phosphate-dependent formulations exposed to Moroccan supply concentration.
Concentrates lead on scale; additives lead on momentum.
End User:
Herd scale and procurement sophistication determine feed specification complexity, with large operations driving customized formulation demand.
- Dairy Farms:High-output operations across Germany, France, and the Netherlands demand precision nutrition calibrated to individual forage profiles through automated TMR systems. These buyers concentrate procurement volumes through cooperative platforms that negotiate direct supply agreements, compressing distributor margins.
- Feedlots:Eastern European cattle finishing operations in Poland present underpenetrated demand for high-energy concentrates and beta-agonist-free formulations as beef feedlot consolidation accelerates.
- Beef Farms:Suckler cow and calf-to-weanling operations prioritize cost-optimized roughage-based rations with minimal concentrate supplementation.
- Commercial Producers:Integrated agribusinesses with captive herd operations and feed manufacturing capabilities source base ingredients for in-house formulation.
Dairy farms dominate procurement volume; feedlots present the steepest growth opportunity.
Distribution Channel:
Logistics reliability and technical service access shape channel preference, with large herds disintermediating traditional distributors.
- Direct Sales:Compounders with integrated logistics networks deliver just-in-time to multiple farm sites, bypassing distributors as dairy processors consolidate procurement through cooperative buying platforms in the Netherlands and Germany.
- Wholesalers:Regional distributors serve fragmented mid-scale operations with limited storage infrastructure and irregular order patterns.
- Retail Stores:Agricultural supply outlets cater to smallholder herds with bagged product and basic nutritional advisory.
- Online Sales:Digital procurement platforms emerge for standardized supplement reorders, though bulk feed remains logistics-constrained for e-commerce.
Direct sales capture volume concentration; online sales expand most quickly in supplement categories.
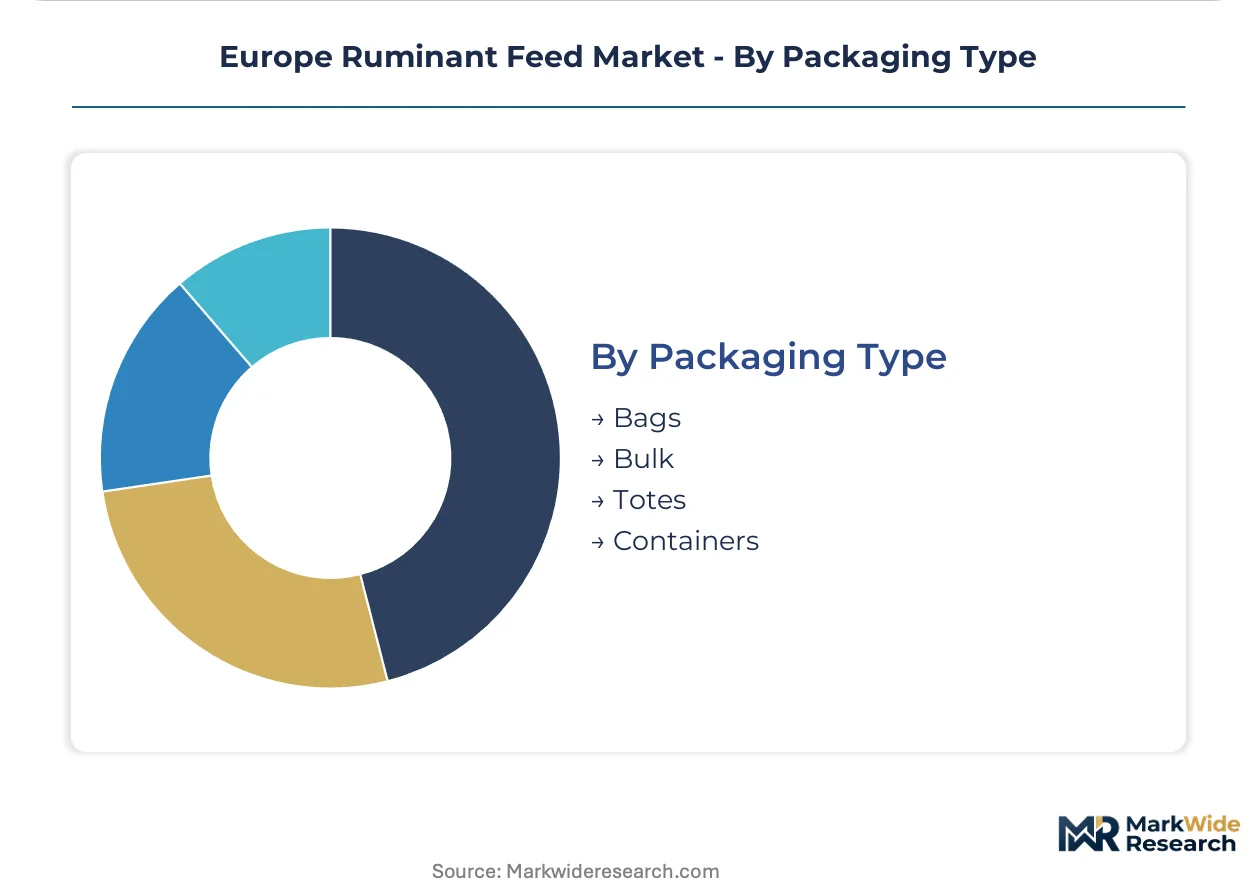
Packaging Type:
Storage infrastructure and handling economics determine format selection, with scale dictating bulk adoption.
- Bulk:Unpackaged delivery via pneumatic or auger systems minimizes unit costs for operations with on-farm silo capacity, standard across northwestern dairy clusters with 200-plus cow herds.
- Bags:25-50kg woven polypropylene sacks serve small-to-mid scale operations lacking bulk handling equipment, prevalent in Eastern European beef farms and mountainous regions.
- Totes:Intermediate bulk containers bridge bulk and bagged formats for mid-scale operations with limited silo investment.
- Containers:Specialized liquid additive totes and mineral supplement bins support precision dosing systems in high-technology dairies.
Bulk leads on scale; totes gain share fastest as mid-scale operations upgrade handling infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial compound feed production for European ruminants traces its modern lineage to post-war cooperative consolidation across the Low Countries and northern Germany, where dairy specialization first created demand for scientifically formulated concentrates.
Germany
Lower Saxony's dense dairy corridors drive concentrate procurement volumes as herd sizes expand beyond 300 cows per operation. The EU Green Deal's Farm to Fork Strategy mandates 50% pesticide reduction targets that reshape crop rotation planning for homegrown forage. FrieslandCampina's German procurement hubs around Oldenburg and Münster negotiate direct supply contracts with compounders embedding methane-reduction additive tiers.
Netherlands
Automated TMR systems with real-time dry matter sensors proliferate across Gelderland and Friesland, creating demand for customized concentrate blends calibrated to individual farm forage profiles. EFSA's accelerated feed additive authorizations for 3-nitrooxypropanol open premium formulation tiers for suppliers with dedicated regulatory affairs capabilities. Royal FrieslandCampina's cooperative buying platforms aggregate volume across member farms, compressing traditional distributor margins.
France
Western dairy basins in Brittany and Normandy concentrate Holstein herd expansion, with operations above 500 cows driving precision nutrition adoption. The national Low-Carbon Label certification program creates procurement preference for feed suppliers offering verified carbon footprint data. Lactalis's vertical integration into feed sourcing around Laval and Saint-Malo reshapes supplier relationships toward long-term partnership models.
Belgium
Flemish dairy operations cluster around Mechelen and Leuven, where phosphate emission regulations under the EU Nitrates Directive constrain mineral premix formulations. The regional Manure Action Plan imposes strict nitrogen application limits that intensify demand for optimized protein efficiency in compound feeds. Arla Foods' Belgian procurement cooperatives prioritize suppliers with integrated logistics networks capable of just-in-time multi-site delivery.
Poland
Eastern European beef feedlot consolidation accelerates across Masovia and Greater Poland, generating underpenetrated demand for high-energy concentrates and beta-agonist-free finishing formulations. National environmental permit procedures under EU Industrial Emissions Directive implementation create compliance complexity for new facility construction. Danish and Dutch compounders establish distribution partnerships around Warsaw and Poznań to capture volume concentration in the region's fastest-expanding cattle finishing segment.
Europe Ruminant Feed Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory certification depth, with methane-reducing additive portfolios commanding the steepest price premiums. The vendor base clusters into three tiers: integrated multinationals with captive ingredient sourcing, regional compounders with cooperative-anchored distribution, and specialty additive houses with EFSA submission expertise. Dominant competitive moves include backward integration into protein ingredient processing and strategic partnerships with precision nutrition hardware providers.
Among Netherlands-based integrated nutrition groups, Nutreco N.V., ForFarmers N.V., and De Heus Beheer B.V. exemplify the regional compounder archetype with cooperative-anchored distribution networks. These entities occupy positions where EFSA regulatory affairs capabilities and just-in-time logistics infrastructure determine contract access. Cargill Inc. represents the multinational integrated model with volume positions in northwestern dairy corridors, while Royal Agrifirm Group anchors cooperative-backed procurement consolidation in the Dutch-German border region.
| Leading Market Players |
|---|
| Nutreco N.V. |
| ForFarmers N.V. |
| Cargill Inc. |
| Alltech Inc. |
| Archer Daniels Midland |
| De Heus Beheer B.V. |
| Royal Agrifirm Group |
| DLG Group |
| Avril Group |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EFSA-authorized methane-reducing formulations and standard concentrates manifests in both margin capture and procurement channel structure across northwestern European dairy corridors. Premium-tier suppliers command embedded sustainability clauses in direct supply contracts while commodity compounders face compressed distributor margins through cooperative buying platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by EFSA certification status and methane-reduction performance claims. Price differentiation rests on EFSA additive authorization tiers and embedded carbon-accounting verification, with premium formulations capturing sustained margin pools. Cost compression in standard concentrates intensifies as cooperative procurement platforms aggregate volume and squeeze compounder margins. Small-to-mid scale Eastern European beef operations exhibit highest price sensitivity, while Dutch and German dairy cooperatives above 500 cows prioritize performance guarantees over unit cost.
Supply Chain Analysis
Soybean meal supply rests on Brazilian and Argentine crushing capacity, with Black Sea origins gaining intermittent share during favorable trade windows. Phosphate rock dependency centers on Moroccan and Russian export concentration, while amino acid production draws from Chinese fermentation capacity. Single-source vulnerability in phosphorus feedstock creates formulation risk for mineral premix suppliers. Distribution runs through integrated compounder logistics networks delivering just-in-time to multi-site dairy operations, bypassing traditional wholesale channels in volume-concentrated corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA methane-reduction additive authorizations determine portfolio viability and pricing power across the European dairy supply base.
For Market Incumbents: Deploy regulatory affairs capacity as the primary defensive lever. Front-load toxicology studies for 3-nitrooxypropanol derivatives ahead of EFSA environmental risk assessment updates to secure authorization moats. Establish captive supply partnerships with Moroccan phosphate processors to offset geopolitical concentration risk in mineral premix formulations. For New Entrants and Emerging Players: The price-point gap between EFSA-certified methane-reducing concentrates and economy-grade standard feeds opens viable entry corridors. Polish beef feedlot modernization presents the most penetrable demand pool, with beta-agonist-free high-energy concentrates underserved by established northwestern dairy-focused compounders. Pursue distribution partnerships with Eastern European agricultural cooperatives as the anchor go-to-market mechanism. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty additive houses possessing dedicated EFSA submission teams and methanogen inhibition R&D pipelines. Long-term viability favors entities with regulatory-first capabilities over volume-scale commodity compounders. Watch EFSA authorization timelines for novel microbiome-modulating compounds as the inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Regulatory Submission Acceleration | Priority resource allocation for methane-inhibiting additive candidates compresses competitor entry windows. |
| Backward Integration into Phosphate Processing | Captive supply of Moroccan phosphate rock mitigates geopolitical concentration risk in mineral premix formulations. |
| Precision Nutrition Hardware Partnership | Integration with automated TMR mixing systems locks in customized concentrate blend demand. |
| Carbon-Accounting Service Layer Addition | Verified footprint data offerings capture EU Green Deal farm-level emissions reporting revenue streams. |
| Eastern European Distribution Partnership | Local alliances around Warsaw and Poznań capture Polish beef feedlot consolidation volume. |
Research Methodology
Direct dialogue with compound feed procurement managers, dairy cooperative technical directors, EFSA regulatory affairs specialists, and precision nutrition hardware engineers grounded the qualitative foundation. Secondary validation drew from EU feed production statistics, EFSA feed additive authorization registers, national environmental permit databases, and customs trade flow records. Bottom-up farm-level demand modeling and top-down compounder production capacity estimates were triangulated to constrain forecast variance.
Segment-level value outputs across product type, end user, distribution channel, and packaging format dimensions were generated through the analytical framework. CAGRs were derived from regression-adjusted trend extrapolation incorporating herd size expansion trajectories and EFSA authorization pipeline velocity. Feed conversion ratio improvements and methane-reduction mandate compliance cost curves served as industry-specific forecast inputs throughout the projection horizon.
Caveats apply where EFSA regulatory timeline delays, South American soybean harvest disruptions, or phosphate export restrictions could materially shift the outlook. Forecasts embed assumptions regarding continued EU Green Deal enforcement intensity and cooperative procurement platform consolidation trajectories. A small set of regulatory authorization triggers and input cost volatility signals warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
Straw Market
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Artificial Fishing Baits Market