
 Asia-Pacific Ruminant Feed Premix Market | 2026-2036
Asia-Pacific Ruminant Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ruminant Feed Premix Market Outlook
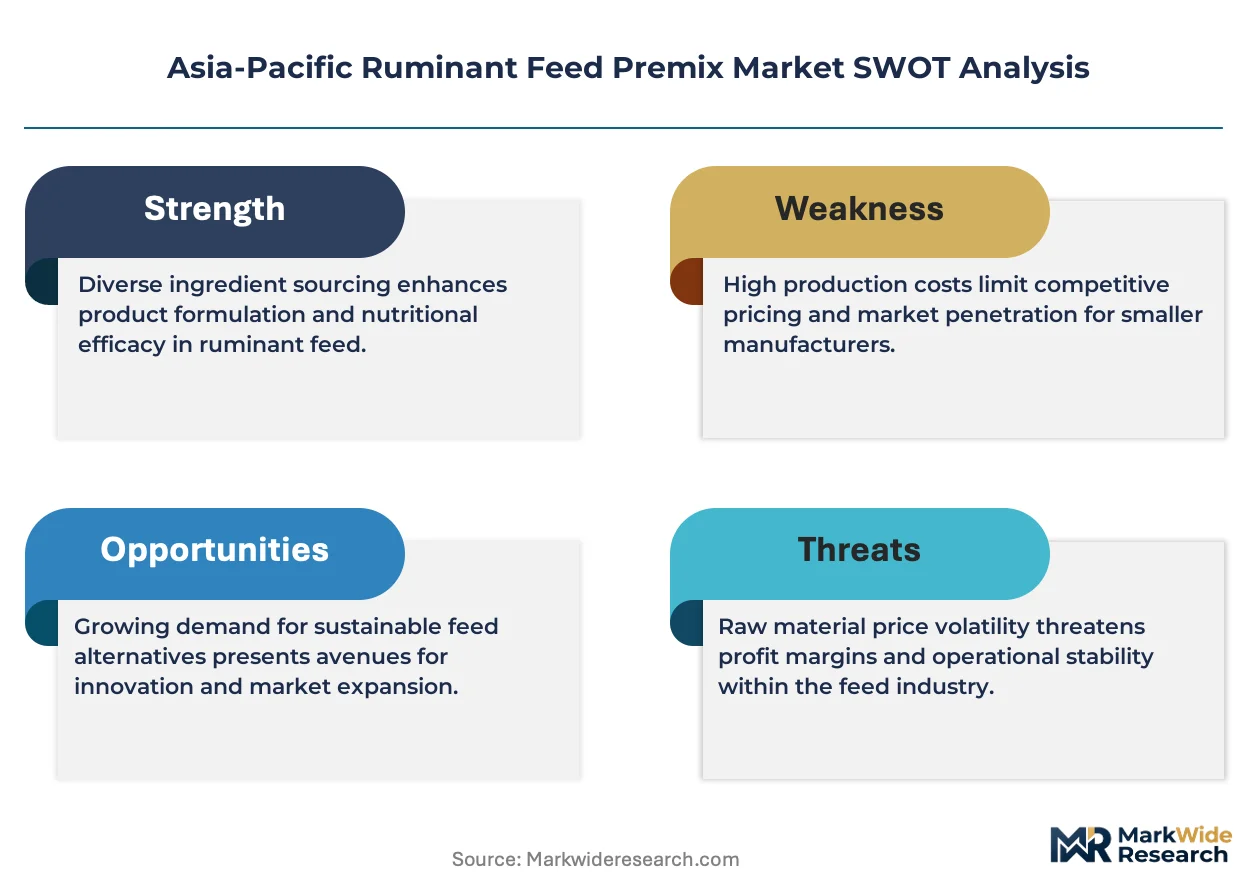
Australia's feed additive manufacturing base is narrowing as domestic compounders consolidate blending capacity around export-grade mineral premix output. Cargill Incorporated leverages its Queensland distribution network to supply cattle stations across the eastern seaboard. BASF SE anchors vitamin premix supply through technical partnerships with Southeast Asian feed mills. Godrej Agrovet Ltd dominates India's western dairy corridors with captive distribution into Maharashtra cooperative channels.
Asia-Pacific ruminant feed premix comprises micro-ingredient blends containing vitamins, minerals, amino acids, and functional additives dosed at 0.5–3.0% of total ration mass, manufactured via precision batching and cold-pelleting to preserve thermolabile compounds. These formulations correct nutritional deficiencies in forage-dependent herds across tropical and temperate grazing systems. Mineral premix holds the largest volume share where calcium-phosphorus balancing drives repeat procurement in high-yielding dairy operations. Additive premix, encompassing yeast cultures and organic trace minerals, captures expanding margin pools as Vietnamese and Indonesian feed manufacturers reformulate for antibiotic-free cattle finishing protocols.
China's SAMR enforces GB 13078 feed hygiene standards that mandate heavy metal limits and mycotoxin screening for imported premix constituents, raising compliance costs for regional suppliers. India's FSSAI and BIS jointly oversee feed-grade vitamin potency labeling, while Australia's APVMA regulates veterinary chemical residues in premix formulations destined for export-certified beef herds. Stakeholders must track evolving MEE environmental audits on Chinese premix plants and India's emerging carbon-footprint disclosure rules for livestock input supply chains.
Market Dynamics
Dairy cooperatives across India and Vietnam are consolidating premix procurement into multi-year supply agreements, compressing spot-market liquidity and favoring compounders with captive vitamin synthesis and cold-chain distribution networks.
Growth Catalysts
- India's PLI scheme for animal husbandry inputs:Production-linked incentives for feed-grade vitamin manufacturing are drawing domestic chemical firms into backward integration, expanding regional supply capacity.
- Antibiotic-free cattle finishing mandates:Vietnamese and Indonesian feed manufacturers are reformulating rations with organic trace minerals and yeast cultures to meet export protocol requirements.
- Organized dairy cluster formation:Bulk premix offtake is accelerating in Gujarat and Maharashtra where cooperative federations standardize nutritional protocols across member farms.
Market Restraints
- GB 13078 feed hygiene standards:China's SAMR mandates heavy metal limits and mycotoxin screening that raise compliance costs for regional premix importers.
- Vitamin A and E price volatility:Feed-grade vitamin concentrate markets swing with petrochemical feedstock costs, squeezing blender margins on fixed-price contracts.
- Single-source mineral dependency:High-purity selenium and cobalt premix constituents concentrate in limited processing jurisdictions, creating supply vulnerability.
Strategic Opportunities
- Indonesia's emerging dairy belt:Java-based cooperative expansion offers first-mover positioning for mineral premix suppliers establishing technical service presence.
- Carbon-footprint disclosure rules:India's emerging livestock input supply chain regulations will advantage premix compounders with verified Scope 3 emissions tracking.
- Precision livestock integration:Convergence of rumen bolus sensors with dynamic ration formulation software enables real-time premix dosing adjustments.
Industry Challenges
- Thermolabile compound stability:Vitamin premix formulators face shelf-life degradation in tropical storage conditions without continuous cold-chain integrity.
- Multi-jurisdiction label compliance:Exporters must reconcile India's BIS potency standards, Australia's APVMA residue limits, and China's GB additive lists for cross-border premix shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ruminant Feed Premix Market |
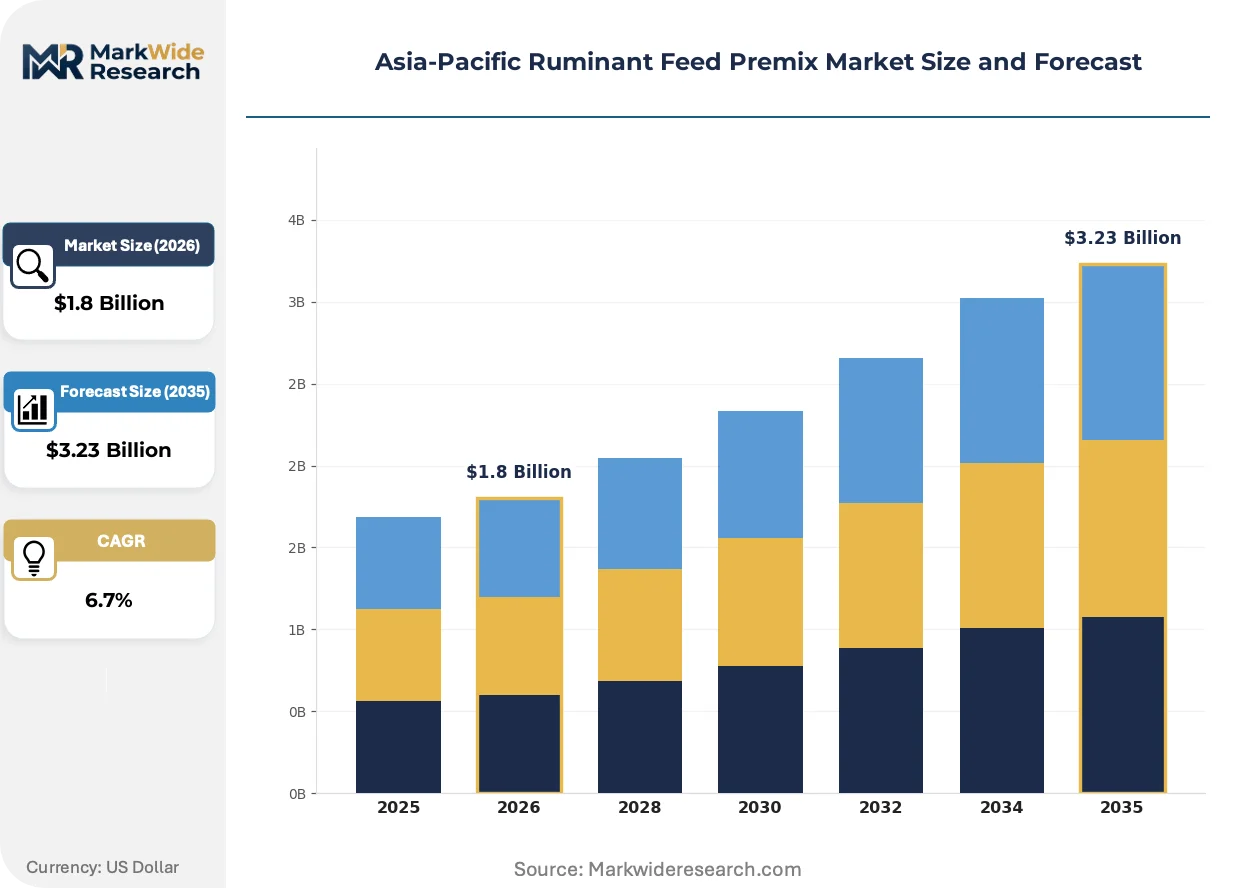
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Premix, Vitamin Premix, Protein Premix, Additive Premix Distribution Channel: Online Retail, Specialty Stores, Agricultural Cooperatives, Direct Sales Animal Type: Cattle, Sheep, Goats, Bison End User: Farmers, Feed Manufacturers, Veterinary Clinics, Livestock Producers |
| Companies Covered | BASF SE, Godrej Agrovet Ltd, Cargill Incorporated, Lallemand Inc, Nutreco NV, ADM Animal Nutrition, Land O Lakes, Amul Cattle Feed, DSM NV, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ruminant Feed Premix Market Strategic Shifts
Digital ration formulation platforms are virtualizing traditional nutritionist-consultant relationships, while regulatory tightening on feed hygiene and antibiotic residues forces continuous reformulation cycles across Southeast Asian compounders.
Encapsulated fat-soluble vitamin technologies are virtualizing conventional spray-dried premix formats by enabling higher loading densities and extended tropical stability. Australian feed mills serving export-certified beef herds are adopting these micro-encapsulated formats fastest, replacing standard vitamin A and D3 premixes. This shift is virtualizing the economics of long-distance premix distribution by reducing refrigeration intensity and extending effective shelf life.
China's MEE environmental audits on premix manufacturing facilities are tightening wastewater and particulate emission controls, forcing plant upgrades or closures among smaller regional compounders. Facilities in Shandong and Hebei provinces face the steepest compliance timelines. Mineral premix exporters to China must now document environmental management system certification to maintain import eligibility.
Dairy cooperatives in Maharashtra and Karnataka are consolidating premix procurement through centralized tender platforms, displacing fragmented distributor relationships with direct manufacturer contracts. This channel compression rewards compounders with technical service teams capable of on-farm ration auditing. The procurement model change is most visible in India's western dairy corridors where cooperative federations now specify premix composition rather than accepting standard formulations.
Asia-Pacific Ruminant Feed Premix Market Segmentation
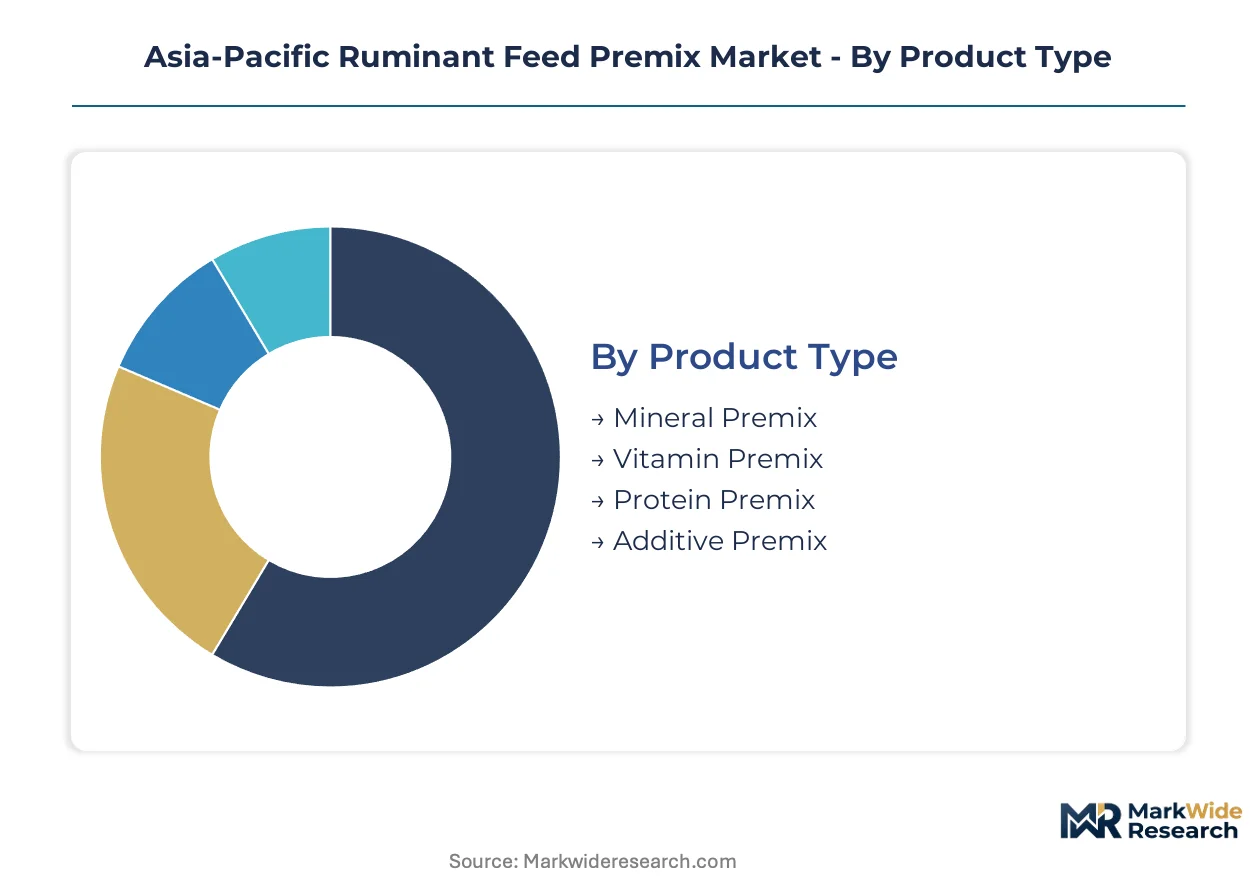
Segmentation in the Asia-Pacific ruminant feed premix market reveals how procurement patterns diverge across dairy cooperatives, export-certified beef operations, and smallholder systems. Each dimension exposes distinct technical requirements, from cold-chain vitamin stability to mineral balancing for high-yielding Holstein herds.
Product Type:
Use-case spectrum spans basic nutritional correction through functional performance enhancement, with cost sensitivity and technical sophistication determining blend selection.
- Mineral Premix:Calcium-phosphorus balancing formulations dominate high-volume procurement by organized dairy clusters in Gujarat and Maharashtra. Cooperative federations specify custom mineral ratios rather than accepting standard blends, compressing spot-market liquidity for generic products.
- Vitamin Premix:Thermolabile compound formulations require continuous cold-chain integrity through tropical distribution networks. BASF SE anchors regional supply through technical partnerships with Southeast Asian feed mills, though price volatility in feed-grade vitamin A and E concentrates squeezes blender margins.
- Protein Premix:Rumen-degradable protein supplements address forage quality deficiencies across Indonesian and Vietnamese smallholder systems.
- Additive Premix:Yeast cultures and organic trace minerals enable antibiotic-free cattle finishing protocols for export-certified operations.
The dominant share belongs to Mineral Premix, while Additive Premix is closing the gap fastest.
Distribution Channel:
Channel economics reflect customer scale and technical service intensity, with bulk procurement consolidating toward direct manufacturer relationships.
- Direct Sales:Multi-year supply agreements between compounders and dairy cooperatives displace fragmented distributor networks. Godrej Agrovet Ltd leverages captive distribution into Maharashtra cooperative channels, while Cargill Incorporated supplies cattle stations across Australia's eastern seaboard through Queensland-based technical teams.
- Agricultural Cooperatives:Centralized tender platforms in Karnataka and Maharashtra displace traditional distributor relationships, rewarding manufacturers with on-farm ration auditing capabilities.
- Specialty Stores:Regional distributors serve smallholder segments with standard formulations and limited technical support.
- Online Retail:Digital platforms virtualize procurement for remote cattle stations and emerging dairy belts with limited physical distribution access.
Direct Sales commands the largest volume flow, though Agricultural Cooperatives are expanding procurement share fastest.
Animal Type:
Species-specific nutritional protocols create distinct premix specification requirements across dairy, beef, and fiber production systems.
- Cattle:Dairy and beef operations drive bulk mineral premix offtake, with high-yielding Holstein herds in India's organized clusters requiring precise calcium-phosphorus balancing. Australia's export-certified beef stations specify premix formulations meeting APVMA residue limits for international market access.
- Sheep:Selenium-responsive conditions in New Zealand-influenced Australian grazing systems drive targeted mineral supplementation.
- Goats:Smallholder dairy goat operations in Indonesia and Vietnam utilize standard mineral premix adapted from cattle formulations.
- Bison:Niche protein production in specialized Australian and New Zealand operations requires limited premix volume.
Cattle represents the dominant consumption base, while specialized sheep premix formulations are gaining technical sophistication fastest.
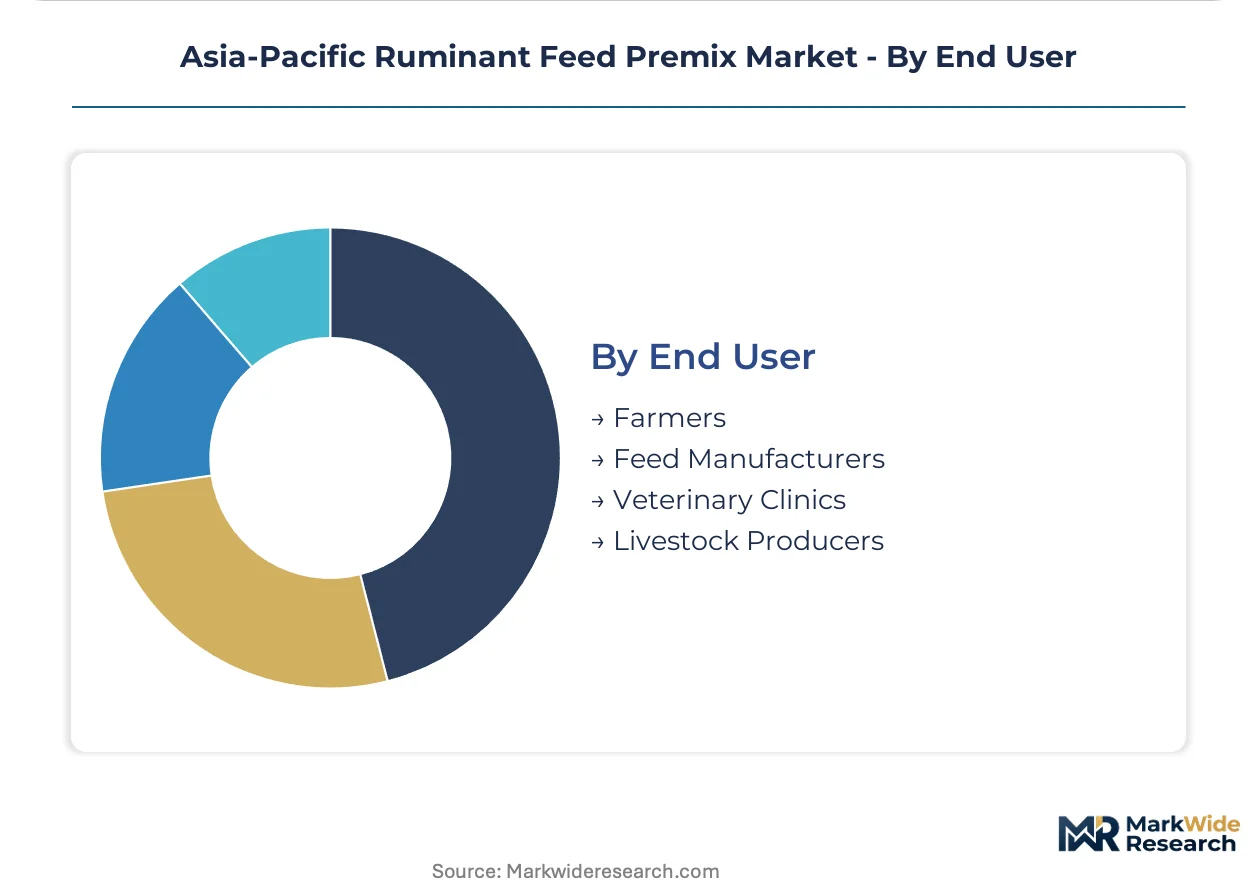
End User:
Customer technical capability and procurement scale determine premix specification complexity and service intensity requirements.
- Feed Manufacturers:Vietnamese and Indonesian compounders reformulate rations for antibiotic-free protocols, sourcing organic trace minerals and yeast cultures through technical partnerships. China's SAMR-enforced GB 13078 standards mandate heavy metal limits and mycotoxin screening, raising compliance costs for premix constituents.
- Livestock Producers:Organized dairy clusters in India's western corridors standardize nutritional protocols across member farms, consolidating premix procurement into cooperative-level tenders.
- Farmers:Smallholder segments in Indonesia's emerging Java-based dairy belt rely on distributor networks with limited technical service.
- Veterinary Clinics:Specialized therapeutic premix dispensing addresses metabolic disorders in high-value breeding stock.
Feed Manufacturers hold the largest procurement volume, though Livestock Producers are consolidating purchasing power fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors regulatory stringency across the Asia-Pacific ruminant feed premix landscape through GB 13078 feed hygiene standards. National regulators in India, Australia, Vietnam, and Indonesia enforce divergent compliance frameworks that reshape procurement patterns and manufacturing investment across the region.
China
Shandong and Hebei provinces concentrate mineral premix manufacturing capacity where MEE environmental audits force wastewater and particulate emission upgrades. GB 13078 mandates heavy metal limits and mycotoxin screening for imported constituents, raising compliance costs for regional suppliers. Facilities lacking environmental management system certification face import eligibility revocation.
India
Gujarat and Maharashtra dairy belts drive bulk mineral premix offtake as cooperative federations standardize nutritional protocols across member farms. The PLI scheme for animal husbandry inputs draws domestic chemical firms into backward integration for feed-grade vitamin manufacturing. BIS and FSSAI jointly oversee feed-grade vitamin potency labeling with tightening enforcement.
Australia
Queensland's cattle stations across the eastern seaboard specify premix formulations meeting APVMA residue limits for export-certified beef herds. Domestic compounders consolidate blending capacity around export-grade mineral premix output as the manufacturing base narrows. New South Wales and Victoria feed mills adopt micro-encapsulated vitamin formats fastest for tropical stability.
Vietnam
Feed manufacturers in the Red River Delta reformulate rations with organic trace minerals and yeast cultures to meet antibiotic-free cattle finishing protocols for export markets. SAMR-equivalent national standards on feed hygiene drive continuous reformulation cycles among compounders. Ho Chi Minh City-based distributors serve emerging dairy cooperatives consolidating procurement into multi-year supply agreements.
Indonesia
Java-based cooperative expansion offers positioning for mineral premix suppliers establishing technical service presence in the emerging dairy belt. Smallholder segments rely on distributor networks with limited technical support while organized clusters standardize procurement. National regulators enforce evolving feed additive registration requirements that compress spot-market liquidity for generic products.
Asia-Pacific Ruminant Feed Premix Market Competitive Environment
Capability concentration sits with integrated chemical manufacturers possessing captive vitamin synthesis; scale advantage sits with diversified agribusiness conglomerates with established distribution infrastructure. The market structures around three tiers: global nutrition majors with technical partnerships, regional compounders with cooperative channel access, and domestic blenders serving price-sensitive smallholder segments. Dominant competitive moves include backward integration into feed-grade vitamin manufacturing and consolidation of blending capacity around export-grade output.
Among global nutrition majors, BASF SE anchors vitamin premix supply through technical partnerships with Southeast Asian feed mills. Godrej Agrovet Ltd occupies a position within the regional compounder tier, leveraging captive distribution into Maharashtra cooperative channels. Cargill Incorporated exemplifies the diversified agribusiness archetype, supplying cattle stations across Australia's eastern seaboard through Queensland-based infrastructure.
| Leading Market Players |
|---|
| BASF SE |
| Godrej Agrovet Ltd |
| Cargill Incorporated |
| Lallemand Inc |
| Nutreco NV |
| ADM Animal Nutrition |
| Land O Lakes |
| Amul Cattle Feed |
| DSM NV |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Singapore container freight corridor anchors cost dynamics across Asia-Pacific ruminant feed premix markets, where refrigerated container rates directly compress blender margins on vitamin premix shipments while enabling price differentiation between cold-chain-dependent formulations and ambient-stable mineral blends. Cooperative procurement consolidation in India's western dairy belts feeds back into supply choices, favoring compounders with captive synthesis capacity over import-dependent distributors.
Pricing Analysis
Price spreads between Australian export-grade mineral premix and Indian domestic formulations reflect cold-chain intensity and certification tier differentiation. Three-tier pricing structure across export-certified, cooperative-grade, and smallholder-economy levels stratifies procurement, with GB 13078 compliance costs and APVMA residue testing driving premium tier separation. Pricing pressure stems from vitamin A and E concentrate volatility squeezing fixed-contract blender margins. Smallholder segments in Indonesia's emerging dairy belt exhibit highest price sensitivity, while Australian export-certified beef stations prioritize residue compliance over unit cost.
Supply Chain Analysis
China's GB standards on feed additive imports function as de facto export controls on premix constituent flows, restricting uncertified mineral and vitamin concentrate entry. Supply concentrates in China's Shandong and Hebei provinces, India's Gujarat and Maharashtra, and Australia's Queensland, with high-purity selenium and cobalt processing anchored in limited jurisdictions. Raw material dependencies span feed-grade vitamin concentrates, organic trace mineral chelates, and rumen-protected amino acids. Single-source mineral vulnerability creates structural supply risk. Distribution runs through direct manufacturer relationships with dairy cooperatives and compounder technical partnerships with feed mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative federation procurement consolidation across India and Vietnam, fragmenting spot-market liquidity and forcing compounders into multi-year supply agreements with technical service obligations.
For Market Incumbents: Harden cold-chain infrastructure in tropical distribution networks to defend against emerging regional compounders with captive vitamin synthesis. Deepen technical service presence through on-farm ration auditing capabilities in Maharashtra and Karnataka cooperative channels. Invest in micro-encapsulation capacity to offset thermolabile degradation risks and extend shelf-life economics.
For New Entrants and Emerging Players: Java's emerging dairy belt offers white-space positioning for mineral premix suppliers establishing technical service presence ahead of cooperative consolidation. Target Vietnam's antibiotic-free cattle finishing reformulation cycle with organic trace mineral and yeast culture portfolios. Pursue partnership-based market entry through feed mill technical collaborations rather than distributor network buildout.
For Investors and Strategic Acquirers: Regional compounders with cooperative channel access and backward integration into feed-grade vitamin manufacturing represent the priority acquisition archetype. Long-term viability hinges on carbon-footprint disclosure compliance capability as India's livestock input supply chain regulations mature. Monitor MEE environmental audit enforcement timelines in Shandong and Hebei as inflection signals for Chinese import eligibility restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Synthesis | Captive production of feed-grade vitamins insulates margins from petrochemical feedstock volatility. |
| Micro-Encapsulation Technology Investment | Extended tropical stability reduces refrigeration intensity and enables long-distance distribution economics. |
| Cooperative Technical Service Expansion | On-farm ration auditing capabilities secure multi-year supply agreements with consolidating dairy federations. |
| Carbon-Footprint Disclosure Infrastructure | Verified Scope 3 emissions tracking positions compounders for India's emerging livestock input regulations. |
| Antibiotic-Free Protocol Formulation Partnerships | Yeast culture and organic trace mineral portfolios capture Vietnamese and Indonesian export-market reformulation demand. |
Study Parameters
Cross-validation between primary interviews with feed mill procurement directors, cooperative federation nutritionists, and premix compounder technical managers anchors the qualitative findings against secondary validation from customs trade data, BIS feed-grade standards filings, and APVMA veterinary chemical residue guidelines. Bottom-up demand modeling from individual dairy cooperative procurement volumes triangulates with top-down market sizing from regional compounder capacity assessments.
Calibration against historical mineral premix and vitamin premix volume trajectories shapes the analytical framework across the analysis window. Segmentation dimensions span product type, distribution channel, animal species, and end-user technical capability tier. CAGRs derive from regression analysis of cooperative procurement expansion rates, regulatory compliance cost trajectories, and cold-chain infrastructure investment patterns.
Practitioners should monitor GB 13078 enforcement intensity, PLI scheme disbursement timelines, and MEE environmental audit outcomes for early signals of supply chain restructuring. Forecasts reflect assumptions on cooperative consolidation velocity and antibiotic-free protocol adoption rates. Material shifts in China's import eligibility criteria or India's carbon-footprint disclosure enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Peat Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Europe Ruminant Feed Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Beet Pulp Pellets Market