
 Sugar Beet Pulp Pellets Market | 2026-2036
Sugar Beet Pulp Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Beet Pulp Pellets Market Insights
Soybean meal in European dairy rations is expanding its displacement by sugar beet pulp pellets as protein-cost volatility and nitrogen-emission rules rewrite feed economics. Südzucker AG leverages integrated sugar-to-pellet processing across German and Polish facilities to sustain margin capture from molasses through finished feedstock. American Crystal Sugar Company anchors North American supply through captive pelleting capacity tied to Red River Valley beet campaigns. Nordzucker AG competes on pellet durability specifications that meet automated feeding system requirements in Scandinavian dairy barns.
Sugar beet pulp pellets are dried, compressed cylindrical feedstuffs typically six to eight millimeters in diameter, produced from the fibrous residue remaining after sucrose extraction, containing fifteen to twenty percent residual sugar and forty to fifty percent digestible fiber on a dry-matter basis. Their primary commercial purpose is to deliver fermentable energy and structural fiber to ruminant livestock, particularly in high-production dairy systems where rumen health and milk butterfat consistency are production priorities. Pellets hold the dominant product position due to handling efficiency and reduced storage spoilage versus powder, while the crumble format is gaining traction among sheep and goat producers seeking lower intake barriers. Animal Feed occupies the largest end-user channel, though Biofuel Production is attracting capital as anaerobic digestion operators seek consistent lignocellulosic feedstock with favorable methane yield coefficients.
The EU F-Gas Regulation and REACH chemical safety framework shape pellet processing standards, particularly around drying-energy sources and dust-emission thresholds at pelleting facilities. Germany's KBA and the broader EU Green Deal farm sustainability metrics are pressuring cooperatives to document carbon intensity per ton of feed delivered. Stakeholders must monitor how evolving EU Common Agricultural Policy conditionality rules restructure subsidy eligibility for feed crops versus crop residues.
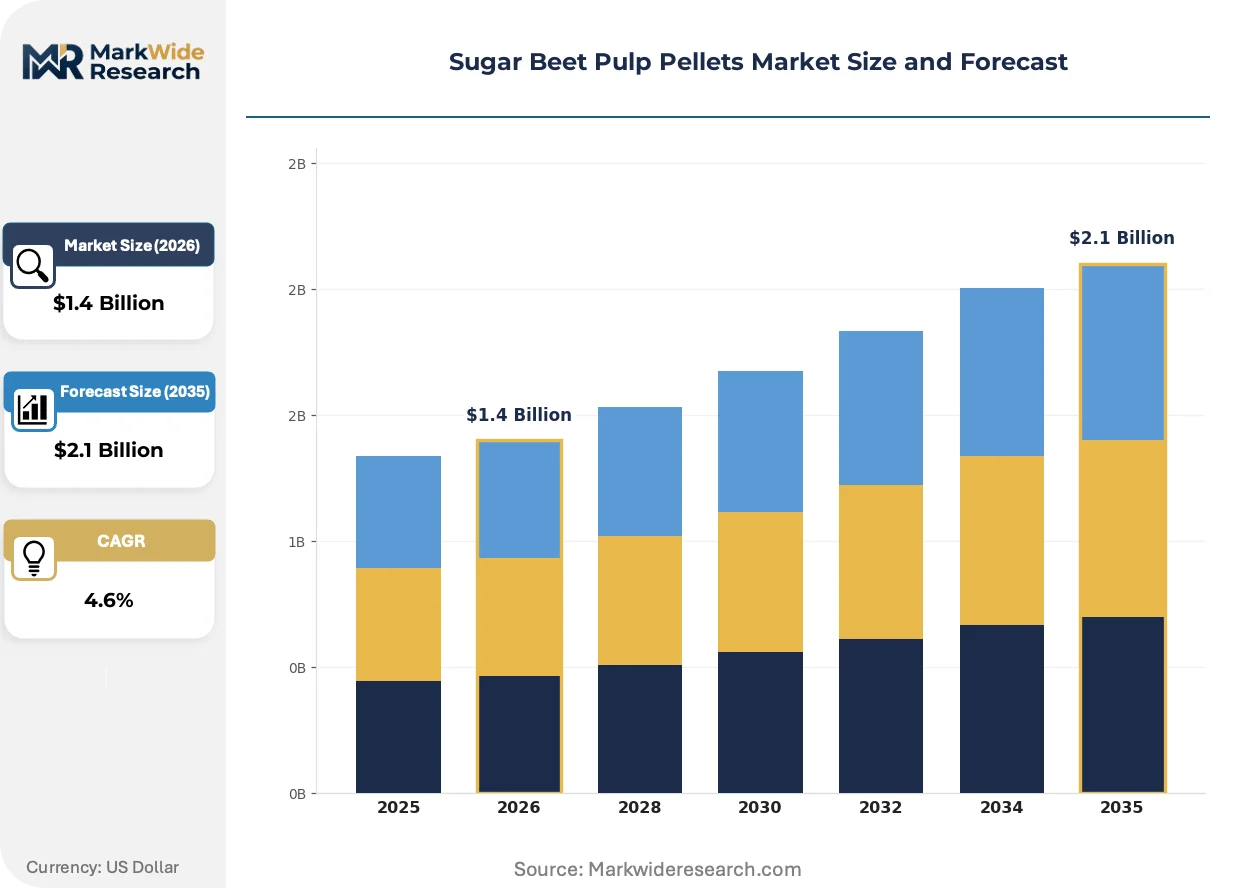
Market Dynamics
EU dairy cooperatives are consolidating procurement around certified low-carbon feedstocks as the Farm to Fork Strategy tightens nitrogen-emission accounting, compressing spot-market liquidity and favoring multi-year offtake structures between processors and end-users.
Growth Catalysts
- Anaerobic digestion feedstock demand:Biogas operators in Denmark and the Netherlands seek lignocellulosic inputs with favorable methane yield coefficients, pulling pellet volumes from traditional feed channels.
- REACH chemical safety alignment:Drying-energy certification under EU frameworks opens premium pricing tiers for processors documenting renewable heat sources.
- Scandinavian automated barn penetration:Dairy operations across Sweden and Finland specify durability-calibrated pellets compatible with robotic feeding systems.
Market Restraints
- Molasses price volatility:Residual sugar content valuation fluctuates with Brazilian ethanol arbitrage, compressing processor margins during campaign peaks.
- Red River Valley supply concentration:North American beet processing clusters in Minnesota and North Dakota create geographic vulnerability to weather-driven campaign interruptions.
- Soybean meal substitution economics:Protein-cost swings in Chicago futures markets periodically restore soy's competitiveness in total mixed rations.
Strategic Opportunities
- Polish processing expansion:Greenfield pellet capacity near Poznan and Wroclaw captures stranded beet fiber from expanding domestic sugar operations.
- Sheep and goat crumble formats:Smaller-diameter pellets reduce intake barriers in Mediterranean small-ruminant systems.
- EU Common Agricultural Policy conditionality:Residue-based feed certification pathways unlock greening-payment eligibility for dairy producers.
Industry Challenges
- Biomass dryer operator scarcity:Specialized technicians for low-temperature pelleting systems command premium wages across German processing corridors.
- KBA emission compliance timelines:Retrofitting existing facilities to meet dust-threshold standards requires extended shutdown windows during narrow campaign windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Beet Pulp Pellets Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Granules, Powder, Crumble End User: Animal Feed, Food Industry, Biofuel Production, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers Application: Nutritional Supplement, Fodder, Soil Amendment, Ingredient |
| Companies Covered | Michigan Sugar Company, American Crystal Sugar Company, Südzucker AG, Western Sugar Cooperative, Sucden Group, Nordzucker AG, AGRANA Beteiligungs-AG, Pfeifer & Langen GmbH & Co. KG, Tereos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Beet Pulp Pellets Market Trends and Innovations
Processing technology and procurement contracting are converging to reduce carbon intensity documentation burdens while expanding addressable end-use segments beyond traditional dairy feed.
Low-temperature belt drying systems are integrating heat-recovery loops and alternative fuel compatibility to satisfy EU F-Gas Regulation energy-source requirements. German and Polish facilities are retrofitting existing drum dryers with biomass-fired heat exchangers. This hardware transition is integrating carbon-accounting software directly into plant control systems, compressing audit preparation cycles from weeks to days.
The EU Green Deal farm sustainability metrics are mandating feed-carbon disclosure at the cooperative level, forcing procurement departments to reject uncertified pellet sources. Dairy processors in the Netherlands now require supplier-provided lifecycle data as a contract precondition. Scandinavian buyers are responding fastest, embedding these requirements into multi-year supply agreements ahead of formal enforcement dates.
Direct contracting between sugar processors and integrated dairy cooperatives is displacing merchant distributor networks across Northern Europe. Long-term offtake structures with fixed volume commitments and indexed pricing are replacing spot-market purchases. This channel compression is most visible in the Netherlands, where FrieslandCampina and similar cooperatives have internalized procurement functions previously outsourced to feed traders.
Sugar Beet Pulp Pellets Market Segmentation
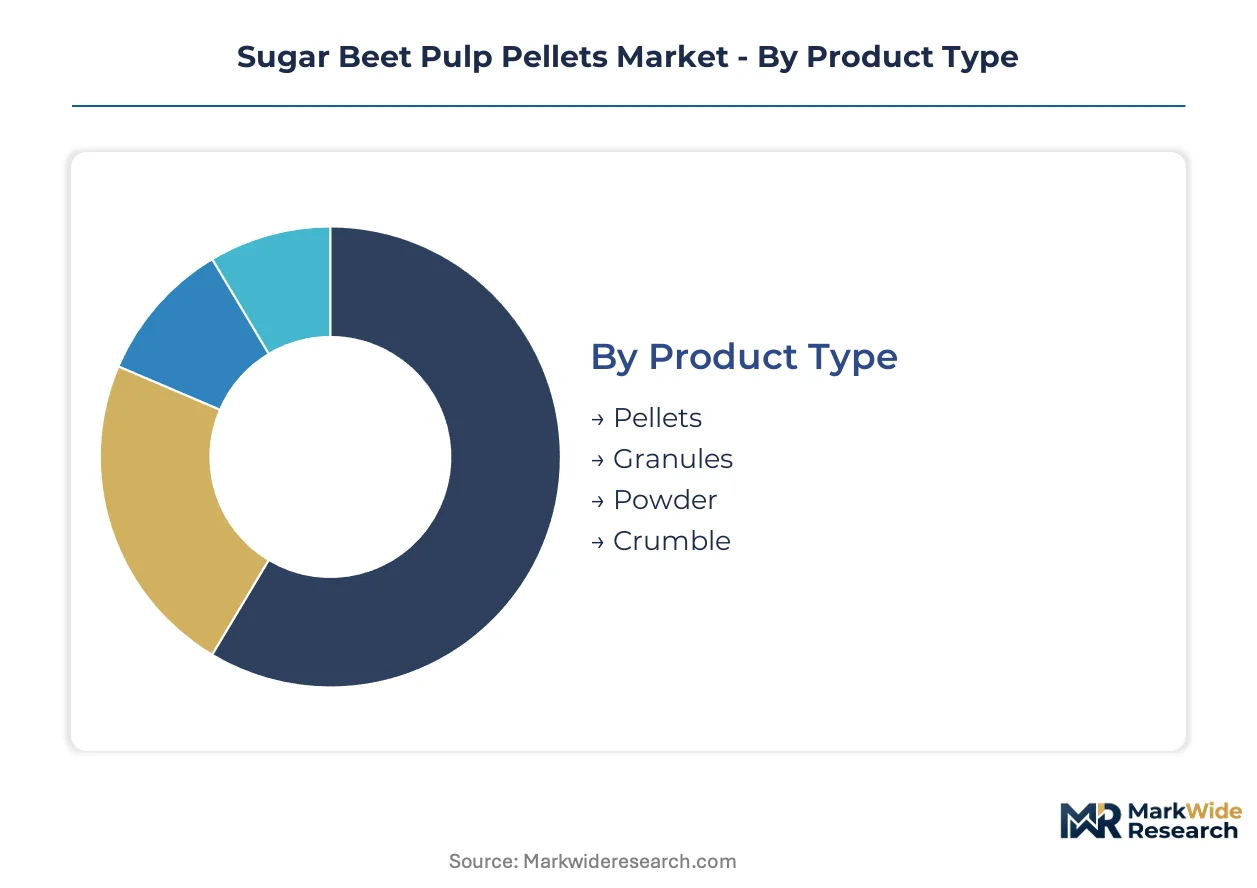
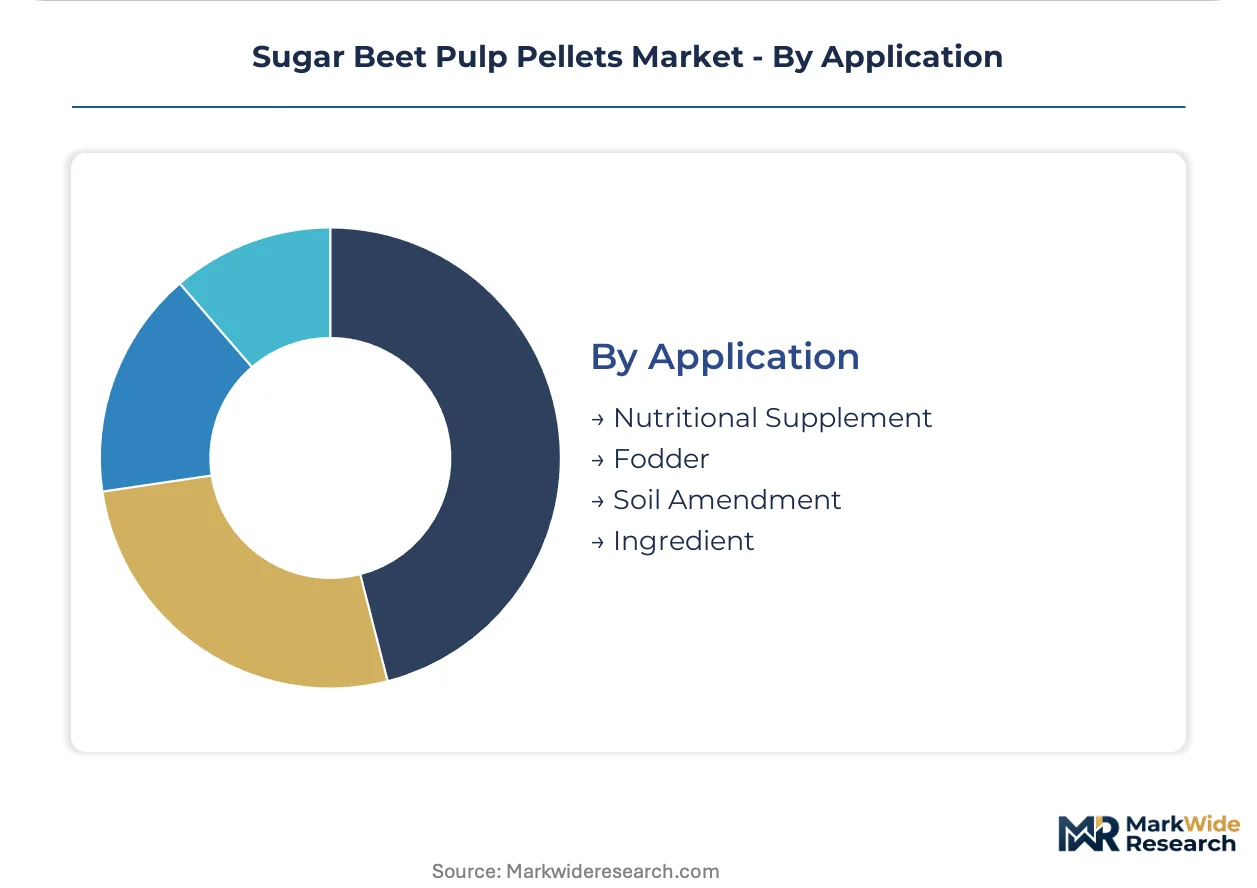
Sugar beet pulp pellet processors calibrate product formats and distribution pathways against ruminant digestive physiology, automated feeding infrastructure, and carbon-accounting compliance requirements. Segment boundaries reflect tension between commodity bulk handling and precision-formulation services for high-output dairy systems.
Product Type:
Standardization dominates high-volume dairy channels while crumble and powder variants serve specialized small-ruminant and precision-blending applications.
- Pellets:Cylindrical compressed feedstuffs six to eight millimeters in diameter, delivering fifteen to twenty percent residual sugar and forty to fifty percent digestible fiber on a dry-matter basis. Dairy operations across Germany and the Netherlands specify durability-calibrated pellets compatible with robotic feeding systems, driven by the Farm to Fork Strategy's nitrogen-emission accounting requirements.
- Crumble:Smaller-diameter fractured pellets reducing intake barriers for sheep and goat producers. Mediterranean small-ruminant systems in Spain and Italy are adopting crumble formats as protein-cost volatility displaces soybean meal with sugar beet fiber sources.
- Granules:Intermediate particle size offering handling efficiency between powder and pellet formats. Equine feed compounders in France utilize granules for custom ration blending where pelleting heat would degrade supplemental additives.
- Powder:Uncompressed fibrous residue requiring moisture-protected storage. Anaerobic digestion operators in Denmark accept powder deliveries for biogas feedstock where handling infrastructure accommodates bulk loose materials.
Most installed capacity flows through Pellets. Expansion is steepest in Crumble.
End User:
Volume concentration in livestock feed channels contrasts with emerging demand from energy recovery and crop management sectors.
- Animal Feed:Primary commercial channel delivering fermentable energy and structural fiber to ruminant livestock. High-production dairy systems prioritize rumen health and milk butterfat consistency, with integrated cooperatives in the Netherlands negotiating long-term offtake contracts directly with sugar processors.
- Biofuel Production:Anaerobic digestion operators seek consistent lignocellulosic feedstock with favorable methane yield coefficients. Danish biogas facilities are pulling pellet volumes from traditional feed channels as the EU Green Deal tightens renewable energy targets.
- Food Industry:Limited application as fiber fortification ingredient. Specialty food manufacturers in Germany explore sugar beet pulp as clean-label texturizing agent in reduced-sugar formulations.
- Agriculture:Soil amendment applications leveraging organic matter content and slow-release nutrient profiles. Polish crop producers apply pelletized pulp as alternative to peat-based soil conditioners.
Revenue concentration sits with Animal Feed. Biofuel Production is gaining share fastest.
Distribution Channel:
Channel compression favors direct processor-to-cooperative structures over merchant intermediaries.
- Direct Sales:Long-term offtake agreements between sugar processors and integrated dairy cooperatives. FrieslandCampina and similar Dutch cooperatives have internalized procurement functions previously outsourced to feed traders.
- Distributors:Regional feed merchants serving fragmented farm operations without scale for direct contracting. German distributors maintain inventory buffers across the narrow beet processing campaign window.
- Wholesalers:Bulk commodity handlers aggregating volumes for export and spot-market liquidity. Polish wholesalers coordinate cross-border movements to Scandinavian buyers.
- Online Retail:Emerging channel for small-scale livestock producers and specialty equine customers. Platform-based purchasing remains marginal due to bulk logistics requirements.
Contract volume concentrates in Direct Sales. Distributors retain relevance in spot-market dislocations.
Application:
Functional differentiation separates energy-supplementation uses from structural fiber and soil-conditioning roles.
- Fodder:Basal ration ingredient replacing hay and silage in total mixed rations. French and German dairy operations expand fodder applications as EU F-Gas Regulation tightens feed sustainability benchmarks.
- Nutritional Supplement:Targeted addition to address fiber deficits or energy shortfalls in precision-formulated diets. Scandinavian automated barns specify supplement-grade pellets with consistent nutrient assays.
- Soil Amendment:Field application improving water retention and organic matter in arable soils. Polish and Romanian agriculture deploys pelletized pulp for carbon-sequestration credentialing under EU Common Agricultural Policy conditionality.
- Ingredient:Component in compounded feeds and industrial formulations. Compound feed manufacturers in Belgium incorporate pulp as cost-stabilizing fiber source amid protein-market volatility.
Volume throughput centers on Fodder. Soil Amendment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red River Valley processing cluster spanning Minnesota and North Dakota anchors North American sugar beet pulp pellet supply through captive pelleting capacity tied to seasonal beet campaigns. European demand concentrates in integrated dairy corridors where cooperatives negotiate direct offtake contracts with processors.
Germany
Dairy cattle operations across Lower Saxony and Bavaria expand pellet use as digestible fiber in total mixed rations. The EU F-Gas Regulation and KBA emission standards tighten processing benchmarks, pushing Südzucker AG facilities toward certified low-carbon production. Integrated sugar-to-pellet corridors near Magdeburg and Plattling sustain margin capture from molasses through finished feedstock.
Netherlands
FrieslandCampina and similar cooperatives consolidate procurement around long-term offtake structures with fixed volume commitments. The EU Green Deal farm sustainability metrics mandate feed-carbon disclosure, forcing rejection of uncertified pellet sources. Direct contracting between sugar processors and dairy cooperatives displaces merchant distributor networks across the Randstad region.
Denmark
Biogas operators seek lignocellulosic feedstock with favorable methane yield coefficients, pulling pellet volumes from traditional feed channels. The EU renewable energy targets tighten anaerobic digestion operator requirements for consistent lignocellulosic inputs. Danish facilities near Aarhus and Odense retrofit existing infrastructure to accommodate pelletized pulp alongside agricultural residues.
Poland
Greenfield pellet capacity near Poznan and Wroclaw captures stranded beet fiber from expanding domestic sugar operations. The EU Common Agricultural Policy conditionality rules restructure subsidy eligibility for residue-based feed certification pathways. Polish crop producers deploy pelletized pulp as soil amendment alternative to peat-based conditioners across Greater Poland Voivodeship.
Sweden
Automated dairy barns specify durability-calibrated pellets compatible with robotic feeding systems. Scandinavian buyers embed carbon-accounting requirements into multi-year supply agreements ahead of formal enforcement dates. Dairy operations across Skåne and Västra Götaland prioritize rumen health and milk butterfat consistency through precision-formulated fiber supplementation.
Sugar Beet Pulp Pellets Market Competitive Landscape
Capacity expansion dominates the current landscape as processors retrofit existing drum dryers with biomass-fired heat exchangers to satisfy EU F-Gas Regulation energy-source requirements. The vendor base stratifies across integrated sugar conglomerates with captive pelleting assets, independent pellet specialists serving spot-market liquidity, and cooperative processors tied to single-region beet campaigns. Three archetypes define competitive positioning: vertically integrated sugar-to-feed operators, regional cooperative processors, and biogas-focused lignocellulosic suppliers. Geographic expansion and technology licensing represent the dominant competitive moves, with players securing heat-recovery loop patents and alternative fuel compatibility certifications.
Within the integrated conglomerate tier, Südzucker AG exemplifies backward integration into sugar-to-pellet processing across German and Polish facilities, while American Crystal Sugar Company anchors North American supply through captive pelleting capacity. Nordzucker AG occupies a position defined by pellet durability specifications calibrated to automated feeding infrastructure requirements. These three entities represent distinct geographic and technological positioning archetypes without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Michigan Sugar Company |
| American Crystal Sugar Company |
| Südzucker AG |
| Western Sugar Cooperative |
| Sucden Group |
| Nordzucker AG |
| AGRANA Beteiligungs-AG |
| Pfeifer & Langen GmbH & Co. KG |
| Tereos Group |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracting by Dutch dairy cooperatives under EU Green Deal carbon-disclosure mandates is compressing spot-market liquidity and forcing processors to certify low-carbon production tiers. This procurement consolidation shifts pricing power toward integrated sugar-to-pellet operators with documented renewable heat sourcing.
Pricing Analysis
Input-cost pass-through from molasses valuation and biomass-fired drying energy dominates contract negotiations. Three-tier pricing structure across certified low-carbon, standard grade, and uncertified spot tiers separates buyers by sustainability documentation requirements. Cost compression in the standard tier is intensifying as Brazilian ethanol arbitrage swings residual sugar valuations. Small-scale ruminant producers remain most price-sensitive, while automated dairy cooperatives absorb premiums for durability-calibrated pellets.
Supply Chain Analysis
Reverse-logistics flows of spent fiber from anaerobic digestion operators back to agricultural soil amendment applications are closing nutrient loops in Danish and Polish corridors. Supply concentrates in Germany, Poland, and the Red River Valley of Minnesota and North Dakota. Raw material dependencies center on sugar beet campaign residue, biomass fuel for drying, and molasses blending agents. Single-source vulnerability runs through the narrow beet processing window. Distribution runs through direct processor-to-cooperative contracts displacing merchant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where premium specifications for carbon-accounting documentation and robotic-feeding compatibility command widening price premiums over commodity grades.
For Market Incumbents: Extend durability-certification programs to capture Scandinavian automated barn specifications before formal EU enforcement dates. Secure captive biomass fuel supply through backward integration into energy crop contracting. Biogas operator demand for lignocellulosic feedstock threatens traditional feed channel volumes. For New Entrants and Emerging Players: Capture crumble-format white space in Mediterranean small-ruminant systems where protein-cost volatility is displacing soybean meal. Target Polish greenfield processing corridors near expanding domestic sugar operations. Lead with carbon-accounting software integration as differentiated service bundling. For Investors and Strategic Acquirers: Asymmetric upside sits with regional cooperative processors possessing stranded beet fiber access and retrofit-ready drying infrastructure. Long-term viability hinges on EU Common Agricultural Policy conditionality enforcement expanding residue-based feed eligibility. Watch for KBA emission compliance timeline acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biomass-Fired Dryer Retrofit | KBA emission standards force German processors toward renewable heat sourcing. |
| Carbon-Accounting Software Integration | FrieslandCampina contract preconditions compress audit preparation cycles. |
| Crumble Format Capacity Addition | Spanish and Italian small-ruminant producers seek lower intake barriers. |
| Long-Term Offtake Structuring | Dutch cooperatives displace merchant distributors with direct contracts. |
| Biogas Feedstock Certification | Danish anaerobic digestion operators pull volumes from traditional feed channels. |
Research Methodology
Coverage spans Northern Europe, North America, and emerging Central European processing corridors, with primary inputs from each. Sugar processing plant managers, dairy cooperative procurement directors, biogas facility operators, and feed distribution channel partners provided operational data. Secondary validation drew from EU F-Gas Regulation filings, KBA emission standard documentation, SEC 10-K disclosures by listed processors, and customs trade data on pellet cross-border movements. Bottom-up campaign volume modeling and top-down feed demand estimation were triangulated.
Granularity-level modeling captured product format differentiation by ruminant species and feeding system compatibility, end-use segmentation across feed and biofuel channels, and distribution channel evolution from merchant intermediaries to direct contracting. CAGRs were derived through multi-year trend extrapolation of campaign volumes and procurement contract tenors. Forecast inputs included beet acreage planting intentions, EU Green Deal implementation pacing, and anaerobic digestion capacity buildout schedules.
Molasses price volatility, regulatory enforcement timeline shifts, and biogas feedstock demand acceleration are the dominant revision risks to modeled outputs. Forecasts reflect assumptions on campaign timing, emission standard compliance costs, and cooperative procurement consolidation trajectories. Practitioners should monitor EU Common Agricultural Policy conditionality rulemaking and KBA inspection intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Premix Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Growing Peat Market