
 GCC Fertilizer Market | 2026-2036
GCC Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Fertilizer Market Foresight
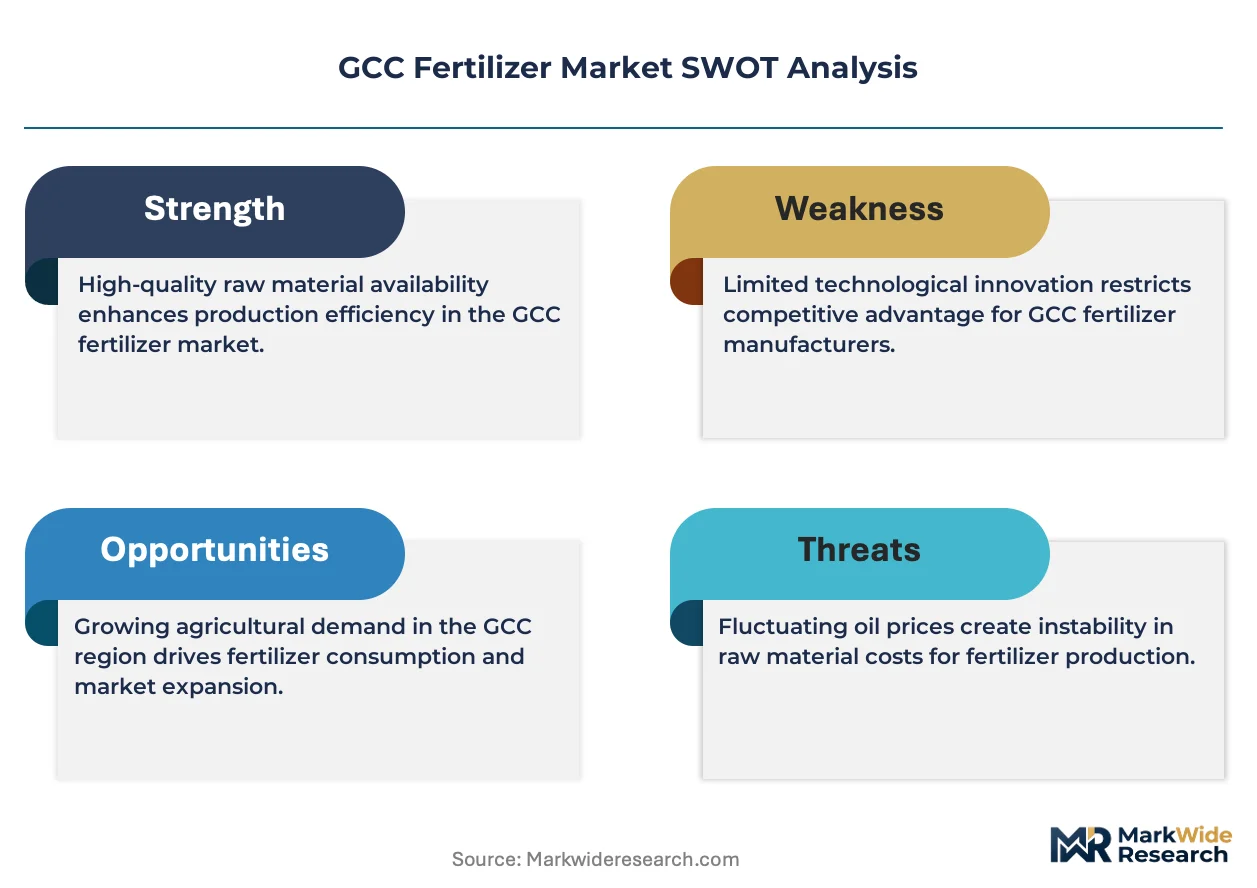
ISO 14001 environmental management certification is unwinding competitive access across the GCC fertilizer value chain, filtering out smaller traders lacking audit capacity. SABIC Agri-Nutrients leverages its integrated gas-to-urea infrastructure across Jubail and Yanbu to sustain cost leadership in nitrogen exports. Ma'aden anchors phosphate rock supply through its Waad Al-Shamal complex, while Qatar Fertilizer Company competes on ammonia derivative specialization for Asian offtake markets.
GCC fertilizers encompass nitrogenous, phosphatic, and potassic nutrient formulations manufactured via Haber-Bosch synthesis, wet acid processing, or bulk blending, with specifications calibrated to regional soil salinity and irrigation water chemistry. Their primary purpose is correcting macronutrient deficits in arid-zone agriculture where natural soil organic matter falls below productive thresholds. Urea dominates volume throughput given regional natural gas feedstock abundance, though compound fertilizers are capturing margin pools as precision agriculture spreads across Saudi cereal operations. Greenhouse operations represent the fastest-growing end-user channel, driven by UAE and Qatar import-substitution programs for fresh produce.
Saudi Arabia's Standards, Metrology and Quality Organization (SASO) governs fertilizer registration and labeling, while the UAE's Ministry of Climate Change and Environment administers agricultural input licensing across emirate-level jurisdictions. Both frameworks are tightening heavy metal limits and slow-release coating standards, forcing reformulation investments from incumbent suppliers. Stakeholders must monitor water-energy-food nexus policy shifts as desalination capacity expansion alters the cost structure of liquid fertilizer application systems.
Market Dynamics
Water-energy-food nexus policies across the Gulf Cooperation Council are forcing capital reallocation toward desalination-integrated liquid fertilizer systems, compressing traditional granular distribution economics while elevating precision application infrastructure.
Growth Catalysts
- UAE reclaimed water mandates:The Ministry of Climate Change and Environment is expanding treated wastewater irrigation networks, creating compatible slow-release and foliar formulation demand from greenhouse operators in Al Ain and Ras Al Khaimah.
- Qatar greenhouse import substitution:National food security programs are expanding hydroponic and controlled-environment agriculture acreage, concentrating specialty nutrient orders for high-value tomato and cucumber cultivation.
- SASO heavy metal limits:Saudi Arabia's Standards, Metrology and Quality Organization is tightening cadmium and arsenic thresholds in phosphate fertilizers, filtering non-compliant imports and securing domestic Waad Al-Shamal complex offtake.
Market Restraints
- Natural gas feedstock volatility:Urea production margins at Jubail and Yanbu complexes remain exposed to domestic gas pricing reforms under Saudi Vision 2030 economic diversification targets.
- Phosphate rock concentration:Ma'aden controls Waad Al-Shamal ore reserves, creating single-source dependency for GCC phosphatic fertilizer manufacturing and limiting price negotiation leverage for downstream blenders.
- Potash import exposure:The region possesses no domestic potassium chloride extraction, forcing 100% reliance on Canadian and Belarusian seaborne supply subject to Red Sea shipping disruptions.
Strategic Opportunities
- Oman underpenetrated coastal agriculture:Salalah and Batinah plain irrigation expansion offers first-mover positioning for compound fertilizer distributors before domestic blending capacity consolidates.
- Biofertilizer convergence:Microbial inoculant-integrated formulations are penetrating date palm cultivation in Al-Ahsa oasis systems, combining synthetic nutrient efficiency with organic certification pathways for export fruit.
- Drone application channels:Variable-rate aerial spreading is emerging across Saudi cereal belt operations, creating service-contract revenue pools beyond product-only sales for input suppliers.
Industry Challenges
- ISO 14001 audit capacity scarcity:Smaller trading houses lack environmental management system certification resources, blocking access to SABIC Agri-Nutrients and Qatar Fertilizer Company direct supply agreements.
- Liquid fertilizer infrastructure capex:Conversion from bagged urea to bulk liquid storage and injection systems requires terminal investments that strain distributor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Fertilizer Market |
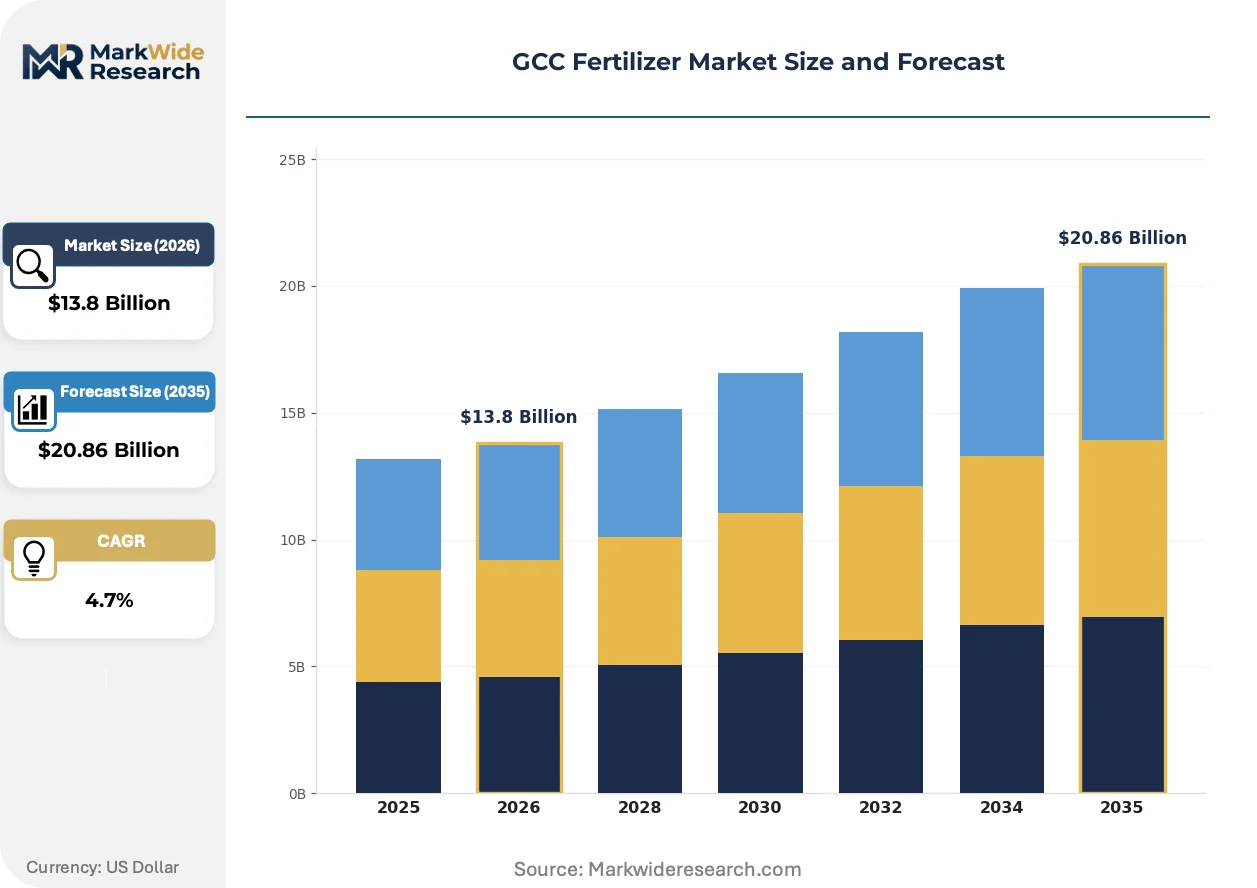
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.86 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fertilizer Type: Urea, Phosphates, Potash, Compound Fertilizers Application: Cereal Crops, Fruits & Vegetables, Oilseeds, Fiber Crops End User: Large-Scale Farms, Greenhouse Operations, Horticulture Producers, Organic Growers Distribution Channel: Direct Sales, Agricultural Retailers, Online Platforms, Cooperatives |
| Companies Covered | Gulf Petrochemical Industries Company, Emirates Bio Fertilizer Factory, SABIC Agri-Nutrients, Union Chemicals Co. LLC, RNZ Agrotech Industries Ltd., Qatar Fertilizer Company, Oman Indian Fertilizer Company, Yara International ASA, Saudi Arabian Mining Company – Ma'aden, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Fertilizer Market Shifts & Advancements
Controlled-release coating chemistry and digital soil mapping are converging to displace blanket application practices across Gulf arid-zone agriculture, compressing per-hectare nutrient volumes while elevating price realization per unit.
Polymer-coated urea is supplanting conventional prilled product in Saudi wheat and alfalfa operations. Large-scale farms in Al-Kharj and Tabuk are adopting sulfur-coated and polymer-encapsulated nitrogen at 15-20% annual adoption velocity. This technology is enabling split-application elimination, cutting labor costs while reducing groundwater nitrate leaching penalties under emerging SASO water quality enforcement.
EU F-Gas Regulation analogues are influencing GCC cold-chain fertilizer storage standards, particularly for ammonium nitrate and calcium ammonium nitrate stability requirements. Industrial consequence includes accelerated investment in climate-controlled warehousing at Jebel Ali and Dammam port zones. Specialty nitrogen importers serving Qatar's greenhouse sector are most affected, responding with temperature-monitoring IoT integration in transit containers.
Consolidated procurement by sovereign-backed farming entities is fragmenting distributor margins across the Emirates. Large-scale operators in Dubai's Food Tech Valley and Abu Dhabi's Al Dahra Agriculture are establishing direct manufacturer relationships, displacing traditional commission-based trading houses. This pattern is most visible in UAE vegetable production, where annual contract volumes now exceed spot-market purchases for nitrogen and compound grades.
GCC Fertilizer Market Segmentation
Segmentation reveals how GCC fertilizer demand fragments across crop systems, operational scales, and procurement channels. Each dimension carries distinct formulation requirements, pricing tolerance, and regulatory exposure that reshape supplier go-to-market priorities.
Fertilizer Type:
Domestic production concentrates nitrogenous output, while phosphatic and potassic grades remain import-dependent with diverging supply security profiles.
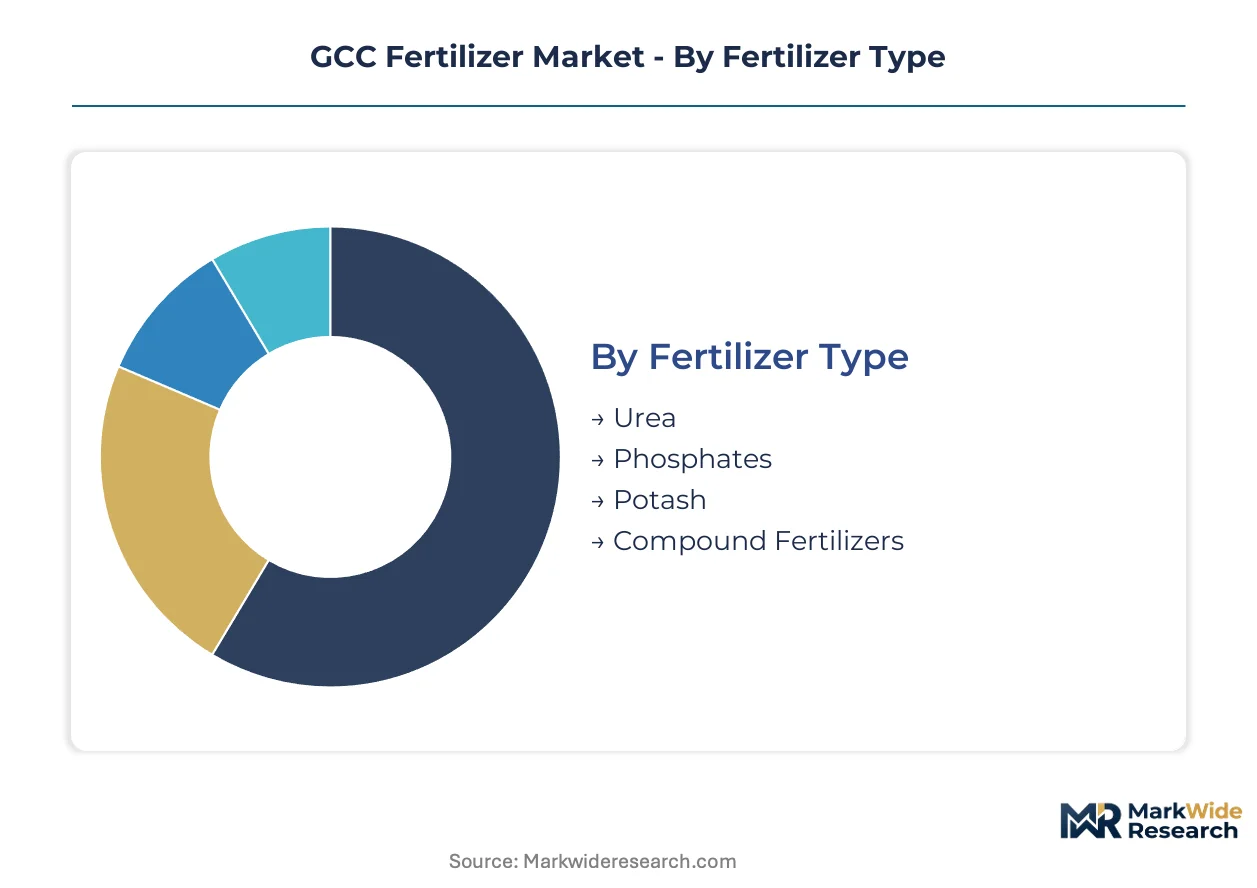
- Urea:Prilled and granular nitrogen formulations synthesized via Haber-Bosch process dominate volume throughput across Saudi Arabia's Al-Kharj cereal belt. SABIC Agri-Nutrients' Jubail and Yanbu complexes anchor regional supply, though domestic gas pricing reforms under Vision 2030 threaten margin stability.
- Phosphates:Diammonium phosphate and monoammonium phosphate grades from Ma'aden's Waad Al-Shamal complex serve domestic blenders and Asian export markets. SASO's tightening cadmium and arsenic thresholds are filtering non-compliant imports and securing captive offtake for domestic rock processing.
- Potash:Muriate of potash and sulfate of potash arrive entirely through seaborne import from Canadian and Belarusian sources, exposing GCC agriculture to Red Sea shipping corridor disruptions.
- Compound Fertilizers:NPK blends calibrated to regional soil salinity and irrigation chemistry are capturing margin pools as precision agriculture spreads across Saudi cereal operations and UAE greenhouse systems.
Urea commands the established base. The steepest expansion runs through compound fertilizers.
Application:
Water availability and crop value per hectare determine formulation sophistication, with protected cultivation driving premium nutrient demand.
- Cereal Crops:Wheat and barley production across Saudi Arabia's central plateau consumes bulk urea and DAP through flood irrigation systems. Polymer-coated nitrogen adoption is accelerating at 15-20% annual velocity as large-scale farms eliminate split-application labor costs.
- Fruits & Vegetables:Date palms in Al-Ahsa oasis systems and greenhouse tomatoes in Qatar's Al Khor complex require micronutrient-fortified formulations and controlled-release coatings. Biofertilizer convergence is penetrating this segment through microbial inoculant integration for organic certification pathways.
- Oilseeds:Sesame and sunflower cultivation in Oman's Batinah plain represents an underpenetrated channel for compound fertilizer distributors before domestic blending capacity consolidates.
- Fiber Crops:Alfalfa production for dairy feed in UAE's Al Ain region drives sulfur-coated urea demand under reclaimed water irrigation mandates from the Ministry of Climate Change and Environment.
Cereal crops anchor volume demand. Protected fruit and vegetable cultivation delivers the fastest margin expansion.
End User:
Procurement scale separates price-takers from price-makers, with sovereign-backed entities rewriting traditional distribution economics.
- Large-Scale Farms:Consolidated operators in Dubai's Food Tech Valley and Abu Dhabi's Al Dahra Agriculture are establishing direct manufacturer relationships, displacing traditional commission-based trading houses through annual contract volumes exceeding spot-market purchases.
- Greenhouse Operations:Hydroponic and controlled-environment agriculture across Qatar's expanded vegetable production and UAE's Ras Al Khaimah clusters concentrate specialty nutrient orders for high-value tomato and cucumber cultivation.
- Horticulture Producers:Open-field vegetable and ornamental growers in Saudi Arabia's Tabuk region rely on agricultural retailers for bagged compound fertilizers with localized soil test recommendations.
- Organic Growers:Date palm export certification requirements in Al-Ahsa are driving biofertilizer adoption alongside reduced synthetic nutrient rates, creating hybrid input demand.
Large-scale farms control pricing leverage. Greenhouse operations are expanding most quickly as import substitution programs accelerate.
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and working capital availability across the value chain.
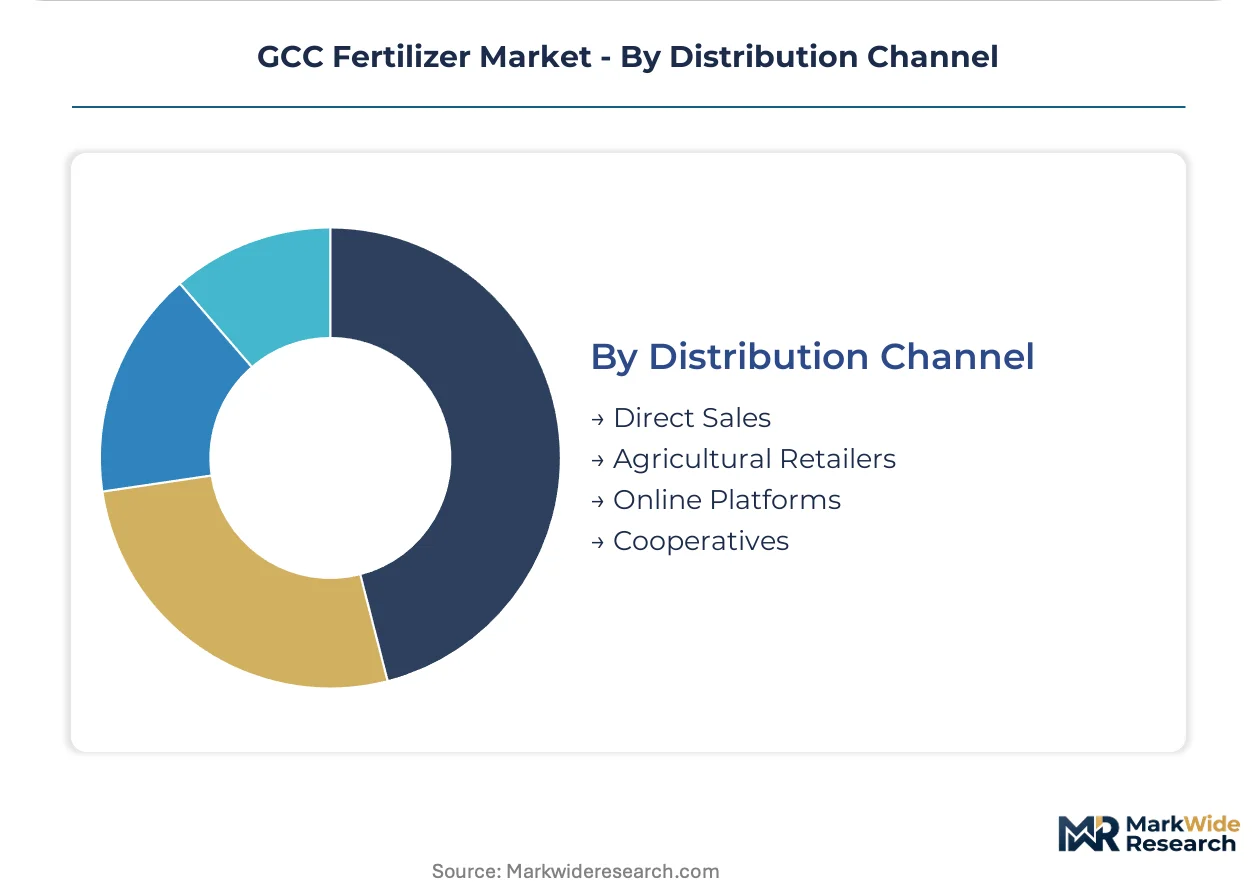
- Direct Sales:SABIC Agri-Nutrients and Qatar Fertilizer Company supply agreements with ISO 14001-certified offtakers bypass distributor margins for bulk urea and ammonia derivative shipments to Asian markets.
- Agricultural Retailers:Traditional trading houses in Jeddah and Dammam serve smallholder horticulture producers with bagged products, though margin compression from consolidated procurement is forcing portfolio diversification into agronomic services.
- Online Platforms:Digital procurement portals are emerging for greenhouse operators seeking specialty foliar formulations with technical documentation and temperature-monitoring logistics integration.
- Cooperatives:Farmer associations in Oman's Salalah coastal agriculture zone aggregate demand for compound fertilizer distributors seeking first-mover positioning before domestic blending capacity develops.
Direct sales capture the highest volume throughput. Digital platforms are gaining share fastest among technically sophisticated greenhouse operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration tilts toward sovereign-backed agricultural entities and consolidated greenhouse operators, with procurement scale determining supplier access across Gulf Cooperation Council jurisdictions. National food security mandates are redrawing distribution economics, favoring direct manufacturer relationships over traditional trading intermediaries. Water-energy-food nexus policies are accelerating capital deployment toward precision application infrastructure in coastal agriculture zones.
Saudi Arabia
Wheat and date palm intensification across the Al-Kharj agricultural cluster is driving polymer-coated urea adoption at double-digit annual velocity. SASO's tightening cadmium and arsenic thresholds in phosphate fertilizers are filtering non-compliant imports and securing captive offtake for domestic Waad Al-Shamal complex processing. Large-scale cereal operations in Tabuk are eliminating split-application labor costs through controlled-release nitrogen deployment.
United Arab Emirates
Reclaimed water irrigation mandates from the Ministry of Climate Change and Environment are reshaping slow-release and foliar formulation demand from greenhouse operators. Dubai's Food Tech Valley and Abu Dhabi's Al Dahra Agriculture are establishing direct manufacturer relationships, displacing traditional commission-based trading houses through annual contract volumes. Alfalfa production for dairy feed in Al Ain drives sulfur-coated urea demand under treated wastewater protocols.
Qatar
National food security programs are expanding hydroponic and controlled-environment agriculture acreage, concentrating specialty nutrient orders for high-value tomato and cucumber cultivation. The Al Khor greenhouse complex anchors import-substitution vegetable production with precision-calibrated compound fertilizer requirements. Qatar Fertilizer Company competes on ammonia derivative specialization for Asian offtake markets alongside domestic greenhouse supply.
Oman
Coastal agriculture expansion across Salalah and the Batinah plain offers first-mover positioning for compound fertilizer distributors before domestic blending capacity consolidates. Farmer associations in irrigation development zones aggregate demand for suppliers seeking channel establishment ahead of infrastructure maturation. Sesame and sunflower cultivation represents an underpenetrated channel for NPK blend penetration.
Kuwait
Greenhouse vegetable import substitution programs are emerging as a secondary demand node within the regional food security architecture. Limited domestic production capacity creates dependency on cross-border supply relationships with Saudi and UAE manufacturers. Coastal agriculture development remains nascent relative to neighboring jurisdictions, presenting delayed-entry positioning for specialty formulation suppliers.
GCC Fertilizer Market Competitive Landscape
Player mix skews toward integrated petrochemical conglomerates with captive natural gas feedstock positions and sovereign-linked mining enterprises controlling phosphate rock reserves. Market structure concentrates nitrogenous output around Haber-Bosch synthesis complexes in Jubail and Yanbu, while phosphatic supply hinges on single-source ore dependency at Waad Al-Shamal. Strategic archetypes span gas-to-urea integrators, phosphate rock miners with downstream acid processing, and specialty compound blenders serving greenhouse precision agriculture. Dominant competitive moves include ISO 14001 environmental certification barriers that filter trading access, and liquid fertilizer infrastructure investments that strain distributor balance sheets.
Within the integrated petrochemical tier, SABIC Agri-Nutrients and Qatar Fertilizer Company anchor regional nitrogen supply through Haber-Bosch synthesis infrastructure. Ma'aden occupies a position as the dominant phosphate rock supplier through its Waad Al-Shamal mining and acid processing complex. Among international specialty players, Yara International ASA represents the compound fertilizer and precision agriculture archetype with greenhouse-focused formulation expertise. Emirates Bio Fertilizer Factory exemplifies the biofertilizer convergence segment integrating microbial inoculants for organic certification pathways in date palm export cultivation.
| Leading Market Players |
|---|
| Gulf Petrochemical Industries Company |
| Emirates Bio Fertilizer Factory |
| SABIC Agri-Nutrients |
| Union Chemicals Co. LLC |
| RNZ Agrotech Industries Ltd. |
| Qatar Fertilizer Company |
| Oman Indian Fertilizer Company |
| Yara International ASA |
| Saudi Arabian Mining Company – Ma'aden |
| Others |
Supply & Pricing Matrix
ISO 14001 environmental management certification gates both supply qualification and price differentiation across the GCC fertilizer value chain, filtering smaller traders from direct manufacturer agreements while creating tiered access premiums for certified offtakers. This dual function compresses margins for uncertified intermediaries and elevates realized prices for compliant distributors serving SABIC Agri-Nutrients and Qatar Fertilizer Company channels.
Pricing Analysis
Cost-plus contracts with Henry Hub and Brent indexation dominate urea and ammonia derivative pricing between Jubail-Yanbu producers and Asian offtake markets. Price differentiation rests on ISO 14001 certification grade and volume scale, with certified large-scale farms commanding 8-12% discounts over spot-trading horticulture retailers. Cost compression in bagged urea distribution is intensifying because sovereign-backed entities are consolidating procurement through direct manufacturer relationships. Smallholder horticulture producers in Saudi Arabia's Tabuk region exhibit highest price sensitivity, while Qatar's Al Khor greenhouse operators accept premium foliar formulation pricing for technical service bundling.
Supply Chain Analysis
Red Sea container congestion and Jebel Ali port availability constraints are elevating inbound logistics costs for Canadian and Belarusian potash shipments. Geographic supply concentrates in Saudi Arabia for nitrogenous output, Morocco and Jordan for phosphate rock alternatives, and Canada-Belarus for potassium chloride. Raw material dependencies rest on natural gas feedstock, phosphate ore, and polymer coating chemicals. Single-source vulnerability at Ma'aden's Waad Al-Shamal complex creates structural risk for GCC phosphatic manufacturing. Distribution runs through direct bulk shipments to sovereign farming entities, bypassing traditional Jeddah and Dammam trading houses for annual contract volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-release coating chemistry adoption across Saudi cereal operations signals early-cycle expansion, with polymer-encapsulated nitrogen penetration at 15-20% annual velocity creating sustained formulation upgrade demand.
For Market Incumbents: Compound defensive positions by securing backward integration into polymer coating supply and accelerating liquid fertilizer terminal investments at Dammam and Jebel Ali before distributor balance sheets recover. ISO 14001 audit capacity scarcity among smaller trading houses threatens channel control for SABIC Agri-Nutrients and Qatar Fertilizer Company direct agreements. Capacity addition in Oman's Salalah coastal zone offers first-mover positioning before domestic blending consolidates. For New Entrants and Emerging Players: Drone application service layers represent the most penetrable white-space target, as incumbent suppliers remain product-centric while Saudi cereal belt operators seek variable-rate aerial spreading contracts. Underpenetrated sesame and sunflower cultivation in Oman's Batinah plain offers NPK blend entry before farmer associations aggregate demand. Digital procurement portals for greenhouse operators with temperature-monitoring logistics integration provide a defensible go-to-market angle against traditional trading houses. For Investors and Strategic Acquirers: SASO's tightening cadmium and arsenic thresholds reshape the acquisition landscape by filtering non-compliant import competitors and securing captive offtake for domestic phosphate processing assets. Long-term viability centers on water-energy-food nexus policy alignment across the projection horizon. Acquisition target archetypes include compound fertilizer blenders with precision agriculture calibration capabilities and biofertilizer-integrated formulation specialists serving Al-Ahsa date palm export certification. The signal to watch is reclaimed water irrigation mandate expansion across UAE emirate-level jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Coating Supply | SABIC Agri-Nutrients secures controlled-release urea margin pools against specialty importers. |
| Liquid Fertilizer Terminal Expansion | Desalination-integrated storage at Dammam port captures reclaimed water irrigation demand from Al Ain alfalfa producers. |
| Biofertilizer Convergence R&D | Emirates Bio Fertilizer Factory combines microbial inoculants with synthetic nutrients for Al-Ahsa organic date certification. |
| Drone Application Service Contracts | Variable-rate aerial spreading across Tabuk cereal operations creates recurring revenue beyond product-only sales. |
| ISO 14001 Certification Investment | Qatar Fertilizer Company filters distributor access while commanding price premiums from compliant offtakers. |
Research Methodology
Desk research of customs trade data, SASO regulatory filings, and GCC agricultural ministry irrigation development plans preceded structured interviews with SABIC Agri-Nutrients procurement directors, Ma'aden Waad Al-Shamal complex operations managers, UAE Ministry of Climate Change and Environment agricultural input licensing officers, Qatar Fertilizer Company ammonia derivative traders, and Omani farmer association cooperative leaders. Secondary validation drew from FAO fertilizer consumption databases, Gulf Petrochemicals and Chemicals Association capacity reports, and Red Sea shipping lane congestion indices. Bottom-up demand modeling across crop systems and top-down supply verification through production complex disclosures were triangulated for cross-validation.
Variance decomposition across fertilizer type, application method, end-user scale, and distribution channel segments structured the analytical framework over the projection horizon. CAGRs were derived from segmented volume build-ups calibrated to national food security program targets and irrigation infrastructure deployment schedules. Industry-specific forecast inputs included reclaimed water mandate implementation timelines and SASO heavy metal threshold enforcement phases.
Forecasts assume regulatory continuity in SASO fertilizer registration regimes and UAE Ministry of Climate Change and Environment licensing frameworks; material policy shifts would require re-modeling. Commodity price volatility in natural gas feedstock and Red Sea shipping disruptions represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
India Urea Market
Fertilizers
Potassium Thiosulfate Fertilizer Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Organic Fertilizers Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Potash Market