
 Asia-Pacific Ruminant Feed Market | 2026-2036
Asia-Pacific Ruminant Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ruminant Feed Market Outlook
The gap between premium compound feeds and commodity roughage is broadening across Asia-Pacific ruminant operations. Charoen Pokphand Foods leverages integrated aquaculture-livestock supply chains to control input costs for dairy customers. New Hope Group anchors its position through captive corn processing and regional distribution density in China. Alltech Inc. differentiates via yeast-based additive portfolios that target mycotoxin management in tropical storage conditions.
Asia-Pacific ruminant feed encompasses formulated mixtures of roughage, concentrates, protein meals, minerals, and additives designed to meet the nutritional requirements of cattle, buffalo, sheep, and goats for meat or milk production. Typical formulations specify crude protein between 14% and 22% and metabolizable energy ranging from 2.5 to 3.0 Mcal per kilogram, with pelleting or mash processing determining palatability and feed conversion efficiency. Dietary Supplements command margin pools where trace mineral and rumen modifier premixes address productivity gaps in smallholder herds. Protein Sources face structural pressure as soybean meal import dependence in India and Southeast Asia exposes buyers to price volatility and currency risk. Feed Additives represent the fastest-growing product dimension as probiotic and enzyme inclusion rates rise in response to antibiotic reduction mandates across multiple Asia-Pacific jurisdictions.
India's FSSAI feed safety guidelines, China's SAMR GB standards, and Australia's APVMA chemical residue limits collectively shape product registration timelines and cross-border trade eligibility for compound feed suppliers. Compliance with these frameworks determines market access for imported premixes and dictates reformulation investments by domestic manufacturers. Stakeholders must track how carbon accounting rules and methane mitigation protocols reshape ingredient sourcing decisions and customer procurement criteria across the region.
Market Dynamics
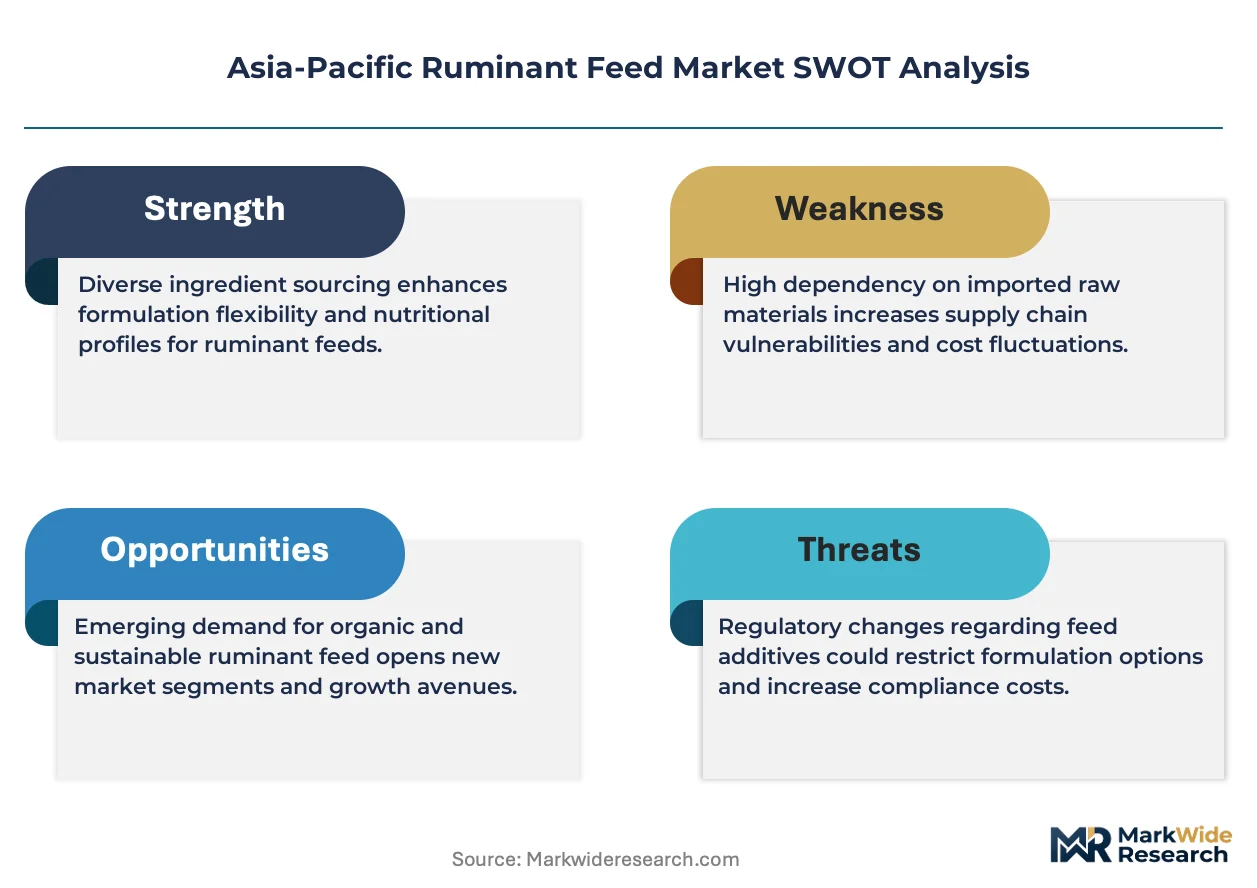
India's PLI scheme for animal husbandry and China's GB standards for feed safety are forcing simultaneous reformulation investments across Asia-Pacific ruminant feed manufacturers. Dairy cooperatives in Southeast Asia now mandate compound feed specifications that exceed national minimums, compressing margins for suppliers unable to upgrade premix capabilities.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive framework for animal husbandry subsidizes feed mill modernization, accelerating commercial compound feed adoption in Gujarat and Maharashtra dairy belts.
- Antibiotic reduction mandates:Multiple Asia-Pacific jurisdictions now prohibit growth-promoting antibiotics, pulling probiotic and enzyme inclusion rates upward in cattle and buffalo rations.
- Cooperative quality benchmarks:Milk cooperatives across Vietnam, Thailand, and Indonesia raise protein and energy specifications, forcing smallholder transitions from commodity roughage to formulated concentrates.
Market Restraints
- Soybean meal import dependence:India and Southeast Asia rely on imported oilseed meals, exposing feed manufacturers to currency volatility and port logistics disruptions.
- Captive corn processing concentration:China's New Hope Group and similar integrated players control regional grain supply, limiting independent feed mill input cost flexibility.
- Tropical mycotoxin loads:Aflatoxin and fumonisin contamination in humid storage conditions forces additive expenditure that commodity roughage alternatives avoid.
Strategic Opportunities
- Vietnam dairy expansion:Vinamilk and TH True Milk are scaling commercial herd sizes in Nghe An and Thanh Hoa provinces, creating demand for total mixed ration formulations.
- Precision fermentation proteins:Microbial and algae-derived protein meals are integrating into ruminant premixes as soy displacement strategies for cost-sensitive operators.
- SAMR GB standard harmonization:China's feed safety framework is becoming the de facto regional reference, enabling cross-border premix registration efficiencies for compliant suppliers.
Industry Challenges
- Rumen microbiology expertise scarcity:Formulation of effective probiotic and yeast-based additives requires specialized veterinary nutritionists that regional universities produce insufficiently.
- Carbon accounting verification:Methane mitigation protocols demand feed-to-farm data integration that legacy smallholder record systems cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ruminant Feed Market |
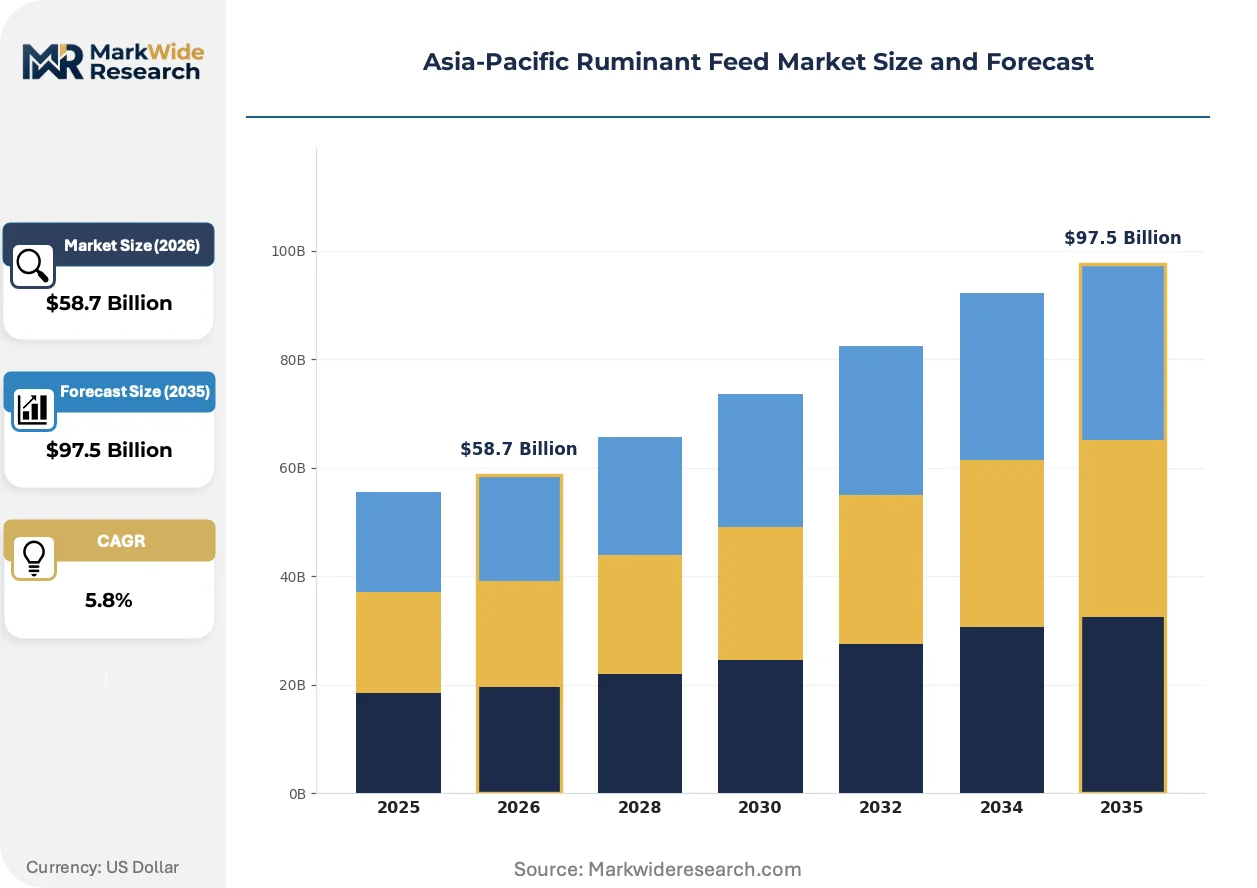
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Protein Sources, Feed Additives, Vitamins End User: Dairy Farmers, Commercial Livestock, Feed Manufacturers, Animal Nutritionists Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Agricultural Cooperatives Packaging Type: Bags, Bulk Containers, Sacks, Pouches |
| Companies Covered | Charoen Pokphand Foods, New Hope Group, Cargill Inc., Alltech Inc., Archer Daniels Midland, Godrej Agrovet, Land O'Lakes Inc., Adisseo SAS, Trouw Nutrition, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ruminant Feed Market Strategic Shifts
Yeast-based additive portfolios and precision fermentation proteins are displacing conventional antibiotic growth promoters across Asia-Pacific ruminant nutrition. Digital feed formulation tools and blockchain traceability systems are compressing procurement cycles for commercial dairy operations.
Direct-fed microbials incorporating Saccharomyces cerevisiae and Aspergillus oryzae fermentation products are integrating into tropical climate formulations to stabilize rumen pH and improve fiber digestibility. Large dairy cooperatives in India and Vietnam are adopting these additives at scale to meet export milk quality specifications. The technology is integrating mycotoxin binding and rumen modifier functions into single-premix offerings that reduce inventory complexity for feed mills.
China's SAMR GB 13078 feed hygiene standards and India's FSSAI feed safety guidelines are tightening maximum residue limits for heavy metals and aflatoxins. Domestic manufacturers must reformulate mineral premixes and source certified low-toxin grain lots to maintain product registration. Small and mid-sized feed mills in Indonesia and the Philippines face the steepest compliance costs as they lack in-house testing laboratories.
Commercial livestock operations are consolidating procurement through cooperative buying platforms that bypass traditional distributor markups. Dairy farmers in Maharashtra and Karnataka now aggregate compound feed orders through digital marketplaces linked directly to mill scheduling systems. This channel compression is most visible in India, where milk cooperative density enables volume-based pricing negotiations previously unavailable to fragmented smallholders.
Asia-Pacific Ruminant Feed Market Segmentation
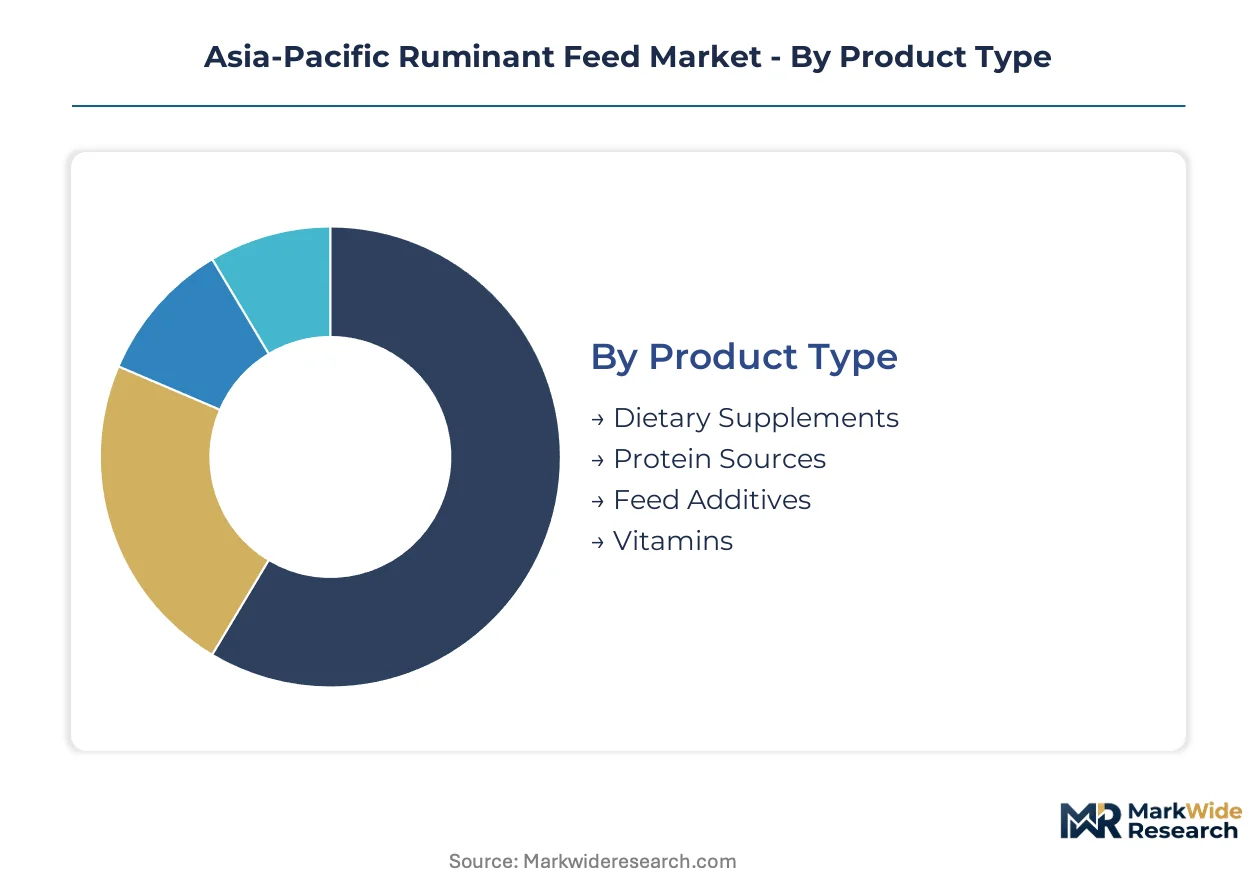
Segmentation in Asia-Pacific ruminant feed reveals how regulatory compliance burdens concentrate in specific product categories while distribution channels reshape procurement economics for commercial dairy operations. Understanding these divides exposes where formulation investments yield registration advantages versus where logistics efficiency determines margin capture.
Product Type:
India's FSSAI feed safety guidelines and China's SAMR GB standards impose tiered certification requirements across product categories, with mycotoxin binding and residue testing protocols varying by segment complexity.
- Dietary Supplements:Trace mineral and rumen modifier premixes address productivity gaps in smallholder herds across Gujarat and Maharashtra dairy belts. Demand concentrates where milk cooperatives mandate mineral fortification exceeding national minimums, forcing reformulation investments by domestic manufacturers.
- Feed Additives:Probiotic and enzyme inclusion rates rise in response to antibiotic reduction mandates across multiple Asia-Pacific jurisdictions. Yeast-based portfolios incorporating Saccharomyces cerevisiae fermentation products integrate mycotoxin binding and rumen modifier functions into single-premix offerings that reduce inventory complexity for feed mills.
- Protein Sources:Soybean meal import dependence in India and Southeast Asia exposes buyers to currency volatility and port logistics disruptions.
- Vitamins:Fat-soluble and water-soluble premixes require stability testing under tropical humidity conditions per FSSAI and SAMR protocols.
Feed Additives sits at the top of the volume ranking, with Dietary Supplements climbing the fastest.
End User:
Customer type determines specification stringency and order aggregation scale, with cooperative-linked operations commanding volume-based pricing unavailable to fragmented smallholders.
- Dairy Farmers:Commercial operations in Vietnam's Nghe An and Thanh Hoa provinces scale total mixed ration formulations as Vinamilk and TH True Milk expand herd sizes.
- Commercial Livestock:Professional procurement through digital marketplaces in Maharashtra and Karnataka aggregates compound feed orders directly to mill scheduling systems, compressing distributor markups.
- Feed Manufacturers:Captive corn processing by integrated players limits independent mill input cost flexibility across China's regional distribution networks.
- Animal Nutritionists:Specialized formulation expertise scarcity constrains probiotic and yeast-based additive development for regional universities.
Commercial Livestock captures the largest order values, with Dairy Farmers expanding most quickly through cooperative density.
Distribution Channel:
Channel selection dictates working capital requirements and traceability system investments, with blockchain-enabled platforms gaining traction among export-oriented cooperatives.
- Agricultural Cooperatives:Milk cooperatives across Vietnam, Thailand, and Indonesia raise protein and energy specifications, forcing smallholder transitions from commodity roughage to formulated concentrates. Cooperative buying platforms bypass traditional distributor markups through volume-based pricing negotiations.
- Direct Sales:Feed mill scheduling systems link directly to dairy farmer digital marketplaces in India's highest-density cooperative regions, compressing procurement cycles.
- Retail Stores:Independent smallholders in Indonesia and the Philippines rely on counter sales where in-house testing laboratory investments are prohibitive.
- Online Platforms:E-commerce penetration remains limited by smallholder digital literacy gaps and payment system fragmentation.
Agricultural Cooperatives holds the dominant channel share, with Direct Sales gaining share fastest through mill-to-farmer platform integration.
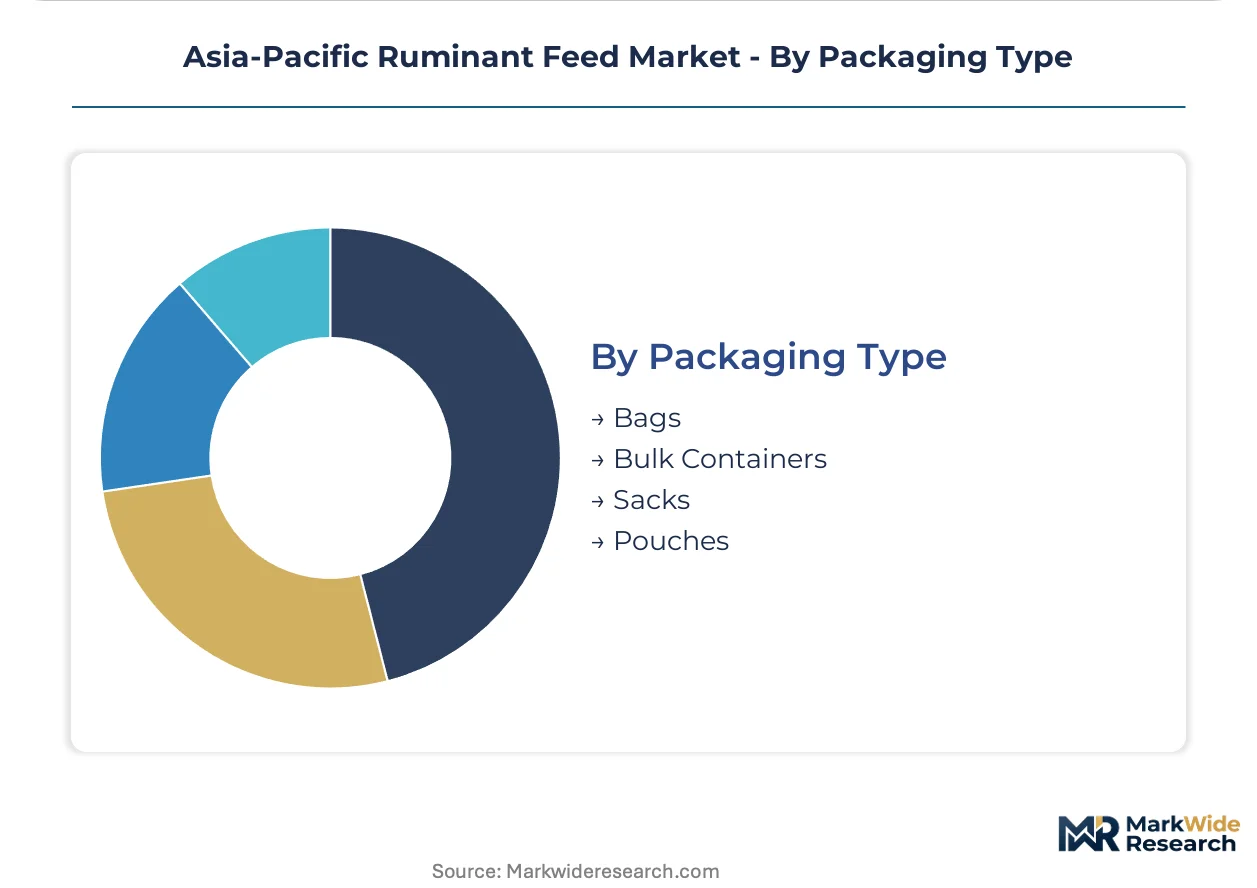
Packaging Type:
Packaging economics track operation scale and storage infrastructure quality, with tropical humidity driving moisture-barrier specifications.
- Bulk Containers:Commercial livestock operations with silo infrastructure capture per-kilogram cost advantages through tanker delivery and pneumatic unloading systems.
- Bags:25-50kg woven polypropylene dominates smallholder procurement in India's dairy belts, requiring aflatoxin-resistant liners per FSSAI guidelines.
- Sacks:Jute and paper-based alternatives face displacement where moisture protection standards tighten under SAMR GB 13078 feed hygiene protocols.
- Pouches:Premix and additive sachets serve precision-fed microbials requiring dosage accuracy for probiotic viability maintenance.
Bags sits at the top of the volume ranking, with Bulk Containers climbing the fastest as commercial herd consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary nutritionists and feed formulation specialists cluster in India's Gujarat and Maharashtra dairy belts, China's Yangtze River Delta feed manufacturing hubs, and Vietnam's emerging Nghe An commercial dairy corridor.
India
Dairy cooperatives in Gujarat and Maharashtra mandate protein and energy specifications exceeding national minimums, forcing smallholder transitions to formulated concentrates. The PLI scheme for animal husbandry subsidizes feed mill modernization, accelerating commercial compound feed adoption. Anand and Pune anchor procurement density where milk cooperative volume enables direct mill-to-farmer platform integration.
China
Captive corn processing by integrated players limits independent mill input cost flexibility across regional distribution networks. SAMR GB 13078 feed hygiene standards tighten maximum residue limits for heavy metals and aflatoxins, forcing mineral premix reformulation. Shandong Peninsula and Yangtze River Delta concentrate manufacturing capacity where New Hope Group anchors upstream grain supply control.
Vietnam
Vinamilk and TH True Milk scale commercial herd sizes in Nghe An and Thanh Hoa provinces, creating demand for total mixed ration formulations. Antibiotic reduction mandates pull probiotic and enzyme inclusion rates upward in cattle and buffalo rations. The Red River Delta dairy corridor professionalizes procurement through cooperative buying platforms that compress distributor markups.
Thailand
Charoen Pokphand Foods leverages integrated aquaculture-livestock supply chains to control input costs for dairy customers across the Central Plains. Tropical mycotoxin loads force additive expenditure that commodity roughage alternatives avoid. Bangkok metropolitan feed mills serve as distribution nodes for northeastern commercial beef operations expanding into formulated concentrate adoption.
Indonesia
Small and mid-sized feed mills face steep compliance costs as they lack in-house testing laboratories for FSSAI-equivalent safety protocols. Soybean meal import dependence exposes manufacturers to currency volatility and port logistics disruptions. Java's dairy belts concentrate demand where milk cooperatives raise quality benchmarks, compressing margins for suppliers unable to upgrade premix capabilities.
Asia-Pacific Ruminant Feed Market Competitive Environment
Capital-heavy producers compete with asset-light designers across Asia-Pacific ruminant feed manufacturing. Integrated agribusinesses with captive grain processing anchor volume positions while independent premix specialists capture margin pools in additive-intensive formulations. Three archetypes dominate: diversified Asian conglomerates with upstream supply control, global nutrition companies with yeast-based biotechnology portfolios, and regional feed mills with cooperative-linked distribution density. Competitive moves concentrate on backward integration into grain origination and strategic partnerships with dairy cooperatives for procurement platform access.
Among diversified Asian conglomerates, Charoen Pokphand Foods and New Hope Group exemplify upstream supply control strategies that limit independent competitor input cost flexibility. Alltech Inc. occupies a position within the biotechnology-specialist archetype, representing yeast-based additive development targeting tropical mycotoxin management. These three companies anchor the competitive structure: Thai and Chinese integrated players control regional grain flows while the Kentucky-based nutrition company differentiates through fermentation-derived rumen modifier portfolios.
| Leading Market Players |
|---|
| Charoen Pokphand Foods |
| New Hope Group |
| Cargill Inc. |
| Alltech Inc. |
| Archer Daniels Midland |
| Godrej Agrovet |
| Land O'Lakes Inc. |
| Adisseo SAS |
| Trouw Nutrition |
| Others |
Value Chain & Pricing Dynamics
Precision fermentation protein integration into ruminant premixes is compressing ingredient cost structures while concentrating procurement leverage among feed mills with captive biotechnology partnerships. This production-method transition simultaneously reshapes supplier economics and pricing power distribution across India's Gujarat dairy belt and China's Yangtze River Delta manufacturing hubs.
Pricing Analysis
Bundled premix-additive formulations versus unbundled commodity ingredient sourcing defines the pricing architecture across Asia-Pacific ruminant feed. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under China's SAMR GB standards and volume scale through cooperative procurement platforms. Pricing pressure stems from soybean meal import dependence exposing Indian and Southeast Asian mills to currency volatility. Smallholder dairy farmers in Indonesia and the Philippines exhibit highest price sensitivity, while export-oriented cooperatives in Vietnam's Nghe An province absorb premium tier costs for quality compliance.
Supply Chain Analysis
Veterinary nutritionist and specialized formulation chemist scarcity in Vietnam's emerging dairy corridor and Indonesia's Java belt constrains production scale-up for probiotic-intensive feed lines. Geographic supply concentration centers on China's Shandong Peninsula for corn processing, India's Maharashtra-Gujarat cluster for dairy feed demand, and Thailand's Central Plains for integrated aquaculture-livestock operations. Raw material dependencies include Brazilian and Argentine soybean meal, Ukrainian and Australian wheat, and regionally sourced corn. Single-source vulnerability runs through China's captive grain processing networks. Distribution runs through agricultural cooperatives and direct mill-to-farmer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's SAMR GB 13078 feed hygiene standards and India's FSSAI guidelines are accelerating reformulation investments and consolidating procurement toward compliant suppliers.
For Market Incumbents: Extend backward integration into certified low-toxin grain origination to defend against independent premix specialists capturing additive margin pools. Add in-house mycotoxin testing laboratory capacity in Indonesia and the Philippines where compliance cost barriers are highest. Scale cooperative-linked digital procurement platforms in India's Maharashtra dairy belt to lock in volume-based pricing negotiations before channel compression accelerates. For New Entrants and Emerging Players: Dairy cooperative technical advisory partnerships offer the most penetrable channel for precision fermentation protein and direct-fed microbial introductions in Vietnam's Thanh Hoa province. Target small and mid-sized feed mills in Indonesia lacking SAMR-equivalent testing infrastructure with outsourced certification and premix formulation services. White-space exists in carbon accounting verification tools for methane mitigation protocols where legacy smallholder record systems fail. For Investors and Strategic Acquirers: Valuations sit cheapest among regional feed mills with cooperative distribution density but lacking captive grain supply or additive R&D capabilities. Long-term viability over the projection horizon hinges on regulatory compliance automation and biotechnology portfolio depth. Watch probiotic inclusion rate mandates across multiple Asia-Pacific jurisdictions as the inflection signal for additive-intensive formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Captive corn supply insulates New Hope Group and similar integrated players from port logistics disruptions. |
| Yeast-Based Additive Portfolio Expansion | Saccharomyces cerevisiae fermentation products differentiate Alltech Inc. in tropical mycotoxin management. |
| Cooperative Procurement Platform Development | Direct mill-to-farmer digital marketplaces in Maharashtra compress distributor markups for Charoen Pokphand Foods. |
| Precision Fermentation Protein Integration | Microbial and algae-derived meals displace soy in cost-sensitive operator formulations across Vietnam. |
| In-House Mycotoxin Testing Laboratory Investment | SAMR GB 13078 compliance costs force consolidation among Indonesian mills lacking certification infrastructure. |
Study Parameters
Multiple input streams — structured interviews with feed mill operations directors, dairy cooperative procurement managers, and veterinary nutritionists; secondary validation through China's SAMR GB standard filings, India's FSSAI guideline updates, and regional trade customs data; plus proprietary production database reconciliation — were synthesized through bottom-up and top-down triangulation. Primary fieldwork captured formulation practices, procurement platform adoption, and compliance investment patterns across the Asia-Pacific ruminant feed value chain. Secondary sources included national agricultural ministry statistics, cooperative annual reports, and feed additive registration databases.
Data-stream reconciliation anchored volume and value outputs across product type, end user, distribution channel, and packaging type segmentation dimensions. CAGRs were derived through trend extrapolation moderated by regulatory milestone timing and technology adoption curve analysis. Industry-specific forecast inputs incorporated PLI scheme disbursement trajectories in India, antibiotic reduction mandate implementation schedules across multiple jurisdictions, and precision fermentation protein cost reduction curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to currency volatility in soybean meal import markets and SAMR GB standard harmonization pace across Southeast Asia. Forecasts reflect documented assumptions regarding cooperative consolidation rates and biotechnology partnership formation. Material deviation in PLI scheme funding continuity or mycotoxin contamination severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Premix Market
Agricultural Commodities
Alfalfa Powder Market
Agricultural Commodities
Europe Feed Amino Acids Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Middle East Feed Amino Acids Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Europe Ruminant Feed Market