
 Cottonseed Meal Market | 2026-2036
Cottonseed Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Cottonseed Meal Market Insights
The gap between premium decorticated grades and standard non-decorticated cottonseed meal is collapsing as protein content specifications tighten across commercial feed contracts. Cargill leverages its North American cottonseed processing network to sustain supply continuity for dairy nutrition customers. Archer Daniels Midland anchors its position through backward integration into cotton ginning operations across the US Southeast. Bunge competes on volume scale in Brazilian export channels where it controls port logistics for meal shipments.
Cottonseed meal is the residual solid remaining after cottonseed oil extraction, typically containing 38-48% crude protein and variable gossypol levels depending on decortication extent and processing method; it serves primarily as a protein supplement in formulated animal feeds where amino acid profiles and toxin thresholds dictate inclusion rates. Decorticated cottonseed meal dominates value capture in ruminant feed applications where higher protein density justifies price premiums over non-decorticated alternatives. Aquaculture feed represents the fastest-growing application segment as shrimp and finfish producers test expanded inclusion rates to offset fishmeal dependency. Refined cottonseed meal occupies a narrow but profitable niche in pet food manufacturing where low-gossypol specifications command formulation premiums.
USDA grading standards and FDA feed safety rules govern allowable gossypol thresholds in interstate commerce, while the EU Feed Hygiene Regulation imposes contaminant limits that filter which processing origins qualify for European import. India's FSSAI and BIS frameworks apply parallel constraints on domestic meal destined for food-adjacent applications such as organic fertilizer streams. Stakeholders must monitor evolving mycotoxin testing protocols and sustainability certification requirements that increasingly determine market access rather than commodity pricing alone.
Market Dynamics
The EU Feed Hygiene Regulation is compressing import pathways for non-EU oilseed meals, forcing processors to revalidate extraction methods and contaminant protocols before European port entry. This regulatory pressure cascades through pricing structures and supplier qualification timelines across the value chain.
Growth Catalysts
- Aquaculture Feed Expansion:Shrimp producers in Southeast Asia are testing elevated cottonseed meal inclusion rates to reduce fishmeal dependency in formulated diets.
- Brazilian Dairy Expansion:Cattle operations in Mato Grosso and Goiás states are increasing cottonseed meal rations as soybean meal prices fluctuate.
- REACH Compliance Adaptation:European crushers investing in solvent extraction upgrades are capturing premium positioning for EU-certified meal shipments.
Market Restraints
- Gossypol Toxicity Thresholds:FDA feed safety rules limit inclusion rates in monogastric feeds, capping addressable market size for standard-grade meal.
- Cotton Lint Price Volatility:Ginning economics favor fiber recovery over seed crushing when lint prices spike, constraining meal supply.
- Soybean Meal Substitution:Higher-protein soybean meal dominates commercial feed formulation, displacing cottonseed meal in price-sensitive contracts.
Strategic Opportunities
- Pet Food Premiumization:Low-gossypol refined grades command formulation premiums in premium dog and cat food segments.
- Indian State-Level Integration:Gujarat and Maharashtra ginneries with captive crushing capacity offer procurement consolidation opportunities.
- Organic Fertilizer Streams:FSSAI-permitted meal diversion into organic fertilizer production opens non-feed revenue channels.
Industry Challenges
- Decortication Skill Shortages:Operating high-efficiency dehulling equipment requires specialized mechanical training that remains scarce in processing regions.
- Mycotoxin Certification Timelines:EU port authorities are extending testing protocols for aflatoxin and fumonisin, delaying customs clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cottonseed Meal Market |
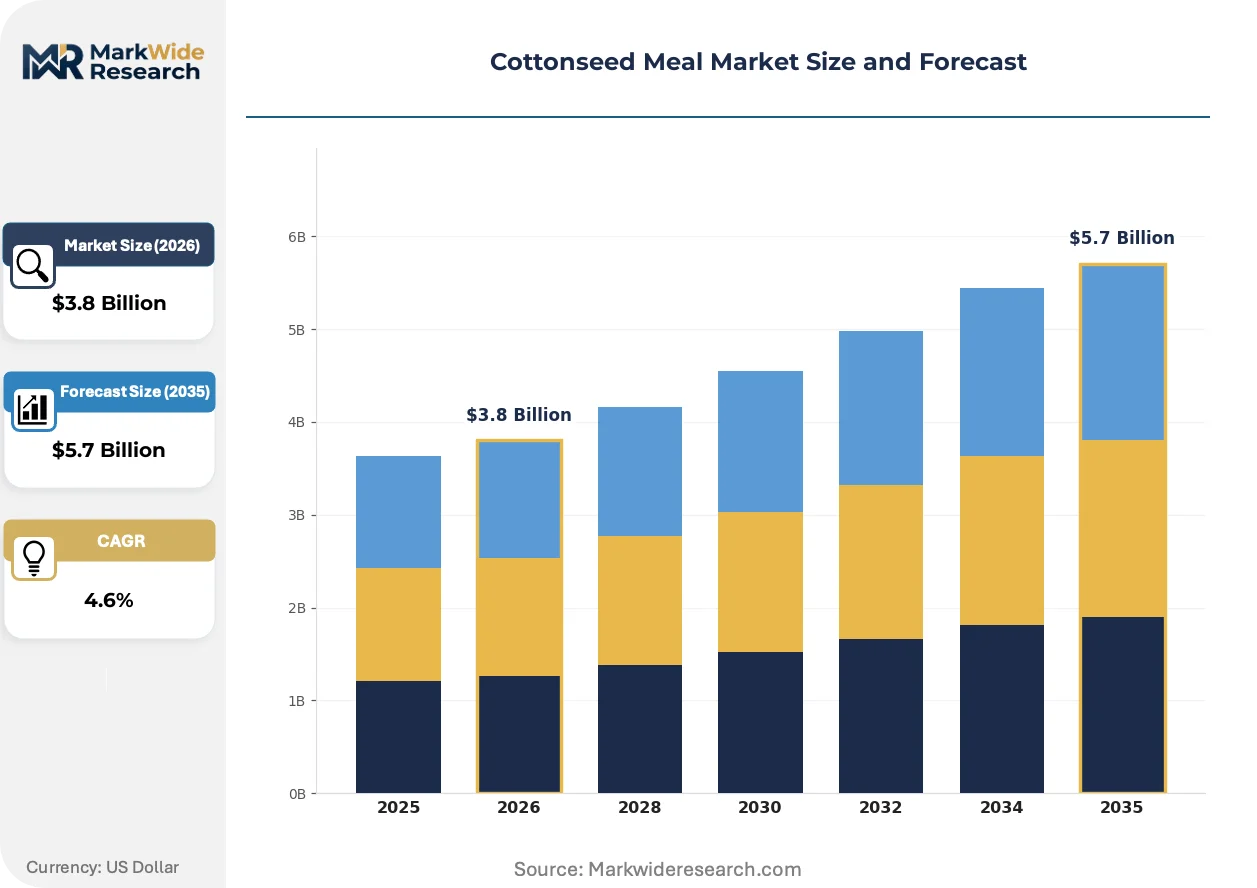
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorticated Cottonseed Meal, Non-Decorticated Cottonseed Meal, Cottonseed Expeller Meal, Refined Cottonseed Meal Application: Ruminant Feed, Poultry Feed, Aquaculture Feed, Pet Food End User Industry: Livestock Farming, Aquaculture Operations, Pet Food Manufacturing, Organic Farming Packaging Type: Bulk Bags, Paper Bags, Polypropylene Bags, Loose Form |
| Companies Covered | Cargill, Archer Daniels Midland, Bunge, Louis Dreyfus Company, Wilmar International, Olam International, Yihai Kerry Arawana Holdings, Richardson International, Zouping Fuhai Weiye Oil & Fat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cottonseed Meal Market Trends and Innovations
Solvent extraction technology is fragmenting competitive positioning in cottonseed processing. Advanced mechanical pressing methods are gaining traction among mid-scale operators seeking lower capex intensity. These shifts are compressing margins for legacy hexane-based facilities while opening formulation-grade supply from non-traditional origins.
Expeller-pressed cottonseed meal is fragmenting the premium protein segment as dairies seek bypass protein characteristics. Northeast US dairy nutritionists are specifying expeller-processed meal for rumen-undegradable protein advantages. This mechanical processing revival is enabling regional crushers to compete against solvent-extracted imports on nutritional specifications rather than price alone.
REACH substance registration requirements are reshaping import compliance for oilseed meals entering Rotterdam and Hamburg. European feed compounders now demand full supply chain documentation from non-EU crushers. Brazilian and Indian exporters are responding by investing in third-party certification audits and batch-level traceability systems.
Consolidated procurement by integrated poultry integrators is compressing spot market liquidity for cottonseed meal. Large US broiler producers are negotiating direct supply agreements with cotton ginneries, bypassing traditional merchant channels. This channel shift is most visible in the Southeast where Tyson and Pilgrim's Pride operations dominate feed demand.
Cottonseed Meal Market Segmentation
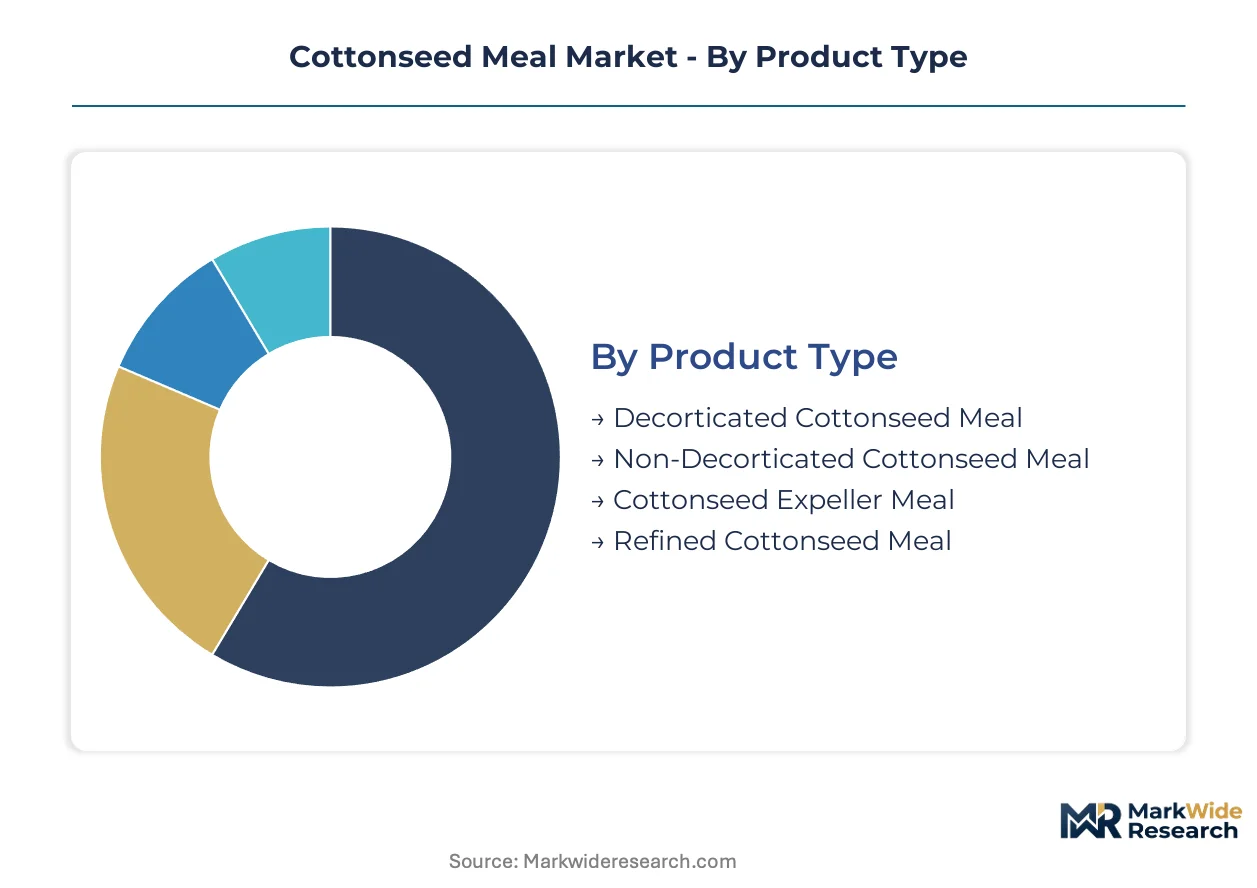
Product differentiation in cottonseed meal hinges on protein density and gossypol content, with each grade commanding distinct price positions across feed formulation tiers. Processors must align output specifications with end-use toxicity thresholds and nutritional density requirements to secure contract placement.
Product Type:
Decorticated grades face acute substitution pressure from soybean meal in high-protein ruminant formulations, while expeller-processed variants carve defensible niches through bypass protein characteristics.
- Decorticated Cottonseed Meal:Higher protein density at 44-48% crude protein content commands premium positioning in dairy cattle rations. Demand concentrates in Brazil's Mato Grosso dairy belt where nutritionists specify decorticated grades for amino acid optimization in total mixed rations.
- Non-Decorticated Cottonseed Meal:Standard 38-42% protein content with hull fragments intact serves price-sensitive poultry and swine operations. Feed compounders in India's Maharashtra state blend non-decorticated meal with soybean meal to manage formulation costs amid volatile oilseed prices.
- Cottonseed Expeller Meal:Mechanical pressing preserves rumen-undegradable protein advantages for high-producing dairy herds. Northeast US nutritionists specify expeller meal for bypass protein benefits in early lactation diets.
- Refined Cottonseed Meal:Low-gossypol processing through advanced solvent extraction meets pet food safety thresholds. Premium dog and cat food manufacturers in the EU source refined grades for hypoallergenic formulations.
Non-decorticated cottonseed meal anchors the volume base while refined cottonseed meal gains share at the steepest rate.
Application:
Feed application segments diverge sharply by species-specific gossypol tolerance, with monogastric constraints capping addressable market depth for standard-grade output.
- Ruminant Feed:Cattle rumen microflora detoxify free gossypol, enabling inclusion rates up to 15% of dry matter in dairy rations. Brazilian operations in Goiás state are expanding cottonseed meal rations as soybean meal import costs fluctuate.
- Poultry Feed:Broiler and layer operations limit inclusion to 3-5% due to monogastric toxicity thresholds, constraining volume capture. Large US integrators in the Southeast negotiate direct supply agreements with ginneries to secure contract pricing.
- Aquaculture Feed:Shrimp producers in Southeast Asia test expanded inclusion rates to offset fishmeal dependency in formulated diets. Finfish trials demonstrate acceptable growth performance at moderate substitution levels.
- Pet Food:Low-gossypol specifications command formulation premiums in premium dog and cat food segments. EU compounders demand full supply chain documentation under REACH substance registration requirements.
Ruminant feed absorbs the dominant volume share while aquaculture feed expands most quickly as fishmeal substitution accelerates.
End User Industry:
Customer concentration patterns follow livestock density maps, with integrated operations displacing merchant channels through direct procurement restructuring.
- Livestock Farming:Dairy and beef cattle operations represent the foundational demand base for standard and decorticated grades. Consolidated feed procurement by Tyson and Pilgrim's Pride in the US Southeast compresses spot market liquidity.
- Aquaculture Operations:Shrimp farming clusters in Vietnam and Thailand drive specification innovation for high-inclusion diets. Feed millers conduct controlled trials to validate performance against marine protein benchmarks.
- Pet Food Manufacturing:Premium brands specify refined low-gossypol grades for hypoallergenic and limited-ingredient product lines. Third-party certification audits verify batch-level traceability for EU export compliance.
- Organic Farming:FSSAI-permitted meal diversion into organic fertilizer production opens non-feed revenue channels in Gujarat and Maharashtra. Soil amendment applications leverage cottonseed meal's nitrogen content and slow-release characteristics.
Livestock farming retains the volume anchor position while aquaculture operations climb the fastest as marine protein substitution intensifies.
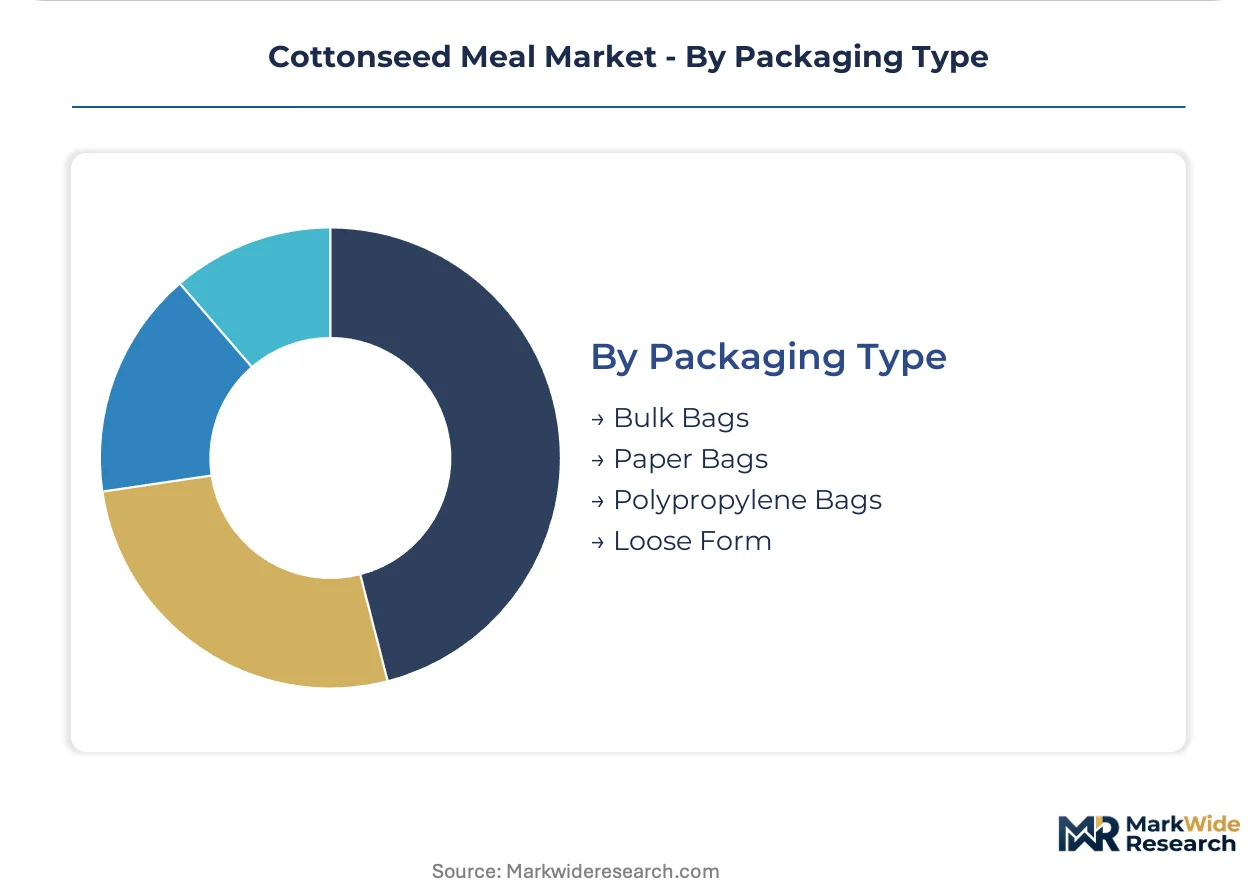
Packaging Type:
Packaging economics track shipment distance and customer scale, with bulk formats dominating export corridors and bagged units serving fragmented domestic distribution.
- Bulk Bags:One-ton flexible intermediate bulk containers minimize handling costs for integrated feed mills and large dairy operations. Port logistics in Brazilian export channels favor bulk formats for ocean freight efficiency.
- Paper Bags:Kraft multiwall construction suits retail-scale organic fertilizer distribution and small livestock operations. Environmental compliance with EU packaging waste directives shapes material selection.
- Polypropylene Bags:Woven PP resists moisture intrusion during monsoon season storage in Indian processing regions. Gujarat ginneries specify laminated PP for extended shelf life in humid climates.
- Loose Form:Direct pneumatic discharge into feed mill receiving hogs eliminates packaging overhead for captive crushing facilities. Captive operations in Maharashtra state bypass merchant channels entirely.
Bulk bags dominate export volume while loose form gains fastest adoption among integrated processor-mill networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity clusters where cotton cultivation density intersects with oilseed crushing infrastructure. Ginning economics in major producing regions directly determine meal supply availability and quality grading distribution.
United States
Southeast cotton ginneries supply captive crushing facilities across Georgia and Alabama. USDA grading standards and FDA feed safety rules govern interstate commerce of oilseed meals. Dairy nutritionists in the Northeast specify expeller-processed meal for rumen-undegradable protein advantages in early lactation diets.
Brazil
Cattle operations in Mato Grosso and Goiás states expand cottonseed meal rations as soybean meal import costs fluctuate. ANVISA and MAPA regulations shape feed safety compliance for domestic and export channels. Port logistics in Santos and Paranaguá favor bulk formats for ocean freight efficiency to Asian markets.
India
Integrated cotton ginneries in Gujarat and Maharashtra states supply captive crushing facilities with direct pneumatic discharge into feed mill networks. FSSAI and BIS frameworks constrain domestic meal destined for food-adjacent organic fertilizer applications. Soil amendment demand in these western states leverages cottonseed meal's nitrogen content and slow-release characteristics.
China
Yihai Kerry Arawana Holdings anchors processing capacity in major cotton-producing provinces. NMPA and MIIT standards govern oilseed meal quality specifications for feed and food-adjacent applications. Crushing clusters in Xinjiang and the Yellow River Delta integrate ginning operations with solvent extraction facilities.
European Union
REACH substance registration requirements and EFSA feed hygiene rules filter import eligibility for oilseed meals entering Rotterdam and Hamburg. Compounders demand full supply chain documentation from non-EU crushers. Dutch and German feed manufacturers source certified meal through third-party audit verification and batch-level traceability systems.
Cottonseed Meal Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the cottonseed meal value chain. The market structure consolidates around integrated agribusiness conglomerates with backward control over ginning networks and regional specialists leveraging proximity to cultivation belts. Three archetypes dominate: multinational traders with port logistics dominance, integrated processors with captive cottonseed supply, and regional crushers competing on nutritional specifications. Competitive moves concentrate on direct procurement restructuring with large livestock integrators and solvent extraction upgrades for EU-certified export positioning.
Among the integrated agribusiness tier, Cargill, Archer Daniels Midland, and Bunge exemplify scale-driven positioning through North American processing networks and Brazilian export channel control. These entities anchor supply continuity for dairy nutrition customers and sustain volume leadership in ocean freight corridors. Regional specialists occupy complementary positions through mechanical processing methods and rumen-undegradable protein specialization for high-producing dairy herds.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Bunge |
| Louis Dreyfus Company |
| Wilmar International |
| Olam International |
| Yihai Kerry Arawana Holdings |
| Richardson International |
| Zouping Fuhai Weiye Oil & Fat |
| Others |
Pricing and Supply Chain Analysis
Crushing capacity utilization rates above 85% in Gujarat and Maharashtra ginneries compress spot market liquidity while elevating contract price floors for decorticated grades. Scale concentration among integrated processors with captive cottonseed supply insulates premium tiers from soybean meal substitution pressure, though non-decorticated standard grades face margin erosion from protein content specification tightening.
Pricing Analysis
EU Feed Hygiene Regulation dictates the pricing tier structure through contaminant threshold compliance costs that filter import eligibility. Three-tier pricing structure across premium, standard, and economy levels segments by decortication extent and gossypol certification, with REACH-registered refined grades commanding formulation premiums in pet food channels. Price differentiation hinges on protein density specifications and batch-level traceability documentation. Cost compression in standard non-decorticated tiers is intensifying because Brazilian export volumes displace spot market liquidity. Poultry integrators exhibit highest price sensitivity through direct procurement restructuring, while EU pet food manufacturers show lowest sensitivity for low-gossypol certified supply.
Supply Chain Analysis
Strategic stockpile preferences dominate cottonseed procurement as ginning seasonality concentrates raw material availability into narrow harvest windows. Supply concentrates in the United States, Brazil, and India where crushing clusters integrate with cultivation belts. Raw material flows draw from cotton ginning networks, solvent extraction facilities, and mechanical pressing operations. Single-source vulnerability runs through Brazilian port logistics where Santos and Paranaguá chokepoints constrain export scheduling. Distribution runs through bulk ocean freight corridors for international trade and direct pneumatic discharge for captive domestic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cottonseed meal markets trace cyclical recovery patterns tied to cotton lint price volatility, with ginning economics favoring fiber recovery over seed crushing during fiber price spikes and reversing when lint markets soften.
For Market Incumbents: Fortify backward integration into cotton ginning operations across the US Southeast and Brazilian Mato Grosso to secure captive seed supply against merchant channel displacement. Invest in solvent extraction upgrades for EU-certified export positioning as REACH compliance filters competitor eligibility. Defensive consolidation through direct procurement agreements with Tyson and Pilgrim's Pride operations compresses spot market exposure.
For New Entrants and Emerging Players: Lead with expeller-pressed mechanical processing specialization targeting Northeast US dairy nutritionists seeking rumen-undegradable protein advantages. Aquaculture feed trials in Vietnam and Thailand offer the most penetrable white-space as shrimp producers test elevated inclusion rates. Go-to-market positioning through third-party certification audits and batch-level traceability systems unlocks EU compounder demand.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional mechanical processing specialists with nutritional specification differentiation over commodity-scale solvent extraction assets. Long-term viability across the 5-10 year window rests on aquaculture feed penetration rates and pet food premiumization sustainability. Acquisition target archetype: integrated ginneries with captive crushing capacity in Gujarat or Maharashtra. The signal to watch is EU port authority extension of mycotoxin testing protocols beyond current aflatoxin and fumonisin screening.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ginning | Cargill and ADM anchor supply continuity through Southeast ginnery networks. |
| Solvent Extraction Upgrade | European crushers capture premium positioning under REACH substance registration. |
| Expeller Processing Specialization | Northeast dairy nutritionists specify mechanical pressing for bypass protein benefits. |
| Third-Party Certification Investment | Brazilian exporters deploy batch-level traceability for Rotterdam and Hamburg entry. |
| Direct Procurement Restructuring | Tyson and Pilgrim's Pride bypass merchant channels through ginnery supply agreements. |
Research Methodology
Desk research of USDA production databases, EU trade statistics, and FSSAI regulatory filings preceded structured interviews with cotton ginning operators, dairy nutritionists, feed compound procurement managers, and aquaculture feed millers. Primary fieldwork with crushing facility engineers and port logistics coordinators in Santos and Paranaguá validated secondary trade flow assumptions. Bottom-up volume modeling across processing capacity clusters triangulated against top-down consumption estimates from livestock census data and feed formulation surveys.
Variance decomposition across product type, application segment, and regional processing hub dimensions shaped analytical framework construction throughout the forecast period. CAGRs derived from segmented growth rate application with cross-validation against historical protein meal substitution elasticities. Industry-specific forecast inputs incorporated cotton lint price volatility regimes and EU Feed Hygiene Regulation compliance cost trajectories.
The analysis sits within stated boundaries; outcomes outside sustained aquaculture feed trial success or cotton lint price stability would require recalibration. Forecasts reflect assumptions regarding gossypol detoxification research progress and mycotoxin certification timeline standardization. Revision becomes warranted when soybean meal price spreads cross thresholds that trigger formulation substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Middle East Feed Amino Acids Market
Agricultural Commodities
Straw Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Europe Feed Amino Acids Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
South America Feed Premix Market