
 Single Feed Market | 2026-2036
Single Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Single Feed Market Analytics
The gap between premium nutrient-dense formulations and commodity-grade single feeds is expanding as livestock producers face diverging margin pressures. Cargill leverages its global procurement network to secure consistent molasses and urea supplies for liquid feed manufacturing. Voermol Feeds anchors its position through deep distribution across Southern African agricultural cooperatives. Nutreco differentiates via R&D intensity in precision-delivery systems for rumen-protected nutrients.
Single feed denotes a nutritionally complete or supplementary ration delivered in one formulation, typically incorporating protein sources, energy carriers, minerals, and vitamins at specified inclusion rates such as 32-48% crude protein in concentrated variants, designed to meet specific production goals without additional mixing. Complete feed dominates volume as integrated poultry and swine operations standardize ration simplicity, while supplementary feed captures faster expansion among pasture-based ruminant systems seeking cost-flexible nutrient top-ups. Medicated feed carries elevated regulatory compliance costs that concentrate margin pools among manufacturers with dedicated veterinary feed directive certifications.
The FDA's Veterinary Feed Directive and the EU's Feed Hygiene Regulation impose prescription and traceability requirements that reshape product development timelines and market access conditions for medicated and specialty formulations. Brazil's MAPA and India's FSSAI enforce parallel but distinct contaminant thresholds and labeling mandates that complicate cross-border formulation standardization. Stakeholders must monitor evolving antibiotic-resistance policies and carbon-accounting rules to anticipate which formulation categories will face accelerated compliance-driven restructuring.
Market Dynamics
Diverging margin pressures across livestock sectors are fragmenting the single feed landscape into premium nutrient-dense formulations versus commodity-grade alternatives, with precision-delivery technologies now determining competitive advantage.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:Sustainability requirements are accelerating demand for traceable, low-carbon ingredient sourcing across European dairy operations.
- Brazil Mato Grosso feedlot integration:Large-scale cattle confinement in this state is concentrating demand for high-protein supplementary rations.
- Rumen-protected nutrient technologies:Precision-delivery systems are improving feed conversion efficiency in North American beef and dairy herds.
Market Restraints
- Molasses and urea price volatility:Liquid feed manufacturers face input cost swings tied to sugar harvests and natural gas derivatives.
- FDA Veterinary Feed Directive compliance:Prescription and traceability requirements for medicated feeds extend product development timelines and concentrate margin pools among certified specialists.
- Soybean meal substitution pressure:Alternative protein sources including insect meal and single-cell proteins threaten traditional formulation economics.
Strategic Opportunities
- Pasture-based ruminant systems in Southern Africa:Cost-flexible nutrient top-ups remain underpenetrated outside cooperative-served commercial farms.
- Carbon-accounting feed certifications:Early alignment with emerging lifecycle assessment standards opens premium positioning before mandatory disclosure.
- Direct-to-farm digital distribution:Bypassing traditional cooperative channels reaches mid-sized independent producers with customized liquid supplement programs.
Industry Challenges
- Veterinary feed directive certification timelines:Manufacturers face extended approval periods for medicated formulations, compressing product launch windows.
- Legacy ration formulation expertise gaps:Precision-delivery system deployment requires skills in rumen microbiology and encapsulation chemistry that outpace workforce development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Feed Market |
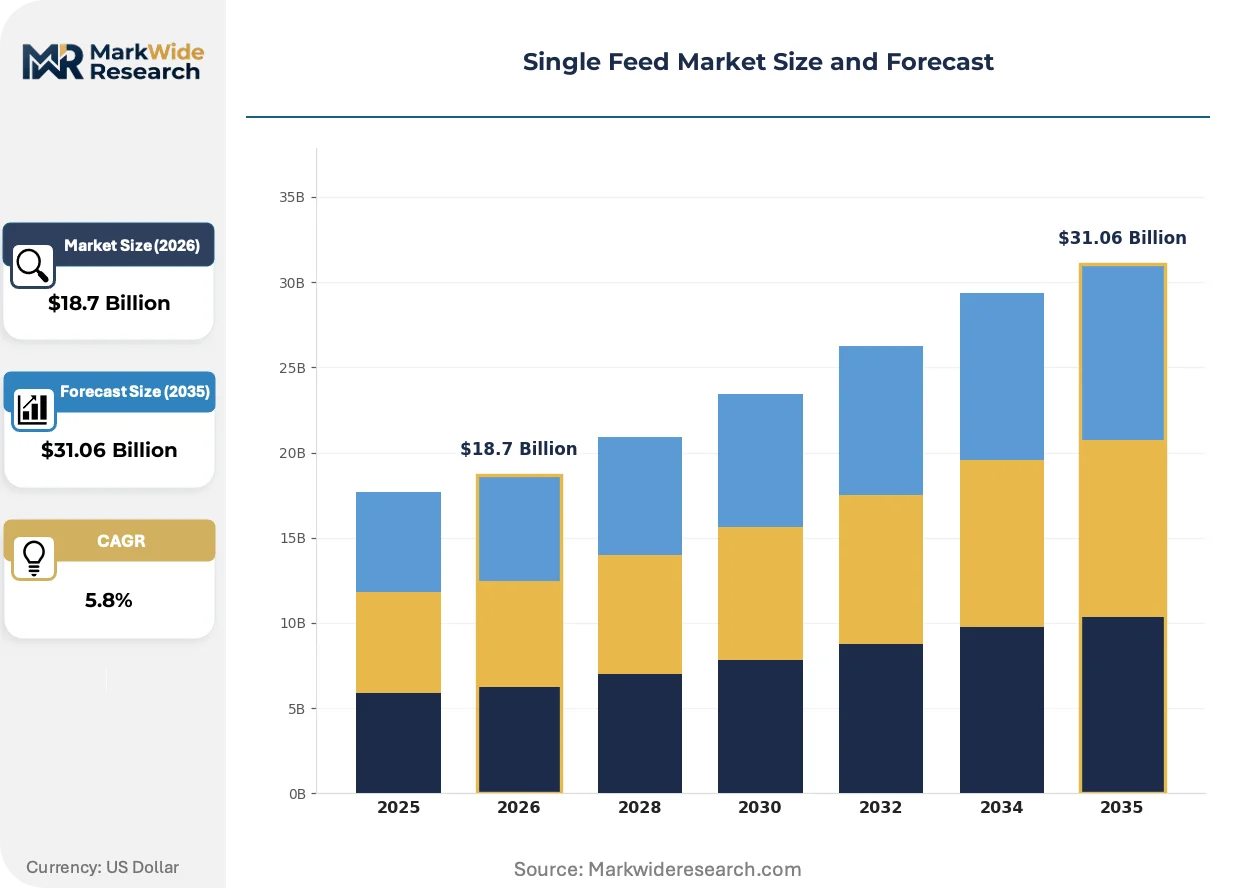
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Concentrated Feed, Supplementary Feed, Medicated Feed Animal Type: Poultry, Swine, Ruminants, Aquaculture Formulation: Natural, Organic, Synthetic, Custom Blend Distribution Channel: Online Retail, Specialty Stores, Feed Mills, Agricultural Cooperatives |
| Companies Covered | Liquid Feeds International, Alliance Liquid Feeds, Voermol Feeds, Double S Liquid Feed Services, Cargill, Archer Daniels Midland Company, Land O'Lakes, Nutreco, Charoen Pokphand Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Feed Market Evolving Landscape
Formulation science and delivery mechanisms are converging to reshape how nutrients reach livestock, with digital integration and regulatory pressure accelerating the shift from commodity mixing to precision nutrition services.
Encapsulation technologies for rumen-protected amino acids and fats are consolidating control over nutrient bioavailability in high-performance dairy herds. Large-scale operations in the Netherlands and Denmark are adopting these systems at accelerated rates. This consolidation is compressing margins for conventional unprotected supplement suppliers while rewarding manufacturers with in-house microencapsulation capabilities.
REACH chemical registration requirements and the EU's Feed Hygiene Regulation are tightening contaminant thresholds for imported protein meals. European compound feed manufacturers are reformulating rations to reduce dependency on non-EU soybean supplies. Medicated feed specialists are responding by localizing production within the customs union to avoid border inspection delays.
Subscription-based nutrition advisory services are displacing transactional feed purchasing among progressive dairy cooperatives. Technical consultants now bundle ration formulation, feed delivery, and performance monitoring into annual contracts. This shift is most visible in Wisconsin and California dairy belts where margin volatility drives demand for cost-certainty arrangements.
Single Feed Market Segmentation
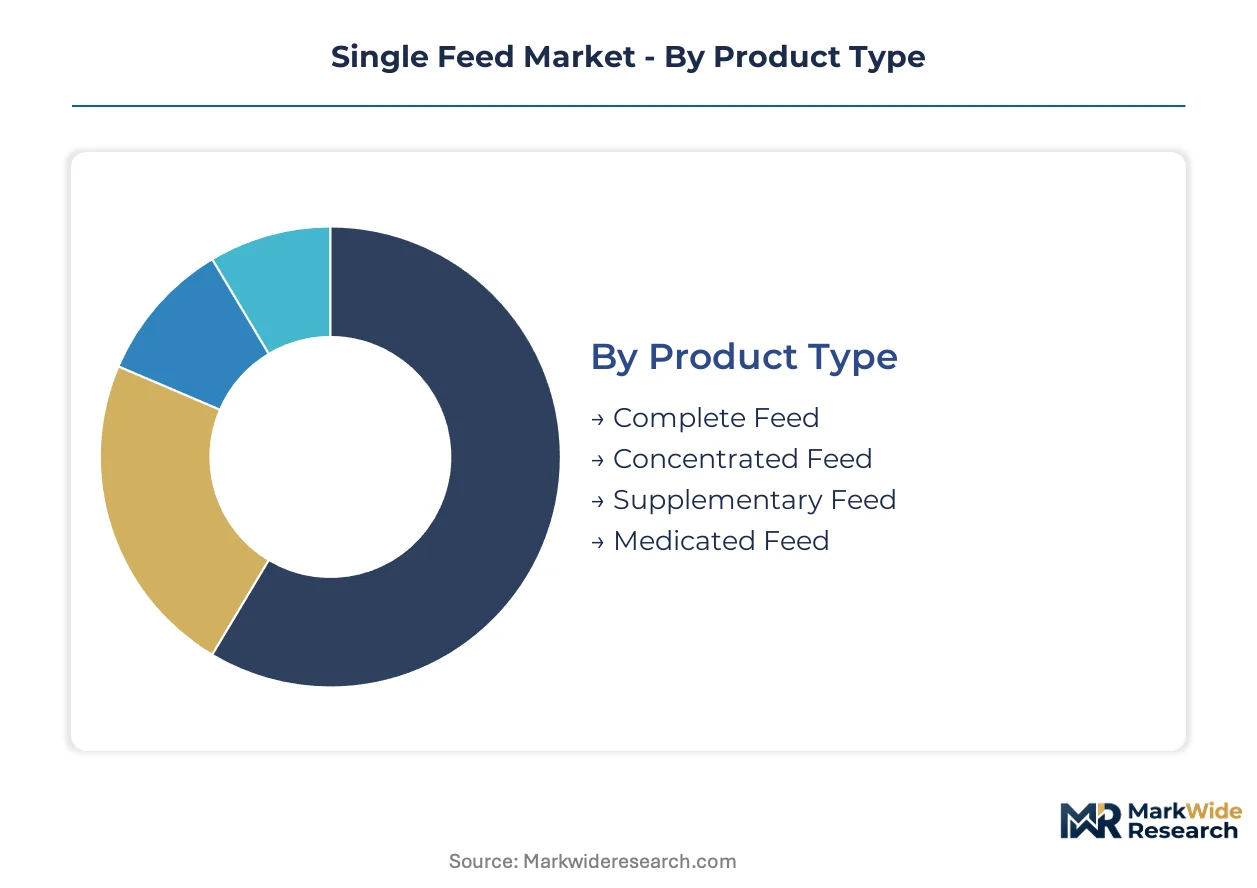
Segmentation in single feed markets reveals how procurement concentration, regulatory burden, and delivery economics fragment revenue pools across distinct product architectures. Understanding these divisions exposes where margin accrues and where commoditization pressures intensify.
Product Type:
Supply concentration among liquid feed specialists in North America and compound feed multinationals in Europe has stratified manufacturing economics across four distinct product architectures.
- Complete Feed:Nutritionally comprehensive rations formulated to meet all dietary requirements without additional supplementation, typically pelleted or mash forms with 16-22% crude protein for finishing phases. Integrated poultry operations in the US Southeast and Denmark's industrial swine sector standardize these formulations to eliminate on-farm mixing labor and variability.
- Concentrated Feed:High-density nutrient packages requiring dilution with base grains at specified inclusion rates, often 32-48% crude protein variants for dairy transition periods. Demand concentrates in Germany's Bavarian dairy belt and California's Central Valley, where precision nutrition consultants specify exact premix ratios for high-yielding Holstein herds facing volatile milk prices.
- Supplementary Feed:Top-up formulations addressing specific nutrient gaps in pasture-based or roughage-heavy systems, including molasses-urea blocks and liquid protein supplements. Pastoral operations in Brazil's Pantanal and Australia's Queensland station country rely on these cost-flexible inputs during dry seasons when native forage quality collapses.
- Medicated Feed:Therapeutic or prophylactic formulations incorporating FDA-regulated active pharmaceutical ingredients under Veterinary Feed Directive protocols. Compliance costs and prescription requirements concentrate manufacturing among specialists with dedicated quality systems and veterinary oversight capabilities.
Complete feed absorbs the bulk of installed capacity; supplementary feed is expanding most quickly among pasture-based systems seeking input cost flexibility.
Animal Type:
Species-specific digestive physiology and production intensity create divergent formulation specifications that reshape ingredient procurement patterns.
- Poultry:High-energy, amino acid-optimized rations formulated for rapid growth conversion in broiler operations and sustained laying persistence in egg production. US Georgia and Arkansas integrators drive volume through standardized corn-soy diets with synthetic amino acid fortification.
- Swine:Phase-feeding programs with precise lysine-to-energy ratios across nursery, grower, and finisher stages. Denmark's SEGES Innovation Centre and Netherlands' Wageningen University research stations pioneer low-protein, amino acid-supplemented formulations to reduce nitrogen excretion under EU Nitrates Directive pressure.
- Ruminants:Fiber-appropriate energy and bypass protein formulations accounting for rumen microbial fermentation dynamics. Large-scale feedlots in Nebraska and Texas Panhandle, plus New Zealand's dairy cooperatives, specify rumen-protected fat and amino acid inclusions to optimize milk component yields and feed conversion.
- Aquaculture:Extruded, water-stable diets with high fish meal or alternative protein inclusion for salmon, shrimp, and tilapia species. Norwegian fjord farming operations and Vietnam's Mekong Delta pangasius producers demand specialized formulations with precise lipid profiles and pellet durability specifications.
Ruminant feed commands the largest production footprint; aquaculture diets are climbing the fastest as marine and freshwater farming intensifies.
Formulation:
Certification requirements and input cost differentials are fragmenting sourcing strategies across four distinct quality tiers.
- Natural:Minimally processed ingredients without synthetic additives, adhering to loose industry conventions rather than formal certification. Niche demand in France's Brittany region and Italy's Emilia-Romagna supports regional feed mill specialization.
- Organic:Certified formulations meeting EU Organic Regulation or USDA National Organic Program standards, mandating non-GMO ingredients and restricted additive lists. Supply bottlenecks for organic soybean meal and trace minerals constrain volume expansion.
- Synthetic:Conventional formulations leveraging industrial amino acids, vitamin premixes, and mineral chelates for cost-optimized performance. Standard in commercial operations where certification premiums do not recover input cost differentials.
- Custom Blend:Client-specified formulations produced to order based on laboratory forage analysis and production targets. Independent nutrition consultants in Wisconsin and Ireland's Dairygold cooperative territory specify these for mid-sized herds seeking precision without full vertical integration.
Synthetic formulations dominate volume throughput; organic certification is gaining share fastest where retailer and processor premiums justify input cost premiums.
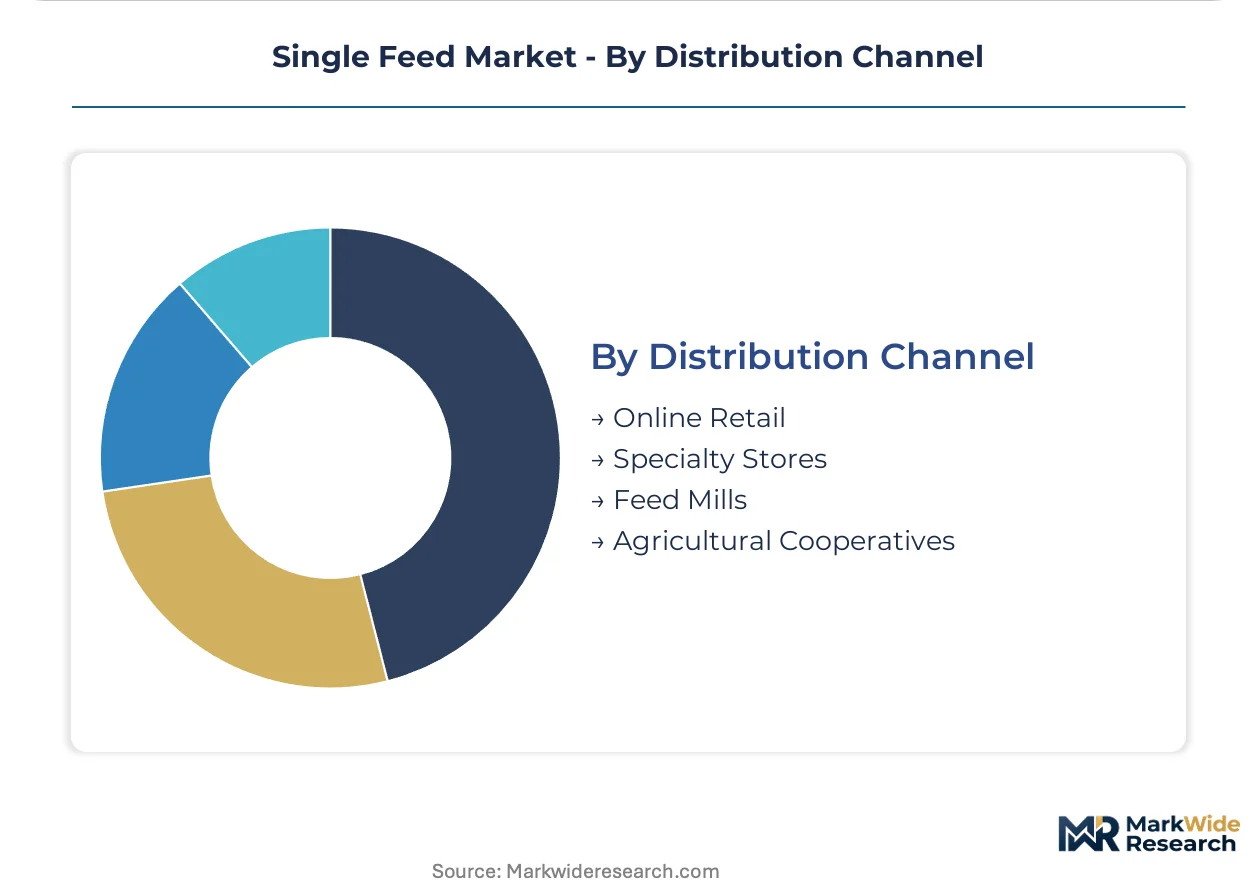
Distribution Channel:
Logistics infrastructure density and producer scale determine channel economics, with digital platforms now penetrating previously cooperative-dominated territories.
- Online Retail:Direct-to-farm e-commerce platforms with subscription delivery models for smaller operations and hobby farms. Tractor Supply Company's digital expansion and Netherlands' ForFarmers web portal illustrate platform growth in regions with reliable last-mile logistics.
- Specialty Stores:Independent agricultural retailers with technical advisory staff serving diversified livestock operations. Strong presence in France's Limousin cattle region and Kentucky's horse country, where relationship-based purchasing persists.
- Feed Mills:Integrated manufacturing and distribution facilities with formulation services and bulk delivery capabilities. US Midwest grain cooperatives and Brazil's Amaggi operations exemplify captive supply chain control over ingredient procurement through finished product delivery.
- Agricultural Cooperatives:Member-owned purchasing organizations aggregating demand for volume pricing and shared technical services. Southern Africa's VKB and AFGRI cooperatives, plus Iowa's Landus, anchor distribution in regions with strong producer association traditions.
Feed mills and cooperatives retain the dominant share of volume movement; online retail is expanding most quickly among smaller, geographically dispersed producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mato Grosso state anchors single feed demand through large-scale feedlot integration, while regulatory divergence across major livestock regions fragments formulation standards and sourcing requirements.
United States
Precision-formulated liquid supplements dominate dairy and beef cattle operations in Wisconsin and California, where margin volatility drives subscription-based nutrition advisory services. The FDA's Veterinary Feed Directive imposes prescription and traceability requirements that extend product development timelines for medicated formulations. Nebraska and Texas Panhandle feedlots specify rumen-protected fat and amino acid inclusions to optimize feed conversion efficiency.
Brazil
Large-scale cattle confinement in Mato Grosso concentrates demand for high-protein supplementary rations, while pasture-based systems in the Pantanal rely on molasses-urea blocks during dry seasons. MAPA enforces distinct contaminant thresholds and labeling mandates that complicate cross-border formulation standardization. Feedlot integration accelerates in São Paulo state's industrial corridor, pulling volume from traditional cooperative channels.
Germany
Bavaria's dairy belt drives concentrated feed demand for high-yielding Holstein herds facing volatile milk prices, with precision nutrition consultants specifying exact premix ratios. The EU Green Deal's farm-to-fork sustainability mandates accelerate traceable, low-carbon ingredient sourcing requirements. SEGES Innovation Centre research stations pioneer low-protein, amino acid-supplemented formulations to reduce nitrogen excretion under EU Nitrates Directive pressure.
Netherlands
Large-scale dairy operations adopt rumen-protected nutrient technologies at accelerated rates, consolidating control over nutrient bioavailability and compressing margins for conventional unprotected supplement suppliers. REACH chemical registration requirements and the EU's Feed Hygiene Regulation tighten contaminant thresholds for imported protein meals. ForFarmers' web portal illustrates platform growth in regions with reliable last-mile logistics for direct-to-farm distribution.
South Africa
Pasture-based ruminant systems in Southern Africa remain underpenetrated outside cooperative-served commercial farms, creating openings for cost-flexible nutrient top-ups. VKB and AFGRI cooperatives anchor distribution in regions with strong producer association traditions, though mid-sized independent producers seek alternatives. Voermol Feeds maintains deep distribution across agricultural cooperatives, capturing share in a fragmented technical advisory landscape.
Single Feed Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that stratifies between integrated multinationals with captive ingredient procurement and regional specialists with cooperative-anchored distribution. Supply concentration among liquid feed specialists in North America and compound feed multinationals in Europe has fragmented manufacturing economics into tiered competitive pools. Three archetypes dominate: global procurement networks securing consistent molasses and urea supplies, R&D-intensive precision-delivery system developers, and cooperative-embedded regional distributors with technical advisory capabilities. Competitive moves center on backward integration into ingredient sourcing and localized production within customs unions to avoid border inspection delays.
Within the global procurement tier, Cargill leverages its network to anchor liquid feed manufacturing, while Nutreco occupies a position among R&D-intensive specialists developing precision-delivery systems for rumen-protected nutrients. Voermol Feeds exemplifies the cooperative-embedded regional archetype, with deep distribution across Southern African agricultural networks. These three represent distinct strategic positions without implying specific market shares or operational details.
| Leading Market Players |
|---|
| Liquid Feeds International |
| Alliance Liquid Feeds |
| Voermol Feeds |
| Double S Liquid Feed Services |
| Cargill |
| Archer Daniels Midland Company |
| Land O'Lakes |
| Nutreco |
| Charoen Pokphand Foods |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap feed mills in Germany's Bavarian dairy belt and Iowa's grain cooperative networks anchor supply discipline through long-term offtake contracts with soybean processors, translating procurement scale into pricing power over independent nutrition consultants and smaller integrators.
Pricing Analysis
Value-based pricing anchored to milk yield per cow and feed conversion ratios dominates premium concentrated feed tiers, separating rumen-protected nutrient formulations from commodity unprotected supplements. Price differentiation rests on certification grade—EU Organic Regulation versus conventional synthetic—and volume scale with integrated poultry operations securing contract discounts unavailable to pasture-based ruminant producers. Cost compression in liquid feed tiers is intensifying because molasses and urea input volatility erodes formulation margins. Independent mid-sized dairy herds in Wisconsin exhibit highest price sensitivity, while Nebraska feedlot operators prioritize conversion efficiency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian soybean meal exports and Thai fish meal supplies, exposing compound feed manufacturers to harvest volatility and El Niño disruption patterns. Geographic supply concentration centers on the United States for corn and distiller's grains, Brazil for soybean crush output, and the Netherlands for specialty vitamin premixes. Raw material dependencies draw from urea derivatives tied to natural gas pricing, marine-based omega-3 lipid sources, and trace mineral chelates. Tariff exposure on non-EU protein meals under REACH registration requirements compresses margin recovery timelines. Distribution runs through agricultural cooperatives in Southern Africa and feed mill direct-to-farm bulk delivery in North American dairy belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision-delivery encapsulation technologies are displacing conventional unprotected supplement mixing, forcing legacy formulation houses to rebuild technical capabilities or retreat to commodity blending.
For Market Incumbents: Hedge against soybean meal substitution pressure by securing backward integration into insect meal or single-cell protein pilot facilities, and defend cooperative channel control through embedded nutrition advisory subscriptions that lock in annual contract volumes against digital platform entrants. For New Entrants and Emerging Players: Enter via direct-to-farm digital distribution in South Africa's underpenetrated mid-sized independent producer segment, targeting cost-flexible supplementary feed top-ups with customized liquid programs that bypass VKB and AFGRI cooperative gatekeepers through mobile-enabled forage analysis and subscription delivery. For Investors and Strategic Acquirers: FDA Veterinary Feed Directive certification backlogs are the leading indicator that medicated feed manufacturing assets will command scarcity premiums; prioritize specialists with dedicated quality systems and veterinary oversight capabilities over commodity blenders, watching for extended approval timelines as the inflection signal for consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Proteins | In-house insect meal production secures supply against soybean price volatility and EU deforestation regulations. |
| Precision-Delivery Technology Licensing | Rumen-protected amino acid patents from Netherlands research stations unlock premium positioning in high-yield dairy herds. |
| Cooperative Channel Embedding | Annual nutrition advisory subscriptions through Iowa's Landus and Southern Africa's VKB lock in volume commitments against digital disintermediation. |
| Localized Production within Customs Unions | EU-based manufacturing avoids REACH border inspection delays and tightens contaminant threshold compliance for compound feed exports. |
| Carbon-Accounting Certification Program | Early lifecycle assessment alignment opens premium positioning before EU Green Deal mandatory disclosure requirements take full effect. |
Research Methodology
USDA National Agricultural Statistics Service crop production reports, EU Feed Hygiene Regulation compliance filings, and Brazilian MAPA import inspection records formed the secondary backbone, cross-referenced with primary interviews involving feed mill procurement directors, dairy cooperative nutrition consultants, veterinary feed directive compliance officers, and precision-delivery system R&D leads. Bottom-up volume modeling from state-level feed consumption data and top-down value reconciliation through customs trade flows enabled triangulation across analysis approaches.
Bottom-up segmentation modeling tracked complete feed, concentrated feed, supplementary feed, and medicated feed architectures across poultry, swine, ruminant, and aquaculture species, with formulation tiers spanning natural, organic, synthetic, and custom blend categories. CAGRs were derived from regression analysis against livestock inventory projections and feed conversion efficiency trends, incorporating rumen-protected nutrient adoption curves and carbon-accounting certification penetration rates as industry-specific demand drivers across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under antibiotic-resistance policy acceleration and molasses supply disruption scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Global Seed Cotton Market