
 North America Feed Lutein and Zeaxanthin Market | 2026-2036
North America Feed Lutein and Zeaxanthin Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Lutein and Zeaxanthin Market Analytics
Canada is fragmenting its feed additive manufacturing base as new extraction facilities in Alberta and Saskatchewan target domestically grown marigold crops. Kemin Industries, Inc. leverages its Des Moines, Iowa, operations to sustain captive supply chains for poultry integrators across the Corn Belt. DSM-Firmenich AG competes through its specialized carotenoid stabilization technologies that extend product shelf life in high-temperature feed milling environments. BASF SE anchors its position with synthetic lutein capacity that dominates price-sensitive swine and ruminant applications.
Feed lutein and zeaxanthin comprise oxygenated carotenoid compounds, typically extracted from marigold oleoresin or synthesized chemically, that deposit in animal tissues to intensify yolk color, skin pigmentation, and flesh hue in farmed species. These compounds function as natural colorants with antioxidant properties, meeting processor and consumer expectations for visually consistent animal products. Natural lutein commands premium positioning in layer and aquaculture feeds where clean-label sourcing influences buyer decisions, while synthetic variants occupy cost-driven segments in swine finishing rations. Poultry applications generate the deepest margin pools due to volume concentration and specification intensity among integrated producers, whereas aquaculture represents the fastest-expanding application as salmonid and shrimp producers adopt pigment-enhanced diets.
The FDA regulates feed lutein and zeaxanthin as food additives under 21 CFR, requiring premarket approval and specific labeling for target species and use levels. The Canadian Food Inspection Agency enforces complementary feed registration standards that restrict unapproved carotenoid sources in commercial rations. USDA organic certification criteria further constrain ingredient sourcing for certified livestock operations, favoring natural extraction pathways over synthetic alternatives. Stakeholders must monitor evolving state-level antibiotic reduction policies, as these programs indirectly intensify demand for pigmentation additives that support bird health signaling and consumer acceptance without therapeutic claims.
Market Dynamics
Broiler integrators across the southeastern United States are consolidating carotenoid procurement under single-source premix contracts, compressing supplier margins while elevating technical service requirements for formulation stability and yolk color consistency.
Growth Catalysts
- USDA Organic Certification:Certified livestock operations favor natural marigold extraction pathways, creating premium pricing tiers for solvent-free lutein suppliers serving layer and turkey producers in the Midwest.
- Antibiotic Reduction Policies:State-level restrictions on therapeutic feed additives intensify demand for pigmentation compounds that signal bird health through visual quality markers without drug claims.
- Salmonid Aquaculture Expansion:Pigment-enhanced diets for farmed salmon and trout in British Columbia and Washington State drive volume growth for stabilized zeaxanthin formulations.
Market Restraints
- Marigold Oleoresin Volatility:Weather-dependent harvests in Mexico and India create input cost instability that squeezes margin predictability for natural extraction processors.
- Des Moines Supply Concentration:Captive supply chains anchored in Iowa create geographic vulnerability for Corn Belt poultry integrators dependent on single-source premix infrastructure.
- Synthetic Price Floors:BASF's chemically synthesized lutein capacity sets baseline pricing that limits premium capture for natural extractors in swine and ruminant applications.
Strategic Opportunities
- Alberta Extraction Facilities:New solvent-free processing plants targeting domestically grown marigold crops reduce Canadian import dependency and shorten supply chains for Prairie livestock operations.
- Shrimp Aquaculture Pigmentation:Underdeveloped carotenoid dosing protocols for Pacific white shrimp in Mexico and Texas present technical white space for species-specific formulation development.
- FDA Food Additive Streamlining:Potential harmonization of 21 CFR approval pathways for novel carotenoid sources could accelerate market entry for fermentation-derived lutein alternatives.
Industry Challenges
- Carotenoid Stabilization Expertise:High-temperature feed milling environments degrade unprotected lutein, requiring specialized encapsulation chemistry skills that remain scarce among regional premix formulators.
- Dual Jurisdiction Compliance:Simultaneous FDA food additive registration and Canadian Food Inspection Agency feed approval timelines create 18-24 month market entry delays for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Lutein and Zeaxanthin Market |
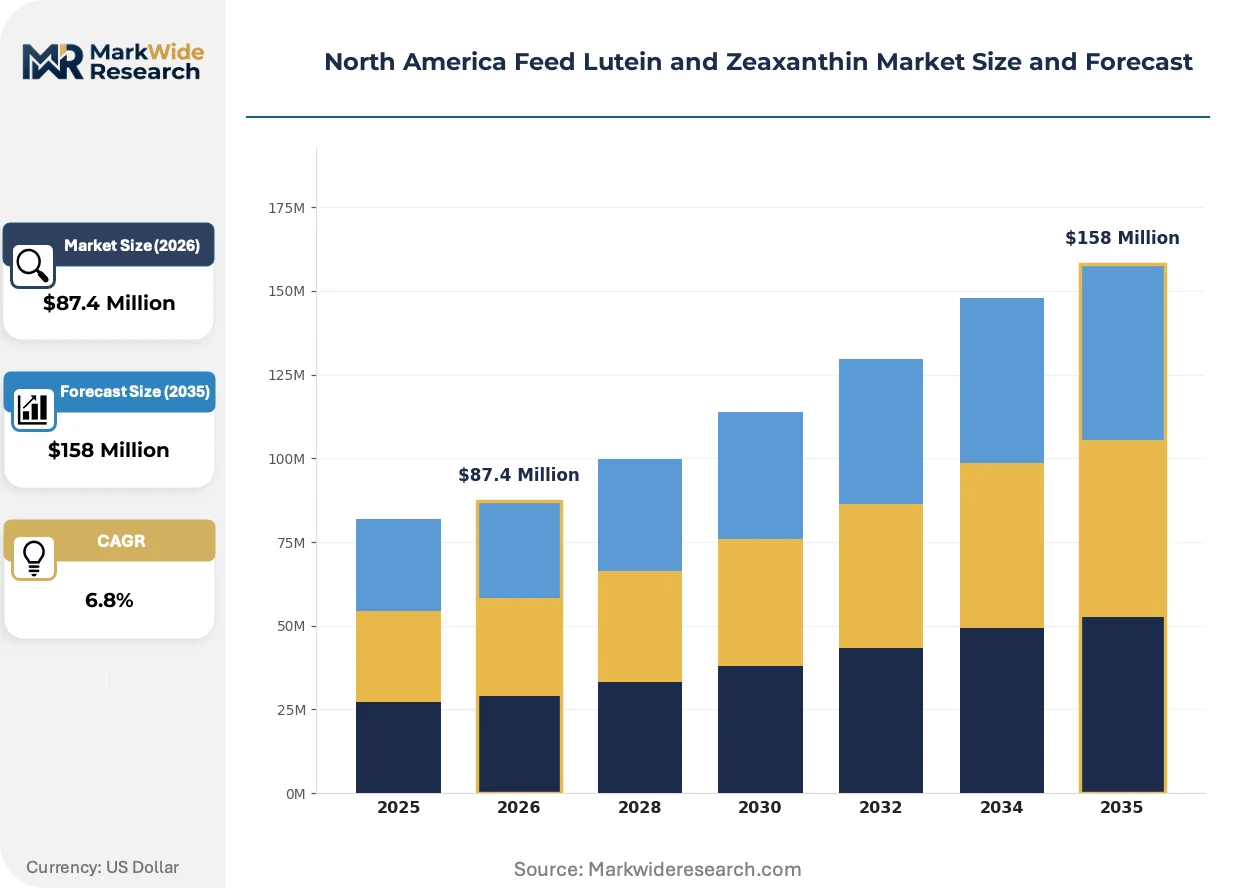
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Lutein, Synthetic Lutein, Natural Zeaxanthin, Synthetic Zeaxanthin Application: Poultry, Aquaculture, Swine, Ruminants Form: Powder, Liquid, Granules, Emulsions Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Kemin Industries, Inc., DSM-Firmenich AG, BASF SE, Alltech, Inc., Novus International, Inc., Cargill, Incorporated, Chr. Hansen Holding A/S, FMC Corporation, Valensa International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Lutein and Zeaxanthin Market Evolving Landscape
Extraction technology and regulatory enforcement patterns are compressing traditional supply chain configurations while end-user specifications harden around colorimetric performance metrics and clean-label provenance.
Microencapsulation technology is hybridizing conventional spray-drying methods with lipid-matrix embedding to protect lutein from oxidative degradation during pelleting temperatures exceeding 85°C. Layer operations in Iowa and Minnesota are adopting these stabilized formulations at accelerated replacement rates. This convergence is compressing commodity premix margins while rewarding suppliers with captive stabilization intellectual property.
The FDA's updated enforcement posture under 21 CFR food additive regulations is requiring premarket notification for novel carotenoid delivery systems previously grandfathered under prior sanctions. Feed compounders in the Midwest and Southeast are restructuring supplier qualification protocols to document target species use levels and stability data. Layer integrators with dedicated quality assurance teams are absorbing compliance costs faster than independent feed mills.
Certification-driven procurement is displacing spot-market purchasing as major broiler and egg processors mandate third-party verified natural extraction documentation for retail-branded product lines. Distributor relationships in the Corn Belt are fragmentating as integrators establish direct technical partnerships with extraction specialists. This behavioral shift is most pronounced among southeastern US broiler operations supplying private-label retail channels.
North America Feed Lutein and Zeaxanthin Market Segmentation
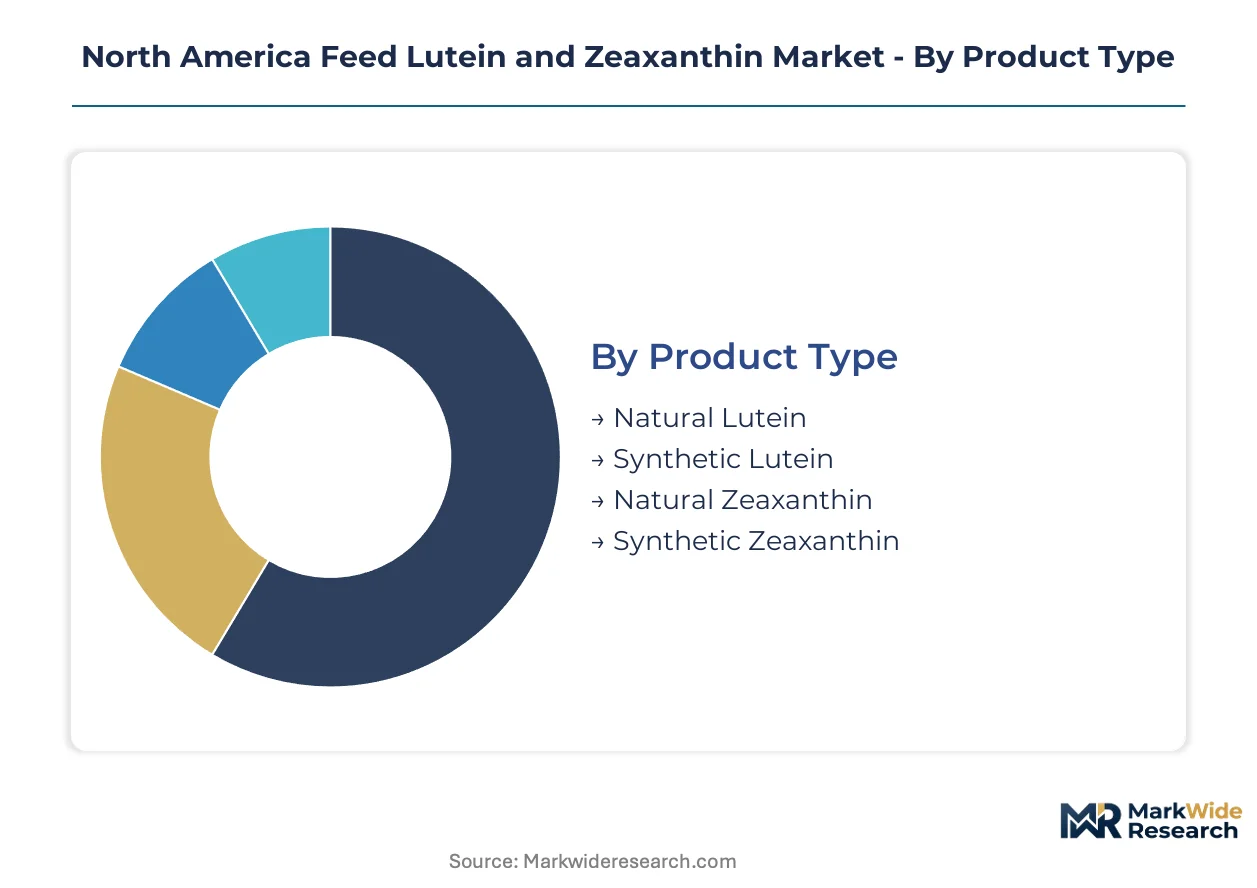
Segmentation in feed lutein and zeaxanthin reveals how extraction chemistry, target species physiology, and feed manufacturing constraints partition commercial opportunity. Each dimension carries distinct margin structures and technical service requirements that reshape supplier positioning across North America.
Product Type:
Cost tier stratification separates solvent-extracted botanical compounds from chemically synthesized alternatives, with premium capture varying by end-use certification requirements.
- Natural Lutein:Marigold oleoresin extraction yields esterified carotenoids requiring saponification for bioavailability. Layer integrators in Iowa and Minnesota absorb premium pricing for USDA Organic-compliant sourcing that satisfies retail clean-label mandates.
- Synthetic Lutein:Chemically manufactured via stereoselective synthesis delivering consistent isomeric purity. Price-sensitive swine finishing operations in the Corn Belt default to this tier where pigmentation specifications tolerate non-botanical provenance.
- Natural Zeaxanthin:Derived from paprika or marigold co-extraction with distinct deposition kinetics in salmonid flesh. British Columbia aquaculture operations specify this grade for pigment-enhanced diets targeting export quality premiums.
- Synthetic Zeaxanthin:Produced through proprietary chemical routes with crystalline stability advantages. BASF's manufacturing scale anchors baseline pricing that constrains natural extractor margins in ruminant applications.
Natural Lutein holds installed capacity. Synthetic Zeaxanthin is rotating up the share rankings.
Application:
Species-specific tissue deposition biology and visual quality economics concentrate margin pools unevenly across animal production systems.
- Poultry:Yolk colorimetric scoring drives specification intensity among integrated layer and broiler operations. Southeastern US integrators consolidate procurement under single-source premix contracts that elevate technical service requirements for formulation stability.
- Aquaculture:Salmonid and shrimp flesh pigmentation commands premium feed economics where astaxanthin co-formulation with zeaxanthin creates species-specific hue targeting. Washington State and British Columbia producers are expanding pigment-enhanced diet adoption.
- Swine:Skin coloration carries modest processor premiums, limiting carotenoid inclusion to finishing phase rations where cost-per-unit-pigmentation dominates formulation decisions.
- Ruminants:Milk and beef fat coloration applications remain peripheral, with dairy operations in Wisconsin and California showing selective adoption for specialty fluid milk positioning.
Poultry commands the deepest margin pools. Aquaculture is climbing the fastest with pigment-enhanced diet expansion.
Form:
Manufacturing process compatibility and oxidative protection requirements differentiate physical delivery systems for feed mill integration.
- Powder:Spray-dried crystalline product standard for inclusion in mash and pelleted feeds. High-temperature pelleting environments exceeding 85°C accelerate demand for microencapsulated variants that protect against thermal degradation.
- Liquid:Oil-suspended concentrates for post-pellet fat coating applications or direct addition to liquid feed systems. Aquaculture extruded feeds favor this form for homogeneous distribution in high-moisture matrices.
- Granules:Agglomerated particles with enhanced flowability for automated premix handling. Midwest feed mills specify this grade for reduced dust exposure and dosing precision.
- Emulsions:Water-dispersible formulations for drinking water supplementation or specialized aquaculture applications. Limited penetration reflects stability challenges in extended storage conditions.
Powder maintains dominant installed capacity. Liquid is gaining share fastest with aquaculture extrusion growth.
Distribution Channel:
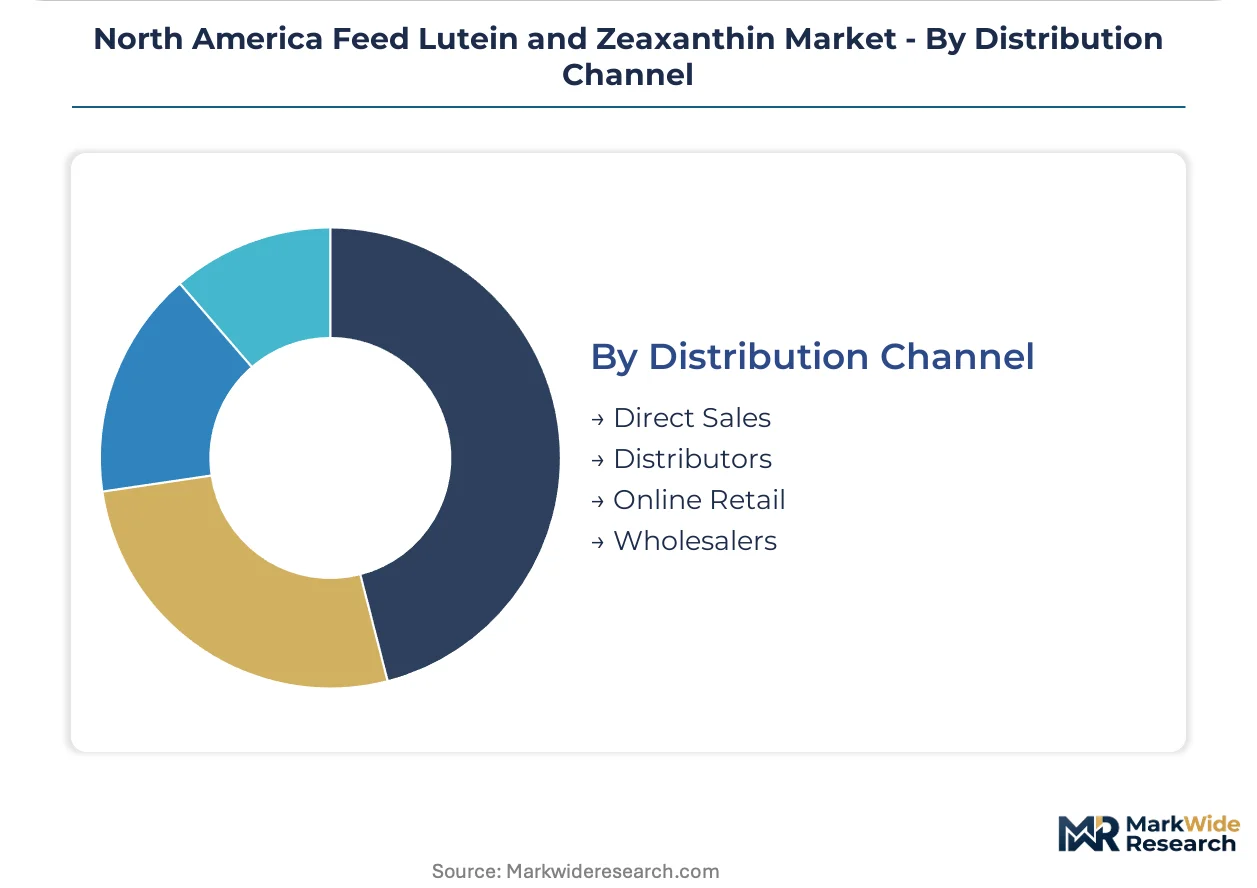
Customer scale and technical service intensity determine channel economics, with direct relationships displacing traditional distributor intermediaries.
- Direct Sales:Technical partnership contracts between extraction specialists and integrated poultry operations. Kemin's Des Moines infrastructure exemplifies captive supply chain anchoring that eliminates distributor margins for Corn Belt layer integrators.
- Distributors:Regional feed additive wholesalers serving independent feed mills and smaller livestock operations. Fragmentation accelerates as integrators bypass this channel for qualified direct sourcing.
- Online Retail:E-commerce platforms targeting hobby farm and specialty livestock segments. Limited volume reflects batch size mismatches with commercial-scale manufacturing minimums.
- Wholesalers:Bulk commodity handlers for price-sensitive swine and ruminant applications where specification intensity remains low. Synthetic lutein volume flows predominantly through this channel.
Direct Sales holds installed capacity. Distributors are rotating down the share rankings as technical partnerships consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern layer operations consume marigold-derived lutein at triple the rate per ton of feed compared to southeastern broiler integrators, who favor cost-optimized synthetic blends for skin pigmentation. Canadian aquaculture demands diverge sharply, with British Columbia salmonid producers specifying zeaxanthin-heavy formulations absent from Prairie livestock rations.
United States
Iowa and Minnesota layer integrators drive bulk procurement of USDA Organic-certified natural lutein for retail egg branding. FDA enforcement of updated 21 CFR food additive documentation compels feed compounders to restructure supplier qualification protocols. Des Moines anchors captive premix infrastructure serving Corn Belt poultry operations.
Canada
Alberta and Saskatchewan extraction facilities target domestically grown marigold crops to reduce import dependency for Prairie livestock feeders. The Canadian Food Inspection Agency enforces feed registration standards that restrict unapproved carotenoid sources in commercial rations. British Columbia salmonid producers expand pigment-enhanced diet adoption for export quality premiums.
Mexico
Pacific white shrimp operations in Sonora and Sinaloa present underdeveloped carotenoid dosing protocols requiring species-specific formulation development. Mexico's national feed safety regulator mandates documentation of target species use levels for imported additives. Yucatán Peninsula poultry integrators test direct sourcing relationships bypassing traditional distributor channels.
North America Feed Lutein and Zeaxanthin Market Competitive Landscape
Capability concentration sits with extraction specialists commanding stabilization chemistry expertise; scale advantage sits with diversified chemical manufacturers. The market structures around three tiers: captive premix integrators, botanical extraction specialists, and synthetic carotenoid producers. Competitive moves center on backward integration into marigold cultivation and microencapsulation technology licensing.
Within the extraction specialist tier, Kemin Industries, Inc. and DSM-Firmenich AG exemplify geographic anchoring strategies, with Iowa-based captive supply chains and specialized stabilization intellectual property respectively. BASF SE occupies a position representing synthetic manufacturing scale that sets baseline pricing across cost-sensitive segments. These three entities collectively illustrate the capability-scale tension defining competitive positioning.
| Leading Market Players |
|---|
| Kemin Industries, Inc. |
| DSM-Firmenich AG |
| BASF SE |
| Alltech, Inc. |
| Novus International, Inc. |
| Cargill, Incorporated |
| Chr. Hansen Holding A/S |
| FMC Corporation |
| Valensa International |
| Others |
Value Network & Pricing Analysis
Iowa's captive premix infrastructure concentrates formulation capacity for Corn Belt poultry integrators, translating geographic supply concentration into pricing leverage for extraction specialists commanding microencapsulation chemistry expertise. BASF's synthetic lutein manufacturing scale in Ludwigshafen anchors baseline pricing that constrains premium capture for natural marigold extractors serving cost-sensitive swine and ruminant segments.
Pricing Analysis
Long-term offtake agreements dominate procurement between integrated poultry operations and extraction specialists, with spot-market purchasing fragmenting among independent feed mills. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic-certified natural lutein from conventional botanical grades and synthetic alternatives. Cost compression in standard-tier natural extracts is intensifying because single-source premix contracts compress supplier margins while elevating technical service requirements. Swine finishing operations in the Midwest exhibit highest price sensitivity, whereas layer integrators with retail-branded product lines absorb premium pricing for certified provenance documentation.
Supply Chain Analysis
FDA food additive regulations under 21 CFR restrict unapproved carotenoid sources in commercial feed rations, creating compliance barriers for novel extraction technologies seeking market entry. Mexico, India, and the United States supply marigold oleoresin feedstock, with Alberta and Saskatchewan emerging as domestic cultivation hubs reducing Canadian import dependency. The supply chain draws from weather-dependent agricultural harvests, solvent extraction processing, and high-temperature feed milling infrastructure. Single-source vulnerability concentrates in Des Moines premix operations serving Corn Belt integrators. Distribution runs through direct technical partnerships displacing traditional regional feed additive wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against synthetic carotenoid substitution threatening natural extractor margins in price-sensitive species applications, particularly as fermentation-derived lutein alternatives advance through regulatory approval pathways.
For Market Incumbents: Build captive stabilization chemistry moats through proprietary microencapsulation intellectual property that protects lutein from oxidative degradation during pelleting temperatures exceeding 85°C. Secure backward integration into marigold cultivation in Alberta and Saskatchewan to reduce input cost volatility from Mexican and Indian harvest dependency. Consolidate single-source premix contracts with southeastern broiler integrators before FDA harmonization of novel carotenoid approval pathways accelerates fermentation-derived competitor entry. For New Entrants and Emerging Players: Species-specific formulation white space for Pacific white shrimp aquaculture in Sonora and Sinaloa represents the most penetrable entry point, as underdeveloped carotenoid dosing protocols create technical differentiation opportunities absent from saturated poultry segments. Solvent-free extraction facilities targeting domestically grown Canadian marigold crops offer geographic arbitrage against Iowa supply concentration. Partner directly with British Columbia salmonid producers seeking zeaxanthin-heavy formulations for export quality premiums, bypassing distributor intermediaries that incumbent extraction specialists already control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extraction specialists with captive microencapsulation technology licensing and long-term technical service contracts with integrated poultry operations. Over the projection horizon, prioritize acquisition targets combining stabilization chemistry expertise with direct premix infrastructure serving Corn Belt layer integrators. Monitor FDA enforcement posture on 21 CFR food additive documentation as the signal indicating whether fermentation-derived lutein alternatives accelerate market entry and compress natural extractor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marigold Cultivation | Alberta and Saskatchewan farming operations reduce Mexican and Indian harvest dependency for Prairie livestock feeders. |
| Microencapsulation Technology Licensing | Proprietary lipid-matrix embedding commands premium positioning in Iowa and Minnesota layer operations adopting thermal protection. |
| Single-Source Premix Contract Consolidation | Southeastern broiler integrators compress supplier margins while locking in formulation stability and yolk color consistency. |
| Species-Specific Aquaculture Formulation Development | Pacific white shrimp operations in Sonora present technical white space for pigment-enhanced diet innovation. |
| FDA Food Additive Registration Investment | Premarket notification documentation accelerates market entry for novel carotenoid delivery systems previously grandfathered. |
Research Methodology
Cross-validation between regulatory filing analysis and feed mill procurement data anchors the qualitative findings in documented compliance patterns and commercial transaction structures. Primary interviews with layer operation quality assurance directors, broiler integrator procurement leads, extraction facility plant managers, and FDA regulatory affairs specialists combined with secondary validation from 21 CFR food additive registrations, Canadian Food Inspection Agency feed approvals, USDA organic certification databases, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across natural and synthetic product categories.
Calibration against historical adoption curves for carotenoid premix programs in Iowa and Minnesota layer operations informs the projection framework. Segmentation dimensions modeled include extraction chemistry tier, target species physiology, feed manufacturing process compatibility, and distribution channel structure. CAGRs derived from fitted growth curves reflecting technology diffusion patterns and regulatory enforcement timelines. Industry-specific forecast inputs incorporate marigold oleoresin harvest variability and FDA documentation requirement evolution.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, feed grain costs, and protein demand cycles would shift the trajectory. Forecasts reflect assumptions regarding continued enforcement of 21 CFR food additive regulations and Canadian feed registration standards. Material shifts in FDA harmonization pathways for fermentation-derived carotenoids or state-level antibiotic reduction policy intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Peat Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Feed Sucrose Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market